
 Global Wine Market | 2026-2036
Global Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wine Market Outlook
Single-serve and alternative-format packaging is recalibrating how consumers experiment with wine outside traditional bottle occasions. E&J Gallo Winery leverages its massive California production base to dominate mainstream retail shelf space. Treasury Wine Estates anchors its portfolio around luxury Penfolds labels that command pricing power in Asian duty-free channels. Constellation Brands differentiates through beer-and-wine portfolio bundling that captures cross-category retail placements.
Wine is an alcoholic beverage produced through the fermentation of grape must, typically containing 11–15% ethanol by volume, with organoleptic profiles shaped by terroir, varietal selection, and controlled oxidation during aging. Its primary commercial purpose spans direct consumption, food pairing in hospitality settings, and investment-grade cellaring. Red wine occupies the largest volume pool globally, while sparkling wine represents the fastest-expanding margin segment as prosecco and champagne-style products penetrate everyday celebration occasions. The price tier structure concentrates profitability at super-premium levels, where scarcity narratives and vintage provenance sustain consumer premiums.
The EU's F-Gas Regulation and REACH chemical standards govern vineyard inputs and cellar processing aids across European production zones, while the FDA and TTB enforce labeling, additive disclosure, and alcohol content accuracy in United States commerce. These frameworks elevate compliance costs for exporters but simultaneously create market access barriers that protect established certification holders. Stakeholders must monitor evolving organic equivalence agreements between major trading blocs, as mutual recognition of biodynamic and natural wine standards will determine which producers capture emerging sustainability-driven demand segments.
Market Dynamics
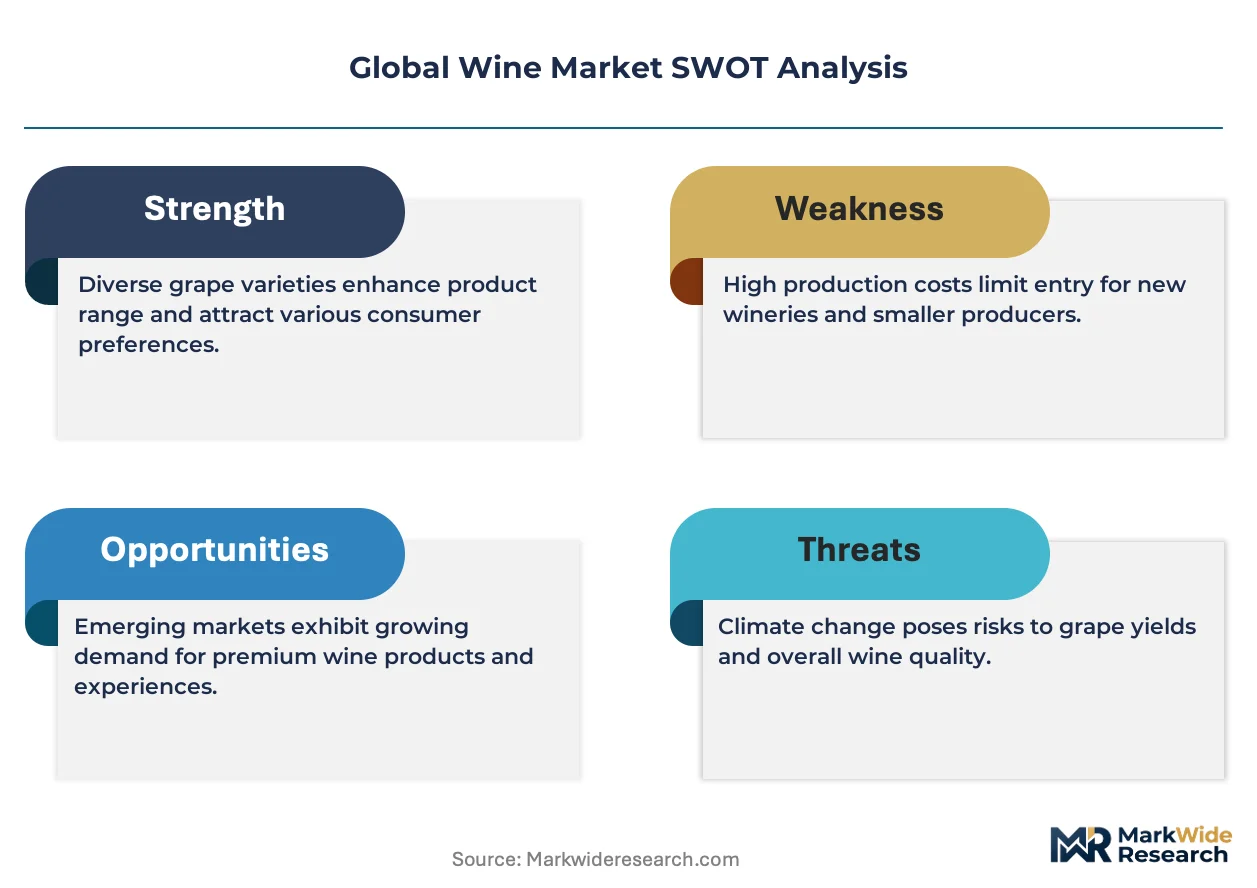
Premiumization pressures from Asian duty-free channels and EU organic certification mandates are compressing mid-tier producer margins while concentrating volume among certified estate bottlers.
Growth Catalysts
- EU Green Deal vineyard standards:France, Italy, and Spain accelerate conversion subsidies. Certified organic hectarage expands export eligibility into Japanese and Chinese import channels.
- Single-serve packaging formats:Canned and boxed wine technologies unlock outdoor recreation and airline hospitality placements previously inaccessible to glass-bottle supply chains.
- China's imported label recognition:Urban tier-one consumers display willingness-to-pay premiums for established Old World provenance markers in gifting occasions.
Market Restraints
- Input cost volatility:Oak barrel and glass bottle supply chains concentrate in Eastern European and Chinese manufacturing zones, exposing producers to energy price swings.
- Climate yield compression:Heat stress in Languedoc-Roussillon and Barossa Valley reduces vintage consistency, forcing reserve depletion and volume rationing.
- REACH chemical compliance:ECHA processing aid restrictions elevate laboratory testing burdens for small-scale biodynamic exporters seeking EU market access.
Strategic Opportunities
- Japanese on-premise channel:Izakaya and hotel restaurant chains underrepresent New World varietals, creating white space for Australian and Chilean label penetration.
- Low-intervention wine convergence:Natural wine production methods intersect with raw-bar and farm-to-table restaurant positioning in Brooklyn, Copenhagen, and Melbourne.
- India import tariff relaxation:FSSAI streamlined labeling requirements reduce entry friction for mid-premium Spanish and Italian cooperative exports.
Industry Challenges
- Viticulture labor scarcity:Seasonal harvest workforce availability contracts in Napa Valley and Western Cape, forcing mechanical picking adoption that compromises berry selection quality.
- Organic certification timelines:Three-year conversion periods lock working capital in transitional vineyard blocks without corresponding price premiums.
- DTC shipping compliance:United States state-level alcohol shipping regulations fragment e-commerce fulfillment, requiring 50-jurisdiction license maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wine Market |
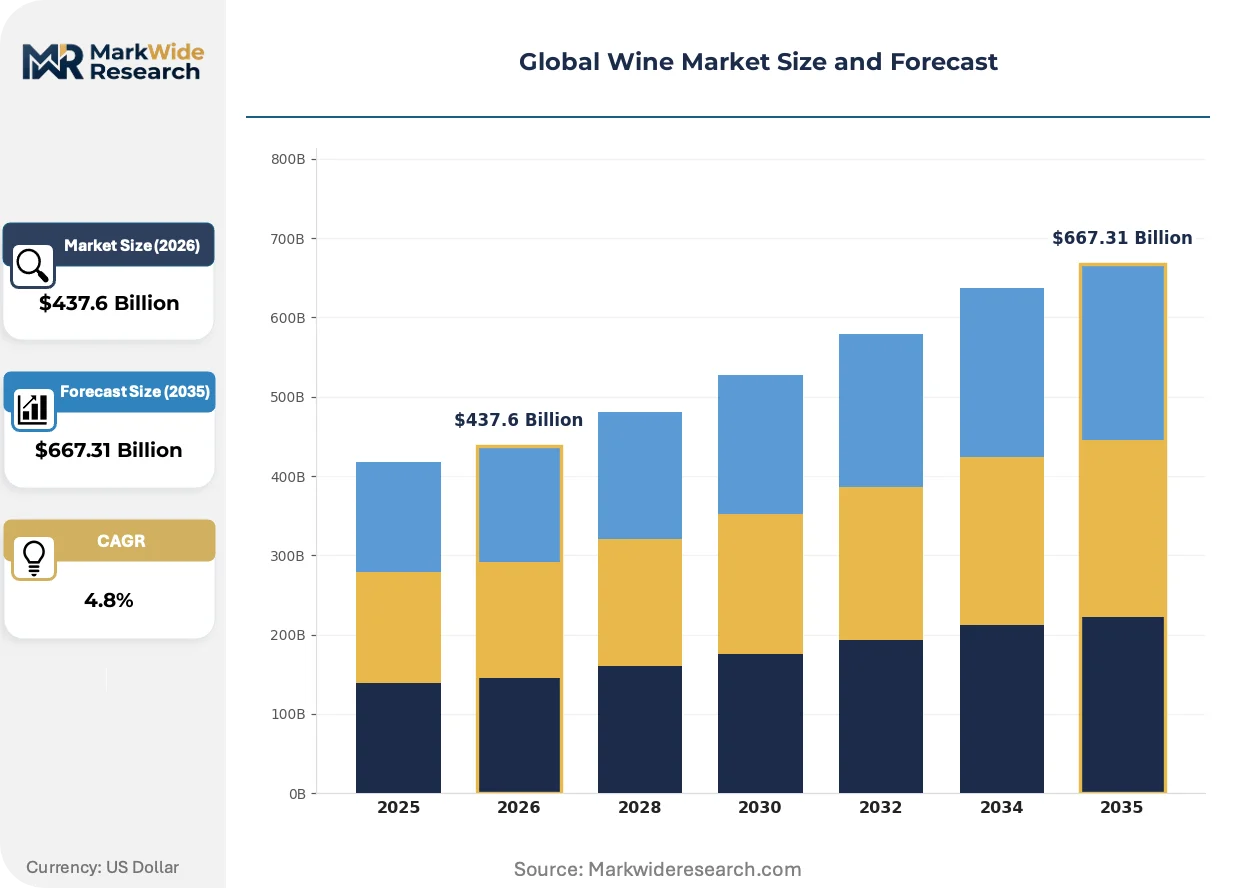
| Market Size in 2026 | $437.6 Billion |
| Market Size in 2035 | $667.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Sparkling Wine, Rose Wine End User: Restaurants, Retail Stores, Online Retailers, Wine Clubs Price Tier: Premium, Super Premium, Value, Economy Distribution Channel: Direct Sales, Wholesale, E-commerce, Supermarkets |
| Companies Covered | E&J Gallo Winery, The Wine Group, Treasury Wine Estates, Constellation Brands, Pernod Ricard, Castel Frères, Jackson Family Wines, Accolade Wines, Concha y Toro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wine Market Strategic Shifts
Digital vineyard management and alternative packaging formats are compressing traditional cellar-to-shelf timelines while regulatory sustainability mandates reconfigure input sourcing across major production zones.
Precision viticulture sensor networks is automating canopy management and irrigation scheduling across large-scale Chilean and Australian estates. Treasury Wine Estates and Concha y Toro deploy drone-mounted spectral imaging to optimize harvest timing block-by-block. Labor cost structures in these regions compress as technology substitutes for manual vineyard scouting.
EU F-Gas Regulation refrigerant phase-down governs cold-chain logistics for temperature-sensitive sparkling wine shipments. Transport operators retrofit reefers with natural refrigerant systems to maintain compliance. Champagne houses and Prosecco consortia absorb capex premiums to preserve Asian export channel access.
Direct-to-consumer subscription models displace traditional three-tier distribution in United States metropolitan markets. Millennial and Gen-Z buyers source limited-production natural wines through winery-managed allocation lists. San Francisco, New York, and Austin demonstrate highest subscriber density, compressing distributor margin capture.
Global Wine Market Segmentation
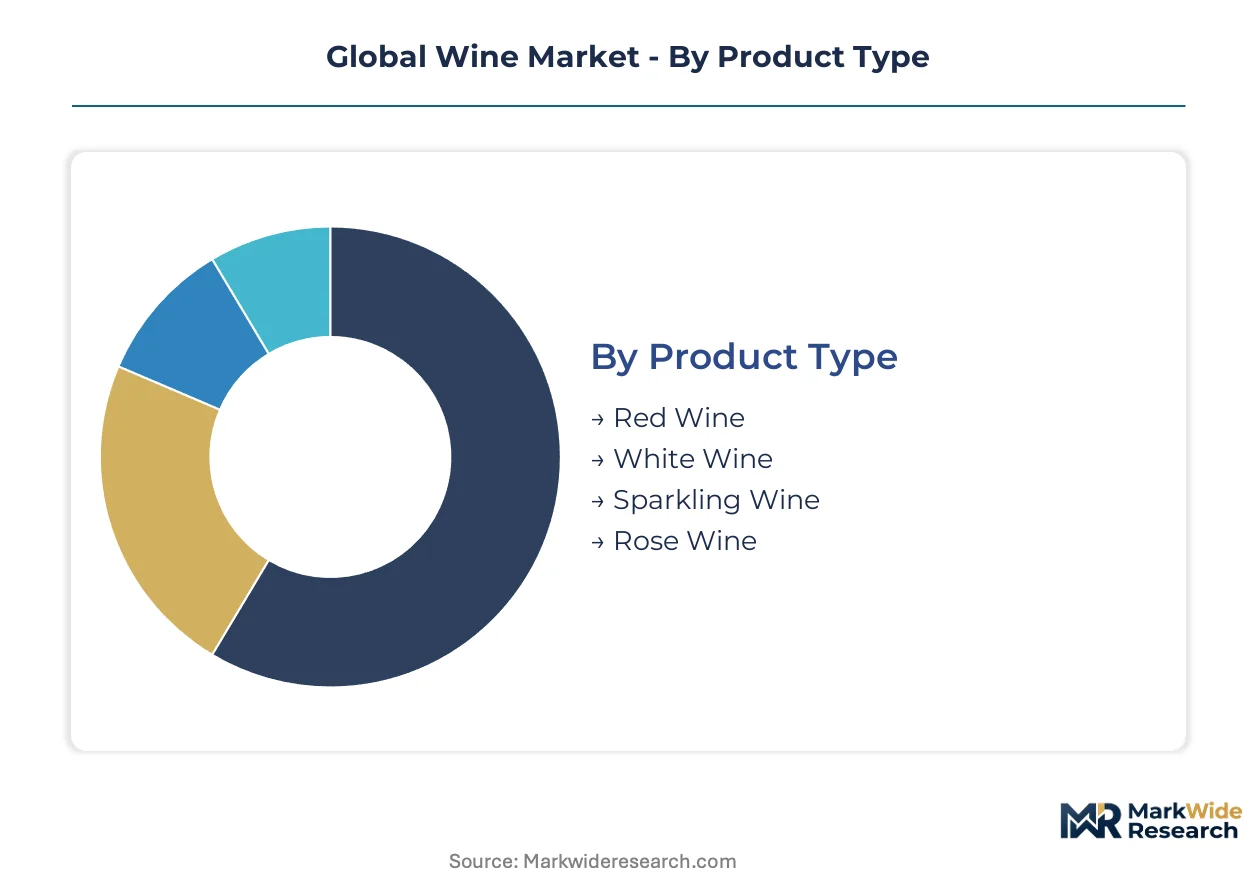
Wine market segmentation tracks how purchase occasions, channel access, and price thresholds partition consumer wallets across production origins. Understanding these splits reveals where margin concentrates and which format innovations unlock new consumption moments.
Product Type:
Varietal choice reflects occasion formality, food pairing traditions, and cellar investment intent among collectors.
- Red Wine:Tannin structure and aging potential from Cabernet Sauvignon, Merlot, and Tempranillo grapes dominate volume in France, Italy, and Spain. Restaurant wine lists in Shanghai and Tokyo allocate disproportionate red selection to Old World provenance markers for business entertaining.
- Sparkling Wine:Secondary fermentation creates CO2 retention in Champagne, Prosecco, and Cava styles. Canned formats penetrate music festivals and outdoor recreation in Australia and the United States, compressing per-unit price points while expanding trial frequency.
- White Wine:Chardonnay and Sauvignon Blanc expressions from cooler-climate zones in Germany and New Zealand.
- Rose Wine:Provence-style pale expressions and darker Spanish Garnacha versions.
Volume sits with Red Wine; growth tilts toward Sparkling Wine.
End User:
Channel control determines label visibility, temperature integrity, and staff recommendation influence at the point of decision.
- Restaurants:On-premise sommelier curation and by-the-glass programs shape discovery for premium and super-premium tiers. Michelin-starred venues in Singapore and Hong Kong drive allocation list access for limited-production Burgundy and Barolo labels.
- Online Retailers:Direct-to-consumer platforms bypass three-tier distribution in the United States, capturing subscriber relationships through algorithmic personalization. Vivino and specialized natural wine merchants in Brooklyn and Copenhagen curate discovery for millennial buyers.
- Retail Stores:Independent merchants and chain wine specialists in London and Sydney.
- Wine Clubs:Subscription allocation models for allocated Napa Valley and Oregon Pinot Noir.
Restaurants command the highest per-bottle margins; Online Retailers are climbing the fastest as fulfillment infrastructure matures.
Price Tier:
Premium thresholds separate mass-market velocity from scarcity-driven investment grade positioning.
- Premium:Estate-bottled wines with controlled appellation status from Bordeaux, Rioja, and Barossa Valley. Duty-free channels in Chinese and Japanese airports concentrate velocity here, where gifting occasions demand recognizable label prestige.
- Super Premium:Single-vineyard designates, classified growths, and aged vintage Champagnes. Asian auction houses in Hong Kong and Singapore transact these as alternative assets, with provenance documentation and optimal storage history commanding bid premiums.
- Value:Branded blends and cooperative production from Languedoc-Roussillon and Chile's Central Valley.
- Economy:Private-label and bag-in-box formats for everyday consumption.
Super Premium captures the steepest expansion trajectory; Value holds the largest absolute volume base.
Distribution Channel:
Logistics configuration determines temperature exposure, regulatory compliance burden, and margin stacking across intermediaries.
- Wholesale:Importer-distributor networks manage customs clearance, excise tax payment, and refrigerated warehousing for temperature-sensitive shipments. European F-Gas Regulation compliance for reefers adds capex recovery surcharges to sparkling wine landed costs.
- E-commerce:Winery-direct shipping and third-party marketplace fulfillment fragment across United States state-level licensing requirements. Compliance platforms automate age verification and excise reporting for sellers in California, New York, and Texas.
- Direct Sales:Tasting room and cellar door transactions in Napa Valley and Western Cape.
- Supermarkets:High-velocity branded placements in Tesco, Carrefour, and Woolworths chains.
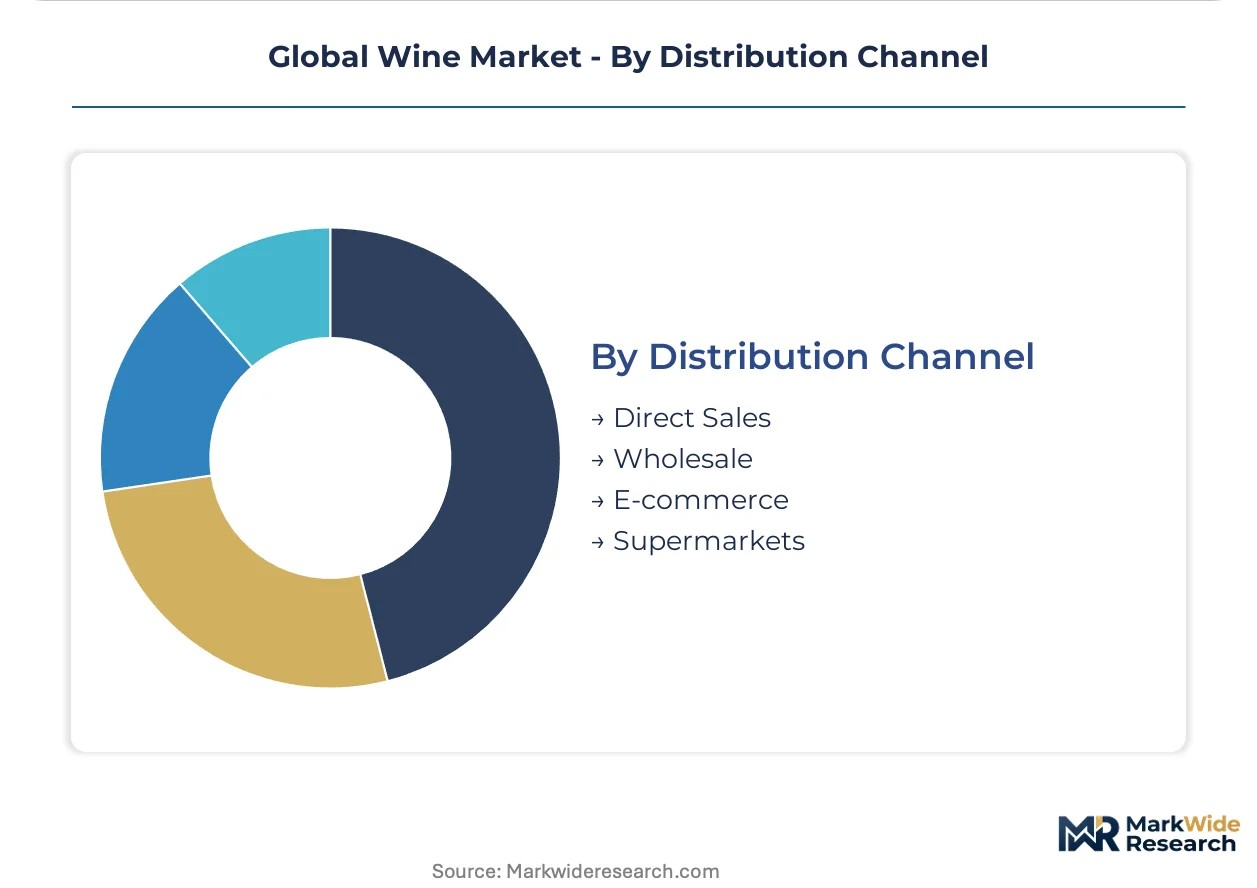
Wholesale retains volume dominance; E-commerce gains share fastest as subscription models displace traditional distributor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Appellation d'Origine Contrôlée zones and Italy's denominazione di origine controllata designations function as de facto special-economic-zones that concentrate premium production and export certification infrastructure.
France
Bordeaux and Burgundy drive super-premium export volumes to Chinese and Japanese duty-free channels. The EU Green Deal accelerates organic hectarage conversion subsidies across Languedoc-Roussillon. Champagne houses absorb F-Gas Regulation compliance costs to preserve Asian cold-chain export access.
Italy
Chianti Classico and Barolo provenance markers command gifting premiums in Shanghai and Hong Kong. ECHA REACH standards govern cellar processing aid compliance for biodynamic exporters. Prosecco consortia in Veneto retrofit reefers with natural refrigerant systems for sparkling wine shipments.
United States
Napa Valley and Sonoma County anchor super-premium allocation list demand from San Francisco and New York subscribers. FDA and TTB labeling enforcement elevates compliance costs for imported European competitors. Treasury Wine Estates and Jackson Family Wines dominate domestic luxury tier positioning.
Australia
Barossa Valley Shiraz and Margaret River Cabernet Sauvignon penetrate Japanese izakaya white space. Precision viticulture sensor networks automate canopy management across Treasury Wine Estates holdings. Concha y Toro deploys drone-mounted spectral imaging to optimize harvest timing block-by-block.
Spain
Rioja and Priorat denominations expand into Indian import channels following FSSAI labeling streamlining. Cooperatives in Languedoc-Roussillon face climate yield compression forcing reserve depletion. Castel Frères leverages volume scale across value-tier European retail placements.
Global Wine Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning bands. The vendor base concentrates among California-based volume producers, Australian luxury exporters, and European heritage houses with controlled appellation access. Three archetypes dominate: scale-driven branded blenders, terroir-focused estate bottlers, and portfolio-conglomerates with cross-category alcohol holdings. Competitive moves center on organic certification acquisition and direct-to-consumer subscription infrastructure buildout.
Among California-based volume producers, E&J Gallo Winery and The Wine Group exemplify scale-driven branded blenders with mainstream retail shelf dominance. Treasury Wine Estates anchors the luxury-export archetype through Penfolds label pricing power in Asian duty-free channels. Constellation Brands occupies the portfolio-conglomerate position with beer-and-wine bundling that captures cross-category retail placements.
| Leading Market Players |
|---|
| E&J Gallo Winery |
| The Wine Group |
| Treasury Wine Estates |
| Constellation Brands |
| Pernod Ricard |
| Castel Frères |
| Jackson Family Wines |
| Accolade Wines |
| Concha y Toro |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap estates in Burgundy and Barossa Valley anchor supply discipline through generational capital allocation, insulating pricing power from quarterly earnings pressure while concentrating quality-tier output among holders of controlled appellation rights.
Pricing Analysis
Margin tightening in mid-premium tiers reflects organic certification conversion costs and climate-induced vintage inconsistency. Three-tier pricing structure across super-premium, premium, and value levels separates estate-bottled appellation wines from cooperative blends and private-label formats. Brand premium and certification grade—EU organic, biodynamic, or natural wine standards—drive price differentiation most sharply in Asian duty-free channels. Buyers in China's tier-one cities display lowest price sensitivity for provenance-marked gifting wines, while European supermarket shoppers compress value-tier margins through private-label substitution.
Supply Chain Analysis
Single-source vulnerability sits with Eastern European oak cooperage and Chinese glass manufacturing zones for bottle supply. France, Italy, and Spain concentrate vineyard hectarage and cellar infrastructure; Chile and Australia feed New World export pipelines. Raw material dependencies rest on French oak staves, Italian cork, and German stainless steel tanks. Logistics chokepoint risk concentrates in refrigerated container availability for sparkling wine cold-chain compliance. Distribution runs through importer-distributor networks managing customs clearance and excise tax layering before retail or on-premise handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and REACH chemical standards erect compliance moats that favor certified incumbents with laboratory infrastructure and documented processing aid histories, raising effective barriers for uncertified exporters seeking European market access.
For Market Incumbents: Cement organic certification acquisition timelines through three-year vineyard conversion contracting, locking transitional hectarage ahead of EU Green Deal subsidy exhaustion. Deepen upstream control over oak barrel supply through captive cooperage partnerships or long-term offtake agreements with Slovenian and Hungarian stave suppliers, insulating against energy-driven input cost volatility from Eastern European manufacturing zones. For New Entrants and Emerging Players: FSSAI streamlined labeling requirements in India open a window for mid-premium Spanish and Italian cooperative exports previously blocked by documentation friction. Target Japanese izakaya and hotel restaurant chains for New World varietal penetration, where Old World list concentration leaves white space for Australian Shiraz and Chilean Carménère. Lead go-to-market through specialized import agents with established on-premise relationships rather than distributor-generalist partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor biodynamic-certified estates in Languedoc-Roussillon and Western Cape facing climate yield compression and working capital strain from conversion lock-up periods. Long-term viability centers on producers with documented Asian duty-free channel access and allocation list subscriber density in San Francisco and New York. Watch organic equivalence agreement negotiations between EU and Chinese regulators as inflection signal for certified producer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Conversion | EU Green Deal subsidies accelerate three-year vineyard transitions ahead of mandate tightening in France and Italy. |
| Direct-to-Consumer Subscription Buildout | Winery-managed allocation lists bypass three-tier distribution margin stacking in United States metropolitan markets. |
| Alternative Packaging Format Expansion | Canned and boxed technologies unlock airline hospitality and outdoor recreation placements inaccessible to glass supply chains. |
| Precision Viticulture Sensor Deployment | Drone-mounted spectral imaging optimizes harvest timing block-by-block across Treasury Wine Estates and Concha y Toro holdings. |
| Asian Duty-Free Channel Deepening | Penfolds label pricing power in Chinese and Japanese airport retail sustains super-premium margin capture. |
Study Parameters
Multi-period observation of certified organic hectarage expansion, import tariff adjustments, and cold-chain logistics compliance costs anchored the trend analysis, supplemented by interviews with vineyard estate managers, export compliance officers, on-premise sommeliers, and airline hospitality procurement directors. Secondary validation drew from EU F-Gas Regulation implementation notices, ECHA REACH guidance documents, FSSAI labeling circulars, and customs trade data from France, Italy, Spain, and Australia. Bottom-up volume builds across price tiers and distribution channels triangulated against top-down macroeconomic consumption indicators.
Input-output matrices modeled demand elasticity across super-premium, premium, value, and economy tiers against supply-side constraints including climate yield variance, labor availability, and certification conversion timelines. Segmentation dimensions spanned product type, end-user channel, price tier, and distribution configuration, with geographic regulatory clusters treated as distinct market access conditions. CAGRs were derived from trend extrapolation of vintage volume data and per-liter pricing trajectories across the projection horizon, incorporating sparkling wine growth coefficients and still wine substitution elasticities as industry-specific forecast inputs.
The model assumes a particular technology adoption path for precision viticulture automation and natural refrigerant cold-chain retrofitting; alternative pathways for drone-based canopy management or ammonia-based reefer systems would alter the outlook for labor cost compression and F-Gas compliance capex recovery. Forecasts reflect assumptions regarding organic equivalence agreement timelines, climate yield stability, and Asian import tariff trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Wine Cellar Market