
 South Africa Casino Tourism Market | 2026-2036
South Africa Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Casino Tourism Market Analytics
Hospitality-trained dealer and croupier talent is bifurcating the competitive landscape as premium integrated resorts compete with standalone casinos for scarce skilled labor. Sun International leverages its Sun City and Carnival City properties to anchor market presence across Gauteng and North West provinces. Tsogo Sun Gaming sustains operational density through its Gold Reef City and Montecasino complexes in Johannesburg. Peermont Global competes via Emperors Palace near OR Tambo International Airport, capturing transit and conference-driven demand.
South Africa casino tourism encompasses purpose-built gaming and entertainment complexes that combine licensed gambling floors with hotels, convention facilities, and live performance venues, typically operating under provincial gambling board oversight with minimum capital investment thresholds and responsible gaming mandates. The primary commercial purpose centers on extending visitor length of stay and per-trip expenditure through integrated hospitality offerings. Resort casinos dominate the facility type landscape, absorbing the bulk of capital deployment and foreign direct investment in the sector. VIP gaming within the gaming experience dimension commands disproportionate margin contribution despite narrower patron volume. Millennials represent the fastest-growing customer demographic as digital-native preferences reshape loyalty program design and on-property entertainment mix.
South Africa's National Gambling Board coordinates with provincial regulators including the Gauteng Gambling Board and KwaZulu-Natal Gambling Board to enforce licensing conditions, machine-to-table ratios, and anti-money laundering protocols that directly shape operator investment decisions and market access timelines. The Financial Intelligence Centre Act compliance requirements impose transaction monitoring obligations that increase operational complexity but strengthen sector legitimacy for international tour operators. Stakeholders must monitor evolving provincial tax rate differentials and emerging integrated resort development applications in secondary cities to anticipate competitive repositioning and capital allocation shifts.
Market Dynamics
Provincial gambling board licensing regimes are tightening capital adequacy and responsible gaming mandates, forcing integrated resort operators to reconfigure floor layouts and escalate compliance expenditure ahead of license renewals. This structural pressure concentrates market access among established license-holders with balance sheet capacity to absorb regulatory escalation.
Growth Catalysts
- Financial Intelligence Centre Act compliance:Transaction monitoring obligations strengthen sector legitimacy for international tour operators, expanding addressable inbound leisure segments from sub-Saharan African source markets.
- Millennial digital-native preferences:Smartphone-integrated loyalty programs and cashless gaming wallets are extending per-visit expenditure and reducing friction at property entry points.
- Gauteng and KwaZulu-Natal corridor concentration:Johannesburg-Pretoria and Durban beachfront clusters aggregate conference, transit, and leisure demand into high-yield catchment zones with superior infrastructure.
Market Restraints
- Hospitality-trained dealer scarcity:Premium integrated resorts and standalone casinos compete for finite croupier talent, inflating wage structures and lengthening onboarding timelines.
- Provincial tax rate differentials:Divergent gambling tax schedules across Gauteng, KwaZulu-Natal, and North West provinces fragment capital allocation efficiency and complicate multi-property portfolio optimization.
- Machine-to-table ratio mandates:Provincial gambling board prescriptions constrain floor configuration flexibility, limiting operator ability to rebalance gaming mix toward higher-margin VIP segments.
Strategic Opportunities
- Secondary city integrated resort development:Emerging license applications in Port Elizabeth and East London offer first-mover positioning in underpenetrated Eastern Cape and Free State catchments.
- Convention facility integration:OR Tambo International Airport transit volume and business event demand create hybrid conference-gaming revenue streams distinct from pure leisure visitation.
- Live performance venue expansion:Entertainment precincts anchored by arena-scale theaters differentiate properties from limited-service competitors and extend length-of-stay metrics.
Industry Challenges
- Anti-money laundering protocol implementation:Financial Intelligence Centre Act transaction monitoring systems require specialized compliance personnel and real-time surveillance infrastructure that strain mid-tier operator resources.
- Responsible gaming mandate enforcement:Provincial gambling board self-exclusion registry integration and staff training certification impose recurring operational burdens with escalating penalty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Casino Tourism Market |
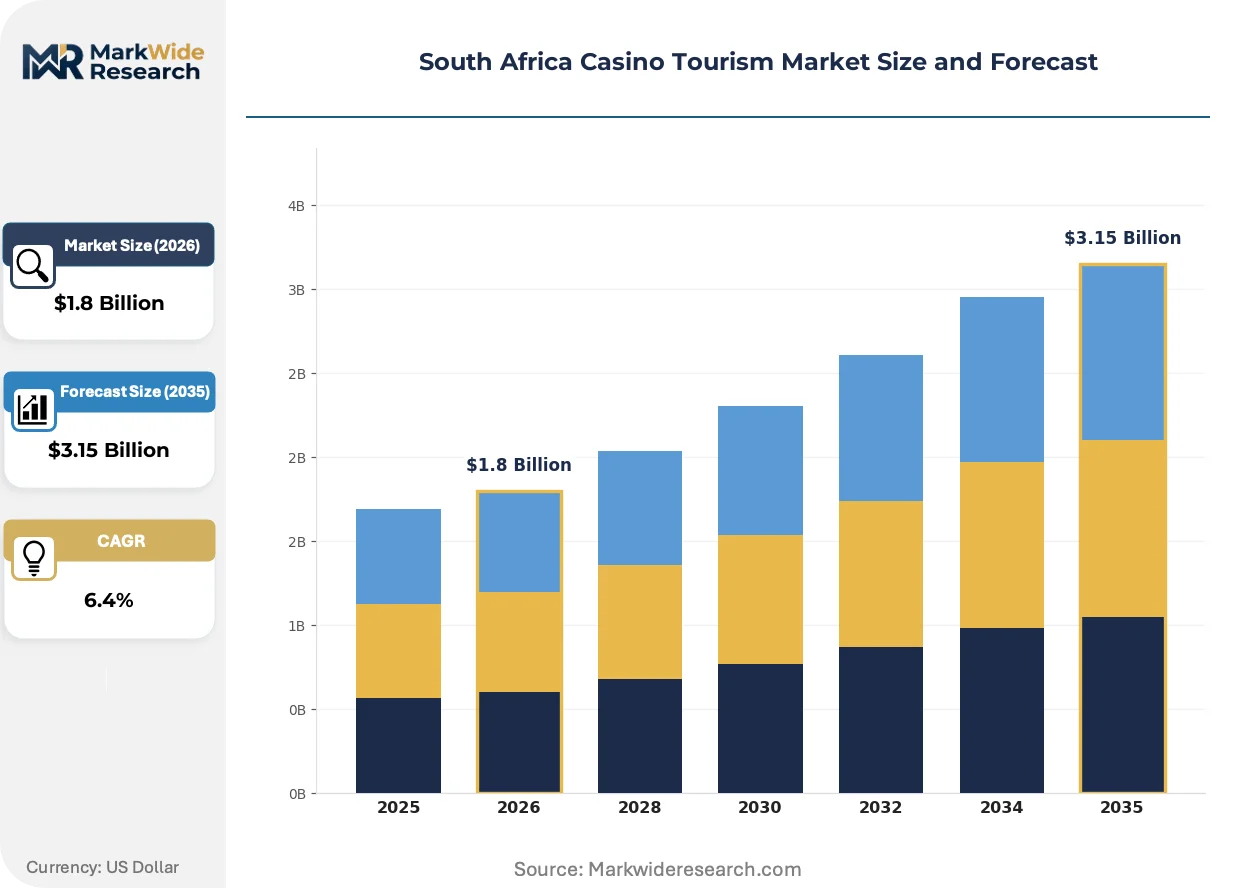
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Resort Casinos, Standalone Casinos, Integrated Resorts, Riverboat Casinos Customer Demographics: Millennials, Baby Boomers, Tourists, Locals Gaming Experience: Table Games, Slot Machines, Poker Rooms, VIP Gaming Event Type: Conventions, Live Shows, Sports Events, Tournaments |
| Companies Covered | Sun International, Tsogo Sun Gaming, Peermont Global, Urvi Tours, Thomas Cook, Abercrombie and Kent Safaris, Heena Tours & Travels, Dook International, Happy Vacations Tours and Travels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Casino Tourism Market Evolving Landscape
Cashless gaming infrastructure and biometric player tracking are compressing transaction latency while generating granular behavioral data that reshapes loyalty program architecture. These innovations alter competitive positioning by rewarding capital-intensive technology deployment.
Biometric facial recognition systems integrated with player loyalty databases are bifurcating the competitive landscape. Premium integrated resorts deploy these tools to accelerate VIP recognition and personalize service delivery. Mid-tier properties lacking comparable capital access face widening service-quality gaps that compress their addressable premium segments.
South Africa's National Gambling Board coordinates with provincial regulators to enforce escalating responsible gaming mandates including machine-to-table ratio compliance and self-exclusion registry integration. These requirements increase operational complexity and compliance staffing intensity. Gauteng and KwaZulu-Natal operators absorb disproportionate regulatory burden given their concentration of gaming positions and higher inspection frequency.
Digital-native millennial preferences are displacing traditional slot-centric floor designs with experiential entertainment precincts combining esports lounges, immersive theater, and social gaming formats. Sun City and Gold Reef City complexes reconfigure square footage toward these hybrid offerings. This behavioral shift concentrates in Johannesburg-Pretoria corridor properties where younger demographic penetration exceeds coastal markets.
South Africa Casino Tourism Market Segmentation
Casino tourism segmentation in South Africa reflects distinct capital deployment patterns and regulatory exposure profiles. Each dimension shapes operator investment decisions and provincial licensing strategies differently.
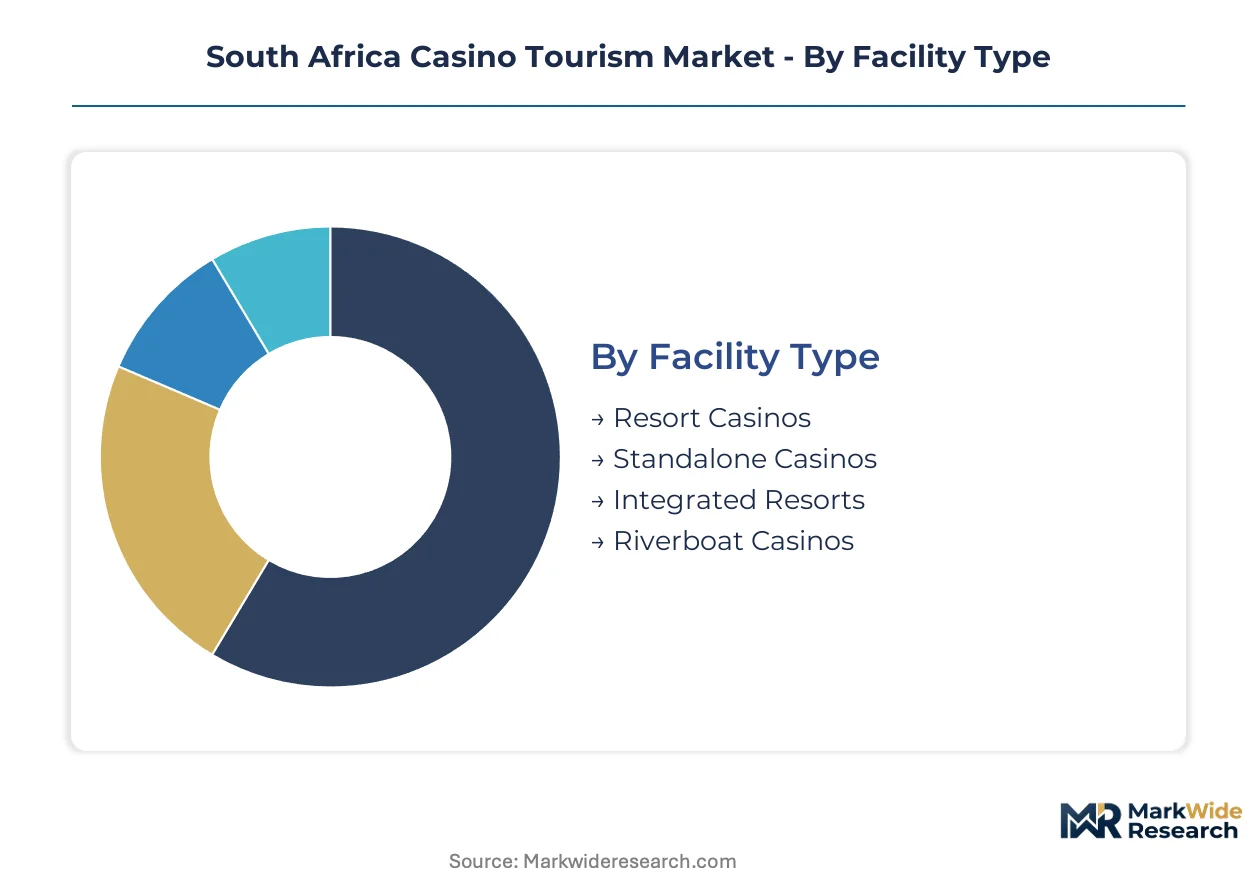
Facility Type:
Resort casinos concentrate in Gauteng and KwaZulu-Natal's domestic leisure corridors, while integrated resorts target international transit volume near OR Tambo International Airport.
- Resort Casinos:Purpose-built complexes combining licensed gaming floors with hotels and entertainment venues under provincial gambling board oversight. Sun International and Tsogo Sun Gaming dominate this segment across Johannesburg-Pretoria and Durban beachfront clusters, where infrastructure density supports extended-stay visitation patterns.
- Integrated Resorts:Large-scale developments incorporating convention facilities, arena theaters, and multiple hotel towers. Emperors Palace near OR Tambo captures transit and conference-driven demand, with the Financial Intelligence Centre Act compliance requirements strengthening legitimacy for international tour operator partnerships.
- Standalone Casinos:Limited-service gaming facilities without integrated hospitality components. These properties compete for scarce hospitality-trained dealer talent against premium integrated resorts, compressing margin structures.
- Riverboat Casinos:Floating or waterfront gaming vessels operating under specialized licensing frameworks. Limited presence in South Africa compared to coastal markets elsewhere.
Resort casinos command the established base. The steepest expansion runs through integrated resorts.
Customer Demographics:
Millennial digital-native preferences are reshaping loyalty program architecture and floor configuration across all property types.
- Millennials:Smartphone-integrated cashless gaming wallets and esports lounges extend per-visit expenditure. This cohort gains share fastest in Johannesburg-Pretoria corridor properties where younger demographic penetration exceeds coastal markets.
- Baby Boomers:Traditional slot-centric visitation patterns with established brand loyalty. Gold Reef City and Sun City complexes retain this base through familiar floor layouts and legacy rewards programs.
- Tourists:International leisure travelers from sub-Saharan African source markets deepening visitation to Gauteng and KwaZulu-Natal complexes. National Gambling Board licensing regimes provide regulatory certainty for inbound operators.
- Locals:Repeat visitation from surrounding catchment areas driving midweek occupancy. Provincial gambling board responsible gaming mandates including self-exclusion registry integration directly affect this segment's access protocols.
Baby boomers anchor current revenue contribution. Millennial engagement is climbing the fastest.
Gaming Experience:
VIP gaming commands disproportionate margin contribution despite narrower patron volume, while slot machines absorb the bulk of floor square footage.
- VIP Gaming:High-limit private salons with dedicated hosts and biometric facial recognition systems. Premium integrated resorts deploy these tools to accelerate recognition and personalize service delivery, widening competitive gaps against mid-tier properties.
- Slot Machines:Electronic gaming devices subject to provincial machine-to-table ratio mandates that constrain floor configuration flexibility. These ratios limit operator ability to rebalance toward higher-margin segments.
- Table Games:Blackjack, roulette, and baccarat requiring hospitality-trained croupiers. Dealer scarcity inflates wage structures and lengthens onboarding timelines across Gauteng and KwaZulu-Natal.
- Poker Rooms:Dedicated tournament and cash game spaces attracting specialized player cohorts. Tournament events extend length-of-stay metrics distinct from pure gaming visitation.
Slot machines retain volume leadership. VIP gaming shows the steepest margin expansion trajectory.
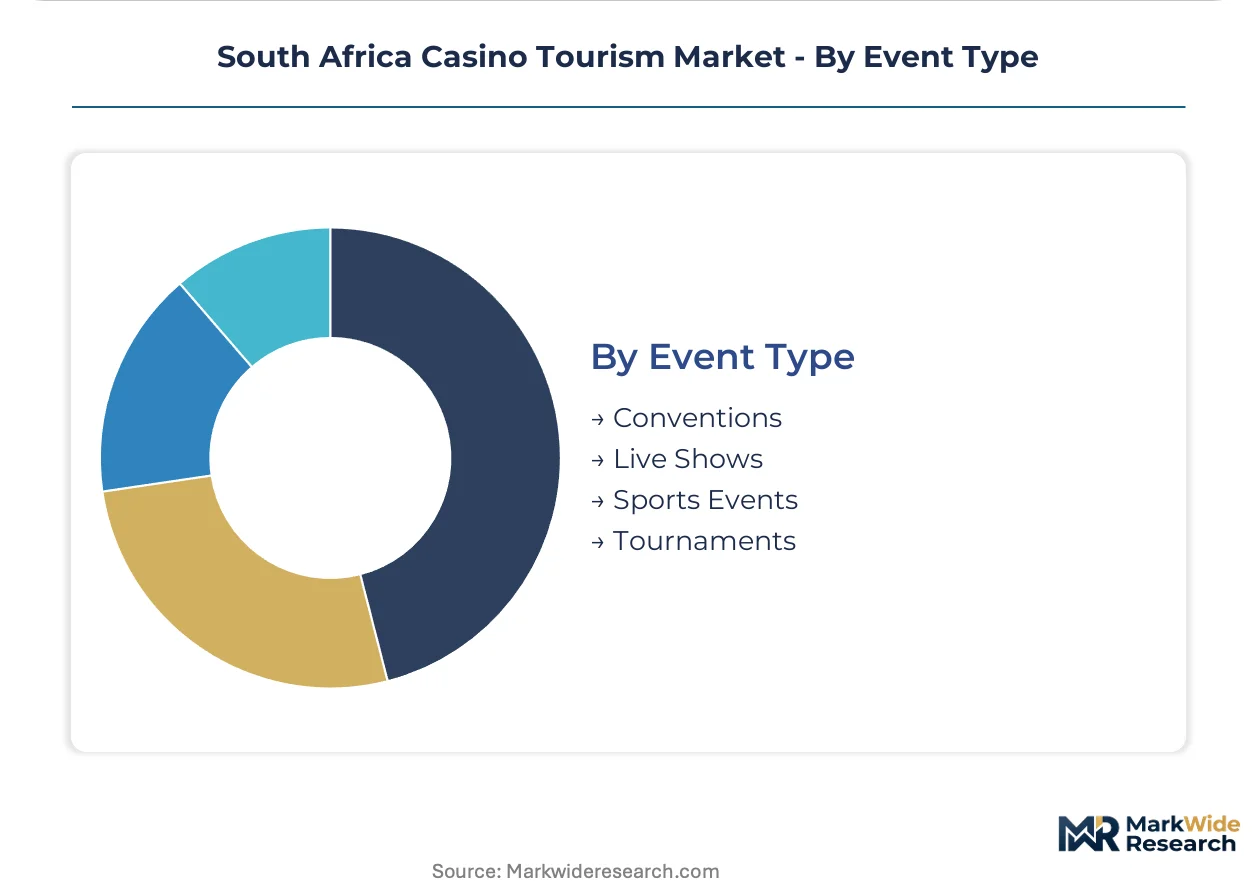
Event Type:
Convention and live show integration differentiates premium properties from limited-service competitors in South Africa's concentrated urban corridors.
- Conventions:Business event facilities generating hybrid conference-gaming revenue streams. OR Tambo International Airport transit volume creates captive demand for Emperors Palace and similar airport-proximate developments.
- Live Shows:Arena-scale theater productions extending length-of-stay metrics. Carnival City and Montecasino complexes anchor entertainment precincts that compete with standalone venues.
- Sports Events:Broadcast and viewing party infrastructure integrated with gaming floors. Durban beachfront properties leverage coastal event calendars.
- Tournaments:Poker and slots competitions attracting destination players. These events concentrate in properties with sufficient hotel inventory to capture extended stays.
Conventions anchor the business-travel revenue base. Live shows are expanding most quickly as differentiation tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Gambling Board anchors regulatory oversight across South Africa's provincial gambling jurisdictions, with Gauteng and KwaZulu-Natal absorbing disproportionate compliance burdens due to gaming position concentration.
Gauteng
Johannesburg-Pretoria corridor infrastructure aggregates conference, transit, and leisure demand into high-yield catchment zones. The Gauteng Gambling Board enforces machine-to-table ratio mandates and responsible gaming certifications that constrain floor configuration flexibility. Sun City and Carnival City complexes anchor market presence across the province, with biometric facial recognition systems accelerating VIP recognition.
KwaZulu-Natal
Durban beachfront clusters leverage coastal event calendars and international airport connectivity to capture sub-Saharan African leisure travelers. Provincial gambling statutes impose minimum capital investment thresholds that filter market access. Gold Reef City and Montecasino complexes sustain operational density through integrated hospitality offerings.
North West
Sun International's Sun City property anchors domestic leisure demand in this underpenetrated catchment. The North West Gambling Board maintains divergent tax schedules that fragment capital allocation efficiency against Gauteng operators. Pilanesberg-proximate positioning captures safari-tourism adjacency.
Eastern Cape
Port Elizabeth and East London present emerging license applications for first-mover positioning in secondary city development. Provincial regulators coordinate with the National Gambling Board on anti-money laundering protocol implementation. Convention facility integration opportunities remain nascent relative to Gauteng benchmarks.
Free State
Bloemfontein and surrounding catchments exhibit limited integrated resort penetration compared to coastal and corridor markets. Financial Intelligence Centre Act compliance requirements strengthen sector legitimacy for international tour operator partnerships. Mangaung metro infrastructure constraints limit large-scale hospitality deployment.
South Africa Casino Tourism Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South Africa's casino tourism sector. Premium integrated resorts deploy capital-intensive biometric systems and cashless gaming infrastructure, while mid-tier properties compete on locational convenience and legacy loyalty bases. The market structures around three archetypes: balance-sheet-heavy resort operators, transit-proximate convention-gaming hybrids, and limited-service standalone facilities. Competitive moves concentrate on M&A consolidation of provincial license portfolios and strategic partnerships with international tour operators.
Within the integrated resort tier, Sun International and Tsogo Sun Gaming occupy dominant positions across Gauteng and KwaZulu-Natal corridors, exemplifying scale-driven archetypes with multi-property provincial portfolios. Peermont Global represents the transit-proximate hybrid model, anchoring conference-gaming revenue streams near OR Tambo International Airport. These three operators collectively illustrate how regulatory compliance capacity and capital access bifurcate competitive positioning in a tightening licensing environment.
| Leading Market Players |
|---|
| Sun International |
| Tsogo Sun Gaming |
| Peermont Global |
| Urvi Tours |
| Thomas Cook |
| Abercrombie and Kent Safaris |
| Heena Tours & Travels |
| Dook International |
| Happy Vacations Tours and Travels |
| Others |
Value Network & Pricing Analysis
Cashless gaming infrastructure replacing legacy chip-and-token systems simultaneously reshapes supplier geography toward technology hubs and compresses transaction-cost economics across Gauteng and KwaZulu-Natal properties. This substitution dynamic rewards operators with capital access for biometric and digital wallet deployment while straining mid-tier competitors dependent on traditional hardware supply chains.
Pricing Analysis
Gauteng's Johannesburg-Pretoria corridor commands premium positioning against North West and Eastern Cape markets, with three-tier pricing structure across premium, standard, and economy levels differentiating Sun International and Tsogo Sun Gaming complexes from limited-service competitors. Price differentiation hinges on certification grade from the National Gambling Board and proximity to OR Tambo International Airport transit volume. Pricing pressure stems from provincial tax rate differentials that fragment capital allocation efficiency. Convention-driven corporate segments show lowest price sensitivity; local repeat visitors exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for hospitality-trained croupiers and biometric facial recognition hardware extend operational planning horizons beyond traditional gaming equipment procurement cycles. Supply concentrates in South Africa for dealer talent, with technology hardware sourcing from Taiwan, South Korea, and China for cashless gaming infrastructure. Raw material dependencies span semiconductor chips, surveillance camera arrays, and loyalty program software licenses. Single-source vulnerability runs through specialized compliance technology vendors serving Financial Intelligence Centre Act mandates. Distribution runs through direct operator-vendor partnerships bypassing traditional gaming equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millennial digital-native preferences fragment demand into experiential entertainment precincts, creating white-space opportunities for operators capable of esports lounge and immersive theater deployment beyond traditional slot-centric configurations.
For Market Incumbents: Fortify license portfolio concentration in Gauteng and KwaZulu-Natal by accelerating renewal applications ahead of tightening capital adequacy mandates from provincial gambling boards. Deepen backward integration into hospitality training academies to secure croupier talent pipelines against wage inflation from standalone casino competitors. Prioritize biometric facial recognition deployment to widen service-quality gaps against mid-tier properties lacking comparable capital access. For New Entrants and Emerging Players: National Gambling Board certification fast-track through provincial gambling board pre-application consultations enables first-mover positioning in Port Elizabeth and East London secondary city developments. Target underpenetrated Eastern Cape catchments where convention facility integration remains nascent relative to Gauteng benchmarks. Pursue hybrid conference-gaming revenue streams distinct from pure leisure visitation through airport-proximate site selection. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed integrated resort operators seeking exit liquidity ahead of license renewal capital expenditure escalations. Five-to-ten year viability hinges on regulatory compliance capacity and technology deployment scale rather than locational convenience alone. Monitor provincial gambling board machine-to-table ratio mandate enforcement frequency as inflection indicator for operational burden escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Player Tracking Deployment | Accelerates VIP recognition and personalizes service delivery at Sun International and Tsogo Sun Gaming properties. |
| Cashless Gaming Infrastructure Rollout | Compresses transaction latency while generating behavioral data for loyalty program architecture redesign. |
| Convention Facility Integration | Captures OR Tambo International Airport transit volume through hybrid conference-gaming revenue streams. |
| Secondary City License Application | Secures first-mover positioning in Port Elizabeth and East London under National Gambling Board coordination. |
| Hospitality Training Academy Investment | Addresses croupier scarcity inflating wage structures across Gauteng and KwaZulu-Natal corridors. |
Research Methodology
A standing panel of casino operations directors, provincial gambling board compliance officers, hospitality training academy administrators, and international tour operator partnership managers provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from National Gambling Board licensing records, Gauteng Gambling Board enforcement statistics, KwaZulu-Natal Gambling Board tax revenue disclosures, and Financial Intelligence Centre Act compliance audit summaries. Bottom-up property-level revenue modeling and top-down provincial gaming tax aggregation enabled triangulation across analysis sources.
Consistency checks validated volume and value outputs against provincial gambling board gaming position counts and national tourism arrival statistics across the analysis window. Segmentation dimensions modeled encompass facility type, customer demographic cohort, gaming experience tier, and event type integration. CAGRs derived from license renewal timelines and capital deployment trajectories reported by integrated resort operators. Industry-specific forecast inputs incorporated machine-to-table ratio mandate evolution and millennial visitation share penetration curves.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and sustained sub-Saharan African inbound leisure growth assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for abrupt provincial tax rate harmonization or national responsible gaming mandate escalation. Revision becomes warranted when Financial Intelligence Centre Act compliance staffing cost inflation crosses thresholds that compress mid-tier operator viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
South Africa Faith-Based Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
SAVE Tourism Market
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Italy Culinary Tourism Market
Destination Management and Attractions
Museums Tourism Market
Destination Management and Attractions
UAE Faith Based Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
Music Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
Cultural Tourism Market