
 USA Faith Based Tourism Market | 2026-2036
USA Faith Based Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
USA Faith Based Tourism Market Analytics
A capital-intensity divergence between online travel aggregators and specialized faith-based operators is bifurcating competitive dynamics in the USA Faith Based Tourism Market. Expedia Group leverages its platform infrastructure and search algorithms to capture incidental religious travelers booking ancillary experiences. Globus Family of Brands sustains decades of ecclesiastical relationships and curated itineraries that anchor its position in group pilgrimage logistics. Peter's Way Tours specializes in Catholic-focused journeys to Marian shrines and Vatican-sanctioned sites, differentiating through clergy-led educational programming.
Faith based tourism encompasses travel undertaken primarily for religious devotion, spiritual formation, or denominational heritage exploration, typically involving structured itineraries to sacred sites, retreat centers, or mission fields with durations ranging from weekend intensives to multi-week overseas pilgrimages. The commercial purpose centers on facilitating transformative experiences that deepen religious commitment while generating hospitality revenue for host communities and religious institutions. Pilgrimage and heritage tours command the largest share of current bookings, reflecting mature demand from aging Catholic and Protestant demographics with established travel patterns and discretionary savings. Spiritual retreats represent the fastest-expanding segment, driven by millennial and Gen Z seekers pursuing wellness-integrated contemplative practices outside traditional congregational structures. Mission trips retain concentrated margin pools through church organization block contracts, though per-trip yields compress as younger participants prioritize shorter-term service engagements over traditional two-week deployments.
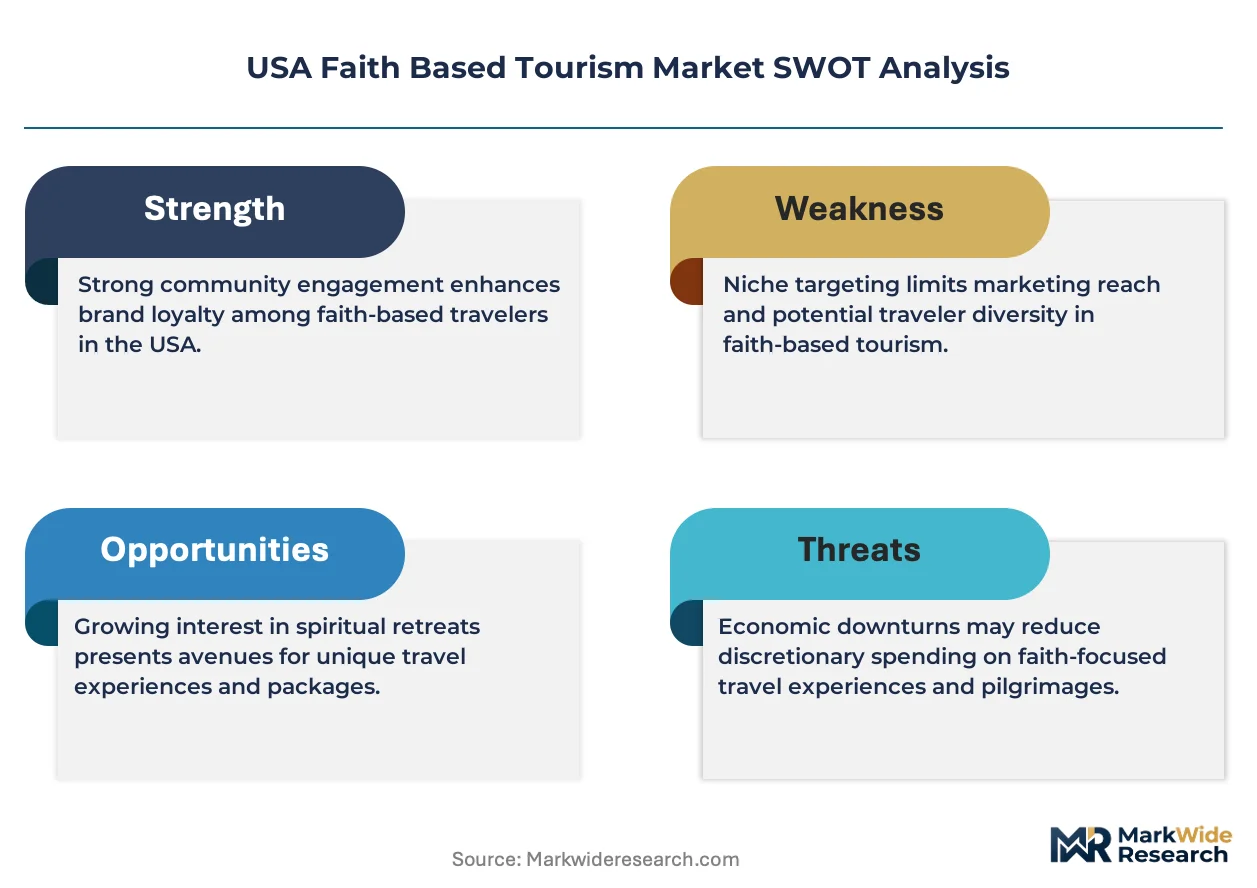
The Department of Transportation enforces motorcoach safety standards that govern overland pilgrimage transport, while the IRS monitors nonprofit tax treatment of church-sponsored travel to prevent private inurement violations. State-level lodging tax regimes vary across jurisdictions, creating compliance complexity for operators routing multi-state heritage circuits. Stakeholders must monitor how denominational membership declines reshape addressable demand, while evaluating whether digital pilgrimage alternatives permanently substitute for physical travel among cost-sensitive or mobility-limited segments.
Market Dynamics
Megachurch networks across the Bible Belt are consolidating group travel procurement, shifting supplier power toward operators capable of handling thousand-passenger block contracts with integrated pastoral programming and DOT-compliant motorcoach logistics.
Growth Catalysts
- IRS Safe Harbor Provisions:Clarified tax treatment for church-sponsored educational travel reduces compliance friction for nonprofit organizers, expanding addressable group volume.
- Retirement-Age Demographics:Aging Catholic and Protestant populations with accumulated savings sustain premium pilgrimage demand to Marian shrines and Reformation heritage sites.
- Wellness-Spirituality Convergence:Monastery-based contemplative retreats attract secular-adjacent seekers, broadening revenue pools beyond traditional congregational channels.
Market Restraints
- Motorcoach Operator Concentration:Consolidation among DOT-certified carriers in the Southeast limits capacity for peak-season pilgrimage surges, compressing margins.
- Fuel Cost Volatility:Diesel price swings directly erode per-mile yields on multi-state heritage circuits where fixed pricing dominates group contracts.
- Denominational Membership Decline:Shrinking mainline Protestant congregations reduce the base of organized travelers available for recurring mission trip and retreat bookings.
Strategic Opportunities
- Appalachian Retreat Corridors:Underdeveloped rural counties in Kentucky and Tennessee offer land-cost advantages for faith-based wellness campus development.
- Digital-Physical Hybrid Pilgrimages:Pre-trip virtual formation modules combined with abbreviated site visits reduce total trip duration while preserving per-capita revenue.
- State Tourism Tax Incentives:Mississippi and Alabama lodging tax abatements for religious group bookings improve net yields versus standard leisure travel.
Industry Challenges
- Clergy-Chaplain Recruitment:Scarce dual-qualified personnel possessing both theological credentials and group travel logistics expertise constrain programming quality.
- Legacy Reservation System Migration:Specialized operators struggle to integrate church management databases with modern booking platforms, fragmenting customer data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Faith Based Tourism Market |
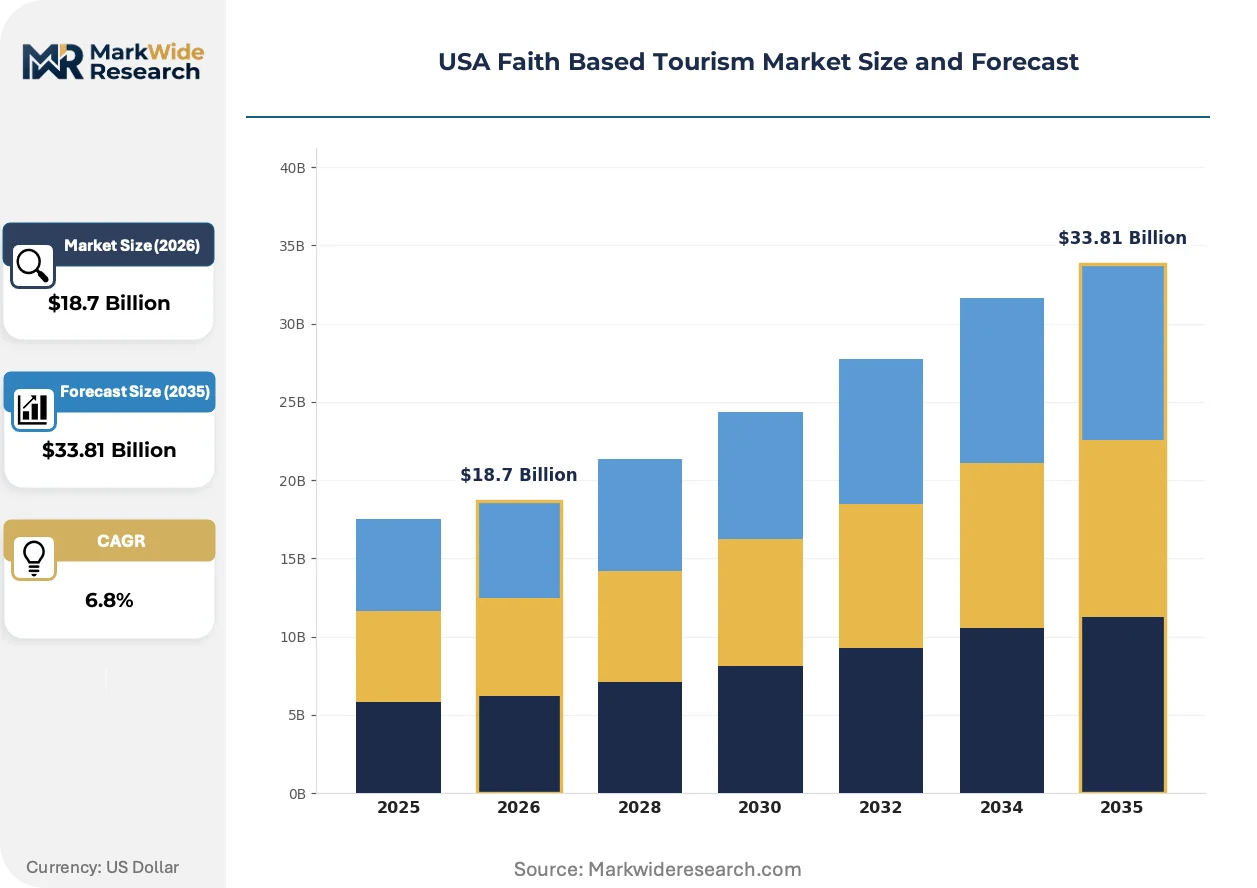
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tour Type: Pilgrimage, Heritage Tours, Spiritual Retreats, Mission Trips Visitor Type: Solo Travelers, Groups, Families, Church Organizations Accommodation Type: Hotels, Hostels, Retreat Centers, Vacation Rentals Activity Type: Workshops, Community Service, Site Visits, Worship Services |
| Companies Covered | Expedia Group, Booking Holdings, Globus Family of Brands, 206 Tours, Pilgrim Tours, Travel with Purpose, Unitours, Peter’s Way Tours, American Christian Tours, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Faith Based Tourism Market Evolving Landscape
Technology is fragmenting the traditional group pilgrimage model, enabling self-directed spiritual travel while forcing incumbent operators to reconfigure around smaller, higher-touch cohorts with curated educational content.
Artificial intelligence itinerary builders are decomposing the role of traditional group tour operators by allowing individual travelers to construct personalized multi-site religious journeys. Megachurch travel coordinators in Texas and Georgia now pilot these tools for member self-booking. The shift compresses commission pools for legacy operators while elevating demand for clergy-led educational modules sold as add-ons.
The Department of Transportation's updated motorcoach safety inspection protocols now mandate electronic logging device integration for all interstate pilgrimage transport. Operators must retrofit aging fleets or face route restriction penalties. Smaller family-run carriers in the Ozarks and Piedmont regions lack capital for compliance, accelerating consolidation toward national fleet operators.
Younger travelers increasingly book abbreviated "micro-pilgrimages" spanning 48-72 hours versus traditional week-long deployments. Church youth pastors in Florida and California now prioritize regional sites accessible by carpool over air travel to mission fields. This pattern compresses per-trip revenue while expanding total trip frequency, forcing operators to optimize for turnover velocity rather than extended-stay yields.
USA Faith Based Tourism Market Segmentation
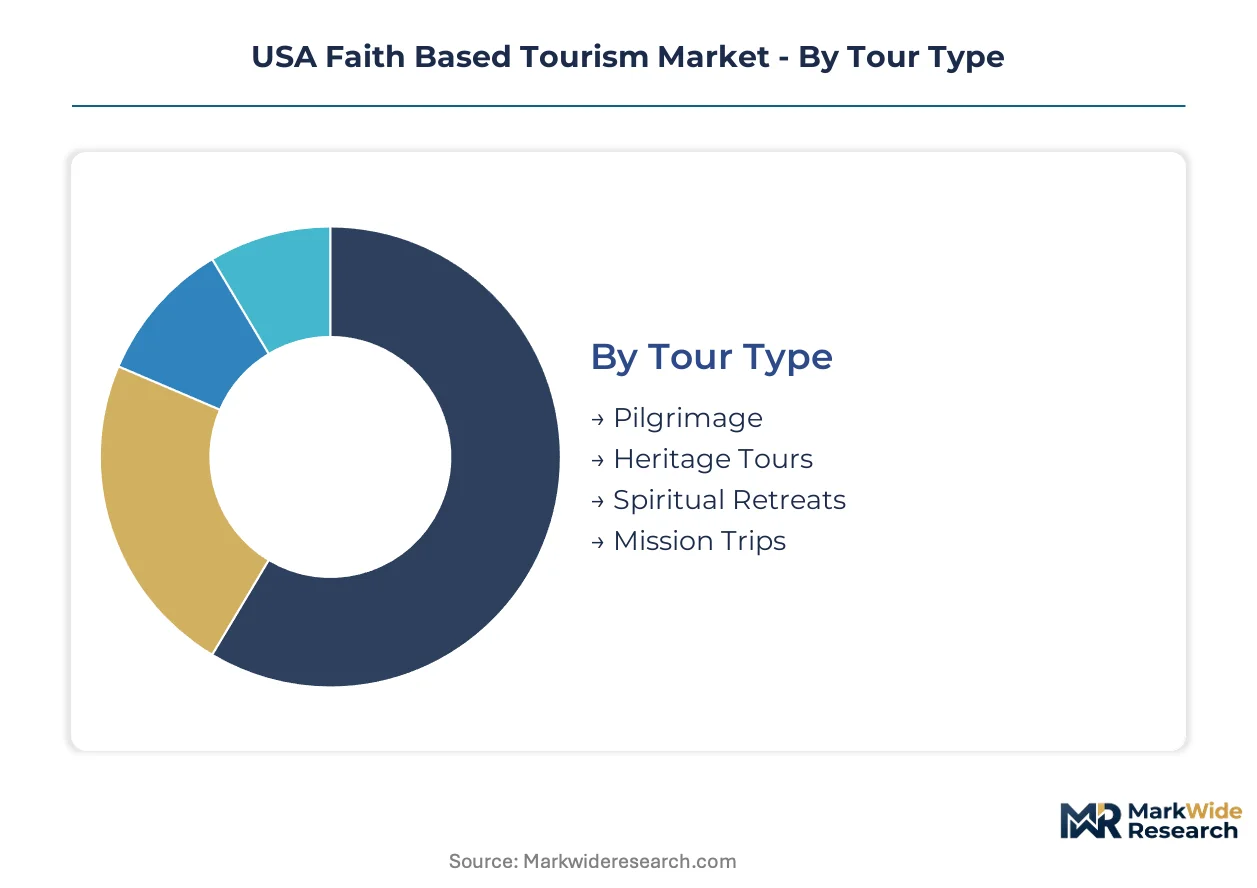
Segmentation in faith based tourism reveals how traveler intent, organizational affiliation, and trip duration reshape booking patterns and revenue per capita. Operators must align service tiers to these distinctions or risk margin erosion from mismatched capacity deployment.
Tour Type:
Pilgrimage and heritage circuits face acute substitution pressure from digital formation platforms and abbreviated micro-pilgrimages, while mission trips retain contractual stickiness through church procurement consolidation.
- Pilgrimage:Structured journeys to canonized sites such as Marian shrines or Reformation landmarks, typically spanning 7-14 days with clergy-led liturgical programming. Demand concentrates among aging Catholic demographics in the Northeast and Midwest, sustained by accumulated retirement savings and established devotional travel patterns.
- Heritage Tours:Denominational history circuits tracing Methodist circuit-rider routes, Mormon pioneer trails, or African American church legacy sites. Bible Belt megachurches in Texas and Georgia drive recurring group volume through pastoral anniversary programming and elder congregation travel.
- Spiritual Retreats:Monastery-based contemplative intensives attracting secular-adjacent wellness seekers outside traditional congregational structures.
- Mission Trips:Service deployments to domestic or international ministry fields, typically contracted through church youth pastor networks.
Pilgrimage anchors the volume base while spiritual retreats gain share at the steepest rate.
Visitor Type:
Cost tier stratification separates high-touch group procurement from price-sensitive independent booking, with church organizations commanding volume discounts unavailable to solo travelers.
- Church Organizations:Institutional buyers negotiating thousand-passenger block contracts with integrated pastoral programming and DOT-compliant motorcoach logistics. Procurement concentrates among Bible Belt megachurch networks consolidating travel spend under single coordinators.
- Groups:Cohorts of 15-40 travelers from single congregations or regional denominational associations, typically booking through specialized faith-based operators rather than online aggregators.
- Families:Multi-generational units seeking heritage education for children alongside devotional content for adults.
- Solo Travelers:Individual pilgrims using AI itinerary builders to construct self-directed journeys, compressing commission pools for legacy operators.
Church organizations command the pricing power while solo travelers expand most quickly through platform-enabled self-booking.
Accommodation Type:
Application-specific lodging requirements vary sharply between contemplative silence mandates and youth mission trip bunkhouse economics, forcing operators to maintain heterogeneous supplier relationships.
- Retreat Centers:Purpose-built contemplative facilities with chapel infrastructure, silence protocols, and meal services aligned to monastic schedules. Demand concentrates in Appalachian corridor counties of Kentucky and Tennessee where land costs enable wellness campus development.
- Hotels:Branded properties accommodating large church groups with meeting space for evening worship and pastoral debrief sessions.
- Hostels:Budget bunkhouse arrangements typical for youth mission trip deployments prioritizing per-capita cost minimization.
- Vacation Rentals:Distributed lodging for extended-family heritage travel requiring kitchen facilities and flexible check-in.
Hotels retain the revenue concentration while retreat centers capture the margin expansion from wellness-spirituality convergence.
Activity Type:
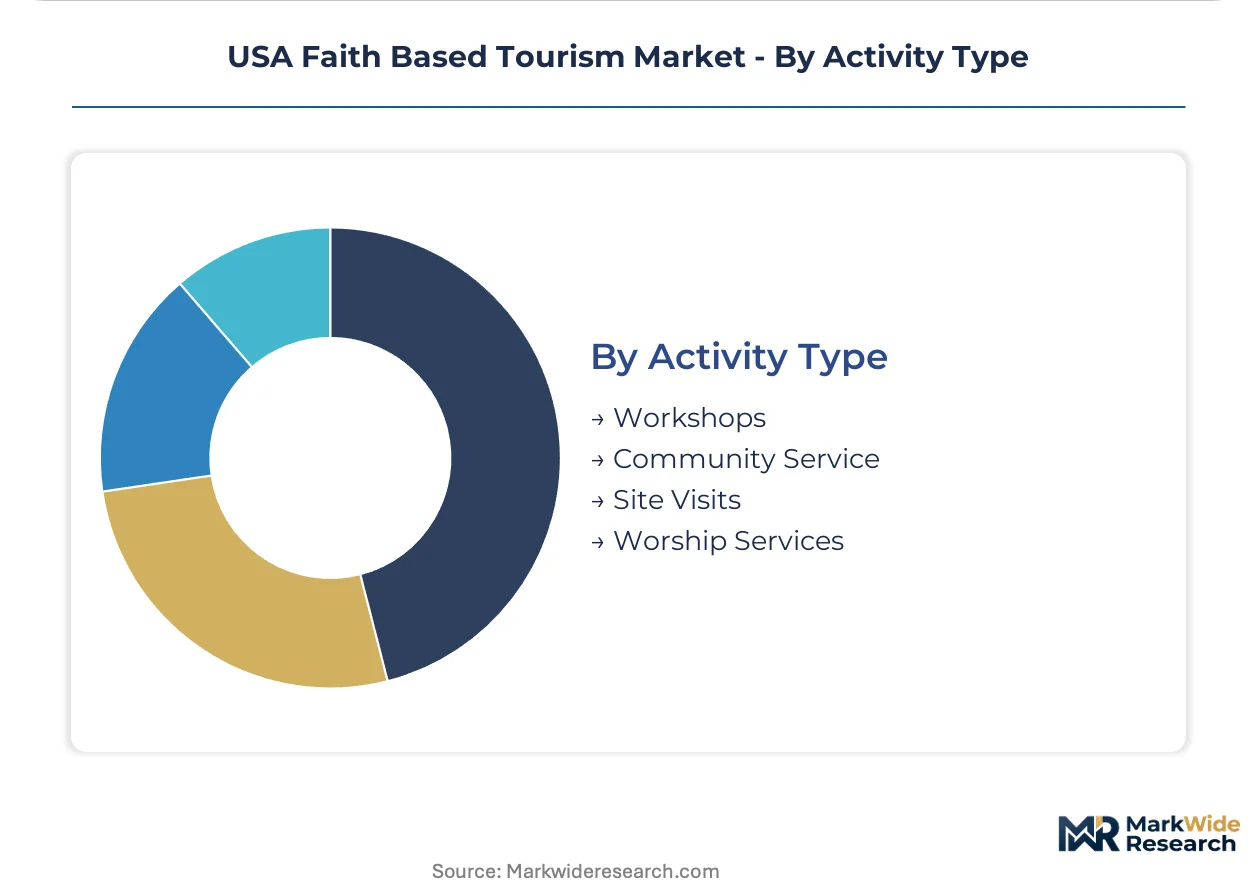
Customer type differentiation separates educational programming from service delivery, with workshops and site visits competing for limited trip duration against worship obligations.
- Site Visits:Curated encounters with sacred architecture, archaeological remains, or denominational historical markers, typically requiring advance reservation and clergy guide coordination. Demand concentrates in aging Protestant and Catholic demographics with established travel patterns and discretionary savings.
- Workshops:Formation-intensive sessions on spiritual disciplines, biblical archaeology, or interfaith dialogue, often led by seminary faculty or recognized authors.
- Community Service:Hands-on ministry deployment ranging from construction projects to medical clinics, contracted through church organization block agreements.
- Worship Services:Liturgical participation at destination sites, from Vatican Mass attendance to regional revival meetings.
Site visits generate the booking frequency while workshops achieve the highest per-capita add-on revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas megachurch corridors while retreat operators in rural Appalachia compete on land-cost advantages. The Southeast commands premium block-contract rates through consolidated procurement networks. California and Florida fragment into price-sensitive independent booking patterns.
Texas
Megachurch networks in Dallas-Fort Worth and Houston consolidate thousand-passenger pilgrimage procurement through single travel coordinators. The Texas Department of Transportation enforces commercial vehicle safety standards that govern DOT-compliant motorcoach logistics for interstate heritage circuits. San Antonio anchors Catholic heritage demand through missions trail programming and Marian devotion sites.
Southeast
Bible Belt states from Georgia to Alabama drive recurring group volume through pastoral anniversary programming and elder congregation travel. Mississippi and Alabama lodging tax abatements for religious group bookings improve net yields versus standard leisure travel. Atlanta serves as the motorcoach consolidation hub where DOT-certified carriers coordinate multi-state circuit logistics.
Appalachia
Kentucky and Tennessee rural counties offer land-cost advantages for faith-based wellness campus development targeting contemplative retreat demand. State tourism development authorities in both states administer rural enterprise zone incentives for hospitality infrastructure. The Cumberland Plateau corridor attracts monastery-based retreat operators seeking silence-protocol facilities outside urban cost structures.
California
Church youth pastors in Los Angeles and Orange County prioritize regional micro-pilgrimages accessible by carpool over air travel to mission fields. The California Public Utilities Commission regulates charter bus operations for intrastate youth group transport. San Diego anchors cross-border mission trip deployment to Baja California ministry fields through established church organization contracts.
Florida
Retirement-age Catholic populations in Miami-Dade and Tampa Bay sustain premium pilgrimage demand to Marian shrines with discretionary savings accumulated over decades. The Florida Department of Transportation coordinates with federal motorcoach safety inspectors on interstate pilgrimage route compliance. Orlando functions as the package tour origination point for Caribbean and Latin American mission trip deployments.
USA Faith Based Tourism Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with online aggregators capturing incidental religious travelers through platform infrastructure while specialized operators sustain ecclesiastical relationships for group logistics. The market structure bifurcates between scale-driven digital platforms and relationship-intensive pilgrimage specialists. Three archetypes dominate: platform aggregators leveraging search algorithms, heritage operators with decades of denominational contracts, and niche clergy-led programming specialists. Competitive moves concentrate on M&A for church management database integration and strategic partnerships with DOT-certified motorcoach carriers.
Among platform-scale aggregators, Expedia Group and Booking Holdings occupy positions capturing self-directed spiritual travelers through AI-enabled itinerary construction. Within the specialized operator tier, Globus Family of Brands exemplifies the heritage circuit archetype through sustained group pilgrimage logistics capabilities. Peter's Way Tours represents the clergy-led programming specialist model focused on Catholic-focused journeys with educational content. These three anchors illustrate how competitive positioning diverges between technology-mediated discovery and relationship-mediated group procurement.
| Leading Market Players |
|---|
| Expedia Group |
| Booking Holdings |
| Globus Family of Brands |
| 206 Tours |
| Pilgrim Tours |
| Travel with Purpose |
| Unitours |
| Peter's Way Tours |
| American Christian Tours |
| Others |
Value Network & Pricing Analysis
DOT motorcoach safety certification gates both operator qualification and price differentiation simultaneously, as carriers lacking electronic logging device compliance face route restrictions that push group contracts toward premium-certified national fleets. This regulatory filter concentrates pricing power among compliant operators while compressing margins for non-certified regional carriers locked out of interstate pilgrimage circuits.
Pricing Analysis
Configured-to-order pricing for clergy-led programming with integrated pastoral content commands substantial premiums over standardized heritage circuit packages. Three-tier pricing structure across premium, standard, and economy levels separates bespoke Vatican-sanctioned journeys from packaged Bible Belt circuits and bare-bones youth mission deployments. Pricing pressure stems from AI itinerary builders enabling solo traveler self-booking that bypasses traditional operator commissions. Megachurch organizations exhibit lowest price sensitivity through thousand-passenger block contracts, while solo travelers using platform aggregators drive cost compression.
Supply Chain Analysis
The United States anchors motorcoach fleet operations and DOT-certified carrier networks, while Mexico feeds cross-border mission trip deployment infrastructure and Canada supplies specialized retreat center construction materials. Diesel fuel, commercial vehicle insurance, and clergy-chaplain labor constitute the primary input dependencies. Single-source vulnerability concentrates in Southeast motorcoach operator consolidation, where peak-season capacity constraints risk contract fulfillment. Distribution runs through church organization procurement coordinators who consolidate member bookings before forwarding to specialized operators or platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Bible Belt megachurch networks consolidating thousand-passenger procurement under single travel coordinators, fragmenting supplier leverage across smaller denominational associations and independent congregations.
For Market Incumbents: Consolidate ecclesiastical relationships through exclusive pastoral programming partnerships that AI itinerary builders cannot replicate. Integrate backward into DOT-certified motorcoach operations to secure capacity during peak pilgrimage seasons. The threat of digital platform disintermediation demands channel control through proprietary church management database integration. For New Entrants and Emerging Players: Lead with micro-pilgrimage optimization targeting Florida and California youth pastors prioritizing 48-72 hour regional deployments over traditional week-long circuits. The Appalachian retreat corridor offers the most penetrable geography, with Kentucky and Tennessee rural counties providing land-cost advantages for wellness campus development. A direct-to-youth-pastor digital booking platform with carpool coordination tools provides the strongest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic logging device fleet retrofitting and wellness campus development, favoring scaled operators over family-run regional carriers. Long-term viability across the next decade rests on capturing church organization block contract relationships before procurement consolidates further. Acquisition targets should profile specialized operators with embedded megachurch network contracts. The signal to watch is DOT enforcement intensity against non-compliant carriers, which would accelerate fleet consolidation toward capitalized national players.| Strategic Initiative | Industry Significance |
|---|---|
| DOT Compliance Fleet Retrofit | Electronic logging device integration secures interstate route access for pilgrimage transport contracts. |
| Church Management System Integration | Direct API connections to congregational databases lock in recurring group booking flows. |
| Appalachian Wellness Campus Development | Kentucky and Tennessee rural enterprise zones reduce land acquisition costs for retreat infrastructure. |
| Clergy-Chaplain Certification Program | Dual-qualified personnel pipelines address scarce theological-logistics expertise constraining programming quality. |
| Micro-Pilgrimage Product Line Launch | 48-72 hour regional offerings capture Florida and California youth pastor demand for abbreviated deployments. |
Research Methodology
Operator-level perspectives from motorcoach fleet managers, megachurch travel coordinators, retreat center directors, and DOT compliance officers anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against FMCSA safety databases, state tourism development authority filings, and IRS nonprofit tax guidance. SEC filings from publicly traded travel platforms, church organization procurement records, and regional lodging tax revenue reports provided quantitative grounding. Bottom-up trip volume estimates from specialized operators triangulated against top-down addressable demand calculations from denominational membership data.
Sensitivity analysis tested forecast outputs against variable assumptions for denominational decline rates, fuel cost volatility bands, and DOT enforcement intensity scenarios across the projection horizon. Segmentation dimensions modeled include tour type, visitor type, accommodation category, and activity format, with additional granularity on regional procurement consolidation patterns. CAGRs derived from cohort-specific growth trajectories weighted by current booking share. Forecast inputs incorporated clergy-chaplain supply constraints, motorcoach fleet age distributions, and state-level lodging tax incentive program durability.
The analysis sits within stated boundaries; outcomes outside sustained megachurch network expansion or abrupt DOT regulatory tightening would require recalibration. Forecasts reflect documented assumptions about retirement-age demographic travel propensity and wellness-spirituality convergence durability. Specific risks that could revise projections include accelerated mainline Protestant membership collapse, diesel price spikes exceeding historical volatility bands, or digital pilgrimage alternatives achieving substitutability for physical travel. Recalibration cycles align with material shifts in denominational procurement consolidation or federal motorcoach safety protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Italy Culinary Tourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
Safari Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
Alternative Tourism Market