
 Global Desert Tourism Market | 2026-2036
Global Desert Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Global Desert Tourism Market Foresight
The UAE is reshaping desert tourism infrastructure through billion-dollar conservation-resort hybrids that blend Bedouin heritage with renewable-powered operations. Intrepid Travel leverages community-based partnerships to sustain low-impact cultural circuits across North African dunes. White Desert anchors ultra-premium Antarctic-style camps in Oman and Namibia, controlling exclusive fly-in access to remote formations. Discover Morocco competes through artisan-integrated medina-to-desert itineraries that extend traditional craftsmanship into Saharan hospitality.
Desert tourism encompasses travel to arid regions where annual precipitation falls below 250 millimeters, encompassing guided expeditions, fixed-base lodges, and adventure activities across sand, rock, and salt-flat terrains. Operators engineer water recycling systems, solar microgrids, and lightweight modular shelters to minimize ecological footprint while delivering comfort in extreme thermal ranges. Adventure Travel dominates booking volumes among younger demographics seeking physical challenge, while Luxury Vacation captures the highest margin pools through personalized service ratios and restricted capacity. Eco Lodges represent the fastest-growing accommodation category as certification schemes from the Global Sustainable Tourism Council filter into operator procurement standards.
Morocco's Ministry of Tourism and the UAE's Environment Agency enforce carrying-capacity limits and renewable-energy mandates for new desert concessions. The EU Green Deal's carbon-border adjustments are pressuring European tour operators to document Scope 3 emissions from long-haul desert flights, reshaping supplier selection. Stakeholders must monitor how Saudi Arabia's Red Sea Development Company integrates marine and desert zoning permits as it scales its tourism corridor.
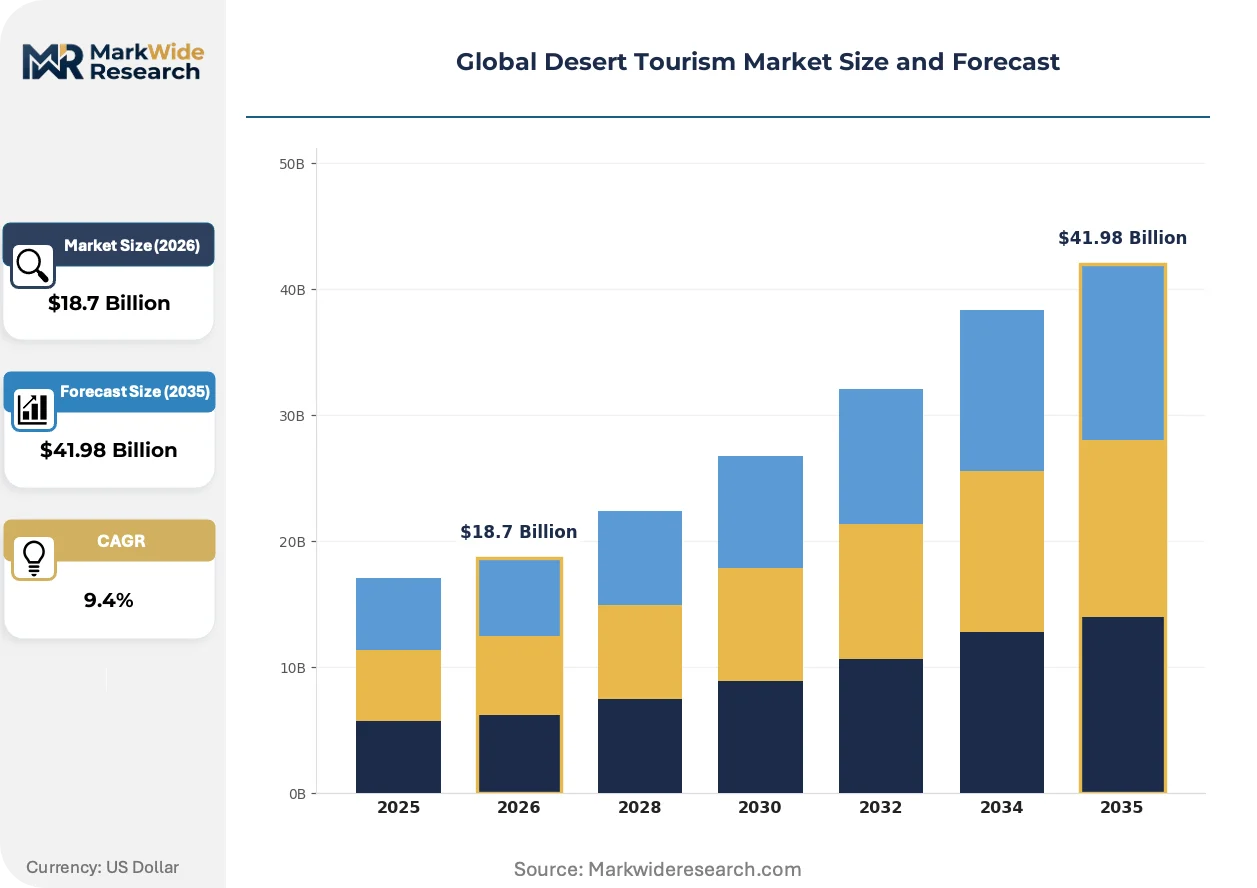
Market Dynamics
Sovereign wealth funds are converting arid landscapes into premium hospitality destinations, reshaping competitive positioning through billion-dollar conservation-resort hybrids that blend Bedouin heritage with renewable-powered operations.
Growth Catalysts
- EU Green Deal carbon-border adjustments:European tour operators now document Scope 3 emissions from long-haul desert flights, filtering supplier selection toward certified sustainable operators.
- Conservation-tourism zoning:Morocco's Ministry of Tourism streamlines protected area designations under its environmental ministry, enabling sustainable access to Saharan corridors.
- Fly-in infrastructure:Ultra-premium Antarctic-style camps in Oman and Namibia control exclusive access to remote formations, expanding addressable high-net-worth demand.
Market Restraints
- Water scarcity economics:Fixed-base lodges in the UAE and Saudi Arabia face 40-60% higher operational costs from reverse-osmosis and recycling systems required in sub-250mm precipitation zones.
- Carrying-capacity ceilings:Morocco's Ministry of Tourism and the UAE's Environment Agency enforce hard visitor limits per hectare, capping revenue scalability at established properties.
- Aviation substitution pressure:Rail and coach networks cannot replicate fly-in access to remote dune formations, locking operators into carbon-intensive transport modes.
Strategic Opportunities
- Artisan-integrated hospitality:Medina-to-desert itineraries that extend traditional craftsmanship into Saharan accommodations capture cultural-authenticity premiums in Morocco.
- Marine-desert corridor zoning:Saudi Arabia's Red Sea Development Company integrates coastal and interior permits, enabling multi-biome itineraries from single regulatory frameworks.
- Community-based partnership models:Low-impact cultural circuits across North African dunes leverage local governance structures for exclusive territory access.
Industry Challenges
- Certification procurement timelines:Global Sustainable Tourism Council standards filter into operator procurement slowly, delaying eco-lodge branding advantages by 18-24 months.
- Modular shelter integration:Lightweight solar microgrids and water recycling systems require specialized technical talent scarce in remote desert labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Desert Tourism Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tourism Type: Adventure Travel, Cultural Exploration, Eco Tourism, Luxury Vacation, Wellness Retreats Accommodation Type: Luxury Camps, Boutique Hotels, Eco Lodges, Homestays, Desert Resorts Activity Type: Sandboarding, Camel Trekking, Stargazing, Dune Bashing, Wildlife Photography Customer Segment: Solo Travelers, Families, Couples, Professional Groups, Retirees |
| Companies Covered | Sun Trails, Intrepid Travel, White Desert, Moroccan Desert Trips, Mayflower Cruises & Tours, Discover Morocco, Morocco Desert Trips, TourRadar, Morocco Joy Travel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Desert Tourism Market Shifts & Advancements
Digital twinning and virtual pre-experience platforms are compressing booking cycles for high-value desert itineraries, while regulatory carbon-accounting mandates reshape operator-supplier relationships.
Immersive pre-departure visualization technology is virtualizing the discovery phase of luxury desert travel. High-net-worth travelers now explore remote formations through photorealistic renderings before committing to fly-in charters. Operators deploying these platforms report compressed decision timelines and reduced cancellation rates for premium-priced expeditions.
REACH chemical restrictions and the EU Green Deal's carbon-border adjustments are forcing European tour operators to requalify ground suppliers across North Africa and the Middle East. Documentation requirements now extend to Scope 3 aviation emissions and lodge-level renewable-energy certificates. German and French operators are accelerating partnerships with properties holding GSTC certification to maintain market access.
Younger demographics now book physical-challenge itineraries through direct-to-operator channels, bypassing traditional travel intermediaries. Adventure Travel segments are disintermediating wholesale distributors in favor of app-based booking platforms with real-time availability. This channel shift is most visible in Australian and UK outbound markets where Intrepid Travel and similar operators have built proprietary digital infrastructure.
Global Desert Tourism Market Segmentation
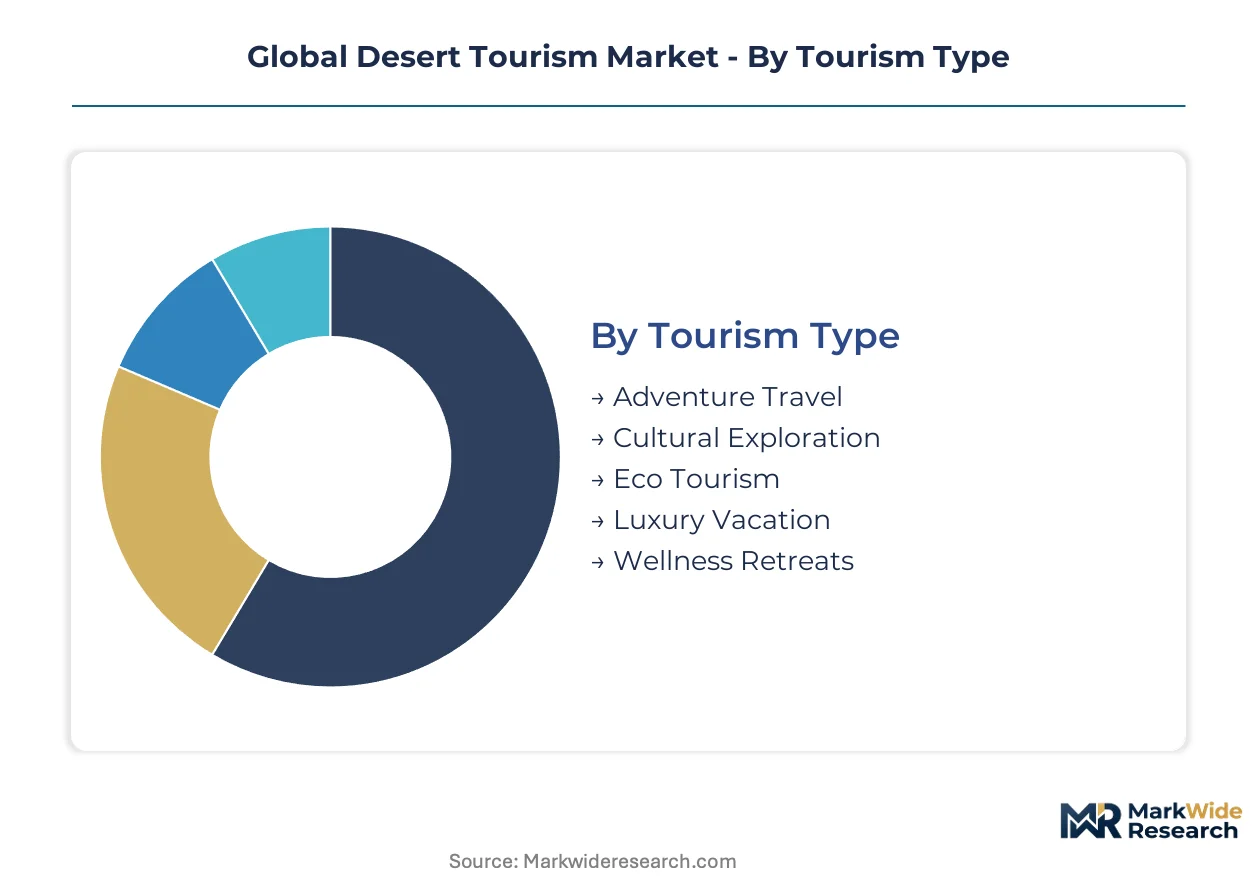
Desert tourism operators configure product portfolios around thermal extremes, cultural proximity, and transport logistics that vary sharply across arid zones. Segmentation reveals where margin pools concentrate and which traveler profiles justify infrastructure investment in water-scarce environments.
Tourism Type:
Cost tier determines operator investment in fixed infrastructure versus mobile assets across arid destinations.
- Adventure Travel:Physical-challenge itineraries emphasize dune trekking, endurance racing, and technical climbing in Namibia's Namib-Naukluft and Oman's Empty Quarter. Australian and UK outbound markets book directly through operator apps, bypassing wholesale intermediaries. Youth demographics drive volume here.
- Luxury Vacation:Personalized service ratios and restricted capacity define this tier. Fly-in Antarctic-style camps in Namibia and Oman command premium positioning through exclusive access to remote formations. Sovereign wealth-backed projects in the UAE and Saudi Arabia target this segment with conservation-resort hybrids.
- Eco Tourism:GSTC-certified circuits emphasize low-impact mobility and community revenue-sharing. Morocco's protected area designations enable sustainable Saharan access.
- Cultural Exploration:Medina-to-desert itineraries integrate artisan workshops with overnight Berber camp experiences. Morocco's Ministry of Tourism streamlines these corridors.
- Wellness Retreats:Thermal therapy and silence-based programming leverage extreme aridity for metabolic recovery positioning.
Luxury Vacation commands the established base. The steepest expansion runs through Eco Tourism.
Accommodation Type:
Application dictates engineering requirements for water recycling, solar microgrids, and modular shelter systems in sub-250mm precipitation zones.
- Eco Lodges:Lightweight modular shelters with closed-loop water systems and photovoltaic arrays minimize ecological footprint. Certification procurement timelines from the Global Sustainable Tourism Council delay branding advantages. Morocco and Namibia lead development here.
- Desert Resorts:Fixed-base properties in the UAE and Saudi Arabia face 40-60% higher operational costs from reverse-osmosis infrastructure. Renewable-energy mandates from the UAE's Environment Agency reshape capital planning.
- Luxury Camps:Seasonal tented inventory allows capacity flexibility without permanent construction in protected zones.
- Boutique Hotels:Small-footprint properties in Morocco's ksar towns blend riad architecture with Saharan access.
- Homestays:Community-based models leverage local governance for exclusive territory access in North African dune systems.
Desert Resorts anchor revenue concentration. The most rapid capacity addition occurs in Eco Lodges.
Activity Type:
Customer type and margin structure vary sharply between motorized access and human-powered or observational experiences.
- Dune Bashing:High-horsepower vehicle fleets generate strong ancillary revenue per visitor in the UAE and Saudi Arabia. Saudi Arabia's Red Sea Development Company integrates these permits with marine zoning for multi-biome itineraries.
- Stargazing:Dark-sky certification programs in Namibia and Chile's Atacama attract astronomy tourism with minimal infrastructure. Scientific partnerships with observatories extend seasonality.
- Camel Trekking:Traditional mobility modes support multi-day circuit logistics in Morocco and Jordan.
- Sandboarding:Equipment-light activity targets day-trip markets from urban desert peripheries.
- Wildlife Photography:Specialist guides and hide infrastructure target oryx, fennec fox, and reptile observation in the Empty Quarter and Namib.
Dune Bashing retains volume leadership. The highest margin expansion attaches to Stargazing.
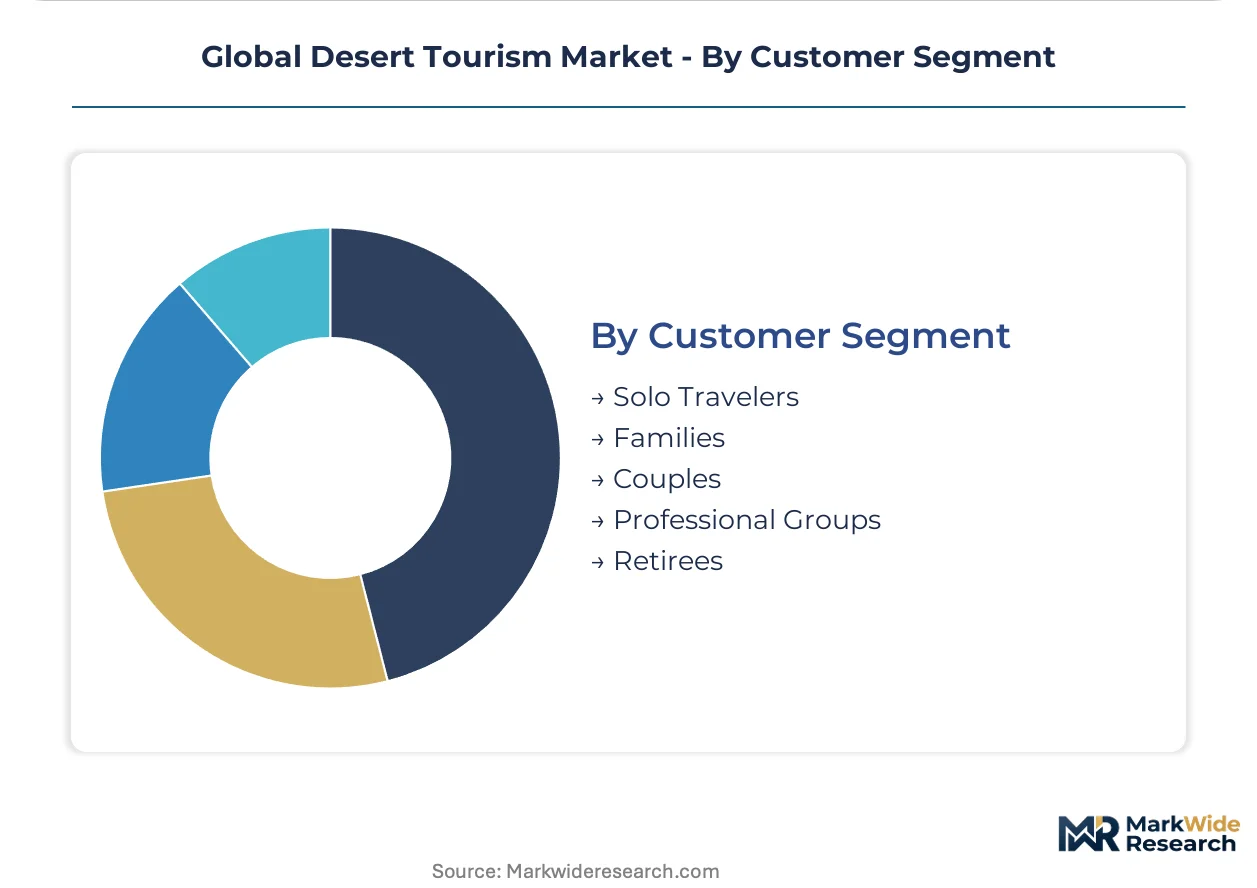
Customer Segment:
Geography and booking channel preferences segment addressable demand for curated versus self-directed desert experiences.
- Couples:Romantic positioning around isolation and astronomical events drives premium pricing in Namibia and Oman. Compressed booking cycles through virtual pre-experience platforms reduce cancellation rates.
- Families:Multi-generational safety requirements and activity breadth favor established resort properties with medical infrastructure. The UAE's giga-projects target this segment with hybrid conservation-education programming.
- Solo Travelers:Risk-mitigation and group-joining preferences favor operator-led circuits in Morocco and Jordan.
- Professional Groups:Corporate retreat and incentive demand concentrates in accessible desert peripheries with conference infrastructure.
- Retirees:Thermal comfort requirements and medical access constraints shape destination selection toward developed desert economies.
Couples generate the highest revenue per available room. Families show the strongest volume growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign wealth deployment and protected-area zoning concentrate desert tourism infrastructure in the Middle East and North Africa. Morocco's national tourism strategy and the UAE's renewable-energy mandates reshape capital allocation across arid hospitality corridors.
United Arab Emirates
Abu Dhabi's Environment Agency enforces renewable-energy mandates for new desert concessions, driving conservation-resort hybrid development. Dubai's giga-projects convert inland dunes into fixed-base hospitality destinations with 40-60% higher operational costs from reverse-osmosis infrastructure. The Empty Quarter border zone anchors premium fly-in camp development.
Morocco
Medina-to-desert itineraries from Marrakech and Fès extend artisan craftsmanship into Saharan hospitality experiences. The Ministry of Tourism streamlines protected area designations under its environmental ministry, enabling sustainable access to Erg Chebbi and M'Hamid corridors. Ouarzazate and Zagora serve as gateway clusters for low-impact cultural circuits.
Saudi Arabia
The Red Sea Development Company integrates marine and desert zoning permits, enabling multi-biome itineraries from single regulatory frameworks. NEOM's northwest region attracts ultra-premium Antarctic-style camp operators through exclusive territory access. Riyadh-based sovereign wealth directs billion-dollar arid landscape conversion.
Namibia
Dark-sky certification programs in the Namib-Naukluft attract astronomy tourism with minimal infrastructure requirements. Community-based partnership models leverage local governance structures for exclusive dune system access. Windhoek and Walvis Bay anchor logistics for fly-in remote formation expeditions.
Oman
The Empty Quarter's Rub' al Khali formations host ultra-premium camps controlling exclusive fly-in access. The Ministry of Heritage and Tourism enforces carrying-capacity limits per hectare in protected zones. Muscat and Salalah serve as coastal gateways for interior desert circuits.
Global Desert Tourism Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with modular shelter and microgrid technology. The vendor base clusters around three archetypes: sovereign wealth-backed conservation-resort developers, community-based partnership operators, and digital-native direct-to-consumer booking platforms. Competitive moves center on exclusive territory access negotiations and GSTC certification procurement.
Within the community-based partnership tier, Intrepid Travel exemplifies direct-to-consumer digital infrastructure for low-impact cultural circuits. White Desert occupies a position among ultra-premium fly-in camp operators with Antarctic-style remote formation access. Discover Morocco anchors the artisan-integrated hospitality archetype, extending medina craftsmanship into Saharan accommodations.
| Leading Market Players |
|---|
| Sun Trails |
| Intrepid Travel |
| White Desert |
| Moroccan Desert Trips |
| Mayflower Cruises & Tours |
| Discover Morocco |
| Morocco Desert Trips |
| TourRadar |
| Morocco Joy Travel |
| Others |
Supply & Pricing Matrix
Dubai's giga-project corridor concentrates fixed-base hospitality capacity, translating sovereign wealth deployment into pricing power across ultra-premium desert accommodations. Reverse-osmosis infrastructure requirements in sub-250mm precipitation zones feed 40-60% operational cost premiums through to rate cards, while renewable-energy mandates from the UAE's Environment Agency reshape capital recovery timelines.
Pricing Analysis
The EU Green Deal's carbon-border adjustments dictate the pricing tier structure across European outbound channels. Three-tier pricing structure across premium fly-in camps, standard lodge properties, and economy circuit tours separates GSTC-certified operators from conventional suppliers. Price differentiation rests on certification grade and exclusive territory access rights. Cost compression in standard-tier properties is intensifying because of water recycling infrastructure amortization. Families represent the most price-sensitive segment; ultra-premium Antarctic-style camps face minimal elasticity.
Supply Chain Analysis
Tariff exposure between European source markets and North African ground suppliers dominates supply chain risk assessment for tour operators. Geographic supply concentration clusters in Morocco, the UAE, and Namibia for operational infrastructure, while China and Germany anchor photovoltaic array and modular shelter component sourcing. Raw material dependencies center on aluminum framing, lithium-ion storage cells, and membrane filtration systems. Single-source vulnerability runs through specialized technical talent for solar microgrid installation. Distribution runs through direct-to-consumer platforms for adventure segments and wholesale intermediaries for family resort bookings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Desert tourism operates as a service-attach opportunity where pre-departure visualization platforms and carbon-accounting documentation layers expand faster than physical accommodation hardware. Recurring revenue from virtual pre-experience subscriptions and certification maintenance contracts outpaces room-night growth.
For Market Incumbents: Insulate established positions through exclusive territory access negotiations with Morocco's Ministry of Tourism and accelerated GSTC certification procurement to preempt regulatory filtering. Sovereign wealth-backed giga-projects threaten margin compression in the UAE and Saudi Arabia through capacity flooding. Vertical integration into modular shelter manufacturing reduces dependency on scarce technical labor pools. For New Entrants and Emerging Players: Mid-market eco-lodge development in Namibia's community-governed dune systems represents the most penetrable entry point, bypassing capital-intensive reverse-osmosis requirements of Arabian Peninsula competitors. Artisan-integrated hospitality in Morocco's ksar towns offers cultural-authenticity positioning without fly-in infrastructure investment. Direct-to-consumer app-based booking platforms bypass wholesale distributor capture in Australian and UK outbound markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital-native operators with proprietary pre-experience platforms and carbon-accounting infrastructure over asset-heavy resort developers. Long-term viability hinges on regulatory compliance automation rather than fixed-base capacity expansion. The signal to watch is EU Green Deal Scope 3 documentation requirements hardening from voluntary to mandatory across German and French operator procurement.| Strategic Initiative | Industry Significance |
|---|---|
| GSTC Certification Procurement | EU Green Deal carbon-border adjustments filter supplier selection toward certified operators in German and French markets. |
| Exclusive Territory Access Negotiation | Morocco's protected area designations under its environmental ministry enable sustainable Saharan corridor control. |
| Digital Pre-Experience Platform Deployment | Virtual visualization technology compresses booking cycles for high-net-worth fly-in camp commitments. |
| Community-Based Partnership Structuring | Local governance leverage in Namibia and North Africa secures low-impact cultural circuit territory rights. |
| Renewable-Energy Infrastructure Integration | UAE Environment Agency mandates reshape capital planning for new desert concessions in Abu Dhabi. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of tourism ministry filings, GSTC certification databases, and sovereign wealth investment disclosures. Primary interviews incorporated desert lodge operators, sustainability certification auditors, European tour operator procurement directors, and renewable-energy infrastructure contractors. Secondary validation drew from UAE Environment Agency concession records, Morocco's Ministry of Tourism protected area designations, and EU Green Deal implementation guidance. Bottom-up property-level capacity data triangulated against top-down sovereign wealth deployment tracking.
Forecast inputs incorporate tourism type segmentation, accommodation category engineering requirements, and customer segment booking channel preferences across the projection horizon. Modeled dimensions span adventure-luxury-eco-cultural-wellness tourism types, eco lodge-resort-camp-hotel-homestay accommodation tiers, and couples-families-solo-groups-retiree customer profiles. CAGRs derived from capacity addition pipelines, regulatory mandate phase-in schedules, and aviation emission documentation adoption curves. Carbon-border adjustment enforcement timelines and fly-in infrastructure permit approvals served as industry-specific forecast sensitivity inputs.
Practitioners should monitor EU Green Deal Scope 3 hardening timelines, Saudi Red Sea Development Company permit integration pace, and Namibia community governance structure formalization for early signals of forecast revision. Operating assumptions reflect documented regulatory trajectories and disclosed sovereign wealth deployment commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Thailand Sustainable Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
Europe Theme Park Market
Destination Management and Attractions
North America Amusement Parks Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
India MICE Tourism Market