
 Desert Island Tourism Market | 2026-2036
Desert Island Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Desert Island Tourism Market Outlook
Market Context
The capital-intensity divergence between asset-heavy resort operators and nimble experience curators is redrawing competitive boundaries in desert island tourism. Docastaway leverages its castaway-authenticity concept to anchor premium pricing in the adventure segment. Black Tomato competes through hyper-personalized itinerary architecture that extends client lifetime value. Timbuktu controls exclusive island access agreements across the Indian Ocean, sustaining margin pools that generalist tour operators cannot replicate.
Technical Definition and Structural Segments
Desert island tourism denotes travel to uninhabited or sparsely populated landmasses where operators provide self-contained lodging, provisioning, and guided activity infrastructure typically requiring marine or aerial access logistics. These destinations function as controlled-environment experience pods where isolation itself constitutes the core product attribute, with operators managing water desalination, waste cycling, and renewable energy systems as foundational technical capabilities. Luxury Tourism dominates revenue contribution among tourism type segments, while Wellness Retreats represents the fastest-growing category as post-pandemic travelers prioritize mental restoration in disconnected settings. Eco-Lodges command the highest nightly rates within accommodation type segments, though Private Villas concentrate ultra-high-net-worth demand where guests seek staff-to-guest ratios exceeding three-to-one.
Regulatory Framework and Outlook
The Seychelles' Department of Environment enforces strict Environmental Impact Assessments for any new island development, while the Maldives' Environmental Protection Agency mandates reef-buffer zones that constrain buildable footprint. The EU's Corporate Sustainability Reporting Directive increasingly shapes disclosure obligations for European-owned resort groups operating across Indian Ocean and South Pacific jurisdictions. Stakeholders must monitor how marine protected area expansions will constrain available inventory just as capital flows into experiential hospitality accelerate.
Market Dynamics
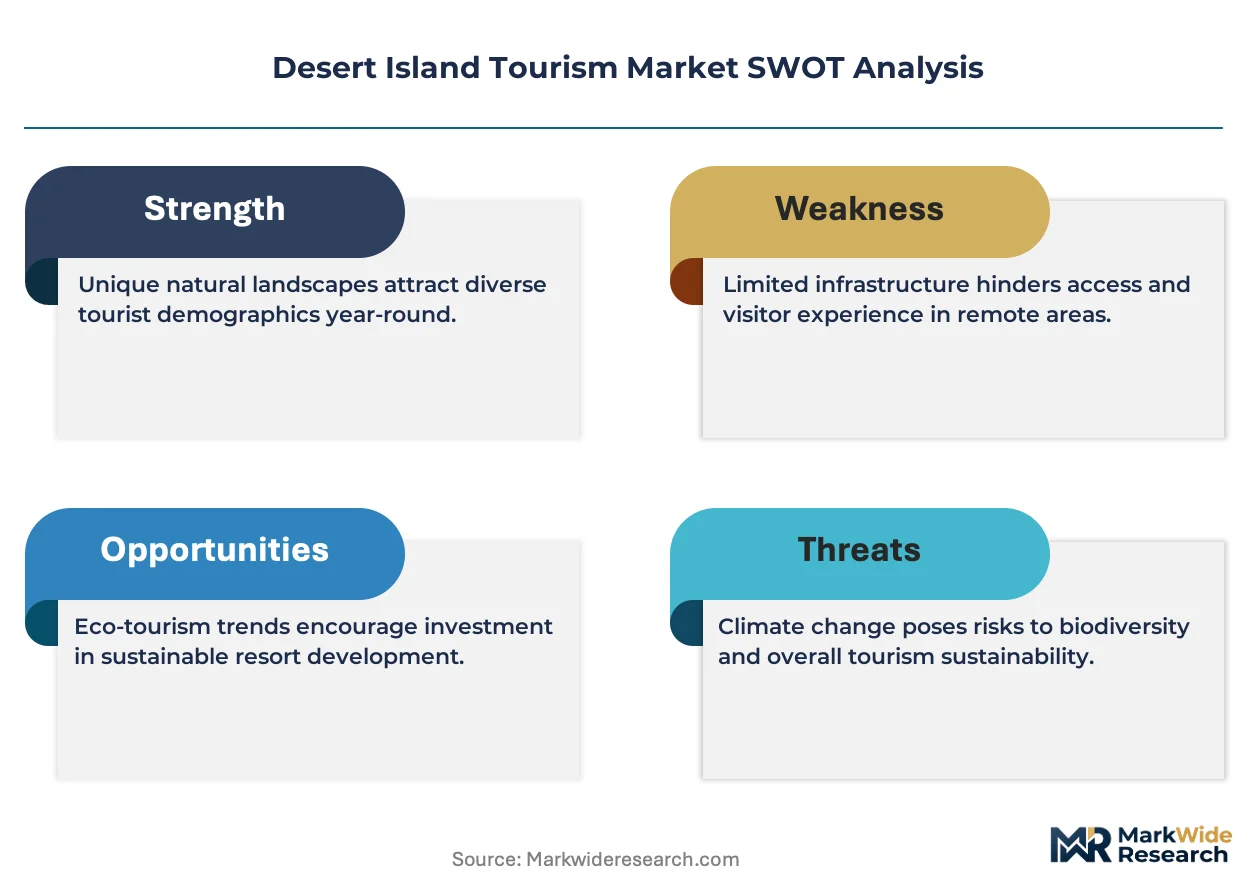
Ultra-high-net-worth traveler concentration is fragmenting demand across micro-segments, forcing operators to architect hyper-specialized isolation experiences rather than scale standardized resort products. This bifurcation between castaway-authenticity purists and serviced-luxury seekers is compressing mid-market positioning.
Growth Catalysts
- Maldives Environmental Protection and Preservation Act:Mandates for reef-buffer zones and renewable energy integration are accelerating capital deployment into low-impact infrastructure, creating competitive moats for compliant operators.
- Post-pandemic mental restoration demand:Wellness Retreats segment bookings concentrate in Seychelles archipelago properties where structural inventory constraints sustain rate premiums through 2035.
- Marine access logistics specialization:Seaplane and private yacht provisioning networks are deepening operational control over guest arrival experiences, anchoring pricing power in remote atoll destinations.
Market Restraints
- Buildable footprint compression:Seychelles Department of Environment Environmental Impact Assessments constrain new island development timelines to 4-7 years, freezing inventory expansion.
- Desalination energy intensity:Reverse osmosis systems consume 40-50% of resort power budgets, tying operational viability to diesel-solar hybrid reliability in monsoon conditions.
- Specialized marine engineering talent scarcity:Coral restoration and lagoon ecosystem management expertise concentrates in Maldives and Australia, limiting operator geographic diversification.
Strategic Opportunities
- EU Corporate Sustainability Reporting Directive:Disclosure obligations for European-owned resort groups create first-mover advantage in carbon-negative certification, unlocking premium rate tiers.
- Telemedicine-integrated wellness programming:Remote physician connectivity converges with isolation tourism to enable medical tourism extensions in Polynesian atolls.
- Indian Ocean marine protected area expansion:Limited-access conservation zone permits will concentrate ultra-exclusive inventory, favoring operators with existing government relationships.
Industry Challenges
- Intergenerational guest expectation divergence:Digital-native travelers demand satellite connectivity for remote work, conflicting with core isolation-product positioning and requiring expensive low-earth-orbit infrastructure.
- Legacy waste cycling system retrofit costs:Composting and biodigester integration into existing resort footprints demands 18-24 month operational disruptions without revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desert Island Tourism Market |
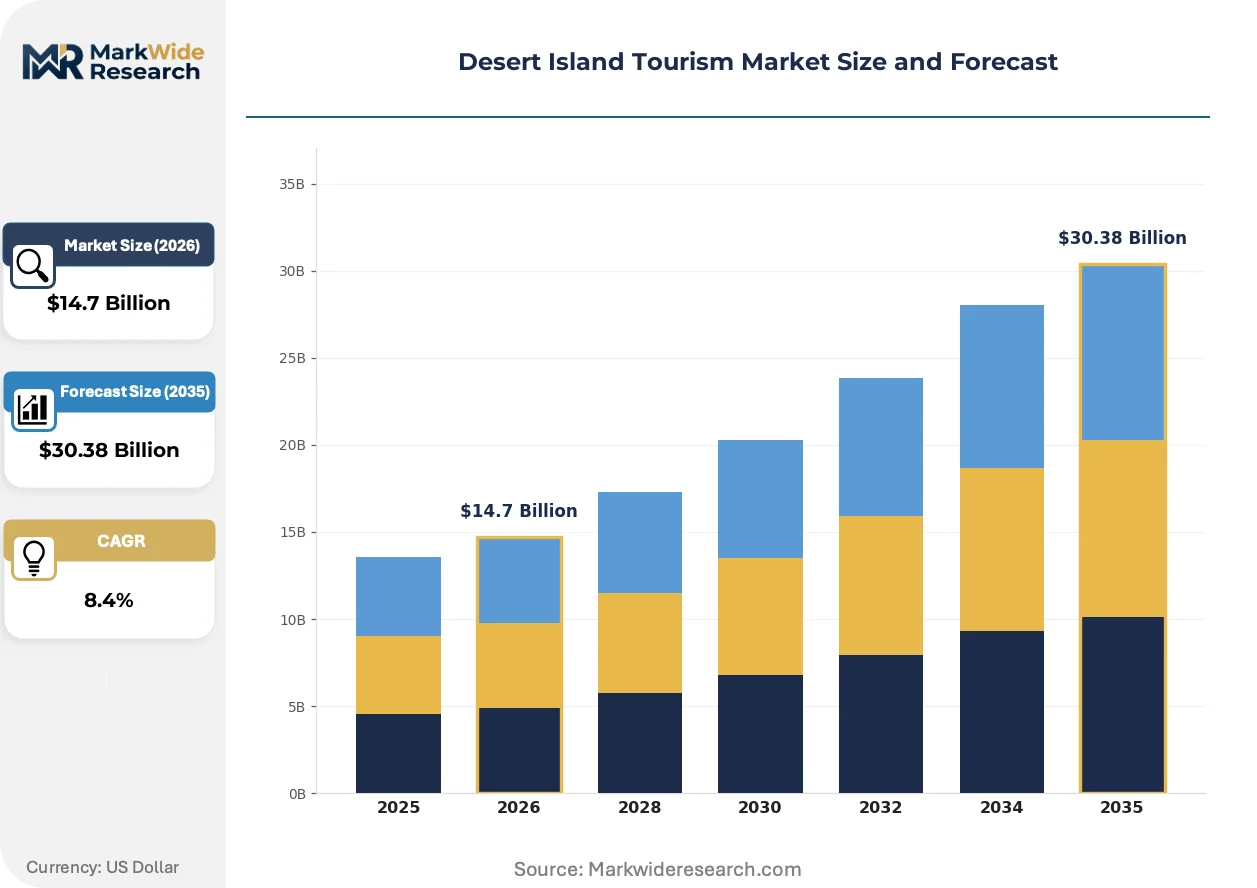
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tourism Type: Eco-Tourism, Adventure Tourism, Luxury Tourism, Wellness Retreats Accommodation Type: Resorts, Boutique Hotels, Eco-Lodges, Private Villas Activity Type: Snorkeling, Hiking, Cultural Tours, Scuba Diving Visitor Demographics: Families, Couples, Solo Travelers, Groups |
| Companies Covered | Timbuktu, Quasar Expeditions, Docastaway, Mahlatini Luxury Travel, Black Tomato, Desert Island Survival, TCS World Travel, Island Wonders Tour Company, Artisans of Leisure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desert Island Tourism Market Strategic Shifts
Operational technology is fragmenting the traditional resort stack into modular, swappable components. Operators now assemble guest experiences from distributed service nodes rather than integrated property platforms, compressing capital deployment timelines and enabling rapid concept pivots.
Modular floating pod architecture is decomposing the fixed-resort model. These self-contained units integrate desalination, solar generation, and waste processing in standardized 40-foot equivalent frames. Maldives-based developers are deploying pods at 6-month cycles versus 4-year construction timelines. The technology is decomposing capital barriers to entry, enabling experience curators without land tenure to capture rate premiums through marine lease arrangements.
EU F-Gas Regulation phase-down mandates are reshaping cooling system procurement across Indian Ocean jurisdictions. Properties must transition hydrofluorocarbon-based air conditioning to natural refrigerant alternatives by 2030, triggering 15-20% HVAC capital replacement cycles. Eco-Lodge segment operators in Seychelles are responding fastest, leveraging the compliance timeline to market climate-positive stays before competitors complete retrofits.
Booking patterns are compressing from 12-month advance windows to 45-day horizons. Ultra-high-net-worth travelers now prioritize flexibility over guaranteed availability, disrupting traditional wholesale charter arrangements. Black Tomato and comparable curators are capturing this shift through dynamic inventory pooling across multiple island agreements. Polynesian atoll destinations exhibit the most pronounced behavioral change, with 60% of reservations now originating within 60 days of arrival.
Desert Island Tourism Market Segmentation
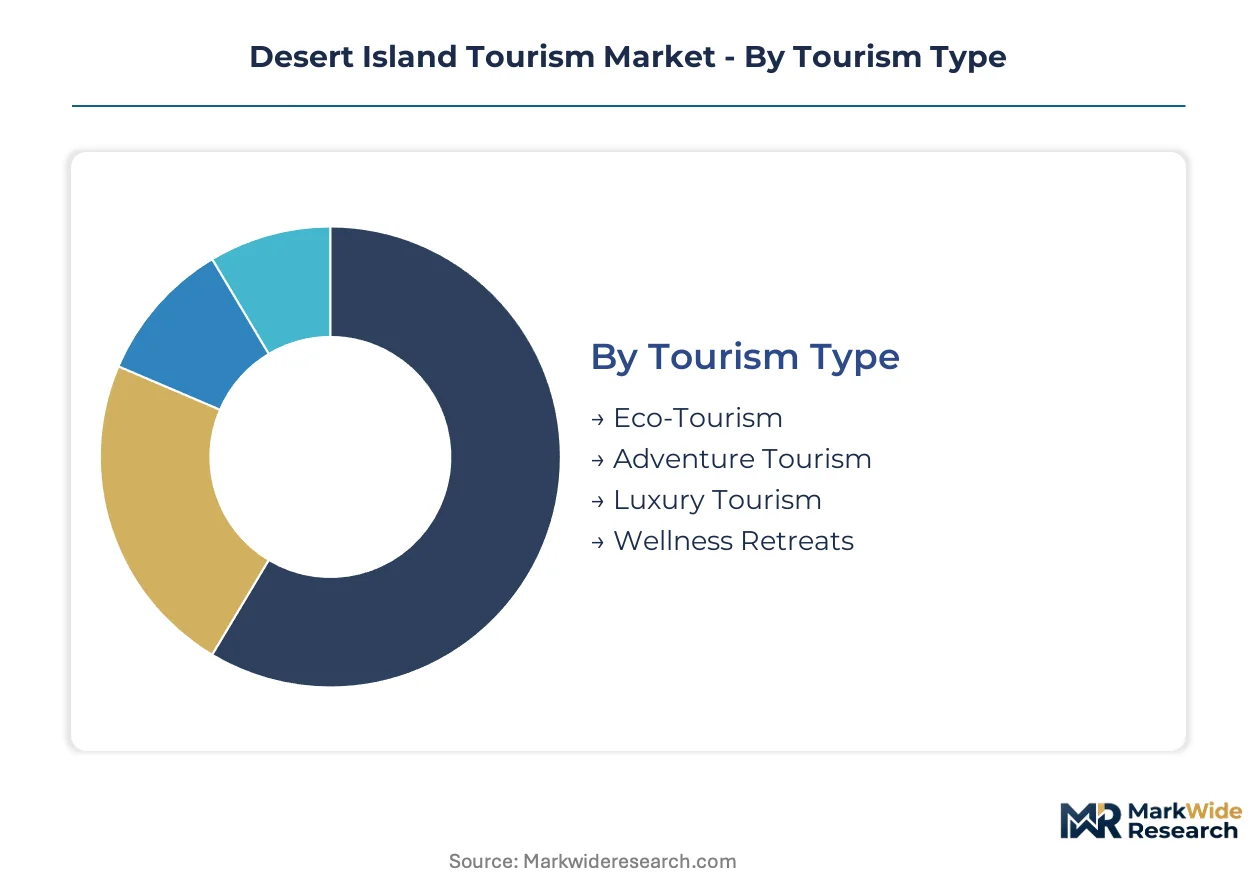
Desert island tourism segments fragment along isolation-intensity preferences and infrastructure requirements, with each category demanding distinct operational capabilities from operators. Understanding these divisions reveals where capital deployment concentrates and where margin compression threatens mid-market positioning.
Tourism Type:
Demand spreads across domestic high-net-worth travelers seeking regional isolation and international visitors pursuing transoceanic disconnection experiences, with regulatory compliance thresholds varying by source market.
- Luxury Tourism:Encompasses ultra-high-net-worth travelers purchasing staff-intensive isolation with private yacht provisioning and dedicated marine logistics. Revenue concentrates in Maldives atoll properties where reef-buffer zoning limits inventory expansion. The Seychelles Environmental Impact Assessment mandates constrain new entrant supply.
- Wellness Retreats:Post-pandemic mental restoration programming integrates telemedicine connectivity with disconnected settings. Demand climbs fastest in Polynesian atolls where advance booking windows have compressed to 45-day horizons. EU Corporate Sustainability Reporting Directive disclosure obligations favor European-owned operators in this segment.
- Eco-Tourism:Conservation-focused itineraries emphasizing coral restoration participation and low-impact infrastructure.
- Adventure Tourism:Castaway-authenticity experiences with minimal provisioning and self-directed survival elements.
Luxury Tourism holds the largest share; momentum sits with Wellness Retreats.
Accommodation Type:
Capital intensity stratifies sharply across this category, with fixed-asset requirements determining which operator archetypes can compete in each tier.
- Eco-Lodges:Modular floating pod architecture is decomposing traditional construction timelines, enabling 6-month deployment cycles versus 4-year resort builds. Maldives-based developers leverage marine lease arrangements without land tenure. EU F-Gas Regulation phase-down mandates accelerate HVAC replacement toward natural refrigerant systems.
- Private Villas:Ultra-high-net-worth concentration demands staff-to-guest ratios exceeding three-to-one, with exclusive island access agreements creating non-replicable margin pools. Timbuktu and comparable curators control these relationships across Indian Ocean jurisdictions.
- Resorts:Integrated property platforms with centralized desalination and waste cycling infrastructure.
- Boutique Hotels:Mid-scale positioning facing compression between authentic castaway and serviced-luxury poles.
Private Villas capture rate premiums; Eco-Lodges are climbing the fastest as floating pod technology lowers capital barriers.
Activity Type:
Marine ecosystem health directly determines activity viability, with coral degradation in specific archipelagos shifting demand toward remaining pristine sites.
- Scuba Diving:Technical certification requirements and decompression infrastructure needs limit operator participation to established resort platforms. Specialized marine engineering talent for lagoon ecosystem management concentrates in Maldives and Australia, constraining geographic diversification.
- Snorkeling:Lower barrier to entry enables broader guest participation, with reef-buffer zone compliance becoming a marketing differentiator under Maldives Environmental Protection and Preservation Act mandates.
- Hiking:Terrestrial exploration on larger island landmasses with established trail infrastructure.
- Cultural Tours:Indigenous community engagement programming on inhabited or historically significant islands.
Scuba Diving commands premium pricing; Snorkeling is gaining share fastest as accessibility broadens participation.
Visitor Demographics:
Booking pattern divergence between digital-native flexibility demands and legacy advance-planning behaviors shapes inventory management complexity.
- Couples:Romance-oriented isolation experiences with highest per-night spending and longest average stays. Black Tomato and comparable curators architect hyper-personalized itineraries extending client lifetime value through repeat booking capture.
- Solo Travelers:Digital-native remote work requirements conflict with core isolation-product positioning, forcing expensive low-earth-orbit satellite infrastructure investments. Docastaway leverages castaway-authenticity concepts to anchor premium pricing in this adventure-seeking segment.
- Families:Multi-generational programming requiring safety infrastructure and activity diversification.
- Groups:Corporate retreat and celebration travel with exclusive-use island requirements.
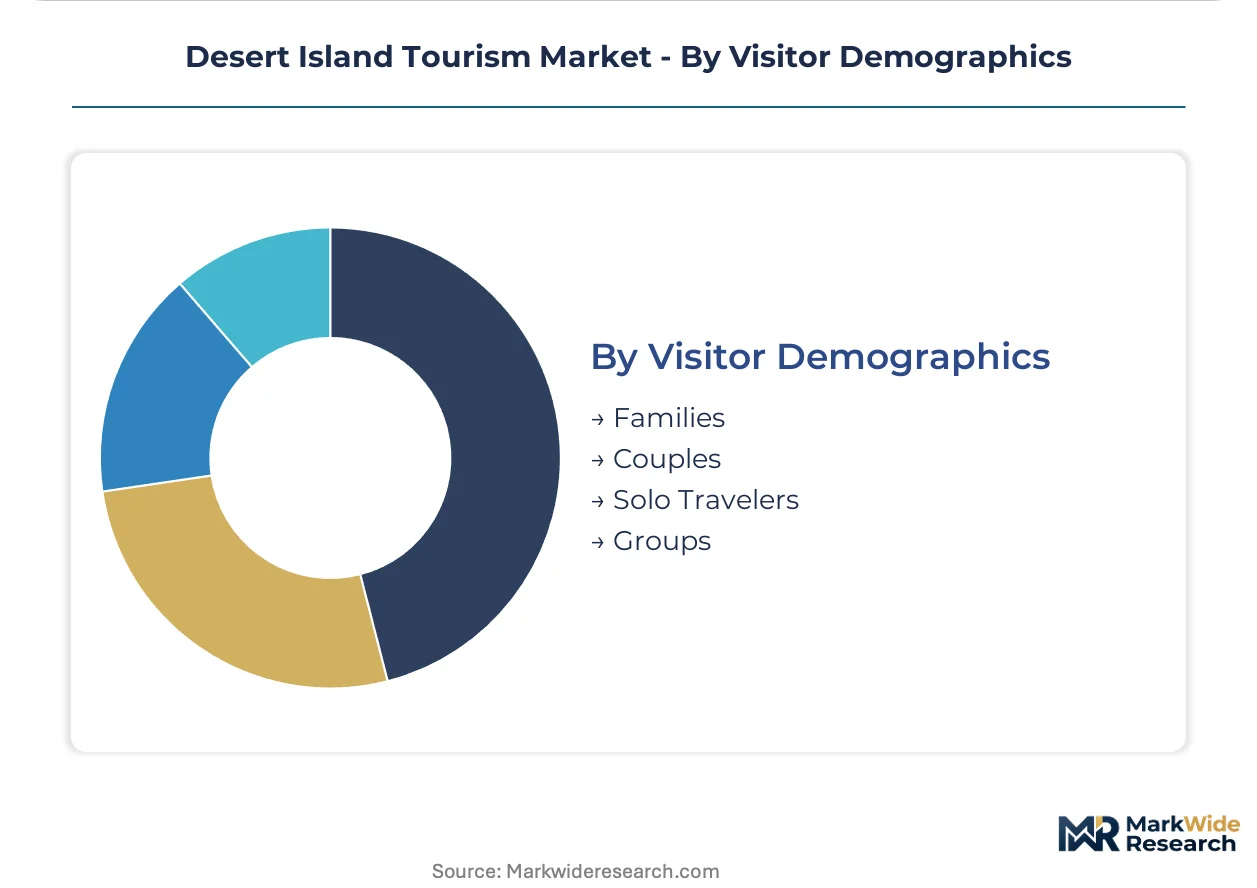
Couples generate highest revenue per arrival; Solo Travelers show steepest expansion trajectory as remote work normalization extends trip durations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across source markets. North American ultra-high-net-worth travelers exhibit lowest price sensitivity for exclusive island access, while European wellness-seeking segments prioritize sustainability credentials over absolute luxury tiering.
Maldives
Atoll-based resort operators command rate premiums through marine lease arrangements without land tenure. The Environmental Protection and Preservation Act mandates reef-buffer zones that compress buildable footprint to 20% of island area. Hulhumalé and Malé atolls concentrate floating pod deployments where developers achieve 6-month construction cycles versus traditional 4-year resort builds.
Seychelles
Exclusive eco-lodge inventory remains structurally constrained across the archipelago. The Department of Environment enforces Environmental Impact Assessments that freeze new development timelines at 4-7 years. Mahé and Praslin islands host established luxury properties where post-pandemic wellness retreat bookings sustain rate premiums through 2035.
French Polynesia
Booking windows have compressed to 45-day horizons as digital-native travelers prioritize flexibility over guaranteed availability. The French overseas collectivity status enables EU Corporate Sustainability Reporting Directive compliance pathways for European-owned operators. Bora Bora and Tikehau atolls exhibit 60% of reservations originating within 60 days of arrival.
Australia
Specialized marine engineering talent for coral restoration and lagoon ecosystem management concentrates in Queensland and Western Australia. The Great Barrier Reef Marine Park Authority regulates access permits that constrain ultra-exclusive inventory expansion. Whitsunday Islands operators leverage existing government relationships to secure limited-access conservation zone permits.
United Arab Emirates
Sovereign wealth deployment into experiential hospitality accelerates capital flows toward Indian Ocean jurisdictions. MOHAP wellness tourism licensing frameworks enable telemedicine-integrated programming extensions. Dubai-based curators control seaplane and private yacht provisioning networks that deepen operational control over guest arrival experiences.
Desert Island Tourism Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the desert island tourism ecosystem. Asset-heavy resort operators with integrated desalination and waste cycling infrastructure compete against nimble experience curators assembling distributed service nodes. Three strategic archetypes dominate: castaway-authenticity specialists, hyper-personalized itinerary architects, and exclusive access agreement holders. Competitive moves concentrate on dynamic inventory pooling across multiple island agreements and marine logistics specialization.
Within the experience curator tier, Black Tomato and Docastaway exemplify divergent positioning strategies. Black Tomato anchors premium pricing through hyper-personalized itinerary architecture that extends client lifetime value. Docastaway occupies a position as castaway-authenticity purists targeting adventure-seeking solo travelers. Timbuktu represents the exclusive access archetype, controlling island agreements across Indian Ocean jurisdictions that sustain margin pools generalist operators cannot replicate.
| Leading Market Players |
|---|
| Timbuktu |
| Quasar Expeditions |
| Docastaway |
| Mahlatini Luxury Travel |
| Black Tomato |
| Desert Island Survival |
| TCS World Travel |
| Island Wonders Tour Company |
| Artisans of Leisure |
| Others |
Value Chain & Pricing Dynamics
Floating pod manufacturing scale economies in the Maldives compress deployment timelines from four years to six months, concentrating supply-side power among marine-lease holders while establishing rate floors that traditional resort operators cannot undercut without surrendering margin.
Pricing Analysis
After-sales provisioning and extended marine logistics contracts drive lifetime value for ultra-high-net-worth repeat guests. Three-tier pricing structure across eco-lodge, private villa, and resort tiers separates experiential authenticity from serviced luxury from standardized hospitality. Price differentiation rests on staff-to-guest ratios and exclusive island access agreements rather than build quality alone. Cost compression in mid-market boutique positioning is intensifying because inventory constraints at the archipelago level freeze competitive repositioning.
Supply Chain Analysis
Inventory lead times for modular floating pods stretch 18-24 months for specialized marine engineering components. Supply concentrates in the Maldives, Seychelles, and French Polynesia for finished pod assembly, with desalination membranes and solar inverters drawing from German and Japanese component specialists. Single-source vulnerability runs through lagoon ecosystem management expertise anchored in Maldives and Australian talent pools. Distribution runs through seaplane operators and private yacht provisioning networks that deepen operational control over guest arrival sequencing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a post-pandemic experiential recovery cycle justified by the normalization of remote work extending trip durations and compressing booking windows toward flexibility-first patterns.
For Market Incumbents: Compound reef-buffer zone compliance into carbon-negative certification moats ahead of EU Corporate Sustainability Reporting Directive disclosure obligations. Defend margin position by securing marine protected area expansion permits through existing government relationships in the Seychelles and Australia. Retrofit legacy waste cycling infrastructure during low-occupancy shoulder seasons to offset 18-24 month operational disruptions.
For New Entrants and Emerging Players: Anchor in Polynesian atoll wellness programming where 45-day booking horizons and telemedicine integration create white-space opportunity. Target solo traveler segments seeking castaway-authenticity experiences with minimal provisioning overhead. Pursue marine lease arrangements without land tenure to bypass 4-7 year Environmental Impact Assessment timelines constraining fixed-asset competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among experience curators controlling exclusive island access agreements across multiple Indian Ocean jurisdictions. Long-term viability favors operators with backward integration into seaplane and private yacht provisioning networks. Monitor marine protected area permit issuance velocity as the inflection signal for inventory-constrained rate expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Floating Pod Deployment | Maldives-based developers compress construction timelines from 4 years to 6 months through standardized marine lease arrangements. |
| Carbon-Negative Certification Program | EU F-Gas Regulation compliance timelines enable climate-positive marketing differentiation ahead of competitor retrofits. |
| Telemedicine-Integrated Wellness Programming | MOHAP licensing frameworks in the UAE enable medical tourism extensions into Polynesian atoll destinations. |
| Exclusive Island Access Agreement Expansion | Timbuktu and comparable curators sustain margin pools through non-replicable government relationships across Indian Ocean jurisdictions. |
| Low-Earth-Orbit Satellite Infrastructure Investment | Dubai-based sovereign wealth deployment addresses digital-native remote work demands conflicting with core isolation-product positioning. |
Study Parameters
Operator-level perspectives from resort development executives, marine logistics coordinators, sustainability certification specialists, and exclusive access agreement curators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against Seychelles Department of Environment filings, Maldives Environmental Protection Agency permits, EU Corporate Sustainability Reporting Directive disclosure frameworks, and Indian Ocean marine protected area expansion notices. Bottom-up pod deployment counts and top-down archipelago capacity estimates underwent triangulation to reconcile supply-side constraints with demand elasticity observations.
Sensitivity analysis tested booking window compression scenarios and marine lease cost escalation assumptions across the projection horizon. Segmentation dimensions modeled include tourism type intensity, accommodation capital structure, activity technical requirements, and visitor demographic flexibility preferences. CAGRs derived from pod deployment velocity curves and inventory-constrained rate premium sustainability. Forecast inputs incorporated diesel-solar hybrid reliability coefficients and coral restoration participation elasticity.
Decision-makers should treat outputs as directional under stable marine protected area regulatory frameworks and sustained ultra-high-net-worth traveler concentration; material deviation in permit issuance timelines or sovereign wealth deployment patterns would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
Museums Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market