
 Morocco Tourism and Hotel Market | 2026-2036
Morocco Tourism and Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Tourism and Hotel Market Foresight
The gap between luxury riad conversions in Marrakech's medina and standardized economy hotels near industrial zones is realigning investment flows across Moroccan hospitality. Accor SA leverages its Sofitel and ibis network to anchor presence in both premium and mid-market tiers. Marriott International Inc. competes through concentrated resort development along the Atlantic coast. Iberostar Group specializes in all-inclusive beach properties that dominate the Agadir-Taghazout corridor.
Morocco tourism and hotel services encompass accommodation, food and beverage provisioning, travel transport logistics, and entertainment programming delivered across physical and digital infrastructure with occupancy cycles tied to seasonal European travel patterns. The sector operates through properties ranging from traditional courtyard riads with artisanal restoration specifications to modern resorts meeting international star-rating criteria for pool, spa, and conference facilities. Accommodation type segmentation shows hotels and luxury resorts capturing the dominant revenue share while riads represent the fastest-growing margin pool due to cultural authenticity premiums. Customer type dynamics reveal leisure travelers sustaining volume leadership as business travel segments recover through Casablanca's financial district and Rabat's government conference demand.
Morocco's Ministry of Tourism coordinates with the country's national tourism regulator to enforce Green Key environmental standards and building heritage codes that shape property renovation timelines and new construction permits. The Ministry of Interior oversees safety inspections and licensing requirements that determine market access for international operators seeking establishment rights. Stakeholders must monitor evolving coastal development restrictions and medina preservation mandates that will determine viable expansion corridors.
Market Dynamics
Online booking platforms are fragmenting traditional distribution channels across Moroccan hospitality, forcing property operators to absorb commission structures while rebuilding direct guest relationships through loyalty programs and experiential packaging.
Growth Catalysts
- Green Key Certification:Morocco's Ministry of Tourism mandates environmental standards that unlock preferential financing for compliant properties. International leisure travelers now filter searches by sustainability credentials.
- Atlantic Coastal Development:Agadir-Taghazout corridor infrastructure investments attract resort construction with streamlined permitting. Premium beachfront land availability concentrates developer attention.
- Riad Restoration Incentives:Heritage building codes in Marrakech's medina offer tax abatements for artisanal renovation projects. Cultural authenticity premiums command rate premiums above standardized inventory.
Market Restraints
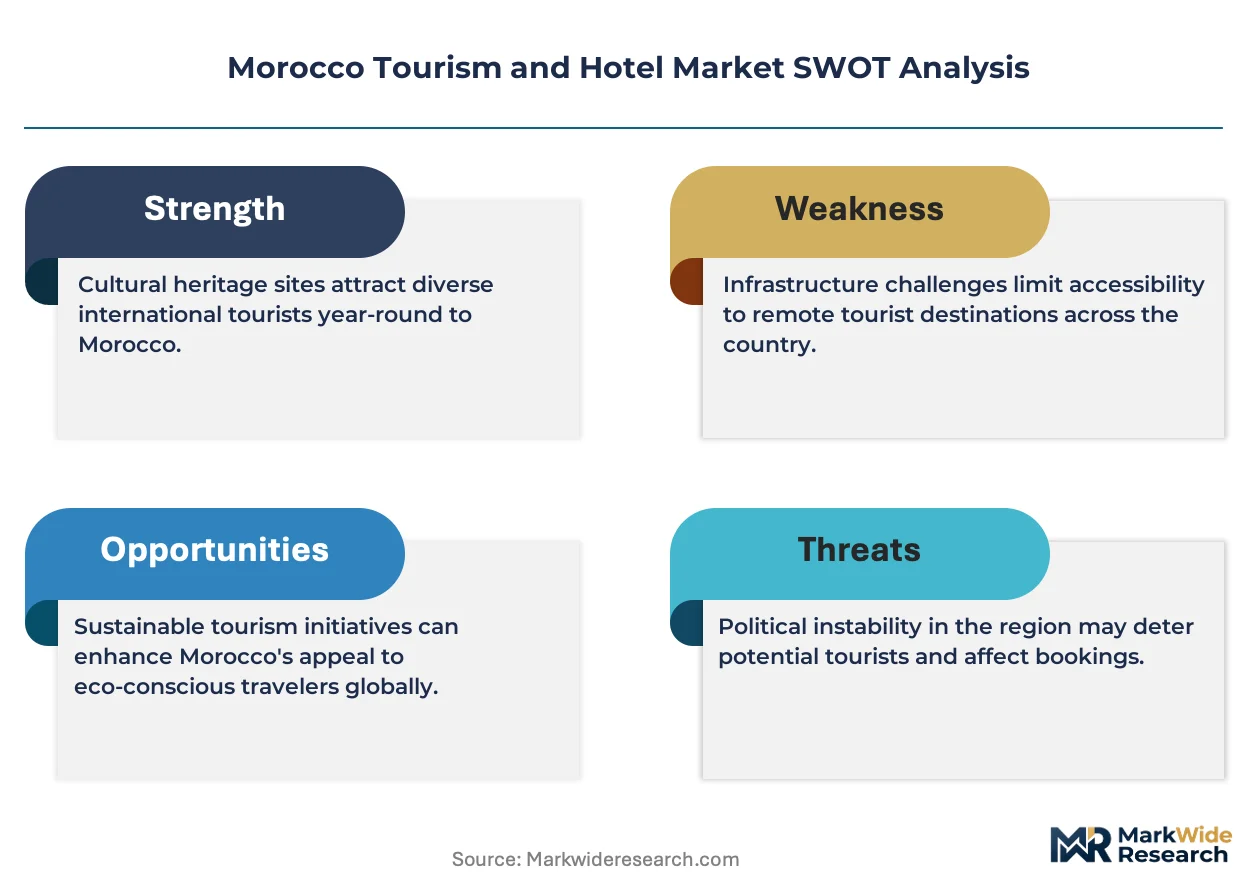
- Seasonal Demand Concentration:European winter sun patterns compress occupancy cycles to November-March peak months. Fixed cost structures strain cash flows during extended shoulder seasons.
- Imported Construction Materials:Steel and glass facade systems face tariff volatility and currency fluctuation exposure. Supply lead times extend project completion horizons.
- Medina Preservation Restrictions:Heritage codes limit vertical expansion and modern amenity installation in protected districts. Floor area ratios cap revenue per available room potential.
Strategic Opportunities
- Atlas Mountain Eco-Lodges:Underdeveloped highland corridors between Marrakech and Imlil present adventure tourism positioning. Trekking infrastructure gaps create first-mover advantages.
- Direct Distribution Technology:Property management system integrations enable commission-free booking engines. Guest data ownership supports personalized pre-arrival upselling.
- Conference Tourism Diversification:Rabat government sector demand stabilizes weekday occupancy. Hybrid event capabilities attract association meetings from Francophone Africa.
Industry Challenges
- Artisanal Craftsmanship Shortage:Zellige tile and tadelakt plaster specialists face generational succession gaps. Restoration timelines extend as qualified labor pools contract.
- Green Key Compliance Documentation:Certification audits require 18-24 month preparation cycles. Properties must demonstrate water recycling and renewable energy thresholds.
- Legacy Property System Integration:Riad inventory management platforms lack API connectivity with global distribution systems. Manual rate parity maintenance consumes revenue management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Tourism and Hotel Market |
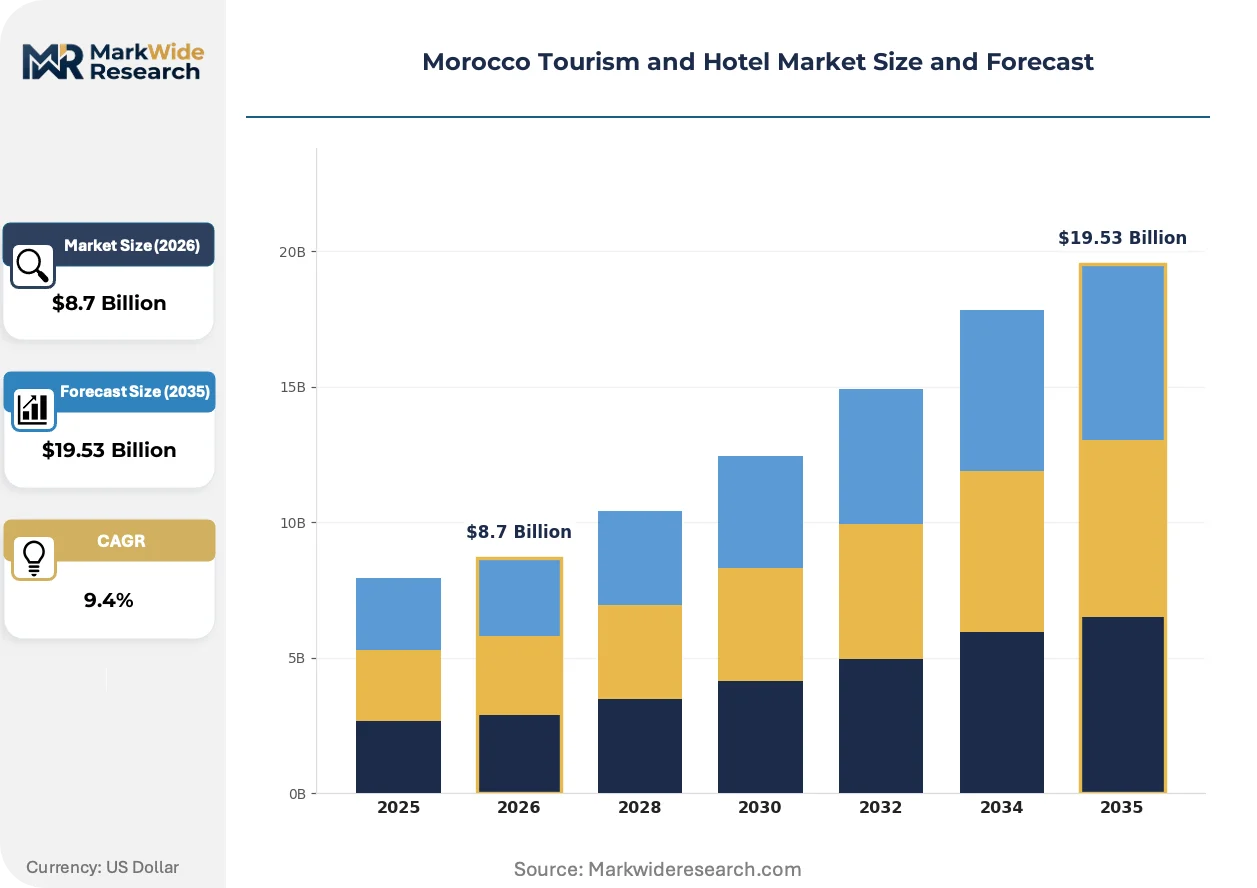
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Food & Beverage, Travel & Transport, Entertainment Customer Type: Leisure Travelers, Business Travelers, Group Tours, Solo Travelers Accommodation Type: Hotels, Riads, Hostels, Luxury Resorts Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Tour Operators |
| Companies Covered | Accor SA, Marriott International Inc., Royal Air Maroc, Hilton Worldwide Holdings, TUI Group, Iberostar Group, Four Seasons Hotels Ltd., Barceló Hotel Group, Booking Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Tourism and Hotel Market Shifts & Advancements
Digital infrastructure investments are compressing booking friction while sustainability mandates reshape physical asset specifications across Moroccan hospitality portfolios.
Smart room technology is expanding into riad and resort properties through mobile key entry and in-room tablet controls. International leisure travelers from France and Spain expect seamless digital check-in experiences comparable to European chain standards. Property operators are retrofitting legacy inventory with IoT-enabled climate and lighting systems to capture direct booking preference shifts.
Morocco's Ministry of Tourism coordinates with the national tourism regulator to enforce Green Key environmental standards and building heritage codes. New construction permits now require renewable energy integration and wastewater recycling specifications. Coastal resort developments in Agadir face additional coastal erosion impact assessments before approval.
Experiential packaging is displacing room-only transactions as primary revenue drivers. Property operators bundle cooking classes, hammam rituals, and guided medina walks into rate structures. Marrakech riad properties lead this shift, leveraging cultural authenticity premiums to reduce commission dependence on online travel agencies.
Morocco Tourism and Hotel Market Segmentation
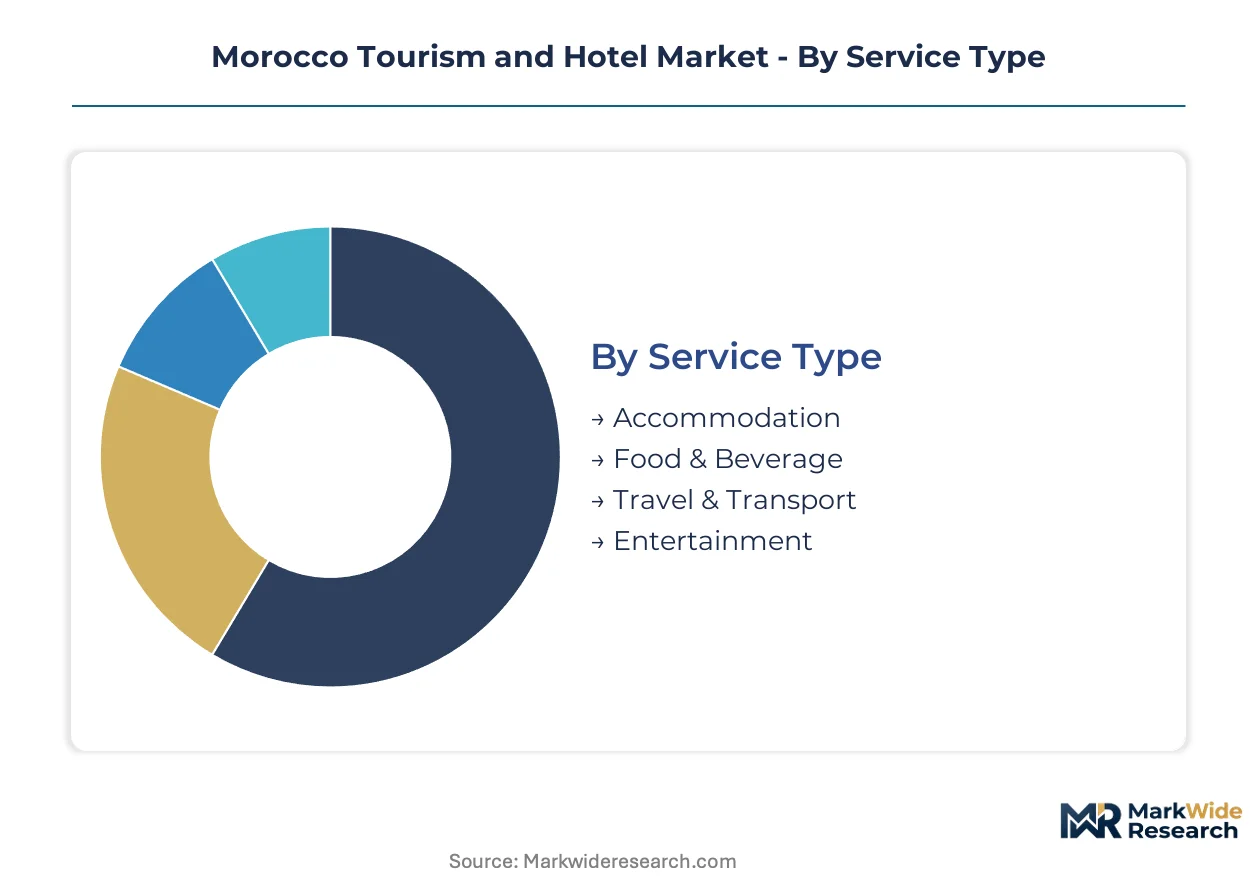
Morocco's hospitality segmentation reveals distinct operational models between mass-market infrastructure and artisanal heritage properties. Each dimension shapes capital deployment, margin structure, and regulatory exposure differently across the value chain.
Service Type:
The customization-vs-standardization spectrum runs from bespoke experiential programming to commoditized logistics services across Moroccan hospitality portfolios.
- Accommodation:Physical lodging assets span restored medina riads with tadelakt plaster specifications to Atlantic coast resorts meeting international star-rating criteria for pool and spa amenities. Properties in Marrakech's medina command authenticity premiums through artisanal restoration, while Agadir beachfront inventory competes on amenity density and conference capacity.
- Food & Beverage:Culinary provisioning ranges from standardized buffet operations at all-inclusive resorts to curated tasting menus featuring regional tagine and couscous preparations. Riads differentiate through intimate courtyard dining with family-style service, whereas luxury resorts invest in multiple restaurant concepts to extend guest capture rates.
- Travel & Transport:Ground logistics encompass airport transfers, intercity coach networks, and private vehicle arrangements connecting Casablanca, Marrakech, and coastal corridors. Operators bundle these services into package rates to reduce guest friction and improve margin predictability.
- Entertainment:Programming includes guided medina walks, hammam rituals, cooking classes, and Atlas Mountain trekking excursions. Marrakech properties lead experiential packaging innovation, leveraging cultural access to reduce commission dependence on distribution intermediaries.
Leading the category by volume: Accommodation. Growing fastest: Entertainment.
Customer Type:
Margin concentration shifts with booking lead times and cancellation flexibility across traveler profiles.
- Leisure Travelers:European winter sun demand from France and Spain sustains November-March occupancy peaks. This segment filters searches increasingly by Green Key sustainability credentials, pressuring property operators to certify environmental compliance.
- Business Travelers:Casablanca's financial district and Rabat's government conference centers anchor weekday demand. Corporate rate negotiations compress average daily rates but deliver predictable occupancy outside leisure seasonality.
- Group Tours:Packaged itineraries concentrate volume through established operator relationships, reducing per-acquisition costs for properties. Commission structures typically exceed individual booking margins.
- Solo Travelers:Digital-native travelers from European source markets favor direct booking channels and mobile-first check-in experiences. This segment shows highest sensitivity to online review scores and sustainability certifications.
Volume leadership sits with Leisure Travelers. Steepest expansion trajectory: Solo Travelers.
Accommodation Type:
Heritage preservation mandates create divergent capital intensity and permitting timelines across physical asset categories.
- Hotels:Standardized inventory in urban and industrial zones offers scalable operations with established brand affiliations. Properties near Casablanca's port and manufacturing corridors serve transit and business demand with limited seasonal volatility.
- Riads:Traditional courtyard houses in Marrakech's medina require artisanal renovation using zellige tile and carved plaster specialists. Heritage building codes limit vertical expansion and modern amenity installation, capping revenue per available room potential.
- Hostels:Budget-oriented shared accommodation targets younger European travelers and backpacker segments. Properties cluster near transport hubs and medina peripheries where land costs permit competitive rate positioning.
- Luxury Resorts:Beachfront developments along the Agadir-Taghazout corridor compete on amenity density including spa, golf, and conference facilities. Coastal erosion impact assessments now extend permitting timelines under Ministry of Tourism environmental standards.
Revenue concentration favors Hotels. Climbing the fastest: Riads.
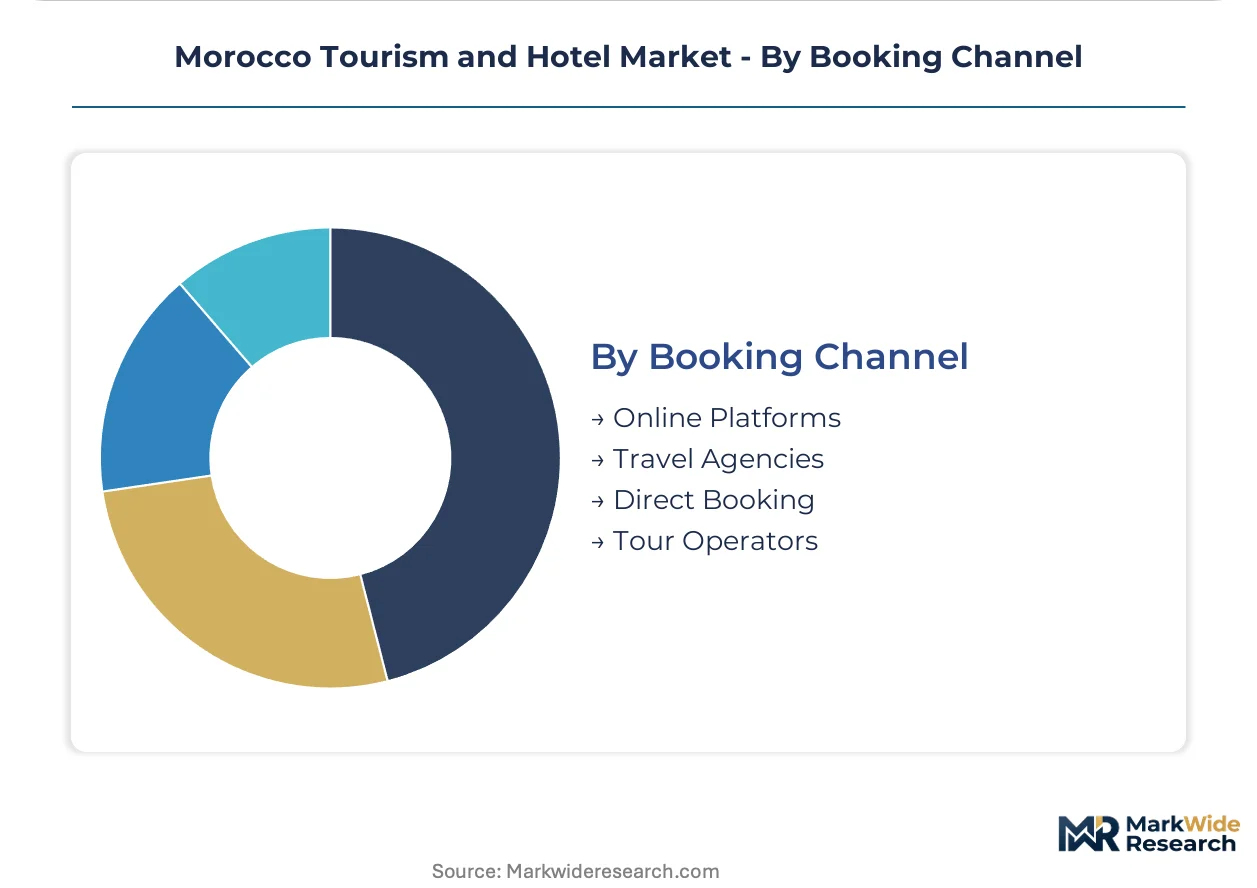
Booking Channel:
Commission absorption pressures and guest data ownership rights determine operator channel strategy.
- Online Platforms:Global distribution systems fragment traditional booking flows, forcing commission structures of fifteen to twenty-five percent on participating properties. Operators counter with loyalty program investments to rebuild direct relationships.
- Travel Agencies:Established networks in European source markets maintain volume for package tour products. Relationships require rate parity guarantees that constrain dynamic pricing flexibility.
- Direct Booking:Property management system integrations enable commission-free reservation engines with guest data ownership. Pre-arrival upselling of experiences and amenities improves net revenue per booking.
- Tour Operators:Wholesale contracting secures block inventory commitments during shoulder seasons. Operators negotiate exclusivity clauses that limit rate transparency to retail channels.
Highest volume flows through Online Platforms. Gaining share fastest: Direct Booking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marrakech's medina district anchors Morocco's hospitality investment flows, with riad conversions and luxury resort development concentrating developer capital across distinct geographic corridors.
Marrakech-Safi Region
European leisure travelers from France and Spain drive November-March occupancy peaks in Marrakech's medina riads and Palmeraie resort zone. Morocco's Ministry of Tourism enforces Green Key certification requirements that shape renovation timelines for heritage properties. The medina's artisanal restoration cluster concentrates zellige tile and tadelakt plaster specialists serving riad conversion projects.
Souss-Massa Region
Atlantic coastal demand centers on Agadir-Taghazout corridor beachfront properties serving winter sun tourism from European source markets. Coastal development restrictions under Ministry of Tourism environmental standards extend permitting timelines for new resort construction. Premium land availability along the Taghazout Bay development zone attracts international resort operators seeking amenity-dense inventory.
Casablanca-Settat Region
Business travel demand from the financial district and port logistics corridor sustains weekday occupancy in standardized hotel inventory. The Ministry of Interior oversees safety inspections and licensing requirements that determine market access for international operators. Industrial zone proximity near Mohammedia and Nouaceur concentrates transit-oriented properties serving manufacturing and shipping sectors.
Rabat-Salé-Kénitra Region
Government conference demand and diplomatic presence stabilize occupancy outside leisure seasonality in the capital corridor. Heritage building codes in Rabat's medina and Kasbah districts limit vertical expansion for boutique properties. The Salé waterfront development zone presents expansion corridors for mid-market hotel capacity serving administrative and institutional travel segments.
Morocco Tourism and Hotel Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the authenticity-amenity spectrum, with riad operators capturing cultural premiums while standardized hotels compete on location efficiency and scale economics. Market structure shows concentration among multinational hospitality groups with established brand affiliations alongside fragmented local riad ownership. Three archetypes dominate: heritage restoration specialists, coastal resort developers, and integrated travel platforms. Competitive moves center on direct distribution technology investments and experiential packaging bundling accommodation with cultural programming.
Within the multinational hospitality tier, Accor SA and Marriott International Inc. occupy positions spanning premium and mid-market segments through distinct property portfolios. Accor SA exemplifies the dual-tier operator archetype with Sofitel and ibis networks anchoring presence across Marrakech and coastal markets. Marriott International Inc. represents the concentrated resort developer model with Atlantic coast properties competing on amenity density. Iberostar Group sits within the specialized all-inclusive segment dominating Agadir-Taghazout corridor beachfront positioning.
| Leading Market Players |
|---|
| Accor SA |
| Marriott International Inc. |
| Royal Air Maroc |
| Hilton Worldwide Holdings |
| TUI Group |
| Iberostar Group |
| Four Seasons Hotels Ltd. |
| Barceló Hotel Group |
| Booking Holdings |
| Others |
Supply & Pricing Matrix
Riad-authenticity premiums versus standardized resort rates create a bifurcation that shapes both revenue management strategies and construction input sourcing across Moroccan hospitality. Properties commanding cultural premiums in Marrakech's medina deploy artisanal labor pools and heritage-certified materials, while Atlantic coast resorts optimize through imported amenity packages and modular construction systems.
Pricing Analysis
Value-based pricing anchored to experiential yield and cultural authenticity premiums dominates rate-setting across riad and resort tiers. Three-tier pricing structure across premium riad conversions, standard branded hotels, and economy transit properties reflects Green Key certification status and amenity density differentiation. Pricing pressure stems from online platform commission absorption, which compresses net revenue per booking for inventory-dependent operators. Leisure travelers from France and Spain show highest price sensitivity during shoulder seasons, while government conference segments in Rabat demonstrate rate inelasticity.
Supply Chain Analysis
Domestic-content mandates under Morocco's Ministry of Tourism heritage codes reshape sourcing toward local zellige tile, tadelakt plaster, and carved cedar specialists for medina restoration projects. Construction inputs draw from Spain, France, and Turkey for steel facade systems, glass curtain walls, and MEP equipment. Raw material dependencies center on imported steel, low-e glazing, and HVAC components. Single-source vulnerability concentrates in artisanal craftsmanship pools facing generational succession gaps. Distribution runs through Casablanca port logistics and overland trucking networks serving Marrakech and Agadir construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's hospitality sector is navigating a technology-transition phase as direct distribution platforms and property management system integrations displace legacy online travel agency dependence. Mobile-first booking engines and guest data ownership capabilities are replacing commission-heavy intermediary relationships.
For Market Incumbents: Hedge against platform commission erosion by accelerating proprietary booking engine deployments with pre-arrival experiential upselling modules. Invest in Green Key certification documentation to capture sustainability-filtered search demand from European leisure travelers. Prioritize loyalty program data architecture that enables personalized rate fencing and direct guest relationship rebuilding.
For New Entrants and Emerging Players: Commission-free direct booking channels present the most penetrable route for riad operators seeking to bypass established online platform gatekeepers. Target underdeveloped Atlas Mountain eco-lodge corridors between Marrakech and Imlil where trekking infrastructure gaps create first-mover positioning. Deploy experiential packaging bundling accommodation with guided treks and Berber cultural programming as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with heritage restoration specialists given Riad-authenticity premiums expanding faster than standardized hotel yield growth. Long-term viability across a multi-year horizon favors operators with captive artisanal labor relationships and direct distribution technology stacks. Monitor Green Key certification completion rates as the signal to watch for portfolio-wide margin expansion inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Distribution Technology Deployment | Property management system integrations enable commission-free booking engines with guest data ownership rights. |
| Green Key Certification Program | Morocco's Ministry of Tourism mandates unlock preferential financing and sustainability-filtered search visibility. |
| Experiential Packaging Bundling | Riad operators combine accommodation with cooking classes and hammam rituals to reduce online travel agency dependence. |
| Artisanal Labor Pool Development | Zellige tile and tadelakt plaster specialist training programs address generational succession gaps in heritage restoration. |
| Atlas Mountain Eco-Lodge Expansion | Underdeveloped highland corridors between Marrakech and Imlil present adventure tourism positioning opportunities. |
Research Methodology
Independent corroboration across property operator interviews, construction contractor assessments, and regulatory filing reviews underwrites the qualitative findings in this study. Primary fieldwork encompassed discussions with riad restoration specialists, resort development executives, Ministry of Tourism licensing officers, and online platform partnership managers. Secondary validation drew from Morocco's national tourism statistics, Green Key certification registries, coastal development permit databases, and European source market travel surveys. Bottom-up property-level capacity modeling and top-down sector expenditure analysis were cross-referenced for triangulation.
Comparable-period anchoring to historical occupancy cycles and construction completion timelines established the forecast window baseline. The analytical framework models segmentation across accommodation type, customer profile, booking channel, and regional corridor throughout the projection horizon. CAGRs were derived from capacity addition pipelines, demand elasticity coefficients, and regulatory timeline assumptions. Industry-specific forecast inputs included European winter sun travel pattern stability and artisanal labor pool expansion constraints.
Inputs from Ministry of Tourism certification registries and coastal development permit databases were available through the study window; gaps in forward-looking riad conversion project pipelines introduce uncertainty bands around heritage inventory growth assumptions. Forecasts reflect documented assumptions regarding Green Key compliance adoption curves and online platform commission structure evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Hotel Furniture and Furnishing Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
United Kingdom HRI Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Germany HRI Market