
 Egypt Faith Based Tourism Market | 2026-2036
Egypt Faith Based Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Faith Based Tourism Market Foresight
A capital-intensity divergence between integrated tour operators and niche pilgrimage specialists is rotating competitive dynamics across Egypt's faith tourism value chain. TUI Group leverages its global distribution network to package multi-site Nile itineraries that bundle flights, ground transport, and guided sacred site visits. Catholic Travel Centre specializes in denomination-specific programming, sustaining margins through curated liturgical experiences at Coptic monasteries and Mount Sinai. Thomas Cook competes on price-accessible charter capacity into Hurghada and Sharm El-Sheikh gateway cities.
Faith based tourism encompasses structured travel to sacred destinations for spiritual fulfillment, religious observance, or denominational education, typically involving guided visits to sites of scriptural significance, participation in ritual ceremonies, and lodging within proximity to worship infrastructure. The activity demands multilingual spiritual guides, halal and kosher meal certification, and prayer facility accessibility as core operational parameters. Pilgrimage travel dominates volume flows, with Sacred Sites capturing the highest per-visitor spend due to premium guide requirements and restricted access protocols at locations like Saint Catherine's Monastery. Group Tours anchors baseline occupancy for Nile cruise vessels and Red Sea resort properties during low-season months.
Egypt's Ministry of Tourism and Antiquities coordinates with the Supreme Council of Antiquities to regulate site access quotas and conservation fees at religious heritage locations, directly constraining daily visitor volumes and shaping operator permit economics. The General Authority for Investment and Free Zones oversees hospitality development incentives in Upper Egypt, influencing where new retreat centers and guesthouse capacity materialize along the pilgrimage corridor. Stakeholders must monitor how antiquities conservation mandates and foreign currency repatriation rules for tourism revenues reshape operational feasibility and partnership structures with local ground handlers.
Market Dynamics
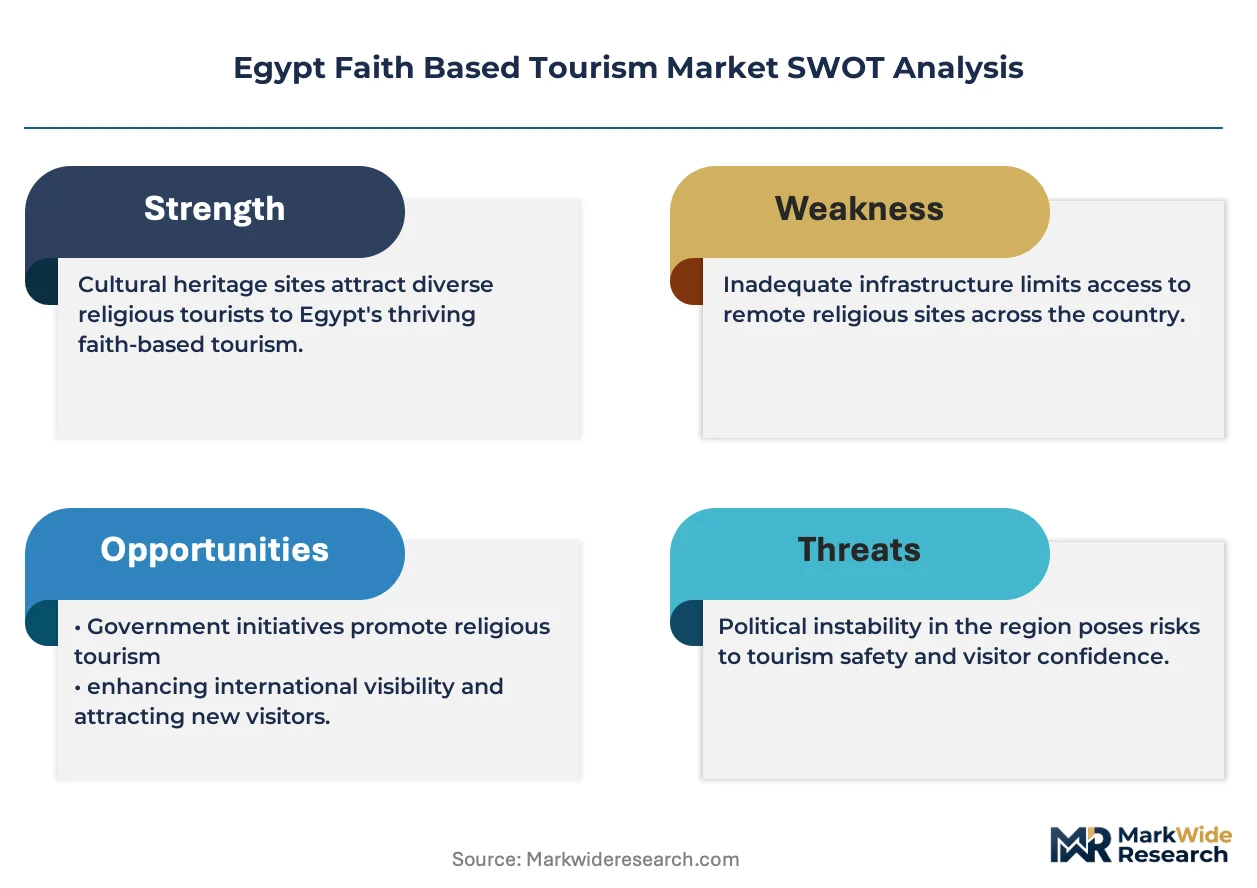
Visa facilitation protocols from Egypt's Ministry of Tourism and Antiquities are compressing entry friction for religious travelers, while conservation quotas at Saint Catherine's Monastery and Coptic heritage sites constrain daily operator capacity and reshape permit economics across the Nile corridor.
Growth Catalysts
- Streamlined Religious Visa Framework:Egypt's Ministry of Tourism and Antiquities has introduced expedited group processing for pilgrimage cohorts, reducing administrative lag for European and North American Christian denominations.
- Halal-Kosher Certification Expansion:Hospitality operators along the Sinai Peninsula and Red Sea gateway cities are securing dual dietary compliance to capture overlapping Muslim and Jewish traveler segments.
- Nile Cruise Infrastructure Renewal:Upper Egypt vessel operators are retrofitting prayer facilities and multilingual guide capacity to anchor occupancy during low-season months.
Market Restraints
- Site Access Quota Rigidity:The Supreme Council of Antiquities enforces daily visitor caps at Saint Catherine's Monastery, compressing operator revenue per sailing.
- Ground Handler Concentration:Cairo and Luxor retain dominant ground transport and guide licensing control, elevating intermediary costs for inbound tour packagers.
- Conservation Fee Escalation:Escalating antiquities preservation levies at Coptic monastery complexes are squeezing margin structures for mid-tier pilgrimage specialists.
Strategic Opportunities
- Sinai Peninsula Retreat Development:The General Authority for Investment and Free Zones offers hospitality incentives for contemplative lodging near Mount Sinai trekking routes.
- Digital Pilgrame Pre-Registration:Mobile-enabled visa and site booking convergence is opening direct-to-traveler channel bypass of traditional operator intermediaries.
- Interfaith Itinerary Packaging:Coptic, Islamic, and Jewish heritage site bundling along the Nile corridor is attracting denominationally diverse group bookings.
Industry Challenges
- Multilingual Spiritual Guide Scarcity:Certified guides fluent in liturgical Arabic, English, and European languages command premium wages, constraining operator scaling.
- Foreign Currency Repatriation Complexity:Tourism revenue conversion rules are complicating partnership structures with European and North American source-market agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Faith Based Tourism Market |
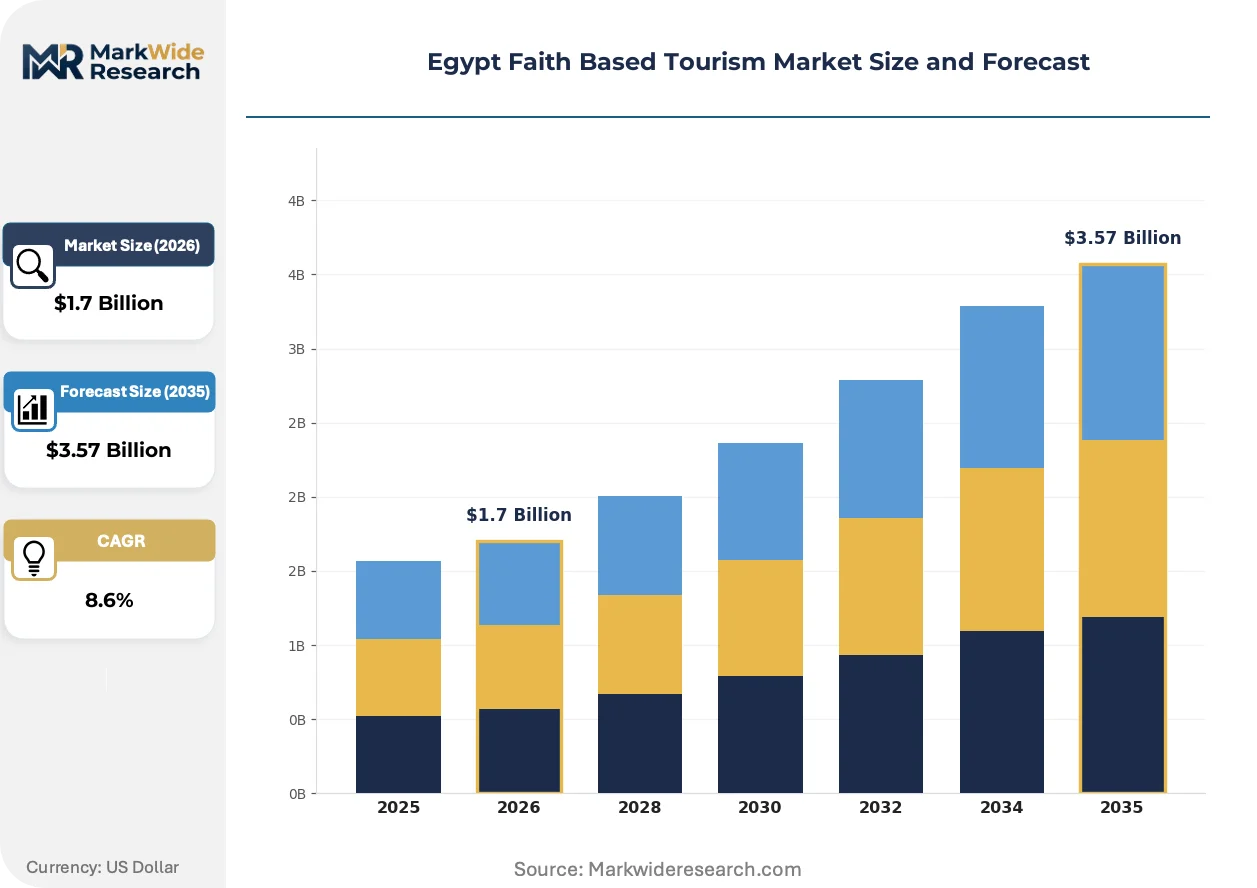
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $3.57 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Pilgrimage, Leisure, Group Tours, Cultural Experiences Visitor Demographics: Families, Seniors, Youth, Couples Attraction Type: Sacred Sites, Religious Festivals, Historical Monuments, Worship Centers Accommodation Type: Hotels, Guesthouses, Hostels, Retreat Centers |
| Companies Covered | TUI Group, Thomas Cook, Expedia, Trafalgar Tours, G Adventures, Globus, Catholic Travel Centre, Holy Land Tours, Pilgrim Tours, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Faith Based Tourism Market Shifts & Advancements
Digital booking platforms and mobile-enabled pilgrimage logistics are compressing traditional operator intermediation, while conservation technology and immersive interpretation tools reshape how sacred sites manage visitor flows and experiential depth.
Virtual reality pre-visit modules are supplanting traditional brochure-based itinerary planning for European and North American Christian pilgrimage cohorts. Denomination-specific travel agencies are deploying immersive previews of Coptic monastery interiors and Mount Sinai trekking routes to accelerate booking conversion. This technology is compressing the research-to-purchase cycle and elevating experiential expectations before arrival.
Egypt's Ministry of Tourism and Antiquities coordinates with the Supreme Council of Antiquities on visitor management mandates that mandate real-time headcount monitoring at restricted religious heritage locations. Tour operators must now integrate digital quota-tracking systems into ground logistics or forfeit same-day site access. Small-scale pilgrimage specialists lacking technical integration capacity face permit exclusion from high-demand liturgical calendars.
Travelers are unbundling traditional package components to construct self-directed pilgrimage itineraries using direct accommodation and transport booking. This fragmentation is eroding Nile cruise vessel occupancy guarantees that historically relied on operator block-booking. The behavior is most pronounced among repeat visitors from German and Italian source markets with established familiarity with Upper Egypt logistics.
Egypt Faith Based Tourism Market Segmentation
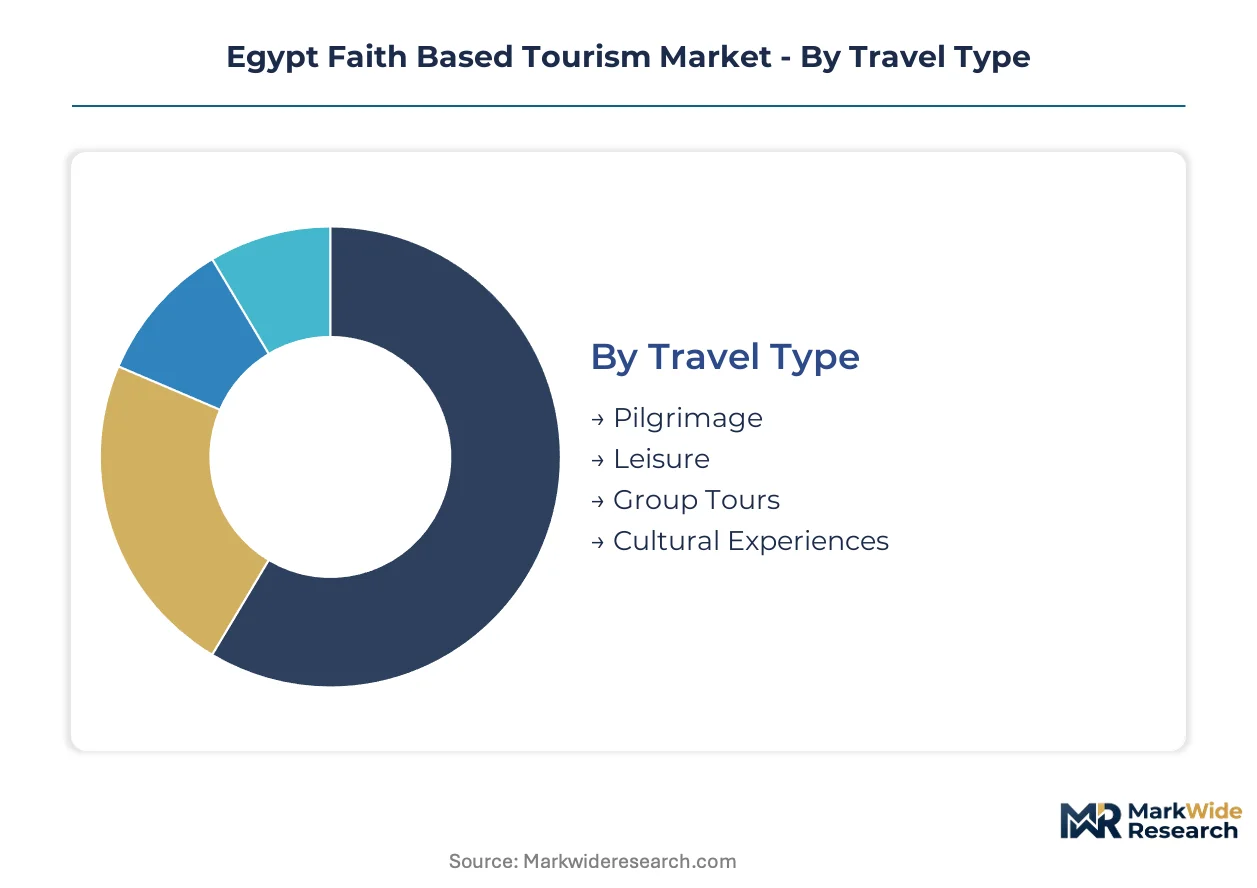
Segmentation in Egypt's faith tourism market reveals distinct operational requirements across travel modalities, demographic cohorts, and site typologies. Each dimension shapes permit economics, guide certification needs, and accommodation procurement strategies for inbound operators.
Travel Type:
Domestic Egyptian travelers favor shorter-duration pilgrimage circuits to Sinai and Upper Egypt monasteries, while European and North American source markets drive outbound-led demand for multi-site Nile itineraries.
- Pilgrimage:Structured journeys to scripturally significant locations including Mount Sinai and Coptic monasteries. Demand concentrates among European Christian denominations seeking liturgical participation at Saint Catherine's Monastery, constrained by Supreme Council of Antiquities daily access quotas.
- Group Tours:Denomination-organized cohort travel with pre-arranged guides, transport, and worship scheduling. Nile cruise vessels anchor occupancy through operator block-booking during low-season months, though direct booking fragmentation is eroding historical guarantees.
- Leisure:Faith-motivated travel with discretionary sightseeing components. Red Sea gateway cities of Hurghada and Sharm El-Sheikh capture this segment through charter capacity.
- Cultural Experiences:Educational itineraries blending religious heritage with archaeological interpretation. Cairo and Luxor ground handlers dominate intermediary services for this modality.
Pilgrimage holds the largest share; momentum sits with Group Tours as visa facilitation streamlines cohort processing.
Visitor Demographics:
Seniors command premium per-visitor spend through extended stays and guided liturgical programming, while youth segments drive volume through budget hostel accommodation and self-directed Sinai trekking routes.
- Seniors:Extended-stay travelers prioritizing comfort-accessible lodging and multilingual spiritual guide accompaniment. Coptic monastery retreat centers in Upper Egypt target this cohort with contemplative programming.
- Families:Multi-generational units requiring halal-kosher meal certification and prayer facility proximity. Sinai Peninsula hospitality operators are securing dual dietary compliance to capture this expanding segment.
- Youth:Budget-conscious travelers utilizing direct booking platforms for hostel and ground transport unbundling. German and Italian repeat visitors exhibit strongest self-directed itinerary construction behavior.
- Couples:Paired travelers seeking intimate retreat experiences near sacred sites. Mount Sinai sunrise trekking routes attract this demographic through boutique guesthouse development.
Seniors dominate revenue contribution; youth segments are climbing the fastest through digital channel adoption.
Attraction Type:
Sacred Sites generate highest per-visitor expenditure due to restricted access protocols and premium guide requirements, while Religious Festivals concentrate demand spikes that strain local accommodation capacity.
- Sacred Sites:Locations of scriptural significance with regulated visitor management mandates. Saint Catherine's Monastery enforces real-time headcount monitoring, compressing operator revenue per sailing for non-compliant packagers.
- Religious Festivals:Seasonal liturgical observances attracting denomination-specific cohorts. Coptic Christmas and Easter calendars drive peak occupancy pricing across Nile corridor properties.
- Historical Monuments:Archaeological heritage locations with religious narrative overlay. Luxor and Aswan temples attract interfaith itinerary bundling from Muslim and Jewish traveler segments.
- Worship Centers:Active religious infrastructure permitting ritual participation. Cairo's Hanging Church and Coptic cathedral complexes anchor day-trip programming for cruise passengers.
Sacred Sites command premium pricing; Religious Festivals show steepest expansion trajectory through liturgical calendar marketing.
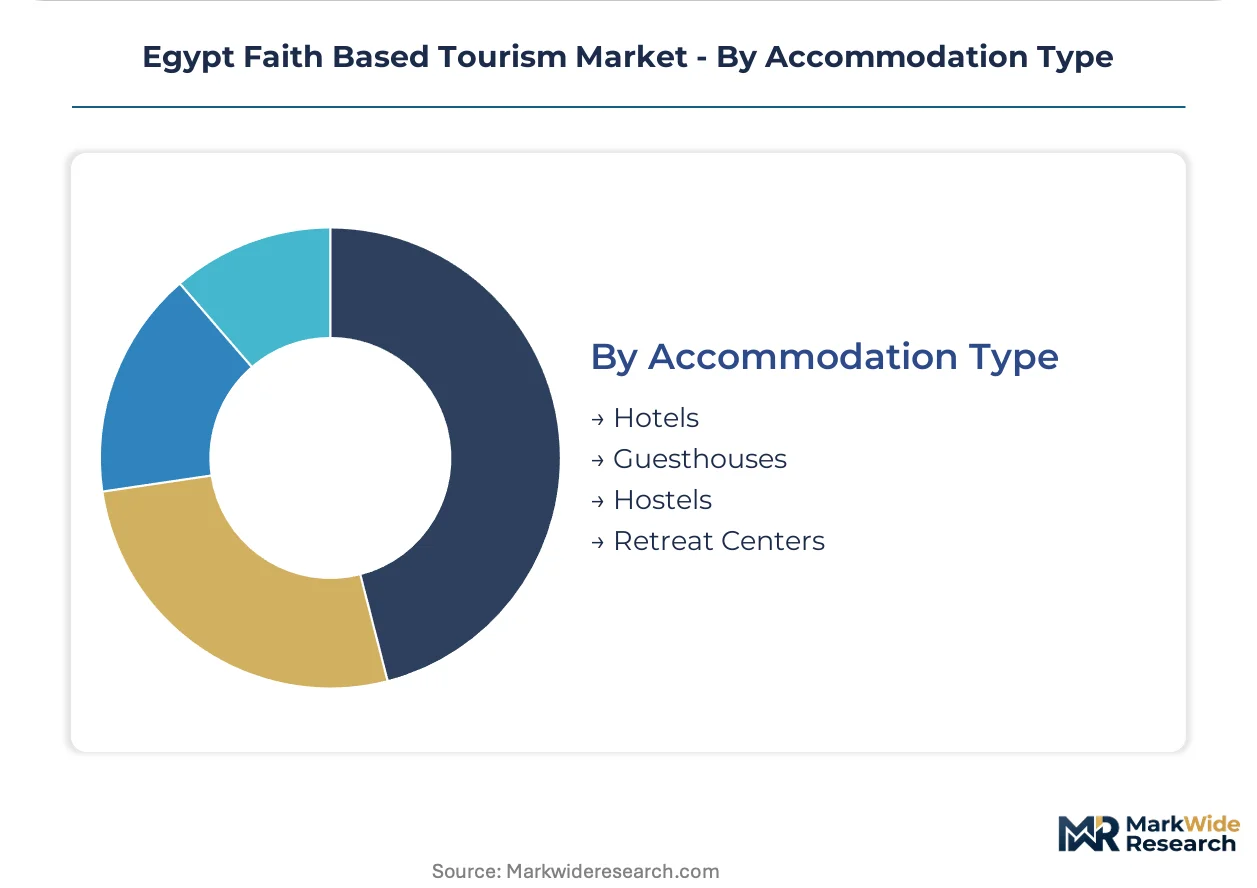
Accommodation Type:
Hotels retain dominant market position through international brand recognition and loyalty program integration, while Retreat Centers capture margin expansion through contemplative programming differentiation.
- Hotels:Full-service properties with standardized amenity provisioning. International chains in Cairo and Red Sea gateway cities leverage global distribution systems for pilgrimage package bundling.
- Retreat Centers:Purpose-built contemplative lodging with prayer facility integration. The General Authority for Investment and Free Zones offers hospitality incentives for Sinai Peninsula development near trekking routes.
- Guesthouses:Small-scale family-operated properties in Upper Egypt pilgrimage corridors. Coptic monastery-adjacent units provide authentic liturgical proximity at mid-tier price points.
- Hostels:Budget dormitory accommodation targeting youth and independent travelers. Cairo and Luxor retain dominant licensing control, elevating intermediary costs for direct-booking platforms.
Hotels maintain volume leadership; Retreat Centers are gaining share fastest through Ministry of Tourism and Antiquities investment incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilgrimage spending power concentrates in European source markets while North American operators command premium packaging margins, creating a pricing-power asymmetry that shapes operator site access economics along Egypt's Nile corridor.
Cairo and Giza Governorates
Coptic Christian heritage sites and Islamic monuments anchor domestic and inbound pilgrimage flows. Egypt's Ministry of Tourism and Antiquities coordinates with the Supreme Council of Antiquities to regulate conservation fees at the Hanging Church and Coptic Museum complexes. New hospitality capacity is materializing in Giza's satellite corridors to capture overflow from Cairo's saturated core.
South Sinai Governorate
Mount Sinai trekking routes and Saint Catherine's Monastery generate the highest per-visitor expenditure in Egypt's faith tourism portfolio. Daily visitor quotas enforced by antiquities regulators constrain operator permit economics and compress revenue per sailing for non-compliant packagers. Boutique retreat development is clustering along Saint Catherine's trekking approach routes under General Authority for Investment and Free Zones incentives.
Luxor and Aswan Governorates
Pharaonic temple complexes with religious narrative overlay attract interfaith itinerary bundling from Muslim and Jewish traveler segments. Nile cruise vessels anchor occupancy through operator block-booking during low-season months, though direct booking fragmentation is eroding historical guarantees. Ground handler licensing concentration in Luxor elevates intermediary costs for inbound tour packagers.
Red Sea Gateway Cities
Hurghada and Sharm El-Sheikh serve as charter flight entry points for European pilgrimage cohorts seeking Sinai access. Dual halal-kosher certification expansion across resort properties is capturing overlapping Muslim and Jewish traveler segments. Thomas Cook competes on price-accessible charter capacity into these gateway cities.
Egypt Faith Based Tourism Market Competitive Landscape
Concentration sits with integrated tour operators leveraging global distribution networks to package multi-site Nile itineraries. Niche pilgrimage specialists sustain margins through curated liturgical experiences at restricted-access sacred sites. Three archetypes dominate: global travel conglomerates with charter capacity, denomination-specific programming specialists, and digital-native experience platforms. Competitive moves center on permit economics optimization at quota-constrained sites and direct-to-traveler channel development bypassing traditional intermediaries.
Within the global conglomerate tier, TUI Group and Thomas Cook exemplify scale-driven packaging strategies that bundle flights, ground transport, and guided sacred site visits across the Nile corridor. Catholic Travel Centre occupies a specialist position, sustaining margins through denomination-specific programming and curated liturgical experiences at Coptic monasteries and Mount Sinai. These three anchors represent divergent capital-intensity strategies across Egypt's faith tourism value chain.
| Leading Market Players |
|---|
| TUI Group |
| Thomas Cook |
| Expedia |
| Trafalgar Tours |
| G Adventures |
| Globus |
| Catholic Travel Centre |
| Holy Land Tours |
| Pilgrim Tours |
| Others |
Supply & Pricing Matrix
Charter flight capacity utilization into Red Sea gateway cities shapes both supply concentration and price floors across Egypt's faith tourism corridor. TUI Group and Thomas Cook leverage scale economies to compress per-seat costs on Sinai-bound routes, while niche pilgrimage specialists absorb premium ground handler markups in Cairo and Luxor where licensing concentration elevates intermediary fees.
Pricing Analysis
The customization-premium spread separates standard Nile cruise packages from curated liturgical experiences at Saint Catherine's Monastery. Three-tier pricing structure across premium, standard, and economy levels reflects guide certification grade and prayer facility integration. Price differentiation hinges on multilingual spiritual guide accompaniment and halal-kosher dual certification. Cost compression in mid-tier pilgrimage packages is intensifying because conservation fee escalation at Coptic heritage sites squeezes operator margins. Youth segments utilizing direct booking platforms exhibit highest price sensitivity, while seniors seeking contemplative retreat programming show lowest elasticity.
Supply Chain Analysis
Just-in-time permit procurement dominates operator behavior at quota-constrained sacred sites, with strategic stockpiling of vessel capacity during low-season months. Geographic supply concentrates in Egypt's Nile corridor, with ground handler licensing anchored in Cairo and Luxor, vessel operations clustered in Aswan, and retreat development incentivized across South Sinai. Raw material dependencies include multilingual guide labor pools, antiquities conservation technology, and mobile-enabled booking infrastructure. Single-source vulnerability runs through Cairo-Luxor ground transport licensing control. Distribution runs through global travel conglomerate networks and denomination-specific specialist agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in self-directed pilgrimage logistics where digital-native travelers bypass traditional operator intermediation. Direct booking platform adoption among German and Italian repeat visitors creates niche service gaps incumbents under-serve.
For Market Incumbents: Compound permit economics optimization at Saint Catherine's Monastery by integrating real-time quota-tracking systems before antiquities regulators expand digital compliance mandates. Vertical integration into Sinai Peninsula retreat development captures General Authority for Investment and Free Zones incentives. Defensive consolidation should target Cairo and Luxor ground handler licensing control to preserve margin structure against direct-booking fragmentation. For New Entrants and Emerging Players: Multilingual spiritual guide scarcity presents white-space targeting for certified training program development and direct employment models bypassing Cairo licensing concentration. Mount Sinai sunrise trekking route boutique guesthouse development offers most penetrable geography under South Sinai investment incentives. Go-to-market positioning should emphasize mobile-enabled pre-registration convergence with visa facilitation protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among denomination-specific programming specialists sustaining margins through curated liturgical experiences. Long-term viability over the projection horizon favors acquisition targets with direct channel development and conservation technology integration capacity. Watch Supreme Council of Antiquities digital quota system expansion as inflection indicator for technical integration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Pilgrimage Pre-Registration Platform | Mobile-enabled visa and site booking convergence bypasses traditional operator intermediation channels. |
| Sinai Peninsula Retreat Development | General Authority for Investment and Free Zones hospitality incentives reduce capital deployment barriers near trekking routes. |
| Multilingual Spiritual Guide Certification Program | Certified training capacity addresses scarcity constraining operator scaling across European source markets. |
| Interfaith Itinerary Packaging | Coptic, Islamic, and Jewish heritage bundling attracts denominationally diverse group bookings along Nile corridor. |
| Conservation Technology Integration | Real-time headcount monitoring compliance preserves permit access at Saint Catherine's Monastery quota-constrained site. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Egypt's Ministry of Tourism and Antiquities policy circulars, Supreme Council of Antiquities conservation mandates, and General Authority for Investment and Free Zones incentive disclosures. Primary interviews engaged tour operator executives, Nile cruise vessel managers, Coptic monastery hospitality coordinators, and Sinai Peninsula retreat developers. Secondary validation drew from customs arrival statistics, antiquities fee schedules, and hospitality licensing records. Bottom-up demand modeling triangulates against top-down spending flow analysis across European and North American source markets.
Segmentation dimensions modeled include travel type, visitor demographic cohort, attraction typology, and accommodation category across the analysis window. Analytical framework incorporates permit economics at quota-constrained sacred sites, ground handler concentration effects, and direct booking fragmentation trajectories. CAGRs derive from cohort-specific spending patterns and capacity utilization trends. Industry-specific forecast inputs include visa facilitation processing volumes and conservation fee escalation schedules.
Forecasts assume regulatory continuity in Egypt's antiquities preservation and foreign currency repatriation regimes; material policy shifts would require re-modeling. Specific risks include Supreme Council of Antiquities quota expansion or contraction, Ministry of Tourism and Antiquities visa framework modifications, and General Authority for Investment and Free Zones incentive withdrawal. Revision becomes warranted when digital quota compliance requirements cross thresholds excluding small-scale operator participation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
South Africa Casino Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
Golf Tourism Market
Destination Management and Attractions
Adventure Tourism Market