
 Theme Park Tourism Market | 2026-2036
Theme Park Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Theme Park Tourism Market Analytics
Multi-source content licensing is expanding as theme park operators diversify intellectual property partnerships beyond single-studio dependencies. Disney Experiences leverages its proprietary character portfolio to sustain captive merchandise demand across resort ecosystems. Universal Destinations & Experiences anchors its growth through licensed franchise integrations that compete directly with original-character parks. Merlin Entertainments Group specializes in location-based entertainment formats that occupy secondary and tertiary tourism markets with smaller-footprint attractions.
Theme park tourism encompasses the commercial operation of gated entertainment destinations featuring mechanical rides, live performances, and immersive environmental design intended to attract overnight and day-trip visitation. These facilities typically integrate food service, retail, and lodging components to maximize per-capita guest expenditure across extended dwell times. Thrill rides and themed experiences command the highest capital allocation and generate disproportionate repeat visitation among domestic audiences. Multi-day ticket structures now dominate revenue architecture for destination parks, while single-day admissions concentrate at regional facilities serving drive markets. Food and beverage operations represent the most reliable margin pool across service categories due to inelastic captive demand during extended guest stays.
The US Consumer Product Safety Commission and ASTM International F24 committee govern ride design standards domestically, while China's SAMR enforces national GB codes for large amusement facilities. These frameworks elevate compliance costs for operators but simultaneously reduce liability exposure and build visitor trust. Stakeholders must monitor evolving accessibility mandates and environmental sustainability disclosures as these criteria increasingly influence licensing approvals and consumer selection behavior.
Market Dynamics
Capital allocation toward immersive intellectual property integration is compressing development cycles and elevating per-guest spending targets across destination parks. This structural force is redistributing competitive advantage toward operators with captive content libraries or exclusive licensing arrangements.
Growth Catalysts
- China's GB 8408 amusement ride safety standards:Unified national codes are accelerating equipment modernization and building visitor confidence in domestic park visitation.
- Multi-day ticket architecture:Destination resorts are capturing extended dwell time through bundled lodging and experience packages that deepen per-capita expenditure.
- Secondary tourism market penetration:Smaller-footprint attractions in tertiary cities are expanding addressable visitation beyond traditional gateway destinations.
Market Restraints
- Steel and aluminum input volatility:Thrill ride construction faces margin pressure from commodity price swings in structural metals and specialized composites.
- Design certification timelines:ASTM F24 committee review processes and state-level amusement ride inspections create extended pre-opening delays for mechanical attractions.
- Substitute entertainment formats:Location-based virtual reality venues and streaming content platforms compete for discretionary leisure spending among younger demographics.
Strategic Opportunities
- India's emerging middle-class leisure expenditure:Underdeveloped branded entertainment infrastructure presents first-mover positioning for international operators and domestic developers.
- EU CSRD sustainability disclosure mandates:Early compliance with environmental reporting requirements is creating licensing advantages and green financing access for European park expansions.
- Seasonal demand smoothing through indoor immersive formats:Climate-controlled environments enable year-round operation in regions with extreme weather patterns.
Industry Challenges
- Specialized ride engineering talent scarcity:The convergence of mechanical systems, show control, and themed narrative design requires hybrid skill sets that outpace vocational pipeline output.
- IP licensing negotiation complexity:Exclusive franchise agreements demand escalating minimum guarantees and creative control provisions that strain operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Theme Park Tourism Market |
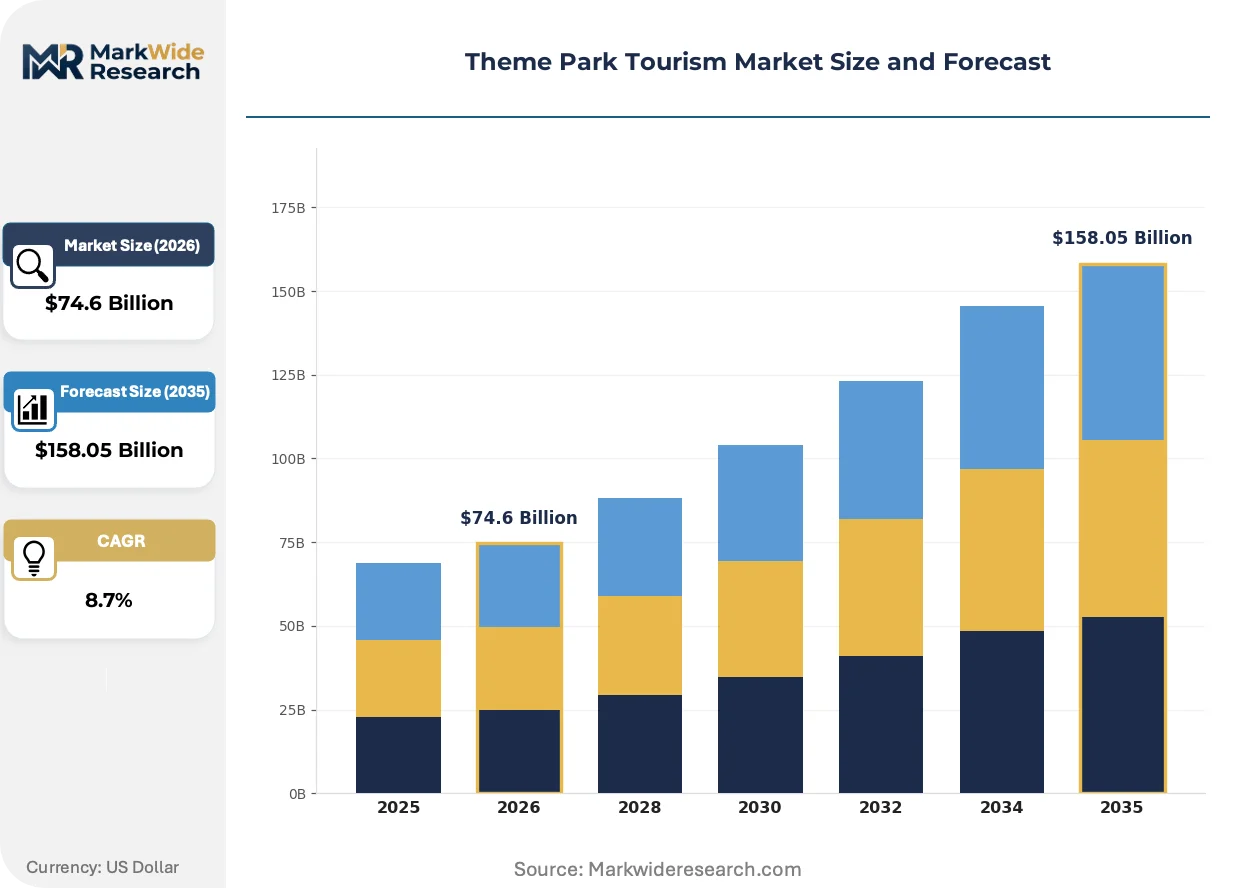
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $158.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Visitor Type: Families, Solo Travelers, Groups, Couples Ticket Type: Single-Day, Multi-Day, Annual Pass, Combo Tickets Attraction Type: Thrill Rides, Water Attractions, Themed Experiences, Live Shows Service Type: Food & Beverage, Merchandise, Guided Tours, Accommodations |
| Companies Covered | Universal Destinations & Experiences, Six Flags, Disney Experiences, Cedar Fair, United Parks and Resorts, Fantawild Group, Chimelong Group, Herschend Family Entertainment, Merlin Entertainments Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Theme Park Tourism Market Evolving Landscape
Experience personalization through real-time data integration is fragmenting traditional one-size-fits-all attraction design. This shift is enabling dynamic pricing, adaptive queue management, and individualized narrative branching that redefines guest engagement metrics.
Trackless ride vehicle systems are modularizing dark ride construction by replacing fixed-path hardware with autonomous navigation platforms. Regional parks in Japan and South Korea are adopting these systems to reduce civil engineering requirements and accelerate installation timelines. This technology is modularizing what were previously bespoke, location-dependent attractions into repeatable, redeployable formats.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration and air conditioning systems across leisure facilities. Theme park operators are retrofitting climate control infrastructure to comply with quota reductions and avoid supply disruptions. Indoor immersive environments in Germany, France, and the Netherlands face the most acute compliance pressure and are accelerating adoption of natural refrigerant alternatives.
Visitor purchasing behavior is fragmenting across digital channels as mobile pre-booking displaces on-site ticket counter transactions. Regional parks serving drive markets are losing walk-up revenue to aggregator platforms and dynamic discount apps. This pattern is most visible in the United States, where third-party resellers now capture substantial share of single-day admission sales.
Theme Park Tourism Market Segmentation
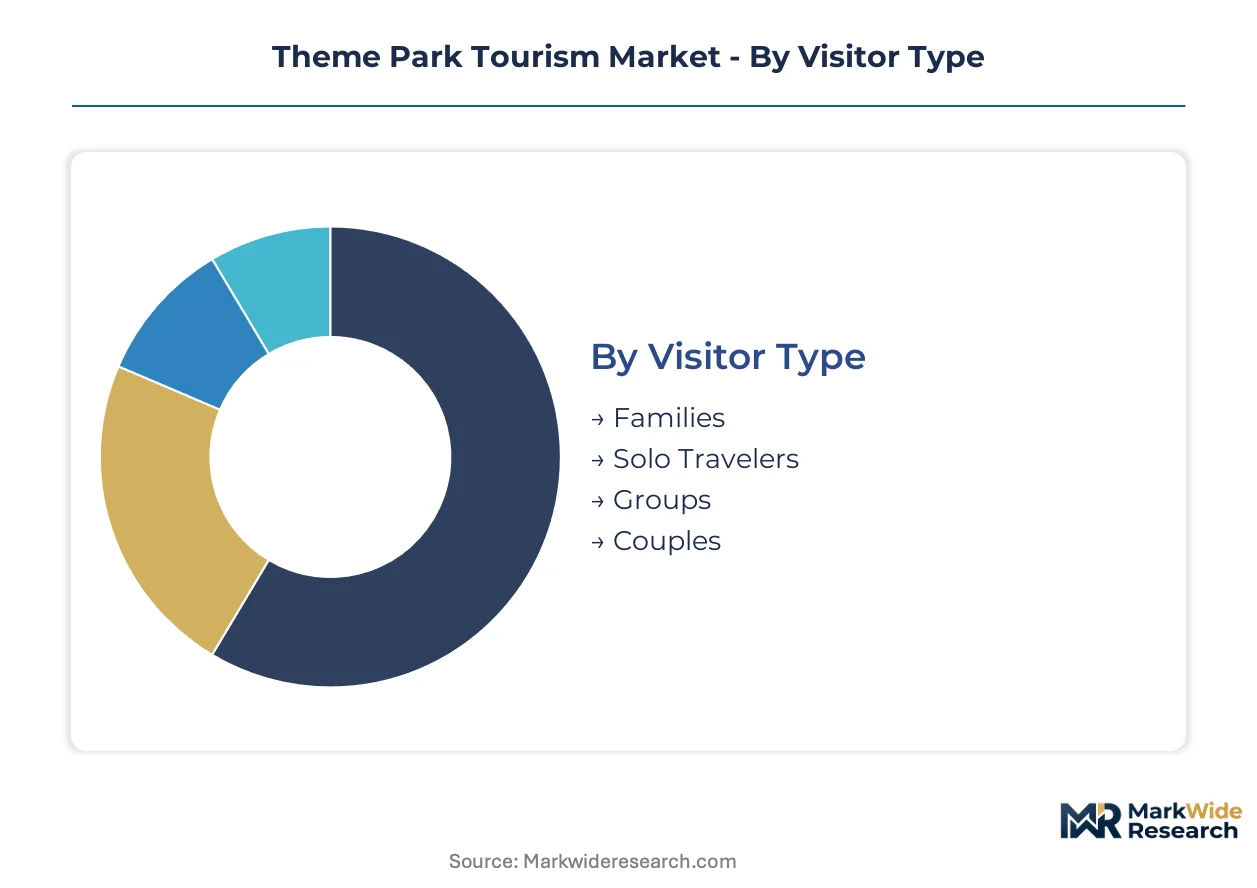
Segmentation in theme park tourism reveals how distinct visitor motivations and spending patterns shape operational design across destination and regional facilities. Understanding these divides enables operators to optimize capacity allocation, pricing architecture, and service mix against specific demand profiles.
Visitor Type:
Purchase behavior diverges sharply based on group composition and decision-making dynamics.
- Families:Multi-generational units drive peak-season occupancy and command the highest per-capita expenditure through bundled meal plans and character dining. Orlando and Anaheim resorts concentrate infrastructure investment here, with China's domestic parks now replicating this model.
- Solo Travelers:Individual visitors prioritize single-rider queue access and flexible scheduling, generating disproportionate repeat visitation at regional facilities with season pass programs. This segment expands most quickly in Japan's urban entertainment clusters.
- Groups:Corporate outings and school excursions fill mid-week capacity troughs through block booking arrangements with predictable catering minimums.
- Couples:Paired visitors concentrate spending on premium accommodations and after-hours events, supporting margin-rich hospitality extensions.
Families lead on scale; solo travelers lead on momentum.
Ticket Type:
Revenue architecture hinges on dwell-time extension and commitment depth.
- Multi-Day:Bundled admission structures anchor destination resort economics by capturing lodging and dining spend across extended stays. Universal Orlando and Walt Disney World have shifted primary inventory toward this format.
- Annual Pass:Subscription models convert local drive markets into predictable recurring revenue with food and beverage upsell potential. Regional operators in Germany and France deploy tiered membership levels to segment price sensitivity.
- Single-Day:Standalone admission concentrates at secondary parks serving spontaneous visitation with lower advance commitment thresholds.
- Combo Tickets:Cross-attraction bundling with museums, zoos, or transportation spreads visitor acquisition costs across partner venues.
Multi-day products dominate revenue contribution; annual pass programs gain share fastest in mature markets.
Attraction Type:
Capital deployment priorities reflect competitive differentiation requirements.
- Thrill Rides:High-capacity roller coasters and launched attractions command the largest construction budgets and generate media coverage that drives destination positioning. ASTM F24 certification requirements extend development timelines for US installations.
- Themed Experiences:Immersive dark rides and narrative environments leverage intellectual property licensing to extend dwell time and merchandise conversion. Trackless vehicle adoption is accelerating in South Korea and Japan.
- Water Attractions:Seasonal and year-round aquatic facilities address climate constraints and family segmentation with lower per-gate capital intensity.
- Live Shows:Theatrical productions and stunt performances provide capacity absorption during peak visitation with fixed operating cost structures.
Thrill rides anchor capital allocation; themed experiences show the steepest expansion trajectory.
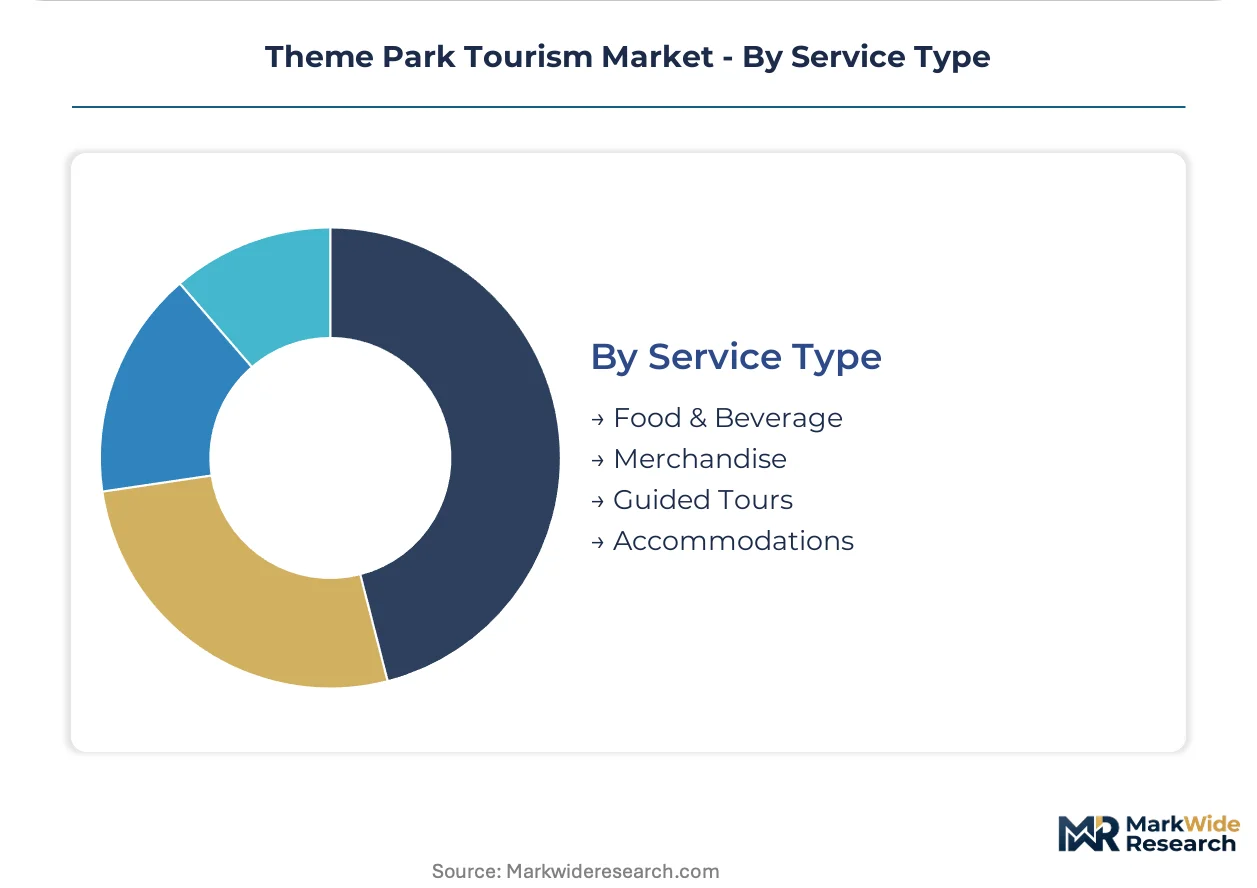
Service Type:
Ancillary revenue streams determine margin sustainability beyond admission economics.
- Food & Beverage:Captive dining operations generate the most reliable margin pool through inelastic demand during extended guest stays. China's GB standards for food safety compliance are elevating operational requirements for domestic park operators.
- Merchandise:Licensed product retail converts emotional engagement into tangible purchase, with proprietary character portfolios outperforming third-party licensing arrangements.
- Accommodations:On-site lodging extends per-visitor revenue capture and enables early entry privileges that improve attraction throughput.
- Guided Tours:Premium experiential add-ons segment price-insensitive visitors through exclusive access and narrative depth.
Food and beverage leads on margin reliability; accommodations drive the highest incremental spend per conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orlando and Anaheim anchor concentrated destination tourism flows in the United States, where theme park infrastructure commands the highest capital deployment density worldwide. China's domestic parks are replicating the Orlando model across tier-one cities. European operators face acute sustainability compliance pressure under the EU F-Gas Regulation.
United States
Multi-day ticket architectures and bundled lodging packages capture extended dwell time across Orlando and Anaheim resort ecosystems. The US Consumer Product Safety Commission and ASTM International F24 committee govern ride design standards domestically, elevating compliance costs but reducing liability exposure. Cedar Point in Sandusky, Ohio and Six Flags Magic Mountain in Valencia, California concentrate thrill ride innovation and seasonal pass program development.
China
Fantawild Group and Chimelong Group are deepening engagement with immersive domestic intellectual property across tier-one urban clusters. SAMR enforces national GB 8408 codes for large amusement facilities, accelerating equipment modernization and building visitor confidence. Shenzhen's Nanshan district and Guangzhou's Panyu district host flagship integrated resort developments competing directly with international destination formats.
Japan
Solo traveler segmentation expands most quickly in Tokyo and Osaka urban entertainment clusters through flexible season pass structures. METI oversees industrial standards coordination while local prefectural governments manage operational licensing for mechanical attractions. Universal Studios Japan in Osaka and Tokyo Disney Resort in Urayasu anchor Asia-Pacific destination tourism flows with proprietary and licensed character portfolios.
Germany
Regional operators deploy tiered annual pass membership levels to segment price sensitivity across drive markets in Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation phases down hydrofluorocarbon use in climate control systems, forcing retrofit investment in indoor immersive environments. Europa-Park in Rust and Phantasialand in Brühl represent the continent's largest family-owned destination resort concentrations outside Disney's European footprint.
United Arab Emirates
Premium accommodation extensions and after-hours events capture margin-rich couple segmentation in Dubai's integrated entertainment districts. MOHAP and local municipal authorities coordinate safety inspections for mechanical attractions in free zone developments. IMG Worlds of Adventure and Dubai Parks and Resorts anchor the Middle East's highest per-capita guest expenditure metrics through climate-controlled year-round operation.
Theme Park Tourism Market Competitive Landscape
Global majors compete with regional champions across intellectual property integration and capital intensity dimensions. The vendor base stratifies between consolidated destination resort operators and fragmented regional facility networks serving drive markets. Three archetypes dominate: proprietary content libraries, exclusive licensing arrangements, and location-based entertainment specialists. Competitive moves concentrate on strategic partnerships for franchise rights and geographic expansion into underpenetrated secondary tourism markets.
Within the proprietary content tier, Disney Experiences exemplifies captive character portfolio monetization across resort ecosystems. Universal Destinations & Experiences occupies a position anchored in licensed franchise integrations that compete directly with original-character parks. Merlin Entertainments Group represents the location-based entertainment specialist archetype, with smaller-footprint attractions concentrated in secondary and tertiary tourism markets. These three operators illustrate the structural divergence between integrated resort economics and regional facility profitability models.
| Leading Market Players |
|---|
| Universal Destinations & Experiences |
| Six Flags |
| Disney Experiences |
| Cedar Fair |
| United Parks and Resorts |
| Fantawild Group |
| Chimelong Group |
| Herschend Family Entertainment |
| Merlin Entertainments Group |
| Others |
Value Network & Pricing Analysis
Destination resort operators concentrating in Orlando and Anaheim anchor pricing power through multi-day bundled packages that compress per-guest acquisition costs across extended dwell times. This buyer archetype concentration feeds back into supply chain decisions, favoring long-term equipment financing structures over spot-market procurement for mechanical attractions.
Pricing Analysis
Steel and aluminum input volatility passes through to thrill ride construction quotes, compressing margins for regional operators lacking volume-scale purchasing leverage. Three-tier pricing structure across premium, standard, and economy levels segments visitors by advance commitment depth, with annual pass holders capturing the steepest per-visit discounts. Pricing pressure stems from substitute entertainment formats competing for discretionary leisure spending, particularly among younger demographics. Regional facilities serving drive markets exhibit the highest price sensitivity, while destination resorts with captive lodging demand maintain inelastic pricing architecture.
Supply Chain Analysis
Specialized ride engineering components rest on concentrated sourcing from Germany, Japan, and the United States, where precision mechanical fabrication and show control system integration cluster. Structural steel, rare-earth magnets for launch systems, and high-performance composites constitute critical input dependencies. Single-source vulnerability persists in trackless vehicle navigation platforms, where South Korean and Japanese suppliers dominate proprietary autonomous guidance technology. Distribution runs through direct OEM relationships for major destination resorts, while regional operators rely on third-party ride brokers and refurbishment specialists for secondary market equipment.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The theme park tourism market reads as a late-cycle quality story, with visitor purchasing behavior fragmenting toward premium immersive experiences that command extended dwell times and elevated per-capita expenditure.
For Market Incumbents: Anticipate margin compression from escalating IP licensing minimum guarantees by diversifying toward proprietary character development and captive content libraries. Defensive consolidation should emphasize backward integration into food service and merchandise supply chains to capture margin pools currently leaking to third-party vendors. ASTM F24 certification investments create regulatory moats against smaller regional competitors lacking compliance infrastructure. For New Entrants and Emerging Players: Launch via location-based entertainment formats in India's underpenetrated secondary cities, where branded entertainment infrastructure remains underdeveloped relative to emerging middle-class leisure expenditure. White-space targets include climate-controlled indoor immersive venues in regions with extreme seasonal weather patterns, and tier-two Chinese markets beyond the Fantawild-Chimelong duopoly. Go-to-market positioning should emphasize flexible season pass structures and single-rider queue optimization to capture solo traveler segmentation expanding fastest in Japanese urban clusters. For Investors and Strategic Acquirers: Regional destination resort operators with established annual pass programs are the most active acquirer in this space, seeking geographic footprint expansion to amortize fixed marketing costs across multiple properties. Long-term viability hinges on IP renewal cycles and regulatory compliance infrastructure that smaller operators cannot replicate. Watch for inflection in steel and aluminum commodity indices as a signal for capital deployment timing on new mechanical attraction development.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary IP Development | Disney Experiences monetizes captive character portfolios across resort ecosystems without licensing minimum guarantees. |
| Climate-Controlled Indoor Expansion | Europa-Park and Phantasialand retrofit immersive environments to comply with EU F-Gas Regulation refrigerant phase-down mandates. |
| Trackless Vehicle Adoption | South Korean and Japanese regional parks deploy autonomous navigation platforms to reduce civil engineering requirements. |
| Annual Pass Program Tiering | German and French operators segment price sensitivity across drive markets through membership level differentiation. |
| Secondary Market Geographic Expansion | Merlin Entertainments Group occupies tertiary tourism markets with smaller-footprint attractions outside gateway destinations. |
Research Methodology
Coverage spans the United States, China, Japan, Germany, and the United Arab Emirates, with primary inputs from each market cluster combining executive interviews with theme park operations directors, IP licensing negotiators, ride engineering procurement leads, and hospitality revenue management specialists. Secondary validation draws from ASTM International committee proceedings, SAMR GB standard filings, EU F-Gas Regulation compliance disclosures, and trade data on amusement equipment imports. Bottom-up segmentation modeling triangulates against top-down macroeconomic leisure expenditure indices.
Granularity-level framing applies visitor type, ticket architecture, attraction category, and service type as distinct modeling dimensions, with geographic regulatory cluster as an overlay variable. CAGRs derive from weighted average growth assumptions across these segments, with mechanical attraction capital expenditure cycles and IP renewal timelines as industry-specific forecast inputs throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility scenarios and regulatory acceleration in sustainability disclosure requirements. Forecasts reflect documented assumptions on visitor dwell time elasticity and substitution effects from location-based virtual reality venues. A small set of triggers—including steel input cost spikes, F-Gas quota enforcement severity, and India's infrastructure development pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
UAE Faith Based Tourism Market
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
SAVE Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Europe Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
North America Amusement Parks Market
Destination Management and Attractions
Agro-Rural Tourism Market