
 Museums Tourism Market | 2026-2036
Museums Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Museums Tourism Market Foresight
Buyer concentration across museum tourism is restructuring as educational groups and corporate incentive planners fragment traditional leisure-dominated demand. Viator competes through platform scale and inventory breadth across heritage institutions worldwide. Metropolitan Museum of Art anchors premium visitation through blockbuster exhibition programming and membership ecosystems. Abercrombie & Kent differentiates via ultra-luxury cultural itineraries with curator-access components.
Museums tourism encompasses structured visitation to institutions preserving and exhibiting collections of artistic, historical, scientific, or cultural significance, typically operating through climate-controlled galleries with specialized conservation protocols and timed-entry capacity management. The primary commercial purpose centers on revenue generation through admissions, ancillary retail, and hospitality while fulfilling educational and preservation missions. International tourists dominate revenue per visitor within the visitor type dimension, though educational groups deliver higher ancillary workshop conversion. Art exhibitions command premium ticketing within exhibition type segmentation, while virtual tours represent the fastest-expanding service type as institutions deploy immersive digital infrastructure.
The EU Web Accessibility Directive, the Americans with Disabilities Act enforced by the Department of Justice, and ISO 9001 quality management standards collectively shape physical and digital access requirements across museum operations. These frameworks mandate captioning, tactile interfaces, and barrier-free routing that drive capital allocation toward inclusive design. Stakeholders must monitor evolving digital heritage preservation standards and carbon accounting rules for cultural travel to anticipate compliance-driven investment cycles.
Market Dynamics
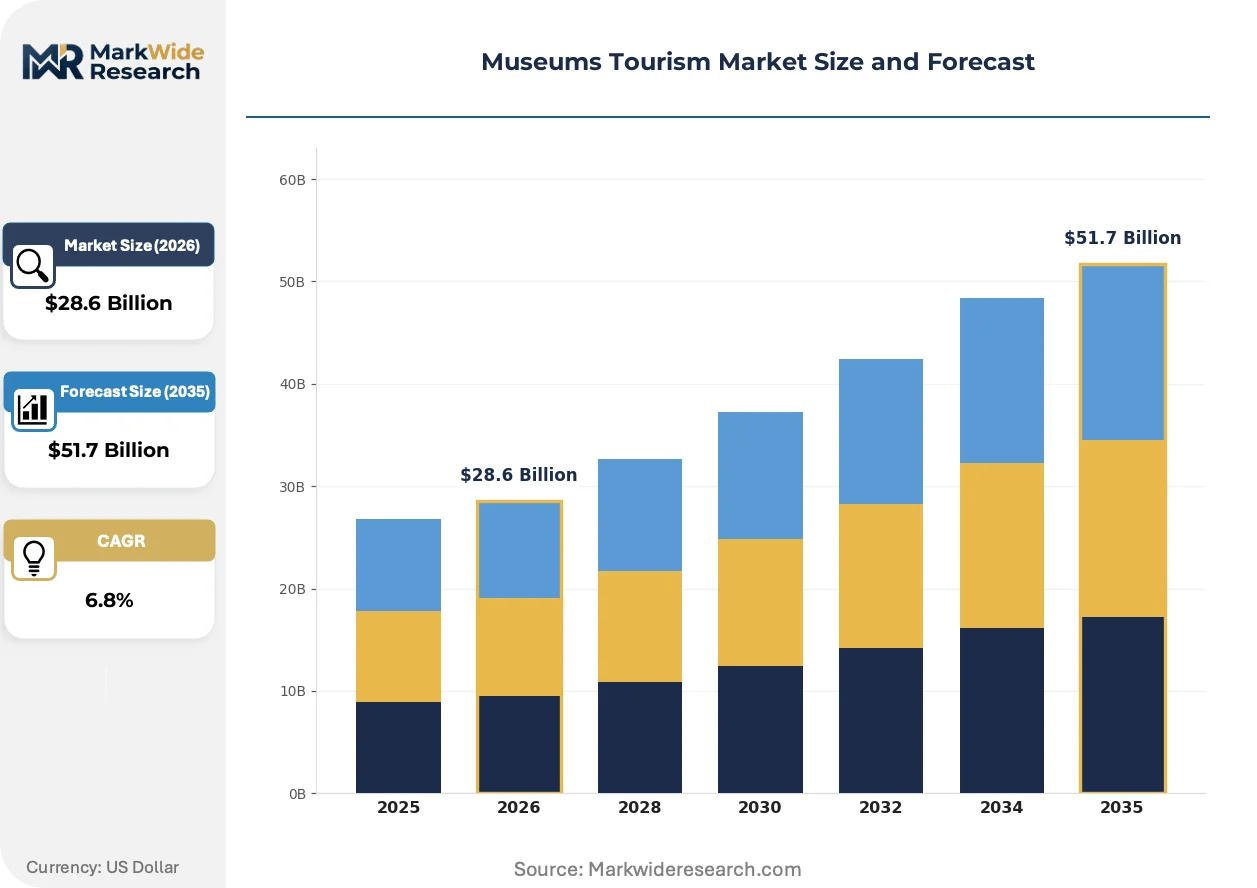
Experiential learning mandates from educational institutions are fragmenting traditional leisure demand while digital accessibility regulations under the EU Web Accessibility Directive force capital reallocation toward inclusive infrastructure across museum operations.
Growth Catalysts
- EU Web Accessibility Directive:Mandates captioning, tactile interfaces, and barrier-free routing accelerate technology upgrades across European institutions.
- Educational group visitation:Schools and universities prioritize curriculum-integrated museum experiences, expanding weekday demand and workshop conversion.
- Paris-London-New York cluster density:Cultural capital concentration enables itinerary bundling and cross-institutional ticketing partnerships.
Market Restraints
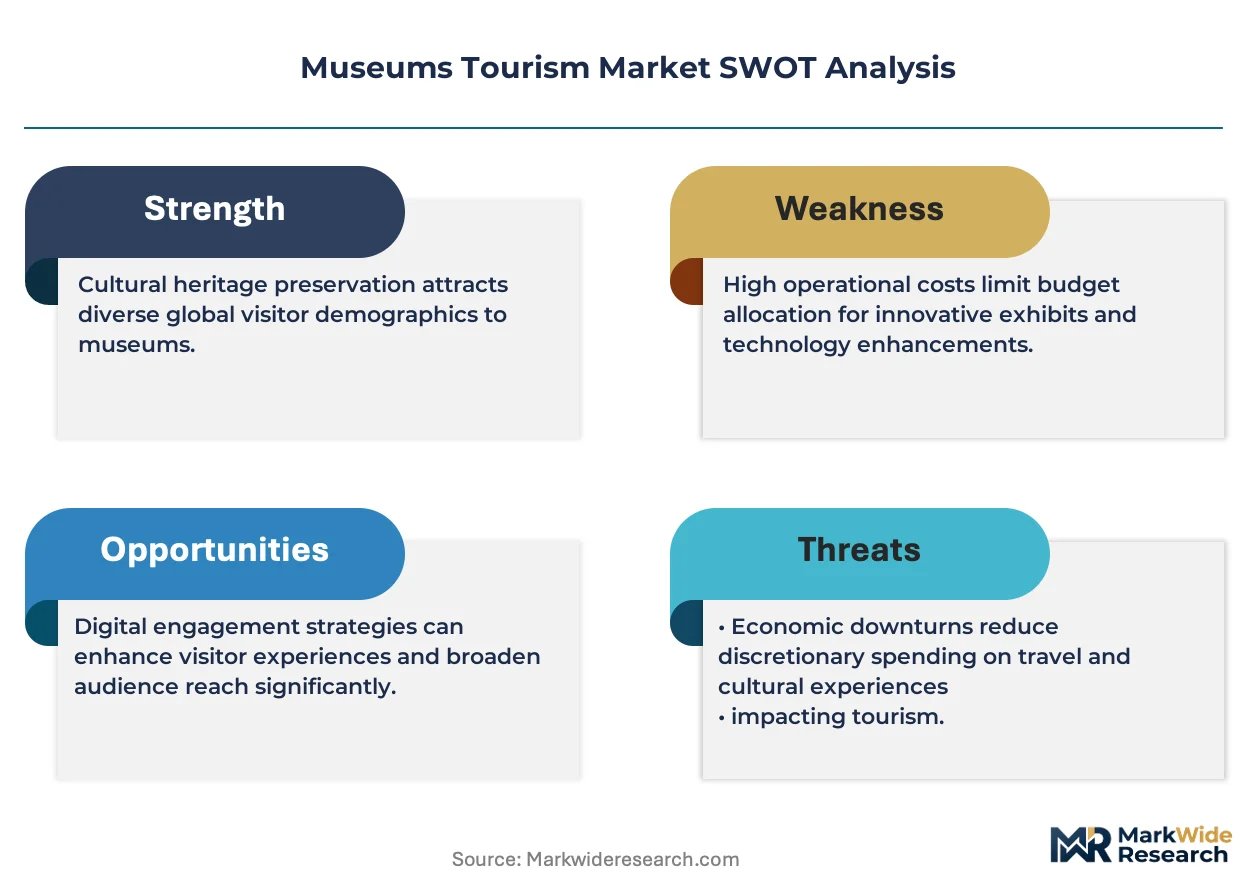
- Conservation-grade climate control energy costs:Specialized HVAC systems for artifact preservation face electricity price volatility, compressing operating margins.
- Curatorial talent scarcity:Specialized conservation and digital curation expertise concentrates in legacy institutions, limiting expansion capacity.
- Substitution by immersive entertainment:Location-based virtual reality experiences and digital heritage platforms divert younger visitor segments.
Strategic Opportunities
- Corporate incentive planners:Curator-access programming and private exhibition hours create premium-tier revenue streams beyond standard admissions.
- Extended reality convergence:Augmented reality overlays combined with haptic feedback systems enable remote collection exploration for immobile populations.
- India outbound cultural tourism:Rising discretionary spending among Indian middle-class households targets European museum circuits for experiential travel.
Industry Challenges
- Carbon accounting for cultural travel:Scope 3 emission tracking across visitor transportation complicates sustainability reporting and net-zero pledges.
- Digital-physical collection integration:Legacy catalog systems require expensive middleware development to unify artifact databases with immersive presentation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Museums Tourism Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Visitor Type: Domestic Tourists, International Tourists, Educational Groups, Senior Citizens Exhibition Type: Art Exhibitions, Historical Exhibits, Science Displays, Cultural Festivals Service Type: Guided Tours, Audio Guides, Virtual Tours, Workshops Ticketing Model: Single Entry, Membership Pass, Group Discounts, Free Entry Days |
| Companies Covered | Cuseum, Viator, Metropolitan Museum of Art, Martin Randall Travel, Abercrombie & Kent, National Geographic Society, Artisans Of Leisure, Arrangements Abroad, Museum of Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Museums Tourism Market Shifts & Advancements
Immersive digital infrastructure is compressing the boundary between physical artifact presentation and remote accessibility, forcing institutions to reconceptualize collection value delivery across distributed channels.
Extended reality hardware is modularizing exhibition design workflows. Curators at major metropolitan institutions deploy mixed-reality headsets to prototype gallery layouts without physical construction. This technology is modularizing capital deployment by enabling virtual testing of climate control placement, visitor flow patterns, and lighting configurations before committing to irreversible build-outs.
Americans with Disabilities Act enforcement by the Department of Justice has intensified physical and digital access litigation against cultural institutions. Settlement agreements now mandate multi-year accessibility roadmaps with court-appointed monitors. Smaller regional museums without compliance infrastructure face disproportionate legal exposure and insurance premium escalation.
Visitor purchasing patterns now favor bundled experiences over single-admission transactions. Travel intermediaries aggregate museum entry with hospitality and transportation into fixed-price cultural itineraries. This unbundling of traditional gate revenue is most visible in London, where platform-based booking has captured significant share from direct institutional sales channels.
Museums Tourism Market Segmentation
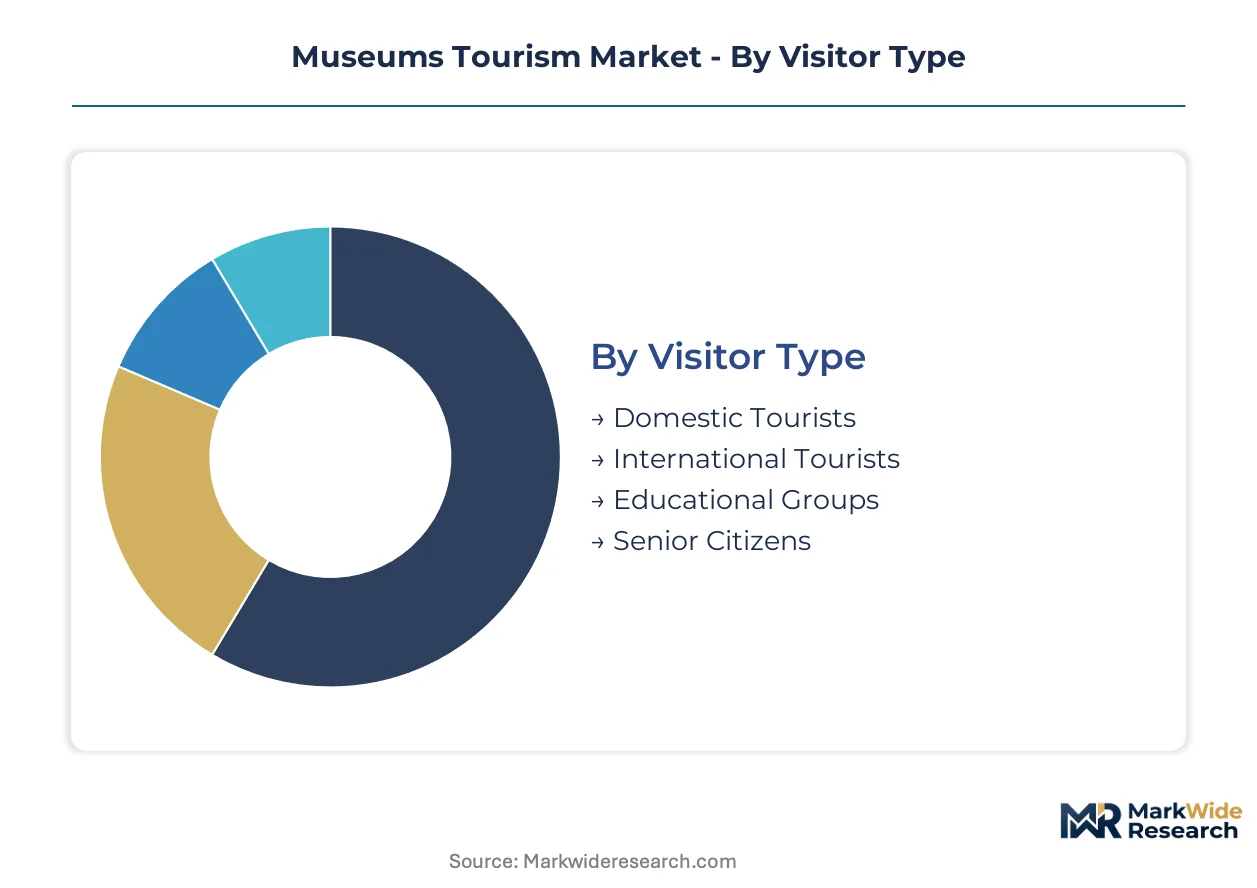
Museums tourism segmentation reveals divergent capital allocation patterns across visitor infrastructure, exhibition buildouts, and digital delivery systems. Each dimension carries distinct fixed-cost profiles that shape institutional investment prioritization and partnership strategies with travel intermediaries.
Visitor Type:
Capital intensity peaks with educational group infrastructure, requiring dedicated learning spaces, workshop equipment, and curriculum alignment personnel that domestic leisure visitation rarely demands.
- Domestic Tourists:Recurring weekend and holiday visitation patterns sustain baseline revenue across metropolitan institutions. Paris museums capture substantial repeat domestic traffic through rotating temporary exhibitions.
- International Tourists:Premium per-visitor spending concentrates in blockbuster destinations with global collection recognition. London's British Museum and New York's Metropolitan Museum anchor transatlantic cultural itineraries.
- Educational Groups:Specialized classroom facilities, hands-on conservation labs, and educator training programs require substantial upfront capital. Schools and universities in Germany and the Netherlands prioritize curriculum-integrated museum experiences, expanding weekday demand.
- Senior Citizens:Accessibility retrofitting and slower-paced programming necessitate barrier-free routing investments. This segment shows strong affinity for guided formats and off-peak scheduling.
Most installed capacity flows through International Tourists. Expansion is steepest in Educational Groups.
Exhibition Type:
Exhibition economics separate sharply between conservation-intensive permanent collections and high-turnover temporary programming with diverging margin profiles.
- Art Exhibitions:Climate-controlled galleries with specialized HVAC and lighting systems command the highest capital deployment per square meter. Premium ticketing in Paris, London, and New York validates these investments.
- Historical Exhibits:Artifact preservation protocols and security infrastructure drive comparable fixed costs with longer amortization periods. Rome and Athens institutions leverage archaeological collection depth.
- Science Displays:Interactive exhibit maintenance and technology refresh cycles create recurring capital demands. This segment attracts family visitation clusters during school holiday periods.
- Cultural Festivals:Temporary infrastructure and programming staff scale flexibly with seasonal demand. Indian and Southeast Asian institutions deploy festival formats to concentrate visitation.
Revenue concentration sits with Art Exhibitions. Science Displays are climbing the fastest among exhibition formats.
Service Type:
Service delivery stratifies between labor-intensive guided operations and technology-leveraged virtual platforms with radically different scalability economics.
- Guided Tours:Trained docent corps and multilingual staffing constitute ongoing operational expenditure with limited leverage. Premium curator-access programming in private settings commands substantial price premiums.
- Audio Guides:Hardware procurement and content production amortize across high visitor volumes. This format shows declining share as smartphone substitution accelerates.
- Virtual Tours:Immersive digital infrastructure including 3D photogrammetry and streaming platforms requires substantial technology capital. EU Web Accessibility Directive compliance accelerates deployment across European institutions.
- Workshops:Dedicated studio spaces and consumable materials inventory support hands-on learning. Educational group conversion rates for workshop add-ons exceed leisure visitor attachment.
Volume leadership belongs to Guided Tours. Virtual Tours show the steepest expansion trajectory among service formats.
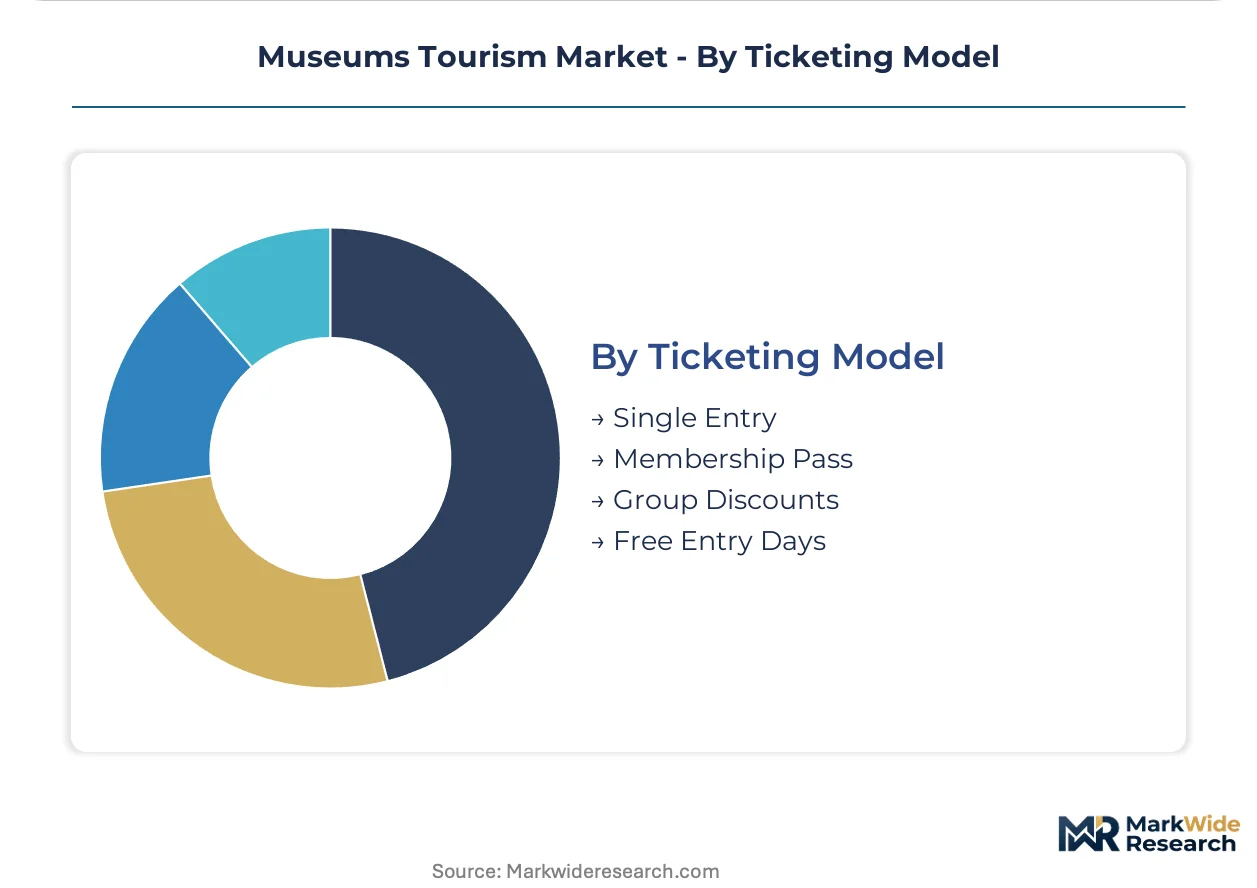
Ticketing Model:
Revenue predictability and cash flow timing diverge materially between transactional single-entry sales and recurring membership ecosystems.
- Single Entry:Transactional revenue without visitor data capture limits relationship building and repeat visitation engineering. Platform intermediaries increasingly aggregate this demand away from direct institutional channels.
- Membership Pass:Recurring revenue streams and visitor identity data enable personalized programming and retail targeting. Major metropolitan museums in the US and UK anchor premium membership tiers with exclusive access benefits.
- Group Discounts:Volume-commitment pricing for educational and corporate segments sacrifices per-capita yield for occupancy smoothing and ancillary conversion.
- Free Entry Days:Public mission fulfillment with donor or government subsidy replacement of foregone gate revenue. Smithsonian institutions in Washington DC operate permanently free entry models.
Membership Pass systems capture the most predictable revenue streams. Group Discounts are gaining share fastest as educational visitation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France captures higher per-visitor museum spending than Italy, while the United Kingdom leads in digital accessibility compliance investment. Cultural capital clustering in specific metropolitan areas drives divergent infrastructure development patterns across national markets.
United States
Blockbuster exhibition programming and membership ecosystems anchor revenue generation at major metropolitan institutions. The Americans with Disabilities Act, enforced by the Department of Justice, mandates multi-year accessibility roadmaps with court-appointed monitors. New York City's museum cluster concentrates global collection recognition and transatlantic cultural itinerary anchoring.
United Kingdom
Platform-based booking intermediaries capture significant share from direct institutional sales channels through bundled cultural itineraries. The Equality Act and associated accessibility frameworks require captioning and barrier-free routing upgrades. London's South Kensington museum district enables cross-institutional ticketing partnerships and concentrated visitor flow management.
France
Premium ticketing for art exhibitions validates substantial capital deployment per square meter in climate-controlled galleries. EU Web Accessibility Directive compliance accelerates tactile interface and digital infrastructure deployment. Parisian institutions leverage dense museum clustering for itinerary bundling and rotating temporary exhibition strategies.
Germany
Curriculum-integrated museum experiences expand weekday demand from schools and universities prioritizing experiential learning. Federal accessibility standards align with EU directives to mandate inclusive design investments. Berlin's museum island concentration supports educational group infrastructure and specialized learning space development.
India
Rising discretionary spending among middle-class households targets European museum circuits for experiential travel. The country's national tourism promotion programs support outbound cultural tourism growth. Mumbai and Delhi institutions develop festival formats to concentrate domestic visitation during seasonal demand windows.
Museums Tourism Market Competitive Landscape
United States institutions anchor one tier; United Kingdom and European specialists hold differentiated positions in luxury cultural itineraries. The vendor base stratifies across platform intermediaries, heritage institutions, and ultra-luxury tour operators with distinct margin profiles. Three archetypes dominate: technology-enabled booking platforms, membership-driven metropolitan museums, and curator-access luxury specialists. Competitive moves concentrate on digital infrastructure partnerships and exclusive programming rights acquisition.
Within the platform intermediary tier, Viator exemplifies scale-driven inventory aggregation across heritage institutions worldwide. Metropolitan Museum of Art occupies a position representing membership ecosystem and blockbuster exhibition anchoring. Abercrombie & Kent sit within the ultra-luxury tier, exemplifying curator-access programming differentiation. These three anchors illustrate the structural segmentation between technology scale, institutional prestige, and bespoke service depth.
| Leading Market Players |
|---|
| Cuseum |
| Viator |
| Metropolitan Museum of Art |
| Martin Randall Travel |
| Abercrombie & Kent |
| National Geographic Society |
| Artisans Of Leisure |
| Arrangements Abroad |
| Museum of Science |
| Others |
Supply & Pricing Matrix
Captive integration of conservation-grade climate control systems anchors both capital deployment intensity and premium ticketing power for major metropolitan institutions. Museum operators that own specialized HVAC infrastructure in-house command pricing leverage through artifact preservation guarantees that outsourced facility management cannot replicate.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for educational group programming as curriculum-integrated experiences expand. Three-tier pricing structure across premium curator-access, standard timed-entry, and economy virtual-only levels captures divergent willingness-to-pay. Price differentiation hinges on exclusivity tier and after-hours access privileges. Cost compression in standard admission channels is intensifying because platform intermediaries aggregate demand and capture margin. Educational buyers exhibit highest price sensitivity; corporate incentive planners show lowest.
Supply Chain Analysis
Domestic-content mandates under the EU Web Accessibility Directive are reshaping sourcing for tactile interface hardware and captioning software deployment. Exhibit fabrication concentrates in Italy, Germany, and France. Specialized conservation materials draw from Belgian textile suppliers and Dutch climate-control component manufacturers. Supply chain risk centers on single-source vulnerability for archival-grade display cases. Distribution runs through institutional procurement teams and travel intermediary platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Museums tourism represents a late-cycle quality story as visitor purchasing patterns favor bundled experiences with hospitality and transportation over single-admission transactions.
For Market Incumbents: Anticipate substitution pressure from immersive entertainment platforms by deepening curator-access programming exclusivity. Defend against platform intermediary margin capture through direct membership ecosystem investment. Prioritize EU Web Accessibility Directive compliance infrastructure as a competitive moat against smaller regional competitors facing disproportionate legal exposure. For New Entrants and Emerging Players: Enter via white-space targeting of Indian outbound cultural tourism circuits and underserved regional museum digitization partnerships. India's rising middle-class discretionary spending offers the most penetrable geography. Pursue go-to-market positioning as extended reality convergence specialists for immobile population access. For Investors and Strategic Acquirers: Roll-up economics work for regional museum networks because digital infrastructure standardization creates platform leverage across dispersed physical assets. Five-to-ten year viability favors membership-driven metropolitan institutions with recurring revenue streams. Target acquisition archetype: mid-tier institutions with undermonetized collection depth. Watch for inflection in carbon accounting rule finalization for cultural travel as signal for sustainability-linked capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Membership Ecosystem Expansion | Recurring revenue streams at Metropolitan Museum of Art validate personalized programming investment. |
| Extended Reality Infrastructure Deployment | EU Web Accessibility Directive compliance accelerates 3D photogrammetry and haptic system adoption. |
| Curator-Access Programming Development | Abercrombie & Kent demonstrates premium pricing power through exclusive exhibition hour arrangements. |
| Educational Group Partnership Formalization | German and Dutch curriculum alignment creates predictable weekday demand smoothing. |
| Platform Intermediary Margin Defense | London's direct channel recovery shows institutional control over bundled itinerary pricing. |
Research Methodology
Coverage spans North America, Western Europe, and South Asia, with primary inputs from each region synthesized through structured protocols. Museum directors, educational curriculum coordinators, travel intermediary platform managers, and conservation technology suppliers provided qualitative ground-truth. Secondary validation drew from EU Web Accessibility Directive implementation filings, Americans with Disabilities Act settlement agreements, Smithsonian annual reports, and tourism board visitation statistics. Bottom-up institution-level modeling triangulated against top-down market sizing.
Granularity-level framing applied visitor type, exhibition format, service delivery mode, and ticketing model as core segmentation dimensions. CAGRs derived from trend extrapolation of educational group expansion rates, virtual tour adoption curves, and membership conversion benchmarks. Analysis window projections incorporated climate control energy cost volatility assumptions and curatorial talent scarcity constraints.
Inputs from regulatory filing databases and institutional annual reports were available through the study window; gaps in real-time platform intermediary transaction data introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding EU directive enforcement timelines and Indian outbound tourism growth trajectories. Carbon accounting standardization delays and immersive entertainment substitution acceleration represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
South Africa Faith-Based Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market
Destination Management and Attractions
Music Tourism Market