
 India MICE Tourism Market | 2026-2036
India MICE Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
India MICE Tourism Market Foresight
The PLI scheme for tourism and hospitality is rebalancing capital deployment toward large-format convention infrastructure. Indian Hotels Company Ltd. anchors its MICE portfolio through heritage property conversions in metro clusters. Marriott International India extends its ballroom inventory across tier-1 cities to capture corporate seminar flows. ITC Hotels differentiates through integrated convention catering and in-house audiovisual capabilities.
India MICE tourism encompasses meetings, incentives, conferences, and exhibitions delivered through purpose-built venues, hotels, and temporary infrastructure, requiring contiguous floor plates exceeding 5,000 square meters, redundant power systems, and customs facilitation for international exhibitors. The segment serves corporate knowledge exchange, trade promotion, and employee motivation programs. Conference and exhibition formats dominate revenue generation due to recurring corporate procurement cycles and trade association calendars. Incentive travel exhibits faster structural expansion as pharmaceutical and IT sectors deploy reward programs for performance cohorts. Corporate clients represent the deepest margin pool given multi-year venue contracts and integrated service bundling across catering and transportation.
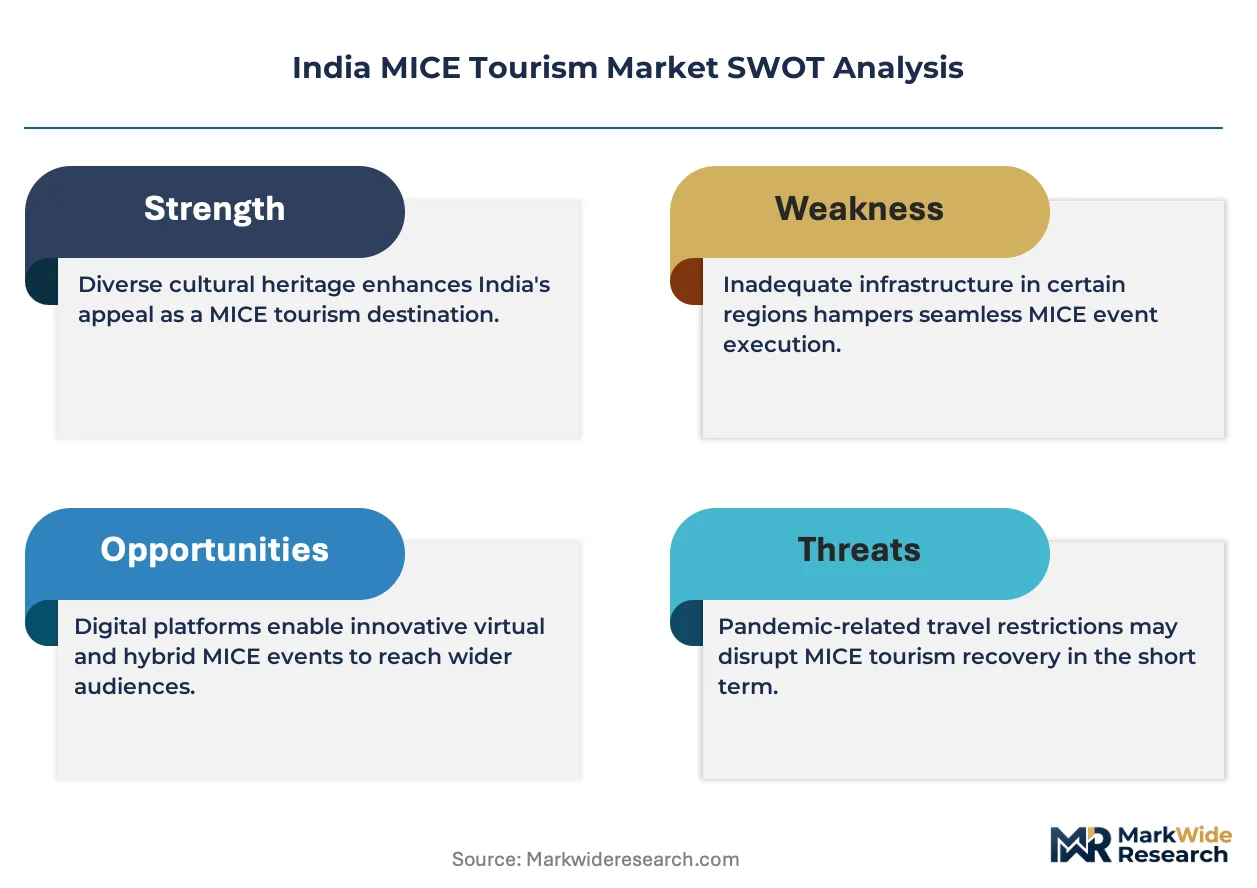
Ministry of Tourism guidelines, state-level MICE policies, and BIS facility standards collectively shape venue certification and international bidding eligibility for Indian convention centers. State governments compete through capital subsidies and single-window clearance mechanisms to attract national association events. Stakeholders must monitor which states operationalize integrated convention districts before competitor destinations lock in recurring event calendars.
Market Dynamics
State-level MICE policy competition is compressing venue development timelines across Maharashtra, Karnataka, and Delhi NCR as capital subsidies and single-window clearances accelerate convention infrastructure deployment.
Growth Catalysts
- PLI scheme for tourism and hospitality:Production-linked incentives are redirecting institutional capital toward large-format convention centers with contiguous floor plates exceeding 5,000 square meters.
- Pharmaceutical sector conventions:Tier-1 cities face sustained venue demand from recurring corporate procurement cycles and trade association calendars in the life sciences vertical.
- BIS facility standards:Venue certification requirements are elevating infrastructure quality benchmarks and unlocking international bidding eligibility for Indian convention centers.
Market Restraints
- Redundant power system capex:Convention centers require dual-feed electrical infrastructure and backup generation capacity that extends project payback periods.
- Customs facilitation bottlenecks:International exhibitors face procedural friction at Indian ports for temporary import of display equipment and promotional materials.
- Tier-2 city infrastructure gaps:Exhibition complexes outside Maharashtra, Karnataka, and Delhi NCR lack contiguous floor plates and integrated transportation connectivity.
Strategic Opportunities
- Gujarat convention district development:Integrated exhibition complexes near Ahmedabad and Surat remain underpenetrated relative to western India corporate demand density.
- Incentive travel expansion:IT sector performance reward programs represent structural white space with faster margin expansion than conference formats.
- Heritage property conversions:Rajasthan and Kerala palace hotels offer differentiated MICE positioning through adaptive reuse of cultural assets.
Industry Challenges
- Audiovisual technician scarcity:In-house production capabilities require specialized labor pools that remain concentrated in Mumbai, Bengaluru, and Delhi NCR.
- Event permitting fragmentation:Single-window clearance mechanisms vary by state, creating operational complexity for multi-city corporate event series.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India MICE Tourism Market |
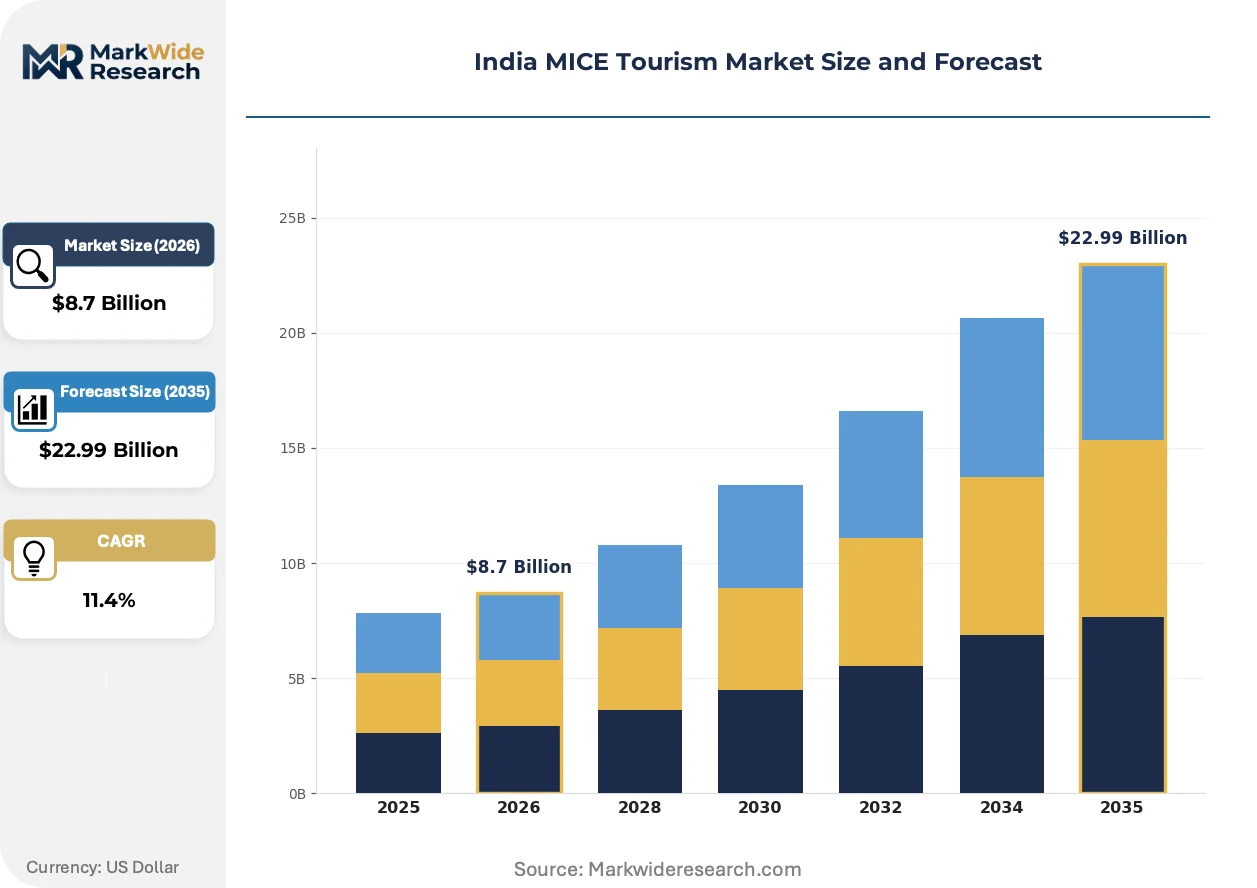
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Conference, Exhibition, Incentive, Seminar Booking Channel: Direct, Travel Agency, Online Platform, Corporate Booking Client Type: Corporates, Government, Associations, Non-profits Service Type: Venue Rental, Catering, AV Services, Transportation |
| Companies Covered | Hyatt Hotels India, Travel Corporation (India) Ltd. (TCI), Indian Hotels Company Ltd. (IHCL), FCM Travel Solutions, Cox and Kings Ltd, Marriott International India, ITC Hotels, Wizard Events, Accor India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India MICE Tourism Market Shifts & Advancements
Digital infrastructure convergence is compressing service delivery models across Indian MICE venues as hybrid event formats become standard in corporate procurement specifications.
Immersive audiovisual systems are integrating holographic presentation capabilities and real-time translation feeds into ballroom infrastructure. Pharmaceutical and IT sector clients are adopting these platforms for multi-site town halls and product launches. This technology is integrating previously siloed in-person and virtual attendee management into unified production workflows.
State-level MICE policies are mandating single-window clearance mechanisms and capital subsidy frameworks for convention center developers. Maharashtra and Karnataka have operationalized these structures fastest, compressing project approval timelines. Tier-1 city venue operators are responding by locking in multi-year corporate contracts before competitor states operationalize comparable incentive packages.
Corporate procurement of MICE services is consolidating around multi-year venue contracts with integrated catering and transportation bundling. Independent event management agencies are losing share to hotel-direct relationships and in-house convention teams. This concentration is most visible in Delhi NCR and Mumbai, where Fortune 500 subsidiaries and domestic conglomerates dominate event spending.
India MICE Tourism Market Segmentation
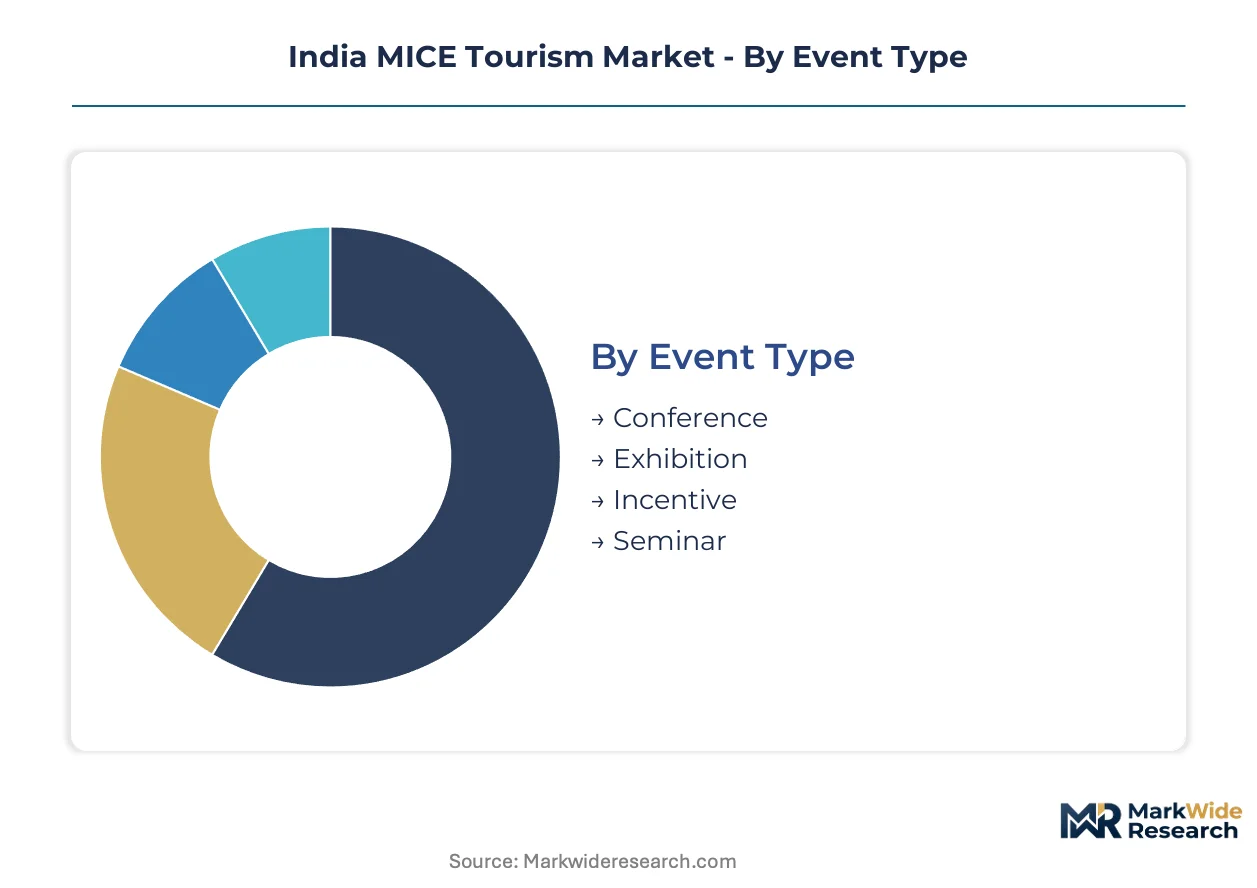
India MICE tourism segmentation reveals distinct procurement patterns across event formats and client categories. Corporate buyers prioritize integrated service bundling while government tenders emphasize compliance certification. Understanding these segment boundaries enables precise capacity allocation and margin capture.
Event Type:
Conference and exhibition formats operate as standalone revenue anchors with dedicated infrastructure requirements, while incentive and seminar segments embed within broader corporate travel programs with lighter fixed asset dependency.
- Conference:Multi-day knowledge exchange formats requiring contiguous floor plates exceeding 5,000 square meters, redundant power systems, and simultaneous translation infrastructure. Demand concentrates in Mumbai and Delhi NCR pharmaceutical sector gatherings driven by CDSCO regulatory update cycles and product launch calendars.
- Exhibition:Trade show formats with temporary booth infrastructure, customs facilitation for international exhibitors, and freight handling capabilities. Maharashtra and Karnataka venues capture recurring industry association events through operationalized single-window clearance mechanisms.
- Incentive:Employee reward travel with heritage property conversion potential in Rajasthan and Kerala.
- Seminar:Single-day corporate training formats with lower venue specification thresholds and hotel ballroom dependency.
Volume placements concentrate in Conference; the faster expansion belongs to Incentive.
Booking Channel:
Direct and corporate booking channels bypass intermediary margins and enable multi-year contract structures, while travel agency and online platform segments introduce commission layers and shorter commitment windows.
- Direct:Venue-operator relationships eliminating agency commissions and enabling customized service bundling across catering and transportation. ITC Hotels and Marriott International India leverage this channel for Fortune 500 subsidiary accounts in tier-1 cities.
- Corporate Booking:Centralized procurement systems with negotiated rate cards and consolidated billing across multi-city event series. Delhi NCR conglomerates dominate this segment through in-house convention teams displacing independent event management agencies.
- Travel Agency:Intermediary channel with destination management expertise for international inbound MICE groups.
- Online Platform:Digital marketplaces with transparent pricing and short-lead transaction capability.
Revenue concentration favors Direct; Corporate Booking climbs the fastest as procurement centralization accelerates.
Client Type:
Corporate and association clients generate recurring revenue streams with multi-year planning horizons, while government and non-profit segments exhibit tender-driven procurement with compliance-heavy documentation requirements.
- Corporates:Pharmaceutical and IT sector accounts with performance reward programs and shareholder meeting obligations. These clients deliver the deepest margin pool through integrated service contracts spanning venue, catering, and ground transportation.
- Associations:Industry body events with rotating host city selection and membership-funded budgets. Medical and engineering associations anchor recurring calendars in Bengaluru and Hyderabad.
- Government:Ministry of Tourism and state administration events with BIS facility standard compliance requirements.
- Non-profits:NGO and foundation gatherings with constrained budgets and off-peak scheduling flexibility.
Contract value peaks with Corporates; Associations gain share fastest through sector-specific event multiplication.
Service Type:
Venue rental and catering function as standalone profit centers with dedicated asset bases, while AV services and transportation embed as bundled components with third-party subcontracting dependency.
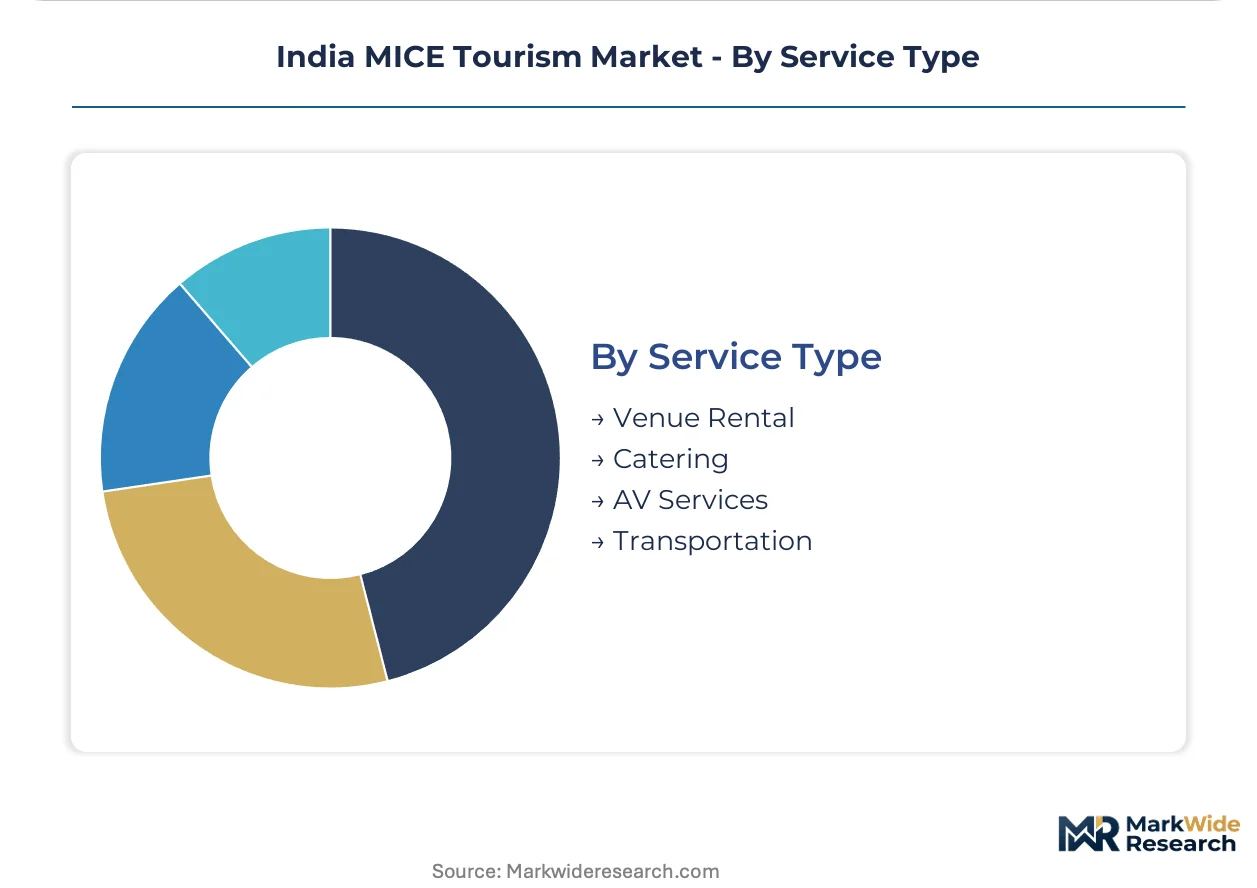
- Venue Rental:Purpose-built convention center and hotel ballroom inventory with contiguous floor plate specifications and redundant electrical infrastructure. Capital subsidies under the PLI scheme for tourism and hospitality redirect institutional investment toward large-format developments.
- Catering:In-house kitchen capacity and integrated F&B operations with volume scale advantages. ITC Hotels differentiates through convention-specific catering capabilities with audiovisual integration.
- AV Services:Holographic presentation and real-time translation technology with technician scarcity concentrated in Mumbai, Bengaluru, and Delhi NCR.
- Transportation:Ground logistics and airport transfer coordination with fleet subcontracting networks.
Margin contribution centers on Venue Rental; AV Services expands most quickly as hybrid format adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Maharashtra and Gujarat accelerate venue concentration through capital subsidy frameworks and single-window clearance mechanisms that compress project approval timelines.
Maharashtra
Pharmaceutical sector conventions drive sustained demand in Mumbai and Pune clusters. The state MICE policy operationalizes capital subsidies for convention centers exceeding 5,000 square meters of contiguous floor plate. Mumbai's exhibition complexes capture recurring medical association events through streamlined CDSCO regulatory coordination.
Karnataka
IT sector incentive travel programs and technology conferences anchor Bengaluru's venue utilization. State-level single-window clearance mechanisms reduce permitting friction for international exhibitors. The Bengaluru International Exhibition Centre expands capacity to capture rotating industry association calendars from Hyderabad and Chennai.
Delhi NCR
Government sector events and Fortune 500 subsidiary shareholder meetings concentrate in Gurugram and Noida convention infrastructure. Ministry of Tourism guidelines mandate BIS facility standards for international bidding eligibility. The India Expo Centre and Mart in Greater Noida locks in multi-year corporate contracts through integrated catering and transportation bundling.
Gujarat
Underpenetrated exhibition capacity near Ahmedabad and Surat presents white space relative to western India corporate demand density. The state MICE policy extends capital subsidies to convention district developments with redundant power infrastructure. GIFT City integrated complexes target financial sector conferences through customs facilitation protocols.
Rajasthan
Heritage property conversions in Jaipur and Udaipur differentiate incentive travel positioning through adaptive reuse of palace hotels. State tourism policies incentivize MICE-specific renovations of cultural assets. The Jaipur Exhibition and Convention Centre competes for pharmaceutical sector reward programs through heritage-experience bundling.
India MICE Tourism Market Competitive Landscape
Metro cluster operators anchor one tier; regional venue specialists hold differentiated positions in heritage and tier-2 markets. The vendor base organizes around three strategic archetypes: integrated hotel-convention portfolios, standalone exhibition complex operators, and incentive travel destination management companies. Consolidation pressures favor multi-year corporate contract structures over transactional agency relationships. Capacity expansion and in-house audiovisual capability development represent dominant competitive moves.
Within the integrated hospitality tier, Indian Hotels Company Ltd., Marriott International India, and ITC Hotels exemplify archetype positioning through metro cluster ballroom inventory and convention-specific service bundling. These operators occupy positions that leverage heritage property conversions and in-house production capabilities to capture corporate procurement centralization. Hyatt Hotels India and Accor India represent additional scale-driven anchors in tier-1 city venue markets.
| Leading Market Players |
|---|
| Hyatt Hotels India |
| Travel Corporation (India) Ltd. (TCI) |
| Indian Hotels Company Ltd. (IHCL) |
| FCM Travel Solutions |
| Cox and Kings Ltd |
| Marriott International India |
| ITC Hotels |
| Wizard Events |
| Accor India |
| Others |
Supply & Pricing Matrix
Backward integration into in-house catering and audiovisual production anchors both supply position and pricing power for tier-1 hotel operators. PLI scheme subsidies for tourism infrastructure compress capital recovery timelines, allowing integrated operators to undercut standalone venue bids while preserving margin.
Pricing Analysis
Short lead-time bookings command 15-25% premiums over contracted annual rates as pharmaceutical sector events face rigid CDSCO regulatory calendars. Three-tier pricing structure across premium heritage properties, standard convention centers, and economy hotel ballrooms differentiates by contiguous floor plate specifications and redundant power certification. Cost compression in economy tier intensifies because of AV technician scarcity concentrated in Mumbai, Bengaluru, and Delhi NCR. Government tenders exhibit highest price sensitivity due to BIS compliance documentation requirements; corporate direct accounts show lowest sensitivity given bundled service contracts.
Supply Chain Analysis
Regional distribution centers for temporary exhibition infrastructure cluster in Mumbai, Delhi NCR, and Bengaluru, with hub-and-spoke freight patterns radiating to secondary venues. Equipment sourcing draws from China for LED display systems, Germany for simultaneous translation hardware, and domestic fabrication for modular booth structures. Single-source vulnerability concentrates in holographic projection technology imports. Distribution runs through venue-operator direct channels, displacing independent event management agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate procurement centralization is forcing consolidation as multi-year venue contracts displace transactional agency relationships. Weaker players lacking integrated catering or in-house audiovisual capabilities face margin compression.
For Market Incumbents: Hedge against technician scarcity by locking Bengaluru and Delhi NCR production talent through captive training partnerships. Expand contiguous floor plate inventory in Gujarat before state-level MICE policy subsidies attract competitor capital. PLI scheme access represents the critical lever for defending position against heritage property conversion entrants. For New Entrants and Emerging Players: Hybrid event platform integration offers a technology-first wedge into IT sector incentive travel programs, where corporate procurement seeks unified virtual-physical attendee management. Target Rajasthan palace hotel adaptive reuse for pharmaceutical reward travel white space. Lead with GIFT City customs facilitation protocols to differentiate from Maharashtra and Karnataka venue congestion. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated hospitality portfolios seeking metro cluster ballroom density. Five-to-ten year viability hinges on state-level MICE policy operationalization speed. Monitor which states achieve single-window clearance implementation before competitor destinations lock recurring association calendars.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Property Conversion | Rajasthan and Kerala palace hotels capture pharmaceutical incentive travel through differentiated cultural asset positioning. |
| In-House AV Capability Buildout | Bengaluru and Delhi NCR technician pools reduce third-party subcontracting dependency for hybrid event production. |
| Multi-Year Corporate Contract Lock | Fortune 500 subsidiaries in Delhi NCR displace independent agencies through integrated catering and transportation bundling. |
| Gujarat Convention District Development | Ahmedabad and Surat exhibition complexes address underpenetrated western India corporate demand density. |
| Single-Window Clearance Operationalization | Maharashtra and Karnataka compress permitting timelines to attract rotating national association event calendars. |
Research Methodology
Multi-period observation of state-level MICE policy implementation, PLI scheme capital deployment, and pharmaceutical sector event calendars anchored the trend analysis, supplemented by interviews with convention center operators, hotel MICE directors, event procurement managers at IT and pharmaceutical firms, and state tourism board officials. Secondary validation drew from Ministry of Tourism guidelines, BIS facility standards documentation, CDSCO regulatory update cycles, and industry association event schedules. Bottom-up venue capacity assessments triangulated against top-down corporate travel spending estimates.
Input-output matrix modeling connected event type segmentation, client procurement channel preferences, and service type margin structures across the projection horizon. CAGRs derived from capacity expansion timelines, corporate incentive program adoption curves, and heritage property conversion permitting velocities. Forecast inputs incorporated PLI scheme subsidy disbursement schedules and state-level single-window clearance operationalization status.
Forecast precision tightens around the base case; tail outcomes carry wider variance under customs facilitation bottleneck persistence or accelerated tier-2 city infrastructure development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Geotourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Industrial Tourism Market
Destination Management and Attractions
Literary Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market