
 UAE Faith Based Tourism Market | 2026-2036
UAE Faith Based Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Faith Based Tourism Market Analytics
Market Context
Online booking platforms and faith-specialized travel agencies is tilting toward curated pilgrimage packages that bundle flights, lodging, and guided worship experiences. Emirates leverages its Dubai hub dominance to capture transit pilgrims en route to Saudi Arabia's holy sites. Etihad Airways anchors Abu Dhabi's positioning as an alternative gateway for religious travelers from South Asia and Southeast Asia. Saifco Travel & Tourism specializes in end-to-end Umrah logistics, controlling ground transportation and accommodation procurement across the emirates.
Technical Definition and Segments
Faith based tourism encompasses journeys undertaken primarily for religious devotion, spiritual enrichment, or participation in sacred rituals, typically involving structured itineraries with designated prayer facilities, halal-certified services, and clergy-guided programming. The sector functions as a specialized hospitality vertical where service providers coordinate visa procurement, gender-appropriate accommodations, and dietary compliance alongside conventional travel logistics. Pilgrimages within the event type category command the deepest margin pools due to high repeat visitation and advance booking patterns. Accommodation services under the service type dimension sustain premium pricing during Ramadan and Hajj seasons when occupancy restrictions apply. The visitor type split shows families generating the longest average stays, while solo travelers from Indonesia and Pakistan represent the fastest-growing inbound segment.
Regulatory Framework
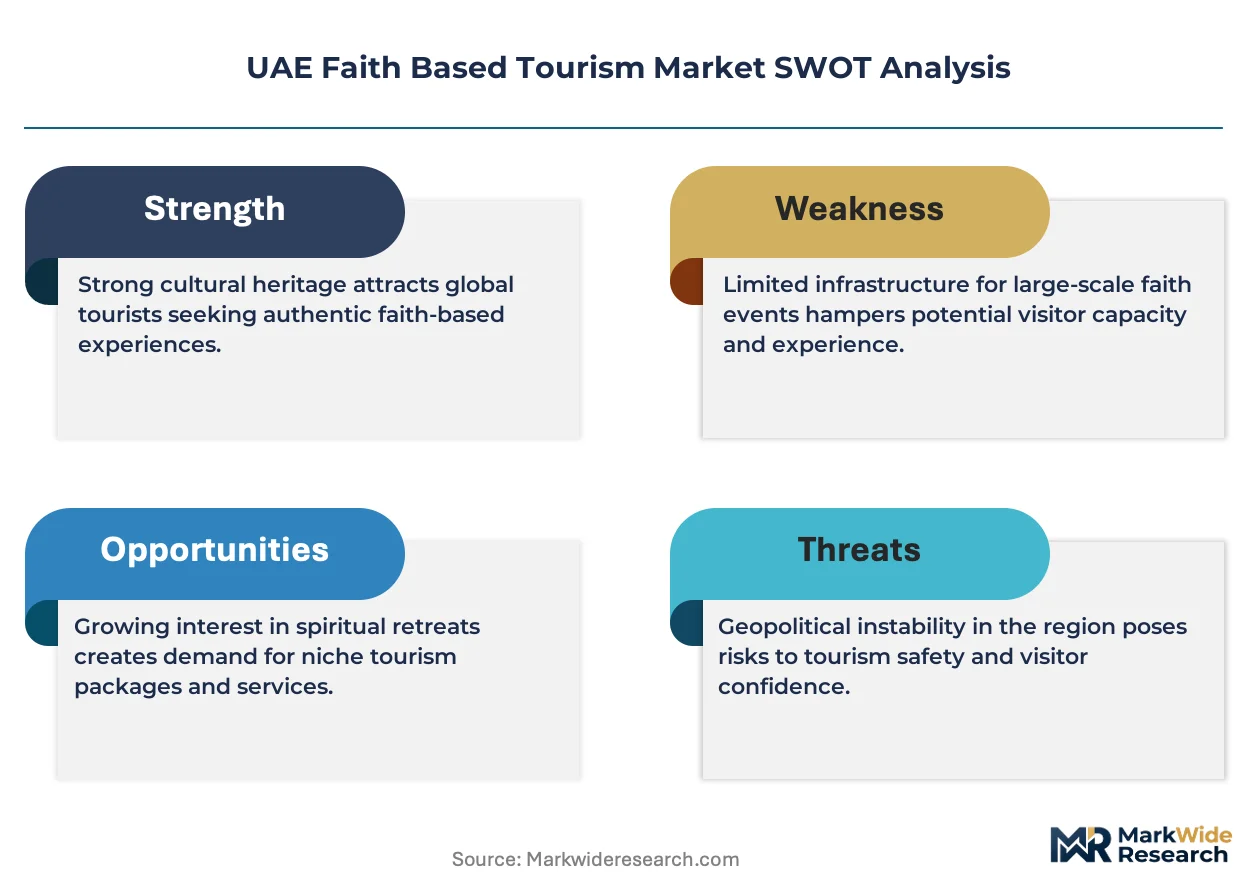
MOHAP oversees halal certification standards for hospitality providers serving religious tourists, while the UAE's General Authority of Islamic Affairs and Endowments regulates sermon content and prayer leader qualifications at tourism-facing mosques. Dubai's Department of Economy and Tourism enforces accommodation grading that weights proximity to prayer facilities and halal dining availability. Stakeholders must monitor evolving visa reciprocity agreements between the UAE and source markets with large Muslim populations.
Market Dynamics
Visa facilitation frameworks from MOHAP and the General Authority of Islamic Affairs and Endowments are compressing entry timelines for religious visitors, redirecting pilgrimage flows through Dubai and Abu Dhabi as staging hubs for Saudi-bound travelers.
Growth Catalysts
- Umrah Logistics Integration:End-to-end package bundling across ground transport, halal lodging, and guided worship experiences is pulling repeat visitation from South Asian source markets.
- MOHAP Certification Standards:Unified halal hospitality grading is reducing buyer search friction and enabling premium pricing for certified properties during Ramadan and Hajj windows.
- Transit Hub Positioning:Emirates and Etihad network density is capturing en-route pilgrims from Indonesia and Pakistan who previously routed through alternative Gulf gateways.
Market Restraints
- Saudi Visa Dependency:Pilgrimage operators remain tethered to Saudi Ministry of Hajj and Umrah quota allocations, creating volume ceilings independent of UAE infrastructure capacity.
- Seasonal Occupancy Compression:Lodging providers face 70-80% revenue concentration in 8-10 weeks annually, straining fixed-cost absorption during off-peak months.
- Clergy Qualification Bottlenecks:General Authority of Islamic Affairs and Endowments sermon-content regulations limit the pool of approved prayer leaders for tourism-facing mosques.
Strategic Opportunities
- Sharjah Cultural Corridor:Underdeveloped heritage infrastructure in the emirate's central district offers first-mover positioning for Islamic museum and manuscript tourism.
- Digital Visa-on-Arrival:MOHAP pilot programs for instant religious-visitor clearance could compress booking-to-arrival cycles from weeks to hours.
- Multi-Destination Packages:Bundling UAE cultural stops with Jordanian and Turkish sacred sites is opening new itinerary architectures beyond Saudi-centric flows.
Industry Challenges
- Gender-Segregation Infrastructure:Property retrofit costs for prayer-space partitioning and accommodation zoning are inflating capex requirements for mid-tier hospitality assets.
- Halal Supply Chain Verification:Cross-border ingredient tracing for F&B operations is extending procurement cycles and complicating menu standardization across emirate properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Faith Based Tourism Market |
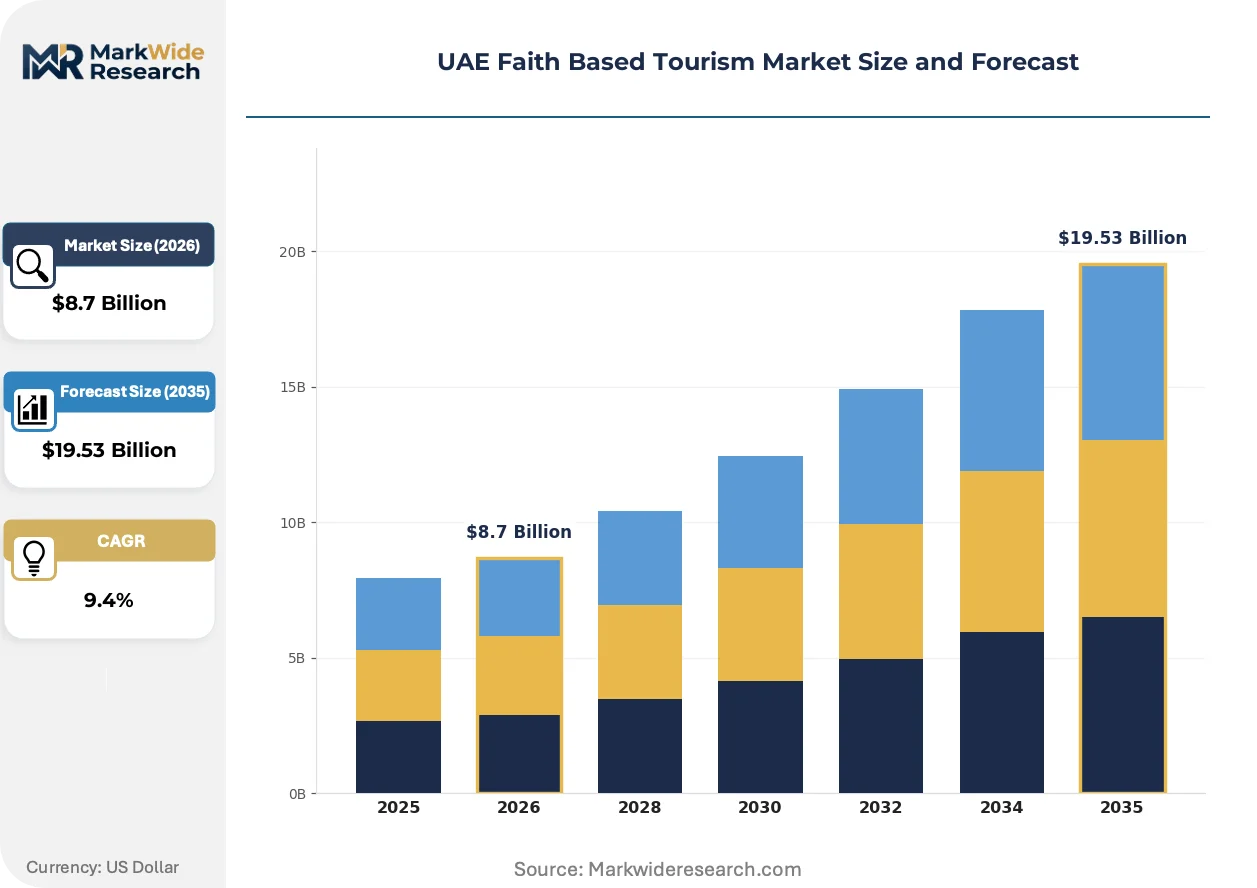
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Pilgrimages, Conferences, Retreats, Festivals Travel Purpose: Spiritual Growth, Cultural Exploration, Education, Religious Observance Service Type: Accommodation, Guided Tours, Transportation, Meal Services Visitor Type: Families, Solo Travelers, Groups, Religious Leaders |
| Companies Covered | Emirates, Etihad Airways, Air Arabia, Burj Al Arab, Dubai Palm Hotel, Rotana, Saifco Travel & Tourism, Expedia Group, Globus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Faith Based Tourism Market Evolving Landscape
Digital pilgrimage platforms and biometric border processing are compressing the traditional travel-agency intermediary layer, while curated worship experiences displace generic religious tourism packages.
AI-powered itinerary customization engines are rendering obsolete the static package model that dominated faith-based travel for decades. Pilgrimage operators from Indonesia and Pakistan are adopting these tools at accelerating rates, compressing margin capture for traditional agencies that lack data-driven personalization capabilities. The structural consequence is a shift toward direct-to-pilgrim booking relationships that bypass legacy distribution layers.
MOHAP's expanded halal certification tiers for hospitality providers are tightening compliance thresholds for prayer-space proximity and dietary verification. Properties failing to meet upgraded standards face exclusion from government-preferred supplier lists for religious tourism contracts. The mid-tier lodging segment is responding with accelerated facility retrofits to maintain package-operator partnerships.
Family-unit bookings are displacing individual pilgrimage arrangements as the dominant transaction architecture, particularly among Pakistani and Bangladeshi source markets. Group coordinators and extended-family liaisons are consolidating decision authority, compressing the number of touchpoints operators must maintain. This concentration is most visible in Dubai's Deira district, where specialized agencies now structure multi-generational packages with embedded childcare and elder-accessibility features.
UAE Faith Based Tourism Market Segmentation
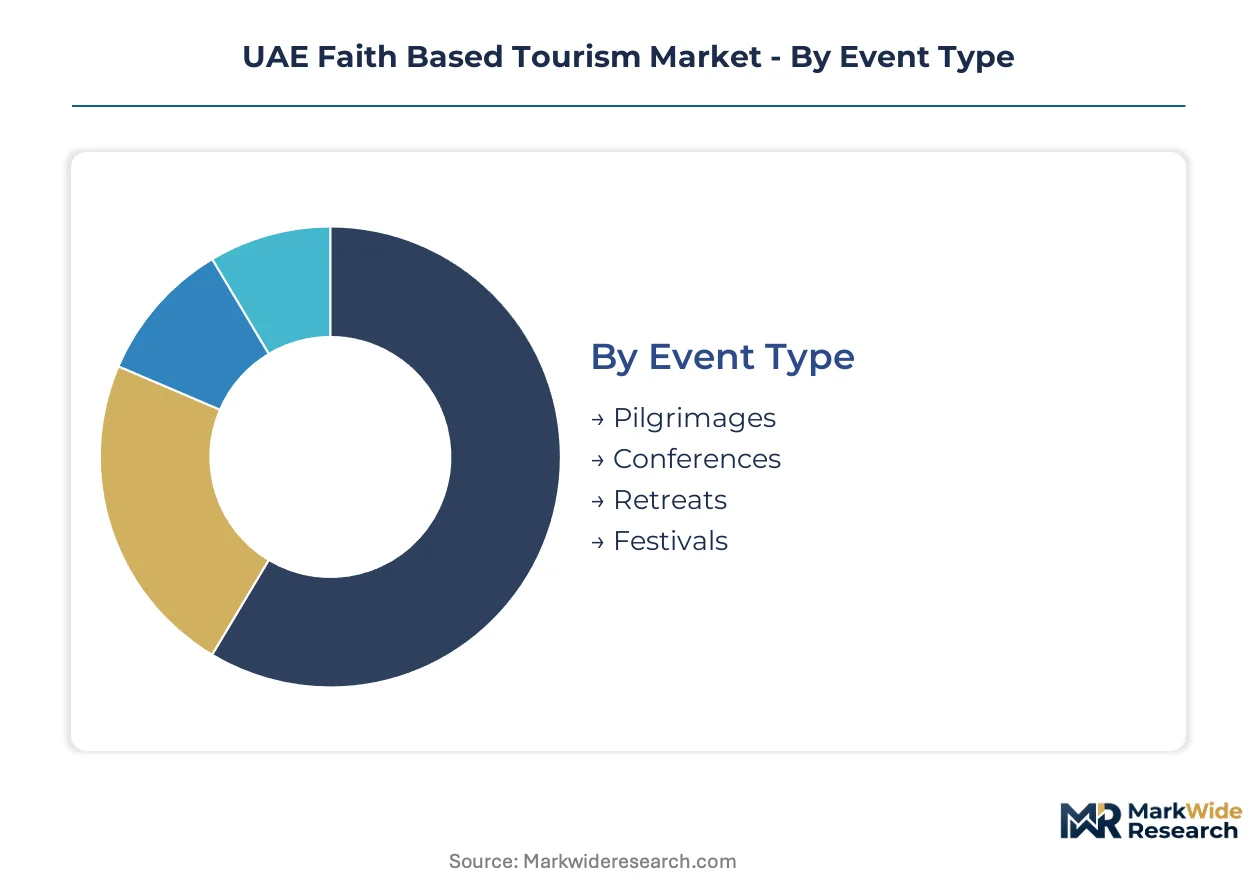
Segmentation in UAE faith based tourism reveals how service providers architect revenue streams around ritual calendars, traveler composition, and halal compliance tiers. Each dimension shapes procurement patterns for pilgrimage operators and hospitality assets across Dubai and Abu Dhabi corridors.
Event Type:
Mature pilgrimage infrastructure dominates revenue capture, while emerging formats test new demand pools outside peak religious seasons.
- Pilgrimages:Structured journeys to Saudi holy sites with bundled visa, ground transport, and gender-segregated lodging command premium pricing during Hajj and Ramadan windows. Demand concentrates among Pakistani and Indonesian family units booking through Dubai-based operators.
- Conferences:Scholarly gatherings and religious symposiums generate mid-week occupancy fill during off-peak months when pilgrimage volumes drop. Abu Dhabi's cultural district developments are capturing Islamic finance and theology forums seeking integrated prayer facilities.
- Retreats:Extended spiritual programs combining meditation, study, and communal worship attract Southeast Asian solo travelers.
- Festivals:Seasonal celebrations marking Islamic holidays create compressed demand spikes for halal catering and family accommodation packages.
Pilgrimages retain volume leadership; conferences hold the steepest expansion curve as operators diversify beyond Saudi-dependent itineraries.
Travel Purpose:
Cost tier stratification separates high-frequency ritual observance from discretionary spiritual tourism investment.
- Spiritual Growth:Extended retreats with clergy-guided programming and structured worship schedules attract premium-paying families from South Asian source markets. Dubai's specialized agencies bundle desert meditation sites with urban mosque circuits.
- Cultural Exploration:Islamic heritage site visits and manuscript tourism leverage Sharjah's underdeveloped museum infrastructure. Demand is concentrating among European Muslim travelers seeking alternative gateways to Middle Eastern sacred geography.
- Education:Seminary visits and religious study programs serve structured group bookings through academic intermediaries.
- Religious Observance:Duty-bound rituals including Umrah and Friday congregational prayers drive the highest repeat visitation rates.
Religious observance anchors volume; spiritual growth climbs fastest as families extend stays beyond minimum ritual requirements.
Service Type:
Margin concentration varies sharply between fixed-asset accommodation and variable-cost tour operations.
- Accommodation:Halal-certified properties with prayer-space proximity and gender-appropriate zoning sustain premium pricing during restricted occupancy periods. MOHAP certification tiers are excluding non-compliant mid-tier assets from preferred supplier lists.
- Guided Tours:Clergy-accompanied itineraries with sermon programming and ritual instruction capture value-add margins above transport-only packages. Abu Dhabi operators are recruiting General Authority of Islamic Affairs and Endowments-approved prayer leaders.
- Transportation:Dedicated coach fleets with onboard prayer facilities and qibla orientation serve group pilgrimage logistics.
- Meal Services:Cross-border halal supply chain verification extends procurement cycles for F&B operations across emirate properties.
Accommodation dominates revenue concentration; guided tours gain share fastest as AI-powered customization displaces static package models.
Visitor Type:
Customer type splits reveal divergent booking behaviors between consolidated family decisions and fragmented individual arrangements.
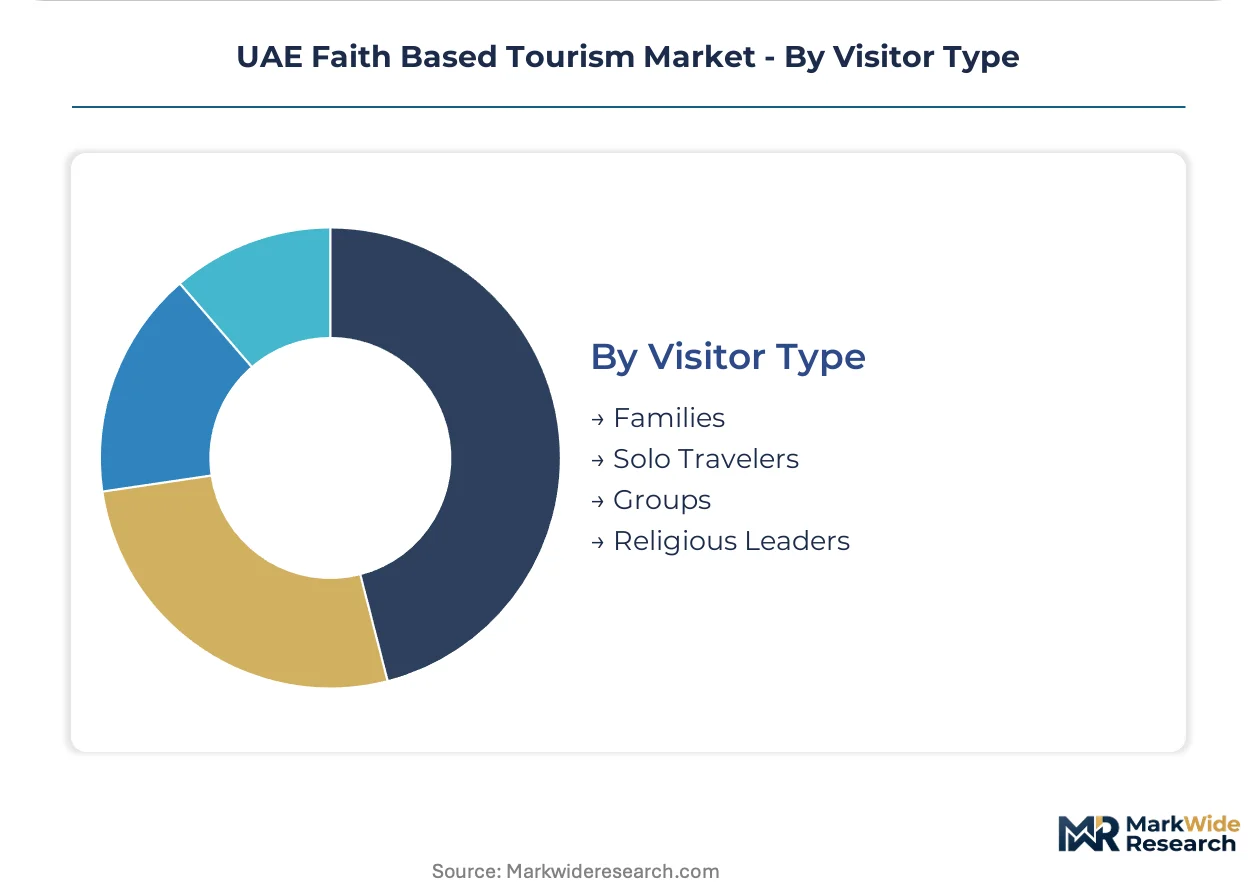
- Families:Multi-generational units with embedded childcare and elder-accessibility features generate the longest average stays and highest per-trip expenditure. Deira district agencies structure packages consolidating decision authority through designated group coordinators.
- Solo Travelers:Individual pilgrims from Indonesia and Pakistan represent expanding volume as digital platforms enable direct booking relationships bypassing legacy agency layers. Biometric border processing compresses arrival timelines for this segment.
- Groups:Structured cohorts through religious organizations and community associations enable volume pricing and coordinated logistics.
- Religious Leaders:Clergy-accompanied delegations requiring sermon-content approval and specialized accommodation protocols serve institutional client relationships.
Families retain volume leadership; solo travelers hold the steepest expansion curve as digital pilgrimage platforms accelerate adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Airport's position as the world's busiest international hub underwrites the UAE's staging role for pilgrims transiting to Saudi holy sites, while Abu Dhabi's Zayed International Airport anchors alternative gateway capacity for South Asian religious travelers.
Dubai
Deira district agencies consolidate multi-generational family bookings with embedded childcare and elder-accessibility features. MOHAP enforces accommodation grading that weights proximity to prayer facilities. The specialized hospitality corridor near the Grand Mosque is absorbing mid-tier property retrofits to maintain certification tiers.
Abu Dhabi
Cultural district developments capture Islamic finance and theology forums seeking integrated prayer facilities. The General Authority of Islamic Affairs and Endowments regulates sermon content at tourism-facing mosques. Saadiyat Island's museum cluster is testing manuscript tourism demand among European Muslim travelers.
Sharjah
Underdeveloped heritage infrastructure in the central district offers first-mover positioning for Islamic museum tourism. The emirate's national tourism authority channels heritage preservation grants toward faith-compatible attractions. The Heart of Sharjah restoration zone is recruiting clergy-approved prayer leaders for guided programming.
Northern Emirates
Ajman and Ras Al Khaimah absorb overflow pilgrimage lodging during peak Hajj and Ramadan windows. Federal visa facilitation frameworks extend digital clearance pilots to these lower-cost accommodation markets. Coastal resort properties are partitioning prayer spaces to capture family-unit bookings displaced from Dubai rate spikes.
UAE Faith Based Tourism Market Competitive Landscape
On the supply side, the industry is bifurcated between full-service carriers controlling transit logistics and specialized ground operators managing end-to-end pilgrimage fulfillment. Full-service airlines leverage hub dominance to capture en-route pilgrims, while hospitality groups compete on halal certification tiers and prayer-space proximity. Two strategic archetypes dominate: scale-driven carriers with network density advantages, and niche operators with clergy relationships and Saudi ministry accreditation. Competitive moves concentrate on visa-processing automation partnerships and multi-destination package bundling beyond Saudi-centric itineraries.
Among UAE-based carriers, Emirates and Etihad Airways exemplify the hub-dominance archetype, anchoring transit flows through Dubai and Abu Dhabi respectively. Saifco Travel & Tourism occupies a position within the specialized ground-operator tier, representing the end-to-end logistics model that controls procurement across accommodation and transport layers. These three entities collectively illustrate the market's structural division between aviation infrastructure owners and pilgrimage fulfillment specialists.
| Leading Market Players |
|---|
| Emirates |
| Etihad Airways |
| Air Arabia |
| Burj Al Arab |
| Dubai Palm Hotel |
| Rotana |
| Saifco Travel & Tourism |
| Expedia Group |
| Globus |
| Others |
Value Network & Pricing Analysis
Saudi Ministry of Hajj and Umrah quota allocations concentrate upstream pilgrimage volume control, directing margin pools toward UAE-based operators with direct Saudi accreditation and ground-transport fleet ownership rather than pure intermediaries.
Pricing Analysis
Volume-discount tiering structures dominate pilgrimage package economics, with family-unit bookings commanding 15-20% per-capita savings over individual arrangements. Price differentiation hinges on MOHAP certification grade and proximity to prayer facilities at lodging assets. Cost compression in mid-tier hospitality is intensifying as properties retrofit gender-segregation infrastructure to maintain operator partnerships. Solo travelers from Indonesia and Pakistan exhibit highest price sensitivity, while multi-generational families prioritize certification tier over rate.
Supply Chain Analysis
Contract-manufacturing concentration sits with Pakistani and Indonesian pilgrimage operators who control end-to-end logistics through Dubai staging hubs. Raw material dependencies include halal-certified food supply chains from Australia and New Zealand, gender-segregated coach fleets assembled in Turkey, and prayer-space construction materials from Saudi Arabia. Single-source vulnerability runs through Saudi visa processing pipelines. Distribution runs through Deira district agencies consolidating family bookings with embedded childcare and elder-accessibility features.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among family-unit coordinators and extended-family liaisons who consolidate decision authority, compressing touchpoints and squeezing margin capture for fragmented agency layers.
For Market Incumbents: Insulate core operator relationships by deepening backward integration into halal-certified accommodation assets and securing General Authority of Islamic Affairs and Endowments-approved prayer leader pools. Threat substitution from AI-powered itinerary platforms demands accelerated certification tier upgrades to maintain preferred supplier status with MOHAP.
For New Entrants and Emerging Players: Sharjah's underdeveloped heritage infrastructure and manuscript tourism corridor represent the most penetrable entry point for Islamic museum programming and clergy-guided cultural circuits. Go-to-market execution should anchor on partnerships with Saadiyat Island museum cluster operators seeking faith-compatible content extensions.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated pilgrimage operators with Saudi ministry accreditation and captive ground-transport fleets. Long-term viability hinges on visa-processing automation capabilities and multi-destination package architectures beyond Saudi-centric flows. Watch MOHAP digital visa-on-arrival pilot expansion as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Tier Upgrade | MOHAP compliance thresholds determine preferred supplier eligibility for government contracts. |
| Multi-Destination Package Bundling | Jordanian and Turkish sacred site integration diversifies revenue beyond Saudi quota dependencies. |
| Digital Visa-on-Arrival Pilot | MOHAP instant clearance compression reduces booking-to-arrival cycles from weeks to hours. |
| AI-Powered Itinerary Customization | Direct-to-pilgrim platforms displace legacy agency intermediaries with data-driven personalization. |
| Gender-Segregation Infrastructure Retrofit | Prayer-space partitioning capex maintains operator partnerships during certification tier transitions. |
Research Methodology
A standing panel of pilgrimage operators, halal hospitality procurement managers, General Authority of Islamic Affairs and Endowments liaison officers, and MOHAP certification auditors provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against UAE national tourism statistics, Saudi Ministry of Hajj and Umrah quota disclosures, and airline network capacity filings. Bottom-up package economics modeling and top-down emirate-level tourism receipts triangulation anchored value estimates.
Scenario-bracketing around Saudi visa quota volatility, MOHAP regulatory tier evolution, and biometric border processing adoption shaped projection ranges across the analysis window. Segmentation dimensions modeled encompass event type, travel purpose, service type, and visitor type with cross-tabulation against source market origin. CAGR derivation integrated historical pilgrimage volume trends, airline seat capacity growth, and accommodation stock expansion with elasticity adjustments for certification tier pricing premiums.
Practitioners should monitor Saudi Ministry of Hajj and Umrah quota allocation announcements, MOHAP certification tier threshold revisions, and Emirates-Etihad network density shifts for early signals of volume redistribution. Quarterly review of digital visa pilot program expansion rates and Sharjah heritage infrastructure investment flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
Europe Theme Park Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
Golf Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Japan Faith-Based Tourism Market