
 Cultural Tourism Market | 2026-2036
Cultural Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Cultural Tourism Market Analysis
Italy's heritage corridor investments are reshaping European cultural tourism infrastructure. Trafalgar Tours leverages its guided-tour expertise across Mediterranean routes. Abercrombie and Kent anchors ultra-luxury cultural journeys through private monument access. Intrepid Travel differentiates via community-based tourism models in emerging destinations.
Cultural tourism encompasses travel motivated by experiencing authentic heritage, arts, cuisine, and living traditions of host communities, typically involving curated site visits, interpretive programming, and direct engagement with local custodians rather than passive sightseeing. Heritage sightseeing and museum visits constitute the core revenue base, while culinary experiences command premium pricing through exclusive chef collaborations and terroir-anchored storytelling. Festival participation shows accelerating growth as social media amplification transforms seasonal events into year-round booking drivers. Virtual experiences remain nascent but attract technology-forward educational groups seeking pre-trip immersion.
UNESCO World Heritage Centre guidelines shape site capacity management across member states, while national tourism ministries enforce visitor impact thresholds at sensitive archaeological zones. The EU Green Deal's sustainable mobility requirements are redirecting coach-based tour flows toward rail-integrated itineraries. Stakeholders must monitor evolving carbon-accounting standards for long-haul cultural travel and assess whether rail partnerships or localized sourcing can preserve margin structures under emerging compliance frameworks.
Market Dynamics
UNESCO capacity mandates and carbon-accounting protocols are forcing destination managers to restructure visitor flows around rail-integrated corridors and digital pre-booking systems, compressing traditional coach-based itinerary economics.
Growth Catalysts
- EU Green Deal mobility requirements:Rail-integrated cultural corridors across Italy, France, and Spain are capturing premium tour operator investment as diesel coach restrictions tighten.
- Educational group field-study expansion:University archaeology and art history departments are scaling semester-abroad programs, creating contracted demand blocks with guaranteed minimum volumes.
- Social media festival amplification:Seasonal heritage events in Rajasthan and Kyoto are converting single-weekend attendance into year-round booking pipelines through influencer content cycles.
Market Restraints
- Heritage site capacity hard ceilings:UNESCO visitor impact thresholds at Machu Picchu and Angkor Wat limit daily ticket availability regardless of demand pressure.
- Specialized conservation labor scarcity:Certified site interpreters and monument conservators concentrate in Italian and French training pipelines, constraining expansion elsewhere.
- Jet fuel cost volatility:Long-haul cultural itineraries remain exposed to aviation fuel price swings that rail cannot fully substitute for intercontinental source markets.
Strategic Opportunities
- Community-based tourism models:Village-level heritage custodians in Vietnam and Guatemala are developing direct booking platforms that bypass traditional operator intermediaries.
- Virtual reality pre-trip immersion:Educational groups are adopting headset-based site familiarization to reduce physical footprint while maintaining enrollment.
- Carbon offset integration:EU CSRD disclosure requirements are creating procurement preference for cultural operators with verified emission accounting.
Industry Challenges
- Multilingual interpretation talent gaps:Mandarin, Arabic, and Portuguese-speaking guides remain underrepresented at Mediterranean UNESCO sites despite visitor growth from those source markets.
- Legacy reservation system integration:Municipal monument authorities operate siloed ticketing platforms that resist aggregation with private tour operator inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultural Tourism Market |
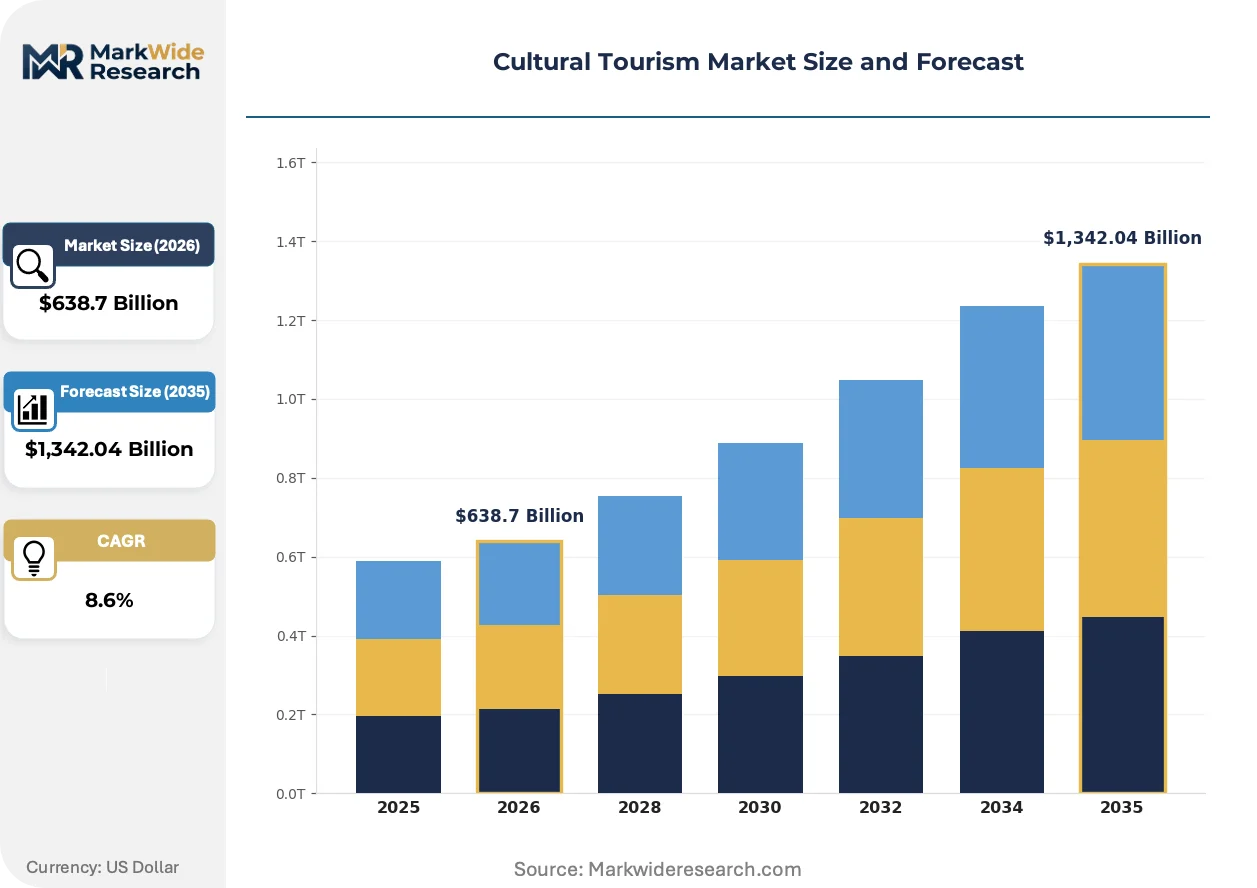
| Market Size in 2026 | $638.7 Billion |
| Market Size in 2035 | $1,342.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tour Type: Historical Tours, Art Tours, Culinary Experiences, Eco-Tours Consumer Segment: Families, Solo Travelers, Educational Groups, Luxury Travelers Activity: Museum Visits, Festival Participation, Cultural Workshops, Heritage Sightseeing Accessibility: Guided Tours, Self-Guided Tours, Virtual Experiences, Accessible Tours |
| Companies Covered | Trafalgar Tours, Trailfinders, Intrepid Travel, Anantara Hotels and Resorts, Explora Journeys, G Adventures, Jules Verne, Wilderness Travel, Abercrombie and Kent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultural Tourism Market Emerging Trajectories
Digital twin technologies and immersive media are compressing the traditional site-visit model, enabling operators to monetize heritage access through pre-arrival engagement and post-departure subscription content.
Extended reality platforms are virtualizing fragile archaeological zones before physical arrival. Educational travel coordinators at North American universities are adopting these tools for semester preparation. The technology is virtualizing revenue capture from students who may never complete the physical journey.
EU Green Deal sustainable mobility mandates are redirecting cross-border tour flows from coach to rail. Italian regional authorities are consolidating fragmented municipal ticketing into unified corridor passes. French and Spanish infrastructure ministries are responding with dedicated cultural rail product development.
Educational procurement officers are unbundling traditional package tours into modular components. Universities now contract directly with site conservators for exclusive access windows, displacing operator intermediaries. This pattern concentrates in British and German institutions with established archaeology departments.
Cultural Tourism Market Segmentation
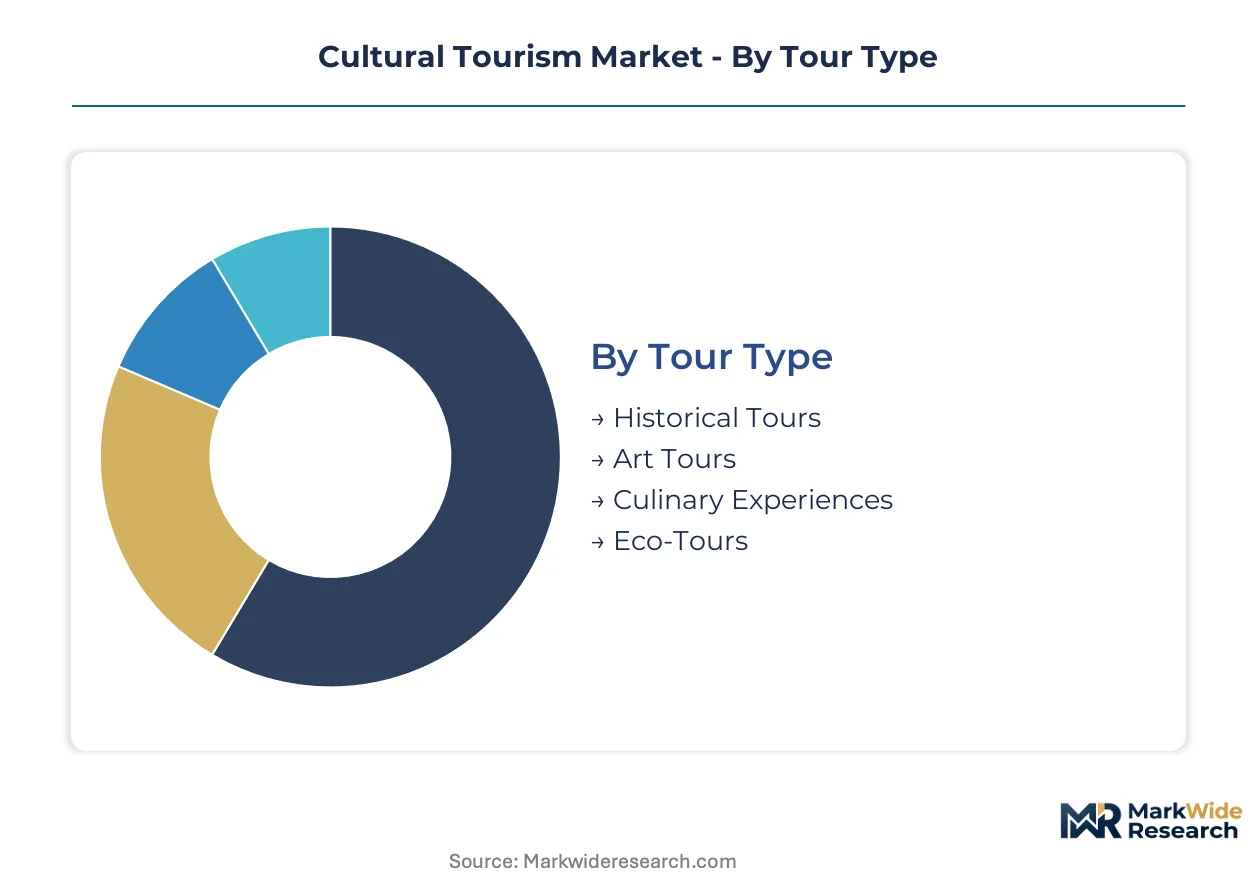
Cultural tourism operators structure product portfolios around four intersecting dimensions that determine booking velocity and margin capture. Tour type and consumer segment together dictate pricing architecture, while activity and accessibility layers shape operational complexity and technology investment priorities.
Tour Type:
Historical tours turn inventory fastest during peak seasons, while culinary experiences stretch booking windows through exclusive chef availability and harvest calendars.
- Historical Tours:These itineraries center on UNESCO World Heritage sites, archaeological zones, and monument circuits with fixed capacity constraints. Italian regional authorities consolidate municipal ticketing into unified corridor passes to manage visitor flows at dense site clusters.
- Culinary Experiences:Terroir-anchored programming pairs exclusive chef collaborations with seasonal ingredient availability. Demand concentrates in France and Italy where appellations and Slow Food networks provide authenticated provenance narratives.
- Art Tours:Museum and gallery circuits with timed entry requirements.
- Eco-Tours:Community-based models in emerging destinations bypassing traditional intermediaries.
Historical tours anchor the volume base while culinary experiences gain share at the steepest rate.
Consumer Segment:
Pricing tiers separate luxury travelers seeking private monument access from educational groups contracting for guaranteed volume blocks at standardized rates.
- Luxury Travelers:Ultra-premium positioning through after-hours site access and conservator-led briefings. Abercrombie and Kent anchors this tier across Mediterranean routes with dedicated monument protocols.
- Educational Groups:University archaeology and art history departments scale semester-abroad programs with contracted minimum volumes. British and German institutions with established departments concentrate procurement here.
- Families:Multi-generational itineraries with activity pacing adjustments.
- Solo Travelers:Flexible booking windows and single-supplement waivers.
Educational groups anchor the volume base while luxury travelers expand most quickly through premium pricing power.
Activity:
Social media amplification has compressed the festival participation cycle from seasonal spikes to year-round booking pipelines.
- Festival Participation:Seasonal heritage events in Rajasthan and Kyoto convert single-weekend attendance into extended booking windows through influencer content cycles. Event organizers now monetize pre-festival immersion and post-event subscription content.
- Museum Visits:Timed-entry systems with digital pre-booking requirements. EU Green Deal mobility mandates redirect coach-based flows toward rail-integrated access.
- Heritage Sightseeing:Archaeological zone circuits with UNESCO-mandated capacity ceilings.
- Cultural Workshops:Hands-on craft and tradition transmission with local custodians.
Museum visits anchor the volume base while festival participation climbs the fastest through digital amplification.
Accessibility:
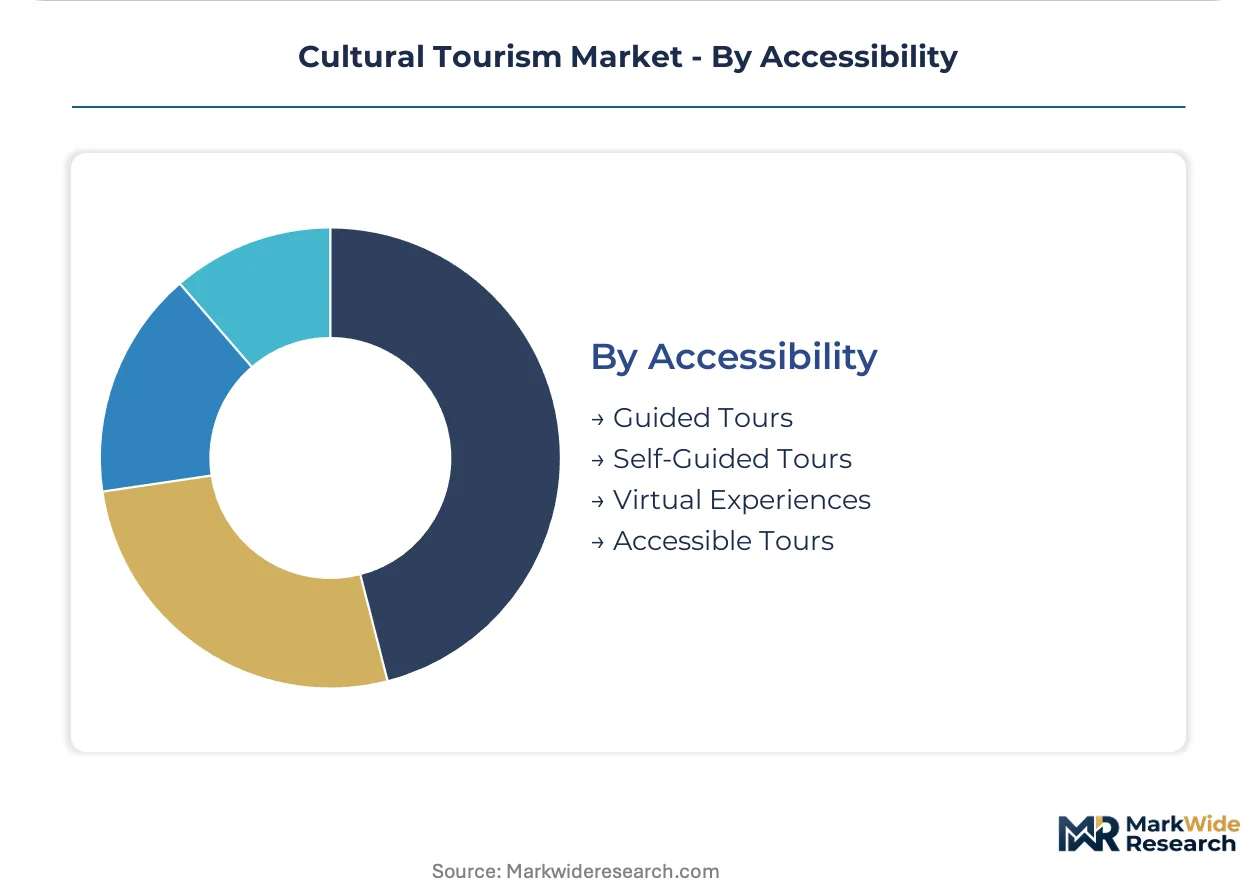
Virtual experiences carry the shortest development cycle but face monetization constraints, while guided tours require sustained interpreter talent pipelines.
- Guided Tours:Certified site interpreters and monument conservators concentrate in Italian and French training pipelines. Mandarin, Arabic, and Portuguese-speaking guides remain underrepresented at Mediterranean UNESCO sites despite visitor growth from those source markets.
- Virtual Experiences:Headset-based site familiarization for educational pre-trip immersion. North American universities adopt these tools to reduce physical footprint while maintaining enrollment.
- Self-Guided Tours:Audio and app-based interpretation with fragmented municipal platform integration.
- Accessible Tours:Mobility and sensory accommodation at heritage sites with retrofit requirements.
Guided tours anchor the volume base while virtual experiences gain share fastest through technology-forward educational procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UNESCO World Heritage Centre guidelines and EU Green Deal mobility mandates anchor European cultural tourism infrastructure development. Italy's regional clustering of heritage sites creates the densest itinerary networks globally. Educational group demand from North American universities and social media-amplified festival participation reshape booking patterns across source markets.
Italy
Regional authorities consolidate municipal ticketing into unified corridor passes across UNESCO site clusters. EU Green Deal requirements redirect coach-based tour flows toward rail-integrated itineraries. Tuscany and Lazio host the densest concentration of heritage sightseeing circuits with timed-entry capacity management systems.
France
Culinary experiences command premium pricing through appellations and Slow Food authenticated provenance narratives. The country's national tourism ministry enforces visitor impact thresholds at sensitive archaeological zones. Provence-Alpes-Côte d'Azur anchors terroir-anchored programming with exclusive chef collaborations.
United States
North American universities scale semester-abroad archaeology and art history field-study programs. Educational procurement officers unbundle traditional package tours into modular components directly contracted with site conservators. Boston and New York Metro concentrate demand coordination for Mediterranean heritage corridors.
Japan
Seasonal heritage events in Kyoto convert single-weekend attendance into year-round booking pipelines through influencer content cycles. METI guidelines shape sustainable tourism infrastructure investment. Kansai region clusters temple and garden circuits with rail-integrated access protocols.
India
Rajasthan festival participation accelerates through social media amplification transforming seasonal events into extended booking windows. The country's national tourism ministry develops visitor management technologies at UNESCO sites. Delhi-NCR serves as the primary demand coordination hub for educational group itineraries.
Cultural Tourism Market Vendor Landscape
Capability concentration sits with heritage interpretation specialists; scale advantage sits with integrated tour operators managing multi-destination logistics. The market structures around three archetypes: ultra-luxury private access providers, community-based emerging destination specialists, and educational group contract aggregators. Competitive moves center on rail partnership integration and direct conservator relationship development.
Within the ultra-luxury tier, Abercrombie and Kent anchors Mediterranean routes through dedicated monument protocols. Trafalgar Tours occupies a position across guided-tour expertise and established corridor infrastructure. Intrepid Travel exemplifies community-based tourism models that bypass traditional intermediaries in emerging destinations.
| Leading Market Players |
|---|
| Trafalgar Tours |
| Trailfinders |
| Intrepid Travel |
| Anantara Hotels and Resorts |
| Explora Journeys |
| G Adventures |
| Jules Verne |
| Wilderness Travel |
| Abercrombie and Kent |
| Others |
Supply Flow & Price Mechanics
Tuscany's heritage corridor consolidation into unified rail-integrated passes concentrates pricing power with Italian regional authorities, compressing operator margins on traditional coach-based itineraries while elevating premium tiers for exclusive monument access windows.
Pricing Analysis
Price spreads between Mediterranean heritage circuits and Southeast Asian community-based alternatives stretch to three-tier differentiation across premium, standard, and economy levels. Luxury travelers purchasing conservator-led briefings at Angkor Wat or Machu Picchu face capacity-constrained premiums, while educational groups contract standardized volume blocks at negotiated rates. Cost compression in the mid-market coach segment intensifies as EU Green Deal diesel restrictions force fleet conversion investments. Families and solo travelers exhibit highest price sensitivity, whereas ultra-luxury buyers demonstrate inelastic demand for after-hours site protocols.
Supply Chain Analysis
Export-control restrictions on immersive media technologies limit virtual reality hardware flows into educational procurement channels, constraining pre-trip immersion deployment. Supply concentrates in Italy, France, and Spain for certified site interpreters and monument conservators, while Vietnam and Guatemala emerge as alternative sources for community-based tourism custodians. Raw material dependencies include rail infrastructure capacity, digital booking platform architecture, and conservation-grade materials for archaeological zone maintenance. Single-source vulnerability sits with Italian training pipelines for multilingual interpretation talent. Distribution runs through tour operator intermediaries, direct conservator contracts, and emerging village-level booking platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cultural tourism sits in early-cycle expansion as educational procurement officers accelerate direct contracting with site conservators, bypassing traditional operator intermediaries and reshaping competitive architecture.
For Market Incumbents: Harden rail partnership integration across Italian and French heritage corridors before diesel coach phase-outs complete. Secure exclusive conservator access windows at capacity-constrained UNESCO sites to defend against university direct-contracting threats. Invest in Mandarin and Arabic interpretation certification pipelines to capture visitor growth from underrepresented source markets. For New Entrants and Emerging Players: Establish a beachhead in virtual reality pre-trip immersion for North American educational groups, where procurement officers seek footprint reduction without enrollment loss. Target community-based tourism models in Vietnam and Guatemala where village-level custodians bypass traditional intermediaries. Lead with direct booking platform development and local interpreter training partnerships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because educational group contract aggregation and rail-integrated corridor control will concentrate with scaled operators. Target acquisition archetypes include specialized heritage interpretation firms with conservator relationships and immersive media developers with university procurement traction. Watch for inflection when carbon-accounting disclosure mandates under EU CSRD redirect procurement preference toward verified emission accounting operators.| Strategic Initiative | Industry Significance |
|---|---|
| Rail Partnership Integration | EU Green Deal mobility mandates redirect coach-based flows toward rail-integrated cultural corridors across Italy, France, and Spain. |
| Direct Conservator Contracting | Educational procurement officers at British and German universities unbundle packages into modular site-specific agreements. |
| Virtual Reality Pre-Trip Deployment | North American universities adopt headset-based familiarization to reduce physical footprint while maintaining enrollment levels. |
| Carbon Offset Integration | EU CSRD disclosure requirements create procurement preference for operators with verified emission accounting systems. |
| Community-Based Platform Development | Village-level heritage custodians in Vietnam and Guatemala build direct booking channels bypassing traditional intermediaries. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of UNESCO World Heritage Centre guidelines, EU Green Deal mobility directives, and national tourism ministry visitor management protocols. Primary interviews engaged tour operator product directors, university study-abroad coordinators, site conservators at Mediterranean UNESCO locations, rail infrastructure planners, and immersive media procurement officers at North American institutions. Secondary validation drew from national statistical offices, heritage site ticketing databases, and rail authority corridor development filings. Bottom-up itinerary volume modeling triangulated against top-down regional tourism expenditure estimates.
Forecast inputs incorporate tour type segmentation across historical, culinary, art, and eco-tour categories; consumer tier differentiation between luxury travelers, educational groups, families, and solo travelers; activity patterns spanning festival participation, museum visits, heritage sightseeing, and cultural workshops; and accessibility modes including guided, virtual, self-guided, and accessible formats. CAGRs were derived from corridor capacity expansion timelines, educational procurement contract growth trajectories, and rail infrastructure investment pipelines across the projection horizon.
Stress conditions across jet fuel cost volatility, heritage site capacity ceiling enforcement, and conservation labor pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU mobility mandate implementation schedules and educational group enrollment trends. Material shifts in UNESCO visitor impact threshold enforcement or carbon-accounting standard adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Europe Theme Park Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
India Faith Based Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
Literary Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Industrial Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
Geotourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Europe Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market