
 Oracle Services Market | 2026-2036
Oracle Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oracle Services Market Outlook
The EU AI Act is rebalancing procurement criteria for Oracle implementations across European financial institutions and healthcare networks. Deloitte leverages its risk advisory depth to embed algorithmic accountability into Oracle Cloud Infrastructure deployments. Capgemini anchors European delivery capacity through specialized Oracle practices in France and the Netherlands. IBM competes by extending Watson governance tooling into Oracle analytics environments for regulated industries.
Oracle services encompass consulting, technical implementation, systems integration, and ongoing support for Oracle's database, applications, and cloud infrastructure portfolios, typically delivered through SOW-based engagements with defined milestone governance and SLA-backed operational parameters. These services enable enterprise data consolidation, financial process automation, and supply chain orchestration across hybrid technology estates. Consulting and implementation segments dominate current revenue pools as enterprises replatform legacy E-Business Suite installations, while cloud deployment models capture the fastest expansion as Oracle's Gen2 infrastructure gains traction among workloads requiring sovereign data residency. Healthcare and financial services verticals concentrate margin-rich transformation engagements due to compliance complexity and integration density with specialized third-party systems.
The EU AI Act, GDPR, and HIPAA constrain how Oracle service providers configure data residency, model explainability, and cross-border transfer mechanisms in client environments. India's BIS cloud standards and the country's PLI scheme for IT services create additional compliance layers for offshore delivery centers supporting North American and European accounts. Procurement leaders must evaluate provider certifications against emerging sovereign AI requirements before committing to multi-year Oracle Cloud transformation contracts.
Market Dynamics
Enterprise migration from on-premises Oracle E-Business Suite to Fusion Cloud Applications is compressing implementation timelines and forcing service providers to restructure delivery models around continuous update cycles rather than discrete upgrade projects.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions in Germany and France require algorithmic governance frameworks for automated credit decisioning, expanding advisory engagements for Oracle Cloud Infrastructure deployments.
- Healthcare data consolidation:US hospital networks are unifying electronic health record systems onto Oracle Health platforms to streamline HIPAA-compliant analytics and patient data orchestration.
- India PLI scheme for IT services:Domestic capability centers in Bangalore and Hyderabad are scaling to support North American Oracle Cloud transformations with sovereign data residency guarantees.
Market Restraints
- Certified Oracle talent scarcity:Supply of architects with Fusion Financials and Supply Chain Management specializations concentrates in Mumbai, Dallas, and London, inflating day rates and project delays.
- Multi-cloud integration complexity:Enterprises running AWS or Azure alongside Oracle Cloud require custom middleware development, extending implementation timelines and eroding margin on fixed-price contracts.
- GDPR cross-border transfer friction:European data localization requirements constrain how Indian delivery centers access production environments for troubleshooting and patch management.
Strategic Opportunities
- Sovereign cloud expansion:Oracle's dedicated region deployments in Saudi Arabia and UAE are creating localized implementation demand for government and banking modernization programs.
- Gen2 infrastructure workload migration:Autonomous Database and Exadata Cloud Service convergence is opening net-new engagements for high-performance analytics in capital markets and pharmaceutical R&D.
- Subscription pricing adoption:Oracle's Universal Credits model is displacing perpetual license conversions, enabling service providers to attach recurring managed services revenue to consumption-based contracts.
Industry Challenges
- Fusion skills pipeline gaps:Universities and training programs have not scaled curricula for Oracle Cloud ERP, HCM, and SCM modules, forcing providers to build captive academies with 12-18 month certification cycles.
- Continuous update disruption:Quarterly release cycles for Fusion Applications break traditional waterfall testing protocols, requiring investment in automated regression suites and DevOps tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oracle Services Market |
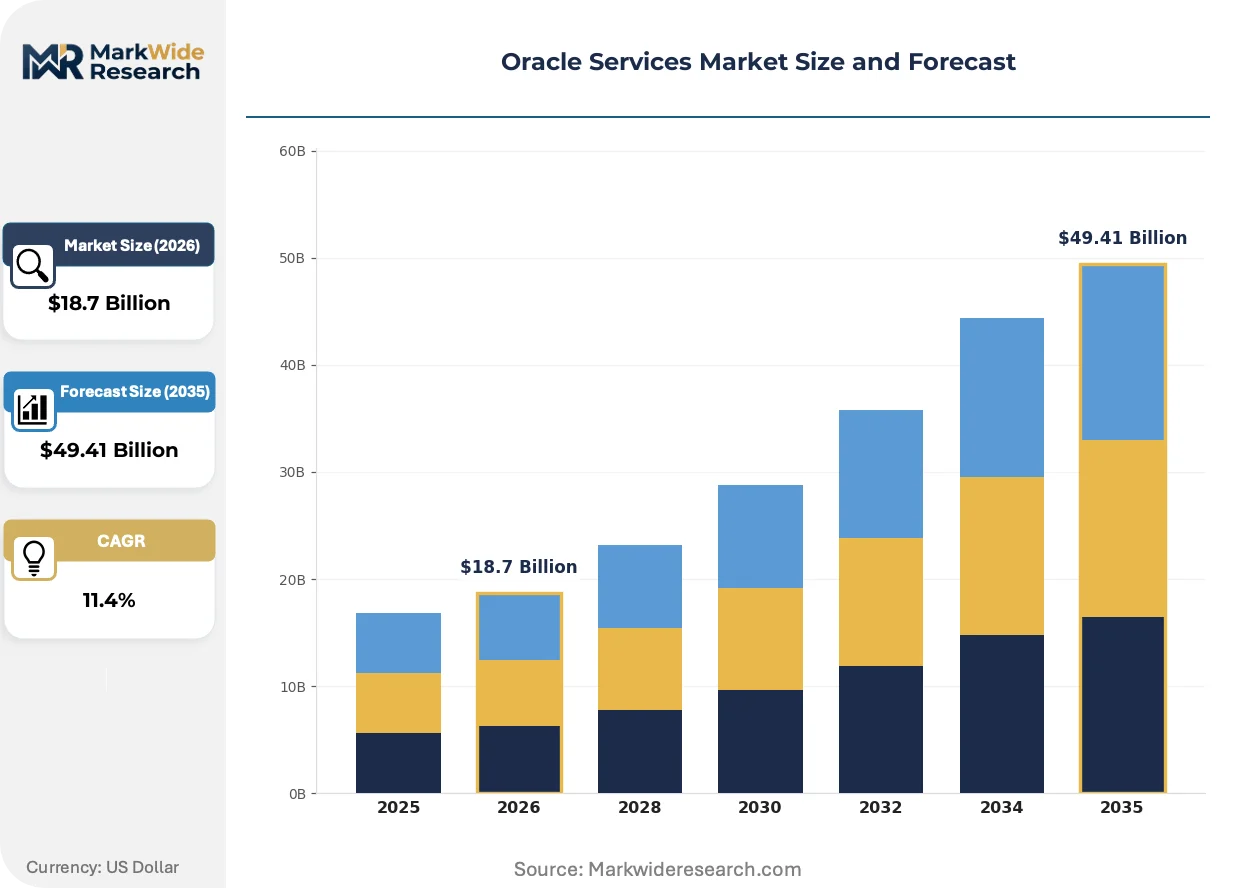
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Integration, Support Deployment Model: On-Premises, Cloud, Hybrid, Managed Services End User: Enterprises, Small & Medium Businesses, Government, Educational Institutions Industry Vertical: Healthcare, Retail, Financial Services, Manufacturing |
| Companies Covered | Oracle Corp, Deloitte, Infosys, TCS, Wipro, Capgemini, Cognizant, HCLTech, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oracle Services Market Strategic Shifts
Oracle service delivery is pivoting from project-based implementation toward embedded operational partnerships, with automation and sovereign compliance requirements reshaping how providers architect talent and technology stacks.
Autonomous Database is absorbing routine DBA functions including patching, tuning, and backup management that previously consumed 30-40% of managed services headcount. Mid-market manufacturers and retail chains are adopting this capability fastest, drawn by consumption-based pricing and elimination of version-lock maintenance windows. The technology is absorbing lower-tier operational support roles and compressing pricing for traditional remote DBA contracts.
GDPR Article 44 transfer mechanism enforcement and the EU AI Act's risk classification system are mandating data residency and model explainability documentation for Oracle analytics deployments. Service providers must now embed privacy-by-design consulting into standard implementation statements of work, extending pre-sales cycles but creating attach opportunities for ongoing compliance monitoring. European banking and insurance verticals are responding by demanding dedicated EU-sovereign Oracle Cloud regions with contractual data processing agreements.
Enterprise buyers are unbundling implementation from multi-year managed services, preferring shorter initial engagements with explicit knowledge transfer obligations. This pattern compresses provider revenue recognition timelines and forces investment in customer success functions to secure renewal and expansion revenue. The shift is most visible in US healthcare networks and German automotive suppliers, where procurement teams prioritize internal capability building over long-term outsourcing dependencies.
Oracle Services Market Segmentation
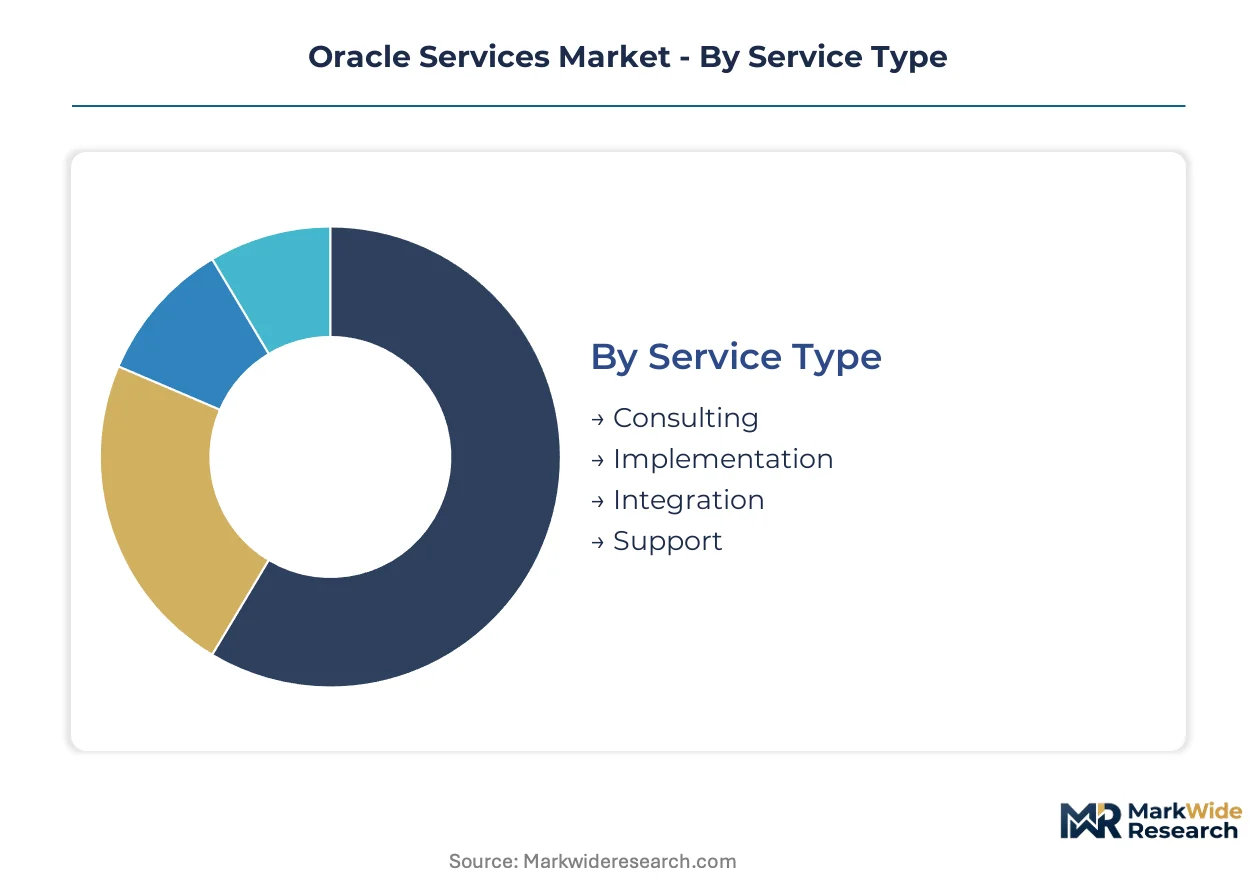
Service segmentation in Oracle implementations dictates procurement complexity, certification requirements, and margin structures for providers. Buyers align segment selection with compliance burden, integration density, and internal capability maturity.
Service Type:
Consulting engagements require Oracle Cloud Infrastructure certifications and regional data residency accreditations that vary by client geography and industry vertical.
- Consulting:Strategic advisory spans cloud migration roadmapping, license optimization, and regulatory alignment for EU AI Act and HIPAA frameworks. German automotive suppliers and US hospital networks concentrate demand here as they replatform legacy E-Business Suite estates.
- Implementation:Technical deployment of Fusion Cloud ERP, HCM, and SCM modules demands certified architects with specialized module credentials. Indian delivery centers in Bangalore and Hyderabad scale this segment for North American accounts seeking cost-arbitrage without sacrificing Oracle partnership tier status.
- Integration:Middleware development connects Oracle Cloud with AWS, Azure, and specialized third-party systems in capital markets and pharmaceutical supply chains.
- Support:Ongoing managed services cover patching, incident response, and quarterly release management for Autonomous Database and Fusion Applications environments.
Implementation sits at the top of the volume ranking, with Support climbing the fastest as subscription pricing displaces perpetual licenses.
Deployment Model:
Cost tier differentiation separates sovereign-compliant dedicated regions from standard public cloud consumption, with hybrid architectures commanding premium implementation rates.
- Cloud:Oracle Cloud Infrastructure delivers Gen2 compute, Autonomous Database, and Exadata Cloud Service through consumption-based Universal Credits. Saudi Arabia and UAE dedicated regions attract government and banking modernization programs requiring data localization guarantees.
- Hybrid:Split workloads between on-premises Exadata and Oracle Cloud preserve latency-sensitive operations while enabling elastic analytics capacity. US financial services firms favor this model for trading systems that must remain on-premises while risk analytics migrate to cloud.
- On-Premises:Legacy E-Business Suite and custom Oracle Database installations persist in defense and classified government environments with air-gapped security requirements.
- Managed Services:Third-party operational takeover of Oracle environments includes SLAs for availability, patching cadence, and compliance attestation.
Cloud deployments dominate current volume, with Hybrid architectures expanding most quickly as regulated industries seek phased migration paths.
End User:
Customer type determines implementation methodology, with enterprises demanding phased rollouts and mid-market buyers accepting accelerated template-based deployments.
- Enterprises:Multi-national corporations with complex organizational structures require customized Fusion Cloud configurations, extensive integration with existing ERP estates, and dedicated change management programs. French banking groups and US healthcare networks typify this segment's procurement patterns.
- Small & Medium Businesses:Rapid template-based implementations of Oracle NetSuite or simplified Fusion Cloud configurations target 90-day go-live timelines. Manufacturing clusters in India's industrial corridors and Germany's Mittelstand sector concentrate uptake here.
- Government:Federal, state, and municipal agencies mandate FedRAMP, StateRAMP, or equivalent sovereign certifications with contractual data processing agreements.
- Educational Institutions:Universities and research hospitals deploy Oracle Cloud for student information systems, research grant management, and HIPAA-compliant health services administration.
Enterprises command the largest project scale, with Small & Medium Businesses gaining share fastest as Oracle pushes downmarket with standardized offerings.
Industry Vertical:
Application-specific functionality and compliance density separate margin-rich transformation engagements from commodity implementation work.
- Financial Services:Capital markets, retail banking, and insurance operations demand algorithmic governance frameworks for EU AI Act compliance, real-time risk analytics on Exadata Cloud Service, and PCI-DSS attestation for payment processing environments. Frankfurt and Paris banking centers anchor European demand.
- Healthcare:Hospital networks and payers consolidate electronic health records onto Oracle Health platforms, embedding HIPAA technical safeguards and HITRUST certification into cloud architectures. Texas Medical Center and Mayo Clinic systems drive US concentration.
- Manufacturing:Supply chain orchestration, IoT-enabled predictive maintenance, and shop-floor integration with ERP systems characterize Oracle Cloud SCM deployments in automotive and industrial equipment sectors.
- Retail:Omnichannel order management, demand forecasting, and customer data platforms leverage Oracle Cloud CX and Fusion SCM for inventory optimization across distributed fulfillment networks.
Financial Services leads vertical revenue concentration, with Healthcare expanding most steeply as provider networks accelerate EHR consolidation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oracle services originated in the United States during the 1970s database revolution, with Redwood Shores anchoring early commercialization before global delivery networks emerged across India and Europe.
United States
Mayo Clinic and Texas Medical Center drive healthcare consolidation onto Oracle Health platforms. HIPAA technical safeguard enforcement compels cloud architecture redesigns. Dallas-Fort Worth concentrates Fusion Financials talent pools serving North American enterprise migrations.
Germany
Deutsche Bank and Commerzbank mandate algorithmic governance frameworks for automated credit decisioning. EU AI Act risk classification rules reshape procurement criteria for Oracle Cloud Infrastructure. Frankfurt's banking quarter anchors advisory demand for compliance-embedded implementations.
India
Bangalore and Hyderabad delivery centers scale to support North American Oracle Cloud transformations. BIS cloud standards and the PLI scheme for IT services create sovereign data residency guarantees. Mumbai concentrates certified Fusion architects, inflating day rates for scarce SCM and HCM specializations.
United Kingdom
Barclays and HSBC replatform legacy E-Business Suite estates onto Fusion Cloud Applications. GDPR Article 44 transfer mechanism enforcement constrains offshore production environment access. London's financial district demands dedicated EU-sovereign Oracle Cloud regions with contractual data processing agreements.
Saudi Arabia
SAMA-regulated banks and NEOM government programs require localized Oracle Cloud Infrastructure deployments. SFDA pharmaceutical traceability mandates drive Exadata Cloud Service adoption. Riyadh anchors dedicated region implementations for sovereign data localization guarantees.
Oracle Services Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and regulatory advisory capability. The vendor base stratifies between global systems integrators with Oracle Diamond partnership status and mid-tier regional specialists competing on cost-arbitrage. Three archetypes dominate: advisory-heavy consultancies embedding compliance frameworks, scale-driven Indian IT services firms with captive delivery centers, and technology-anchored providers extending proprietary governance tooling. Competitive moves concentrate on strategic partnerships for sovereign cloud credentials and portfolio diversification into managed services annuities.
Within the advisory tier, Deloitte and Capgemini exemplify risk advisory depth integrated with Oracle Cloud Infrastructure deployments. Among scale-driven Indian integrators, TCS anchors delivery capacity through Bangalore and Hyderabad capability centers. These three occupy positions spanning premium advisory and volume implementation segments.
| Leading Market Players |
|---|
| Oracle Corp |
| Deloitte |
| Infosys |
| TCS |
| Wipro |
| Capgemini |
| Cognizant |
| HCLTech |
| IBM |
| Others |
Value Chain & Pricing Dynamics
Oracle Cloud Infrastructure compute unit pricing indices cascade through service provider cost structures, compressing margins on fixed-price Fusion implementations while inflating advisory premiums for EU AI Act compliance engagements. This cost transmission splits the market between commodity implementation tiers and sovereign-certified premium offerings.
Pricing Analysis
Consumption-based Universal Credits pricing separates premium advisory tiers from standard implementation bundles from economy remote support contracts. Price differentiation hinges on Oracle partnership tier status and specialized Fusion module certifications, with Diamond partners commanding substantial premiums over regional specialists. Cost compression in standard implementation tiers is intensifying because Autonomous Database automation eliminates routine DBA functions. Small and medium businesses exhibit highest price sensitivity, while financial services enterprises prioritize compliance-embedded premiums over unit cost minimization.
Supply Chain Analysis
Refurbishment and recertification flows for Oracle hardware assets create secondary supply channels that moderate Exadata Cloud Service provisioning costs for mid-market buyers. Talent supply concentrates in India, the United States, and the United Kingdom, with Mumbai, Dallas, and London anchoring certified Fusion architect pools. Delivery capacity draws from Bangalore and Hyderabad capability centers, with sovereign data residency requirements tethered to BIS cloud standards and PLI scheme incentives. Single-source vulnerability sits with concentrated Fusion Financials and SCM specialization scarcity. Distribution runs through Oracle Diamond partnership hierarchies into enterprise direct sales and channel partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oracle services market functions as a regulatory compounder, with EU AI Act algorithmic governance mandates expanding advisory attach rates and extending contract durations across European financial institutions.
For Market Incumbents: Extend compliance advisory depth into Oracle Cloud Infrastructure deployments to capture recurring revenue from quarterly EU AI Act attestation requirements. Build captive Fusion certification academies in Bangalore and Hyderabad to defend against talent scarcity inflating day rates. Vertical integration into sovereign cloud operations within Saudi Arabia and UAE dedicated regions secures government modernization program access. For New Entrants and Emerging Players: The mid-market price-point gap between premium Diamond partner offerings and economy remote support contracts creates white-space opportunity for specialized Oracle Health implementation practices targeting US hospital network consolidation. Template-based NetSuite deployments for German Mittelstand manufacturers offer fastest penetration path. Channel partnership with regional system integrators accelerates credential acquisition without multi-year certification cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with advisory-heavy consultancies embedding algorithmic governance frameworks into Oracle analytics environments. Long-term viability centers on recurring managed services annuities attached to Universal Credits consumption models. Monitor Oracle sovereign region deployment announcements as inflection indicator for localized implementation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Practice Buildout | Captures algorithmic governance advisory demand from Frankfurt and Paris banking centers. |
| Sovereign Cloud Partnership | Secures implementation credentials for Saudi SAMA-regulated bank modernization programs. |
| Fusion Certification Academy Investment | Addresses SCM and HCM specialization scarcity inflating Mumbai and Dallas day rates. |
| Autonomous Database Managed Services Launch | Attaches recurring revenue to consumption-based Universal Credits contracts. |
| Healthcare Vertical Specialization | Targets Texas Medical Center and Mayo Clinic EHR consolidation timelines. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and Middle East, with primary inputs from each region combined with secondary validation across regulatory filings and industry disclosures. Oracle services research incorporated interviews with cloud migration executives, IT procurement officers, Oracle partnership leads, and compliance advisory directors, triangulated against SEC 10-K filings, Oracle quarterly capex disclosures, EU AI Act implementation guidance, and BIS cloud standard certifications. Bottom-up project pipeline analysis and top-down market sizing were reconciled to produce volume and value estimates.
Rate-of-change decomposition across the projection horizon modeled service type, deployment model, end user scale, and industry vertical dimensions, with CAGRs derived from weighted average of historical trajectory and policy-driven step-change assumptions. Forecast inputs included Oracle sovereign region deployment schedules, EU AI Act enforcement timelines, and PLI scheme capacity expansion trajectories for Indian delivery centers.
Caveats apply where regulatory enforcement delays, talent pipeline expansion, or multi-cloud integration complexity could materially shift the outlook. Practitioners should monitor EU AI Act supervisory authority guidance, Oracle Gen2 infrastructure availability announcements, and Fusion certification graduate volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Maintenance Management Software Market
Software & Services
Global Virtualization Software Market
Software & Services
Global Website Builder Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Global User Interface Service Market
Software & Services
Tech Support Services Market
Software & Services
Global Directory Software Market
Software & Services
Load Testing Software Market
Software & Services
Preschool Education Software Market
Software & Services
Performing Arts Software Market
Software & Services
Photo Editing Software Market
Software & Services
Communication Software Market
Software & Services
Global Florist Software Market
Software & Services
Automotive Digital Retailing Software Market