
 Food Grade Glue Market | 2026-2036
Food Grade Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Glue Market Analytics
The EU Green Deal is pivoting food packaging adhesive procurement toward biodegradable and low-migration formulations. Henkel leverages its European R&D network to sustain leadership in compliant hot melt development. HB Fuller anchors North American supply through integrated resin production and direct food manufacturer relationships. 3M competes on technical service density, embedding specialists with major beverage labeling operations.
Food grade glue comprises adhesive systems formulated to meet direct and indirect food contact safety standards, typically exhibiting volatile organic compound limits below industrial grades and migration thresholds tested against fatty food simulants. These adhesives bond paperboard cartons, apply labels to glass and plastic containers, and seal flexible films while preventing chemical transfer to edible contents. Water-based formulations now dominate volume in primary packaging due to lower thermal stress on heat-sensitive substrates and favorable regulatory profiles. Hot melt adhesives represent the fastest-expanding category in high-speed labeling lines where set speed determines throughput economics. Biodegradable formulations within the natural and polymeric segments command premium positioning as European retailers enforce packaging circularity scorecards.
The FDA maintains 21 CFR 175.105 for indirect food contact adhesives while the EPA regulates volatile organic compound emissions from coating operations. EFSA migration testing protocols under EU regulation 10/2011 determine market access for imported adhesive systems. BIS certification requirements in India and China's GB 4806 food contact national standards create layered compliance obligations for multinational suppliers. Stakeholders must monitor evolving state-level extended producer responsibility laws and retailer-specific chemical disclosure mandates that increasingly override baseline regulatory compliance.
Market Dynamics
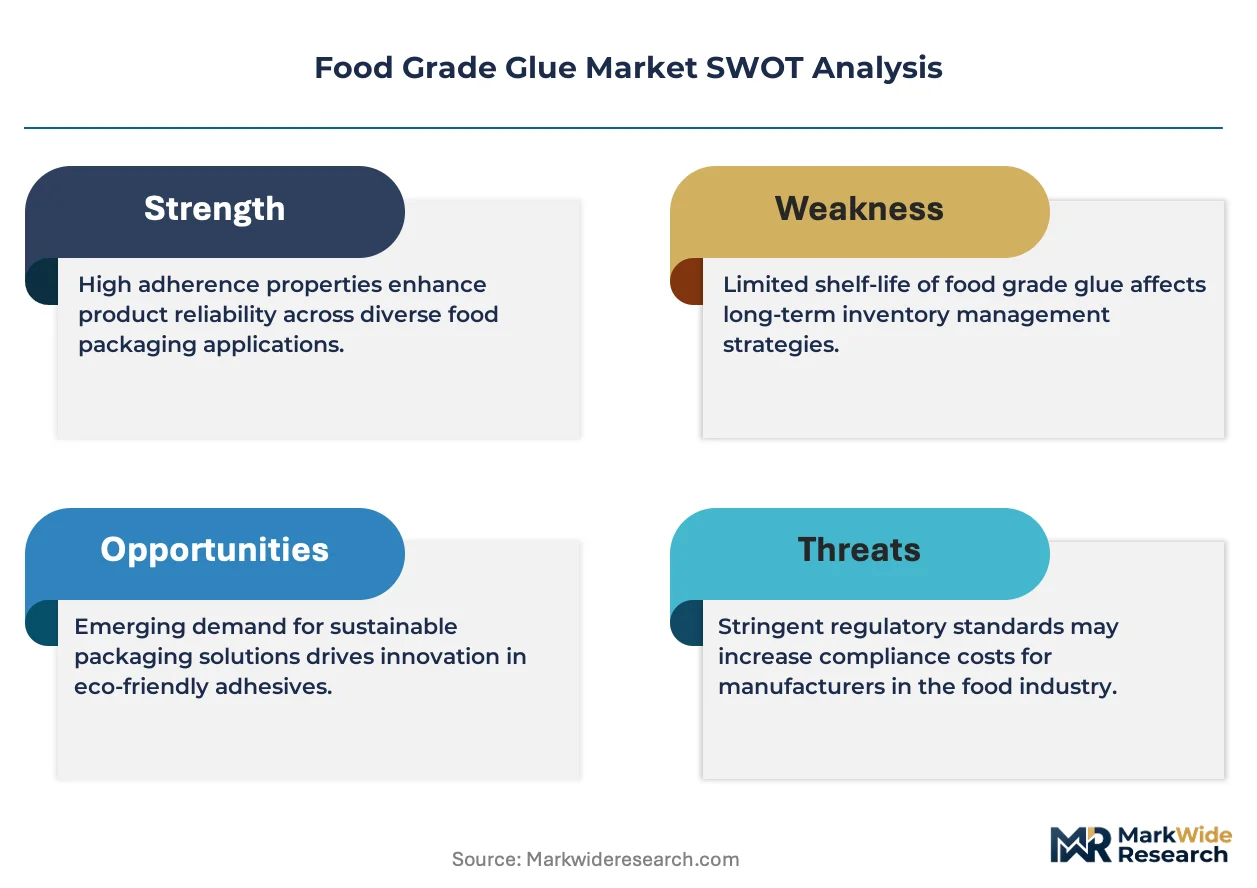
EU Green Deal packaging waste directives are forcing adhesive reformulation across European supply chains, compressing solvent-based systems while pulling biodegradable alternatives into mainstream procurement specifications.
Growth Catalysts
- Biodegradable Mandates:Retailer sustainability scorecards in Germany and France now require circularity certification for carton sealing adhesives, accelerating natural polymer adoption in flexible packaging lines.
- EFSA Migration Testing Harmonization:EU regulation 10/2011 standardization reduces compliance fragmentation for imported adhesive systems, streamlining market access for compliant Asian suppliers.
- High-Speed Labeling Economics:Hot melt set-speed advantages on beverage bottling lines above 60,000 units per hour are displacing water-based alternatives in carbonated soft drink operations.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene-vinyl acetate and metallocene polyolefin resin prices fluctuate with crude oil indices, compressing margins for hot melt compounders without captive polymer supply.
- Specialty Monomer Concentration:Three German chemical conglomerates control over 70% of food-grade tackifier resin supply, creating single-source vulnerability for mid-tier adhesive formulators.
- Migration Testing Burden:EFSA fatty food simulant protocols require 10-day incubation cycles and analytical chemistry capacity that excludes smaller regional blenders from premium segment participation.
Strategic Opportunities
- India BIS Certification Gap:Domestic food contact adhesive production lags behind FSSAI enforcement timelines, creating import substitution potential for EU-certified suppliers with localized blending capacity.
- Cellulose Nanocrystal Convergence:Reinforced biodegradable adhesives combining chitosan binders with nanocellulose structures offer performance parity with synthetic hot melts in frozen food carton applications.
- Direct Food Manufacturer Contracting:Brand owners in Netherlands and Belgium are bypassing packaging converters to specify adhesive chemistry directly, opening technical service relationships with formulators.
Industry Challenges
- Migration Chemist Scarcity:Analytical toxicologists capable of interpreting EFSA 10/2011 threshold calculations command salary premiums that strain mid-cap adhesive laboratory staffing.
- Legacy Equipment Retrofit Costs:Water-based adhesive transition requires tank cleaning systems and humidity-controlled storage that bottling plants built for solvent systems cannot accommodate without six-figure capital outlays.
- Dual Certification Complexity:Simultaneous FDA 21 CFR 175.105 and EFSA compliance demands parallel documentation streams that extend product development timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Glue Market |
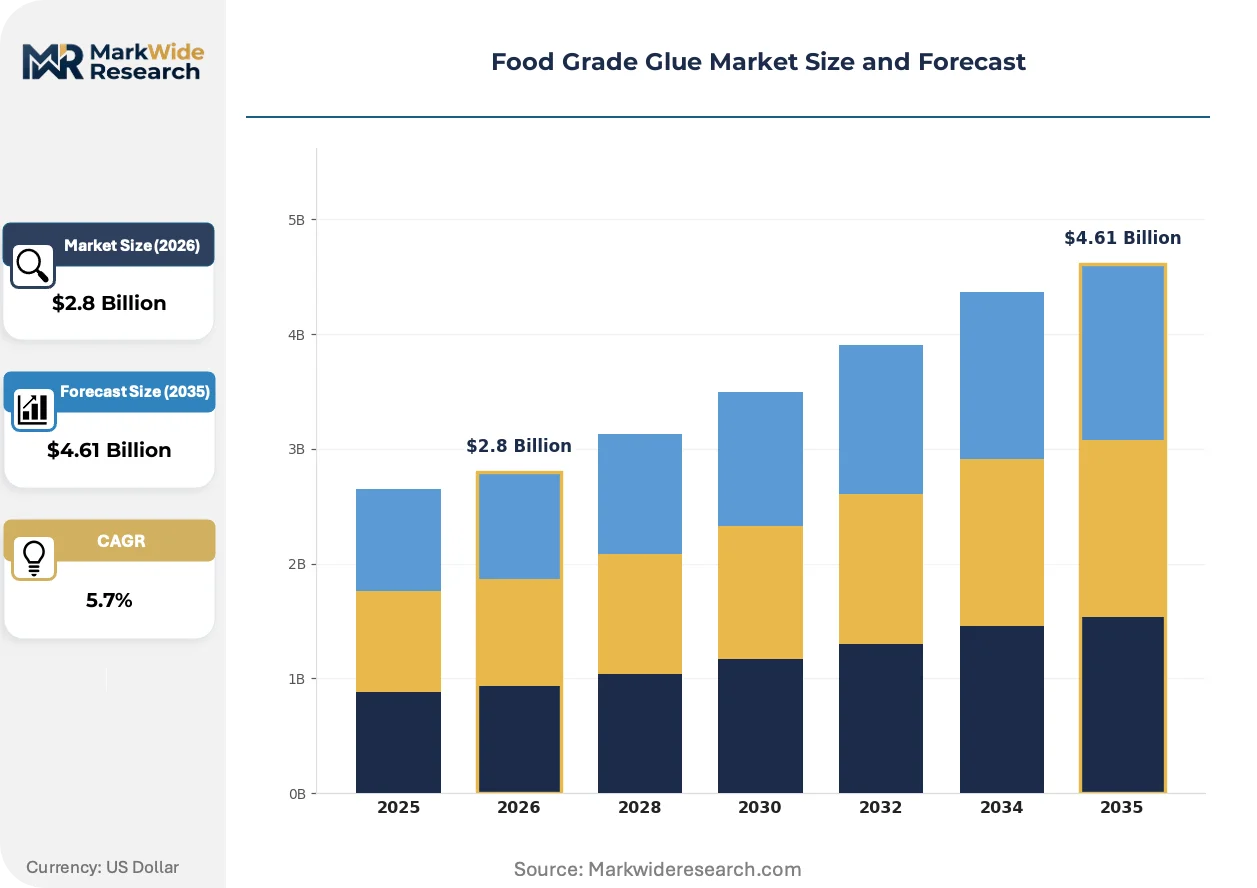
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Water-Based, Solvent-Based, Pressure-Sensitive Application: Food Packaging, Labeling, Sealing, Product Assembly Formulation: Polymeric, Natural, Synthetic, Biodegradable End User: Food Manufacturers, Food Processors, Retailers, Distributors |
| Companies Covered | Henkel, HB Fuller, Permabond, Master Bond, 3M, Intercol, LD Davis, Prostech, Kemtron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Glue Market Evolving Landscape
Adhesive chemistry is pivoting toward bio-based feedstocks while regulatory testing protocols harden migration thresholds. Formulators now compete on compliance documentation velocity as much as bond performance.
Starch-protein hybrid adhesives are absorbing market share in dry food carton sealing where moisture resistance requirements remain moderate. German bakery and breakfast cereal packagers have adopted these systems at scale since 2023. The technology is absorbing volume that synthetic ethylene-vinyl acetate hot melts previously dominated in ambient-stable applications.
REACH authorization requirements for diisocyanate-containing polyurethane adhesives took full effect in August 2023. Industrial users must now complete certified training before handling these chemistries, adding operational friction. Flexible film laminators in Italy and Spain are accelerating water-based acrylic and polyurethane dispersion adoption to eliminate respiratory hazard protocols.
Brand owner technical audits of adhesive suppliers have compressed from triennial to annual cycles. Major beverage and dairy processors in Denmark and Sweden now require real-time batch traceability data through supplier portals. This behavioral shift is most pronounced in private-label supply chains where retailer liability exposure concentrates compliance investment.
Food Grade Glue Market Segmentation
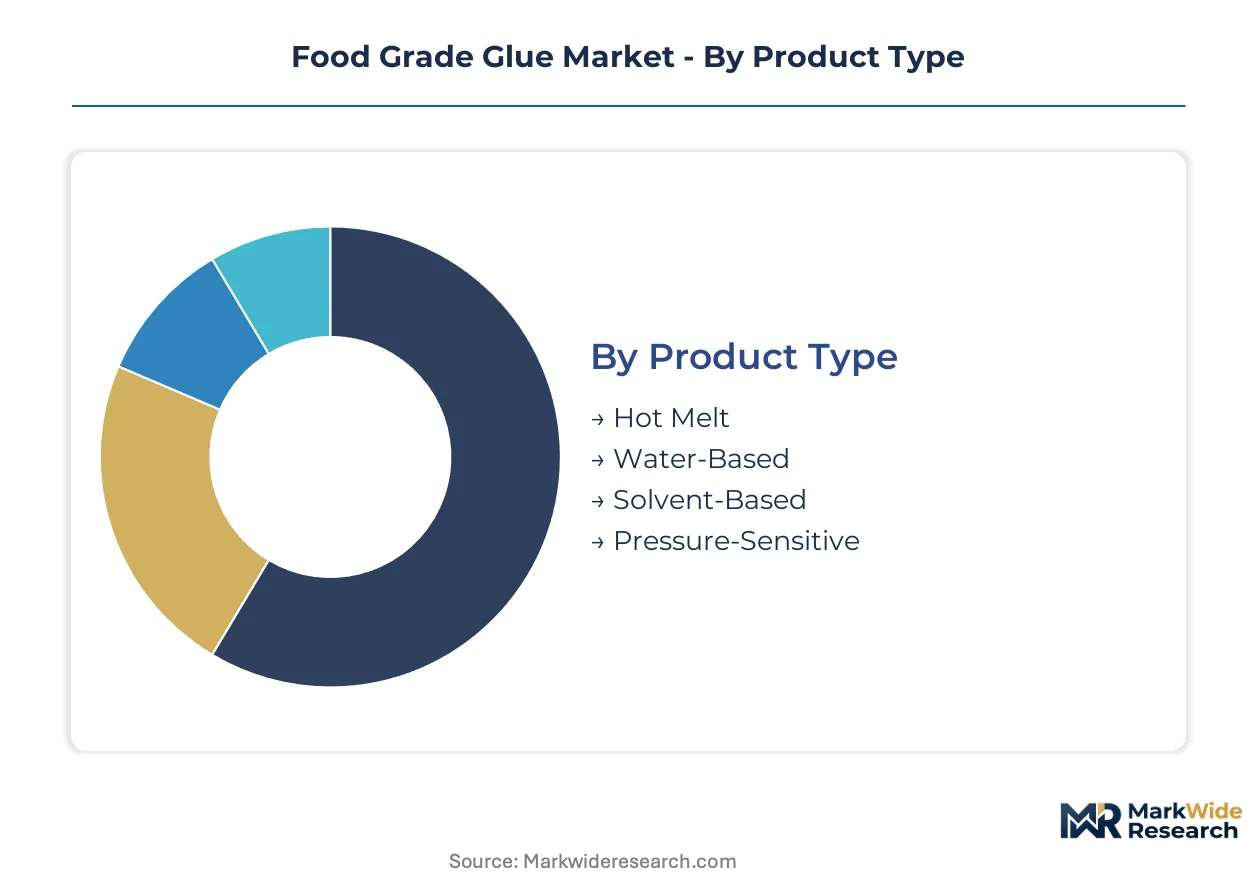
Adhesive specification tiers determine compliance pathways and procurement economics across food contact applications. Formulation chemistry, application method, and end-user scale each create distinct margin structures and technical service requirements.
Product Type:
Thermoplastic and aqueous chemistries diverge on set speed, thermal stress tolerance, and regulatory migration profiles.
- Hot Melt:Ethylene-vinyl acetate and metallocene polyolefin formulations dominate beverage labeling lines above 60,000 units per hour. German dairy and carbonated soft drink bottlers specify these systems for throughput economics where set speed determines line efficiency.
- Water-Based:Acrylic and polyurethane dispersions carry lower volatile organic compound profiles and reduced thermal stress on heat-sensitive substrates. Primary packaging converters in France and Netherlands have displaced solvent systems with these formulations to meet EU Green Deal packaging waste directives.
- Solvent-Based:Polyurethane and rubber-resin solutions persist in flexible film lamination where aggressive substrate bonding demands high initial tack.
- Pressure-Sensitive:Removable and permanent acrylic emulsions serve resealable food pouch and deli label applications.
Water-based formulations lead on scale; hot melt leads on momentum in high-speed bottling investments.
Application:
Primary versus secondary packaging creates divergent migration exposure and certification intensity.
- Food Packaging:Carton sealing for dry cereals, frozen foods, and ambient-ready meals demands compliance with EFSA fatty food simulant protocols. German bakery and breakfast cereal packagers have adopted starch-protein hybrid adhesives at scale since EFSA migration testing harmonization under EU regulation 10/2011.
- Labeling:Glass and plastic container decoration for beverages and condiments requires wet-out and adhesion across condensation-prone surfaces. Danish and Swedish dairy processors now mandate real-time batch traceability data through supplier portals for these applications.
- Sealing:Flexible film closure for snack foods and fresh produce balances peel strength with reseal functionality.
- Product Assembly:Equipment and utensil bonding for food service applications carries indirect contact compliance requirements.
Food packaging commands volume concentration; labeling shows steepest expansion trajectory from beverage line speed investments.
Formulation:
Feedstock origin determines biodegradability certification and circularity scorecard positioning.
- Biodegradable:Chitosan binders reinforced with cellulose nanocrystals offer performance parity with synthetic hot melts in frozen food carton applications. Retailer sustainability scorecards in Germany and France now require circularity certification, accelerating natural polymer adoption in flexible packaging lines.
- Polymeric:Ethylene-vinyl acetate, polyolefin, and polyurethane backbones deliver consistent rheology and thermal stability for automated dispensing equipment.
- Natural:Starch, dextrin, and casein derivatives serve dry food carton sealing where moisture resistance requirements remain moderate.
- Synthetic:Petrochemical-derived adhesives face margin pressure from ethylene-vinyl acetate and metallocene polyolefin resin price volatility tracking crude oil indices.
Synthetic formulations retain installed base dominance; biodegradable variants gain share fastest from retailer mandate compliance.
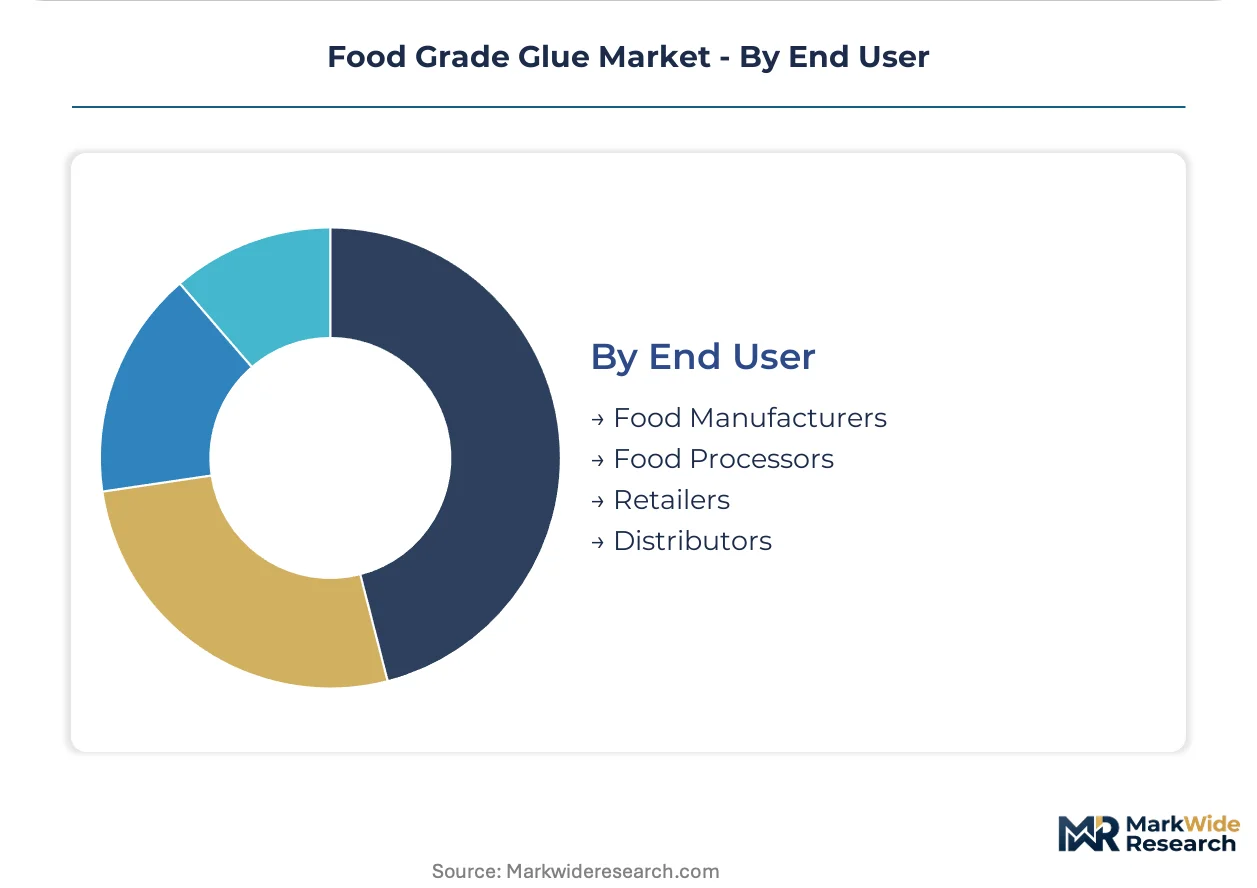
End User:
Procurement centralization and technical specification authority vary sharply across the value chain.
- Food Manufacturers:Brand owners in Netherlands and Belgium are bypassing packaging converters to specify adhesive chemistry directly, opening technical service relationships with formulators. These stakeholders carry liability exposure that concentrates compliance investment in private-label supply chains.
- Food Processors:Co-packing and toll processing operations prioritize adhesive interchangeability across multiple brand specifications.
- Retailers:German and French supermarket chains enforce packaging circularity scorecards that cascade adhesive requirements to their supplier bases.
- Distributors:Regional adhesive resellers serve smaller converters without direct formulator relationships.
Food manufacturers concentrate specification authority; retailers are accelerating compliance mandate velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial adhesive chemistry during the early twentieth century, establishing the technical foundation that European food packaging standards still reference. The EU Green Deal has since redirected this heritage toward biodegradable formulations and circular economy compliance.
Germany
Bavaria and North Rhine-Westphalia host the continent's densest concentration of adhesive formulators serving dairy and beverage bottlers. The EU Green Deal's packaging waste directives mandate EFSA-compliant migration thresholds that German converters now enforce across supplier scorecards. Henkel maintains its European R&D headquarters in Düsseldorf, anchoring compliant hot melt development for centralized continental procurement.
France
Paris Basin food manufacturers are bypassing packaging converters to specify adhesive chemistry directly, concentrating technical service relationships with formulators. REACH authorization requirements for diisocyanate-containing polyurethanes took full effect in August 2023, accelerating water-based acrylic adoption among flexible film laminators. Retailer sustainability scorecards from Carrefour and Auchan now require circularity certification for carton sealing adhesives.
United States
Midwest dairy processors and carbonated beverage bottlers drive hot melt demand on lines exceeding 60,000 units per hour. FDA 21 CFR 175.105 governs indirect food contact adhesives while EPA regulations limit volatile organic compound emissions from coating operations. HB Fuller anchors North American supply through integrated resin production facilities in Illinois and Minnesota.
India
Maharashtra and Gujarat food packaging converters face tightening FSSAI enforcement timelines that domestic adhesive production cannot yet satisfy. BIS certification requirements for food contact materials create import substitution openings for EU-certified suppliers establishing localized blending capacity. Mumbai-based distributors currently bridge supply gaps for mid-tier converters without direct formulator relationships.
China
Yangtze River Delta flexible packaging manufacturers confront GB 4806 national standards for food contact materials that layered compliance obligations onto multinational suppliers. The country's dual carbon goals are pressuring petrochemical-derived adhesive margins while pulling bio-based alternatives into procurement specifications. Shanghai converters are retrofitting legacy solvent-based equipment to accommodate water-based systems.
Food Grade Glue Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance documentation velocity and migration testing capacity. Three German chemical conglomerates control over seventy percent of food-grade tackifier resin supply, creating single-source vulnerability for mid-tier formulators. The competitive terrain stratifies into integrated polymer producers, specialized formulators with captive laboratory capacity, and regional distributors serving smaller converters. Dominant competitive moves include backward integration into resin production and direct contracting relationships with food manufacturers bypassing packaging intermediaries.
Within the integrated multinational tier, Henkel AG and HB Fuller Inc exemplify divergent geographic anchoring strategies. Henkel leverages its Düsseldorf-based European R&D network to sustain leadership in EFSA-compliant formulation development. HB Fuller anchors North American supply through in-house resin production and direct relationships with Midwest dairy and beverage processors. 3M Company competes on technical service density, embedding specialists with major bottling operations rather than pursuing formulator-scale chemistry. These three occupy distinct positions across the premium-to-standard margin spectrum.
| Leading Market Players |
|---|
| Henkel |
| HB Fuller |
| Permabond |
| Master Bond |
| 3M |
| Intercol |
| LD Davis |
| Prostech |
| Kemtron |
| Others |
Value Network & Pricing Analysis
Migration chemist scarcity in German analytical laboratories widens the labor-cost differential between EFSA-certified premium tiers and uncertified economy grades. This workforce concentration compresses margins for mid-tier formulators while concentrating pricing power with integrated players possessing captive laboratory capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA 10/2011 certified systems from FDA-only compliant grades and uncertified commodity alternatives. Price differentiation hinges on migration testing documentation velocity and captive resin production. Cost compression in the standard tier is intensifying because petrochemical feedstock volatility tracks crude oil indices without hedge protection. Small regional blenders exhibit highest price sensitivity due to EFSA fatty food simulant protocol exclusion, while multinational food manufacturers accept premium positioning for batch traceability guarantees.
Supply Chain Analysis
Single-source vulnerability sits with three German chemical conglomerates controlling over seventy percent of food-grade tackifier resin supply. Raw material dependencies draw from ethylene-vinyl acetate, metallocene polyolefin resins, and chitosan binders for biodegradable variants. Regulatory restriction risk concentrates in REACH authorization timelines for diisocyanate-containing polyurethane systems. Distribution runs through packaging converter intermediaries, though Dutch and Belgian food manufacturers are accelerating direct formulator contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal packaging waste directives continuously tighten compliance thresholds and reshape procurement specifications.
For Market Incumbents: To counter petrochemical feedstock volatility, pursue backward integration into captive resin production or secure long-term offtake agreements with German tackifier suppliers. Anchor EFSA 10/2011 certification investment in Düsseldorf and Bavaria R&D clusters to defend documentation velocity advantages against Asian competitors. For New Entrants and Emerging Players: Begin with BIS certification gap exploitation in Maharashtra and Gujarat, where domestic FSSAI enforcement outpaces local adhesive production capacity. Target flexible film lamination applications in Italy and Spain where REACH diisocyanate authorization is displacing incumbent polyurethane systems. Lead with water-based acrylic formulations to bypass respiratory hazard training requirements. For Investors and Strategic Acquirers: Adhesive formulators with integrated laboratory capacity are the most active acquirer in this space, consolidating mid-tier players excluded from premium segments by EFSA testing burden. Over a five-to-ten year horizon, acquisition targets should display cellulose nanocrystal R&D pipelines and established supplier portal traceability systems. Monitor German retailer circularity scorecard enforcement velocity as the decisive inflection signal for biodegradable formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA 10/2011 Certification Investment | Unlocks premium-tier pricing for fatty food simulant compliant systems in German dairy packaging. |
| Backward Integration into Tackifier Resin | Insulates margin compression from three-German-conglomerate supply concentration. |
| Cellulose Nanocrystal R&D Partnership | Delivers performance parity with synthetic hot melts for frozen food carton applications. |
| Direct Food Manufacturer Contracting | Bypasses packaging converter intermediaries in Netherlands and Belgium procurement channels. |
| India BIS Certification Localization | Captures import substitution potential as FSSAI enforcement tightens in Maharashtra. |
Research Methodology
Multiple input streams — primary interviews with adhesive formulator technical directors, packaging converter procurement leads, and food manufacturer quality assurance managers; secondary validation through EFSA migration testing protocols, EU Green Deal directive texts, and customs trade data — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments across product type, application method, formulation chemistry, and end-user procurement centralization dimensions. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic indicators and petrochemical feedstock price indices. Industry-specific forecast inputs included retailer sustainability scorecard adoption curves and REACH authorization timeline impacts on polyurethane adhesive displacement.
Caveats apply where EFSA migration threshold revisions, German tackifier supply disruptions, or India BIS enforcement acceleration could materially shift the outlook. Forecasts embed assumptions about regulatory harmonization velocity and bio-based feedstock cost parity timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Mexico Food Acidulants Market