
 Hospital Surgical Disinfectant Market | 2026-2036
Hospital Surgical Disinfectant Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Surgical Disinfectant Market Intelligence
Market Overview
North American chemical manufacturers are repositioning capacity toward EPA-registered hospital-grade formulations as outpatient surgical volumes climb. Ecolab Inc. leverages its institutional service infrastructure to sustain recurring revenue from large health systems. Steris plc anchors its position through radiation and sterilization technology leadership that extends into chemical disinfectant adjacencies. Kimberly-Clark Corporation competes in wipe-based delivery formats where its nonwoven material science differentiates against commodity alternatives.
Product and Segment Dynamics
Hospital surgical disinfectants are antimicrobial formulations engineered to eliminate vegetative bacteria, mycobacteria, fungi, and enveloped viruses on critical and semi-critical medical device surfaces, typically achieving ≥5-log reduction within standardized contact times. Hydrogen peroxide formulations are gaining share in operating room terminal cleaning protocols due to shorter ventilation requirements and favorable occupational exposure profiles. Alcohol-based products dominate pre-procedural skin preparation and small-surface disinfection where rapid evaporation and minimal residue are prioritized. Spray delivery systems command premium positioning in intensive care unit applications where aerosolized coverage of complex equipment geometries reduces manual wiping burden.
Regulatory Environment and Outlook
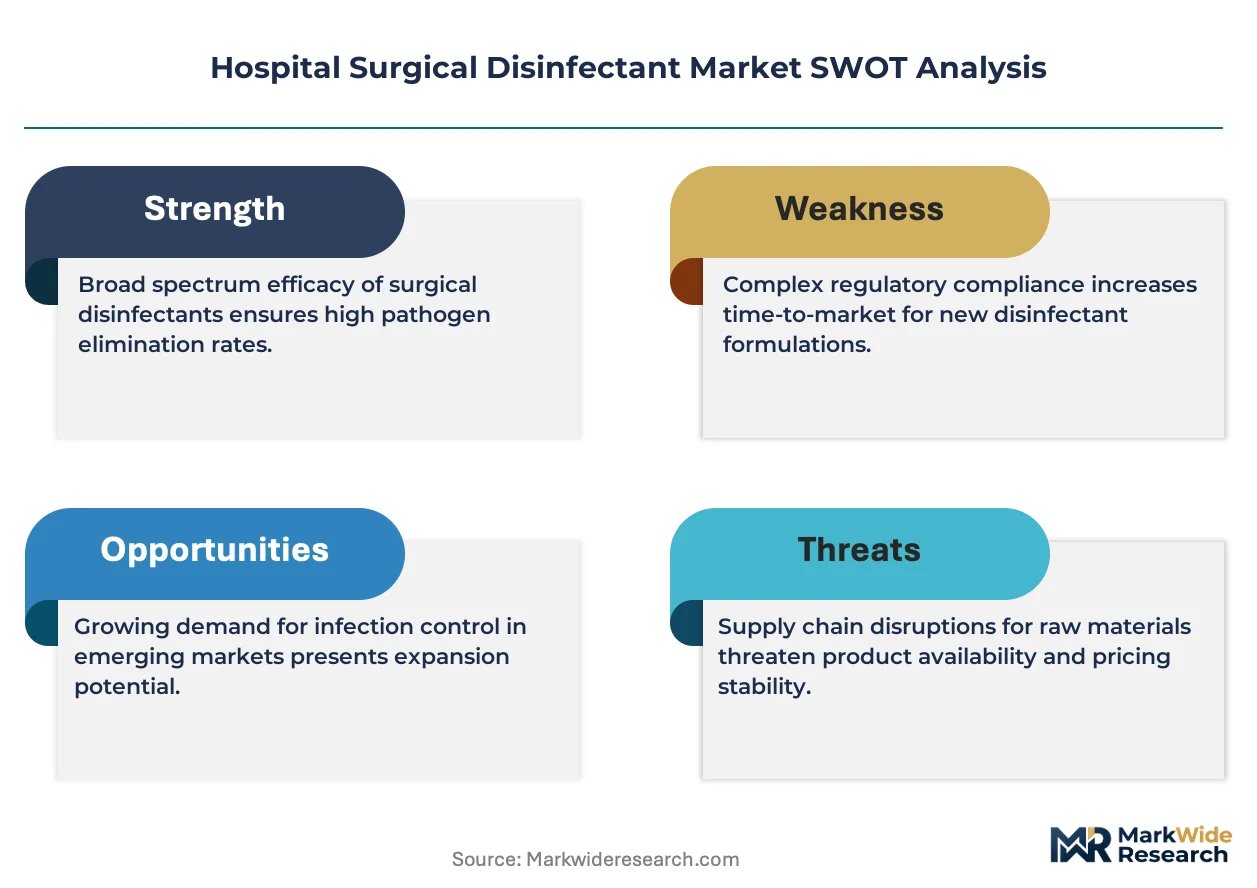
EPA regulates hospital disinfectants under FIFRA through efficacy data requirements against specified organism panels, while FDA oversees liquid chemical sterilants and high-level disinfectants for medical devices under 510(k) pathways. OSHA bloodborne pathogen standards and Joint Commission accreditation surveys enforce compliance documentation that drives replacement demand and premium product selection. Stakeholders must monitor evolving EPA emerging viral pathogen designations and state-level peracetic acid exposure limits that could reshape formulation portfolios and geographic manufacturing footprints.
Market Dynamics
EPA's emerging pathogen claims framework is compressing efficacy documentation timelines while accelerating formulation turnover, forcing manufacturers to maintain parallel R&D pipelines for novel chemistries against evolving organism panels.
Growth Catalysts
- Outpatient surgical volume expansion:Ambulatory surgical centers in the United States are scaling infection control procurement as procedure migration accelerates from inpatient settings.
- OSHA bloodborne pathogen enforcement:Joint Commission accreditation surveys are tightening compliance documentation requirements that drive replacement cycles and premium product selection.
- Hydrogen peroxide chemistry advancement:Shorter ventilation requirements and favorable occupational exposure profiles are displacing legacy quaternary ammonium formulations in operating room terminal cleaning.
Market Restraints
- Peracetic acid feedstock volatility:Concentrated acetic acid and hydrogen peroxide input costs fluctuate with industrial chemical commodity cycles, squeezing margin stability for sterilization-grade formulations.
- EPA registration concentration:Efficacy data requirements and label claim litigation risk concentrate viable manufacturing among entities with dedicated regulatory affairs infrastructure.
- Accelerated hydrogen peroxide limitations:Material compatibility constraints with anodized aluminum and certain polymers restrict deployment across the full medical device spectrum.
Strategic Opportunities
- India outpatient infrastructure buildout:Central government health scheme expansion is creating first-mover positioning for hospital-grade disinfectant registration under CDSCO and BIS frameworks.
- Electrolyzed water technology convergence:On-site generation systems are emerging as alternatives to shipped concentrate in large health systems seeking supply security.
- Spray delivery format penetration:Intensive care unit applications with complex equipment geometries present white space for aerosolized coverage reducing manual wiping labor.
Industry Challenges
- 510(k) pathway timeline compression:FDA liquid chemical sterilant premarket notification reviews are extending as novel antimicrobial chemistries require expanded biocompatibility data packages.
- Legacy quaternary ammonium decommissioning:Health systems face capital allocation decisions for inventory transition and staff retraining during formulation portfolio shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Surgical Disinfectant Market |
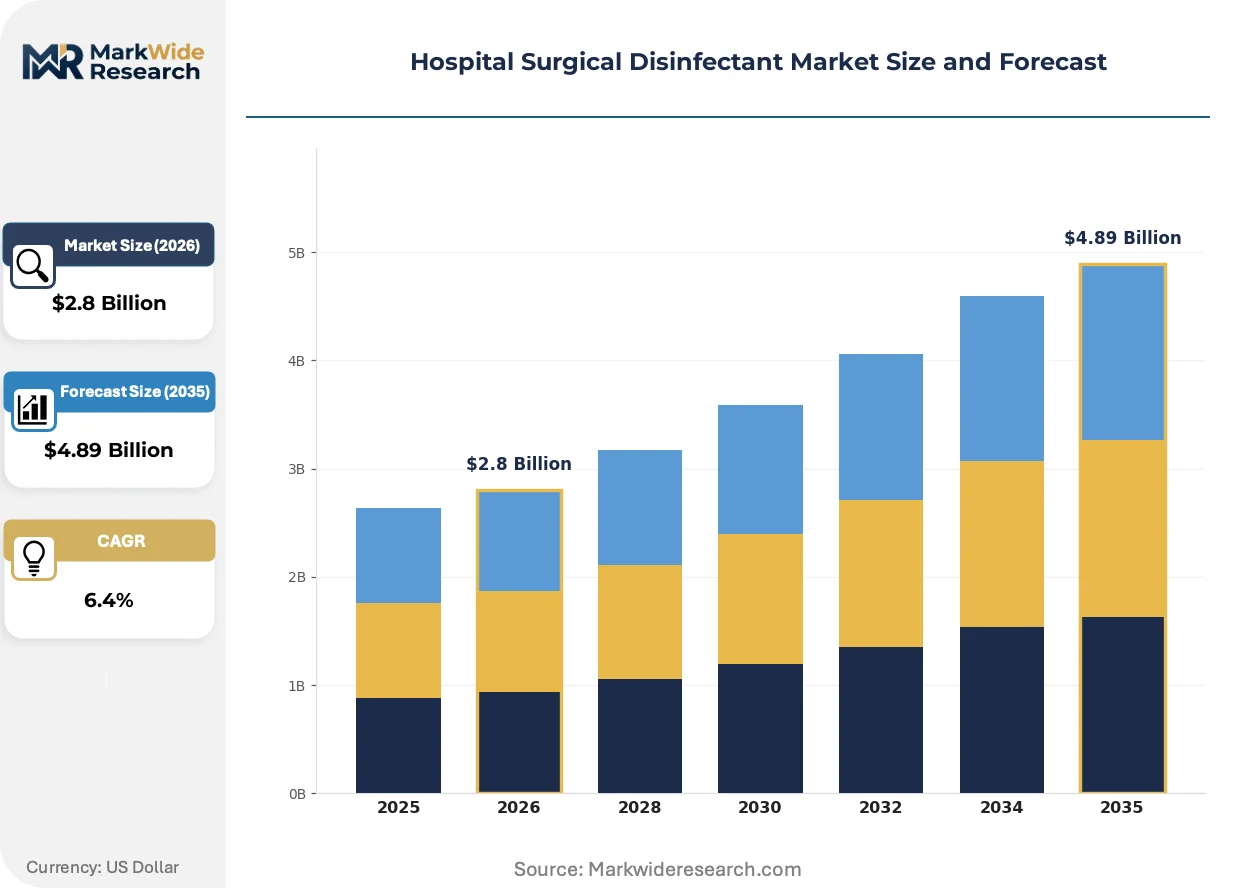
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-Based, Chlorine-Based, Quaternary Ammonium Compounds, Hydrogen Peroxide Application: Operating Rooms, Recovery Rooms, Intensive Care Units, Emergency Departments Delivery Mode: Spray, Wipe, Tablet, Liquid End User: Hospitals, Clinics, Surgical Centers, Long-Term Care Facilities |
| Companies Covered | 3M Company, Ecolab Inc., Reckitt Benckiser Group plc, Steris plc, Johnson & Johnson, Cardinal Health, Kimberly-Clark Corporation, The Clorox Company, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Surgical Disinfectant Market Strategic Shifts & Innovations
Formulation chemistry and delivery mechanism evolution is fragmenting the competitive landscape as legacy incumbents defend installed base against specialty entrants with targeted efficacy claims.
Accelerated hydrogen peroxide systems are converging with automated room disinfection hardware to enable terminal cleaning protocols without manual application labor. Large integrated delivery networks are piloting these combinations in orthopedic surgery suites where turnover time constraints are most acute. The technology pairing is compressing service contract structures toward bundled equipment-consumable arrangements.
EPA's emerging viral pathogen designation process is accelerating label claim expansion requirements for SARS-CoV-2 and subsequent respiratory virus threats. Manufacturers must maintain organism-specific kill data against evolving panels rather than relying on broad-spectrum surrogates. Hospital procurement committees are rewriting specifications to mandate documented emerging pathogen efficacy, favoring registrants with active surveillance infrastructure.
Health system procurement committees are consolidating supplier relationships from fragmented multi-vendor portfolios toward single-source infection prevention contracts. Group purchasing organizations are unbundling commodity wipe formats from premium chemistries to capture transparency in true product costs. This concentration is most visible in the United States where Medicare reimbursement pressure is forcing operational standardization across formerly autonomous facility purchasing.
Hospital Surgical Disinfectant Market Segmentation
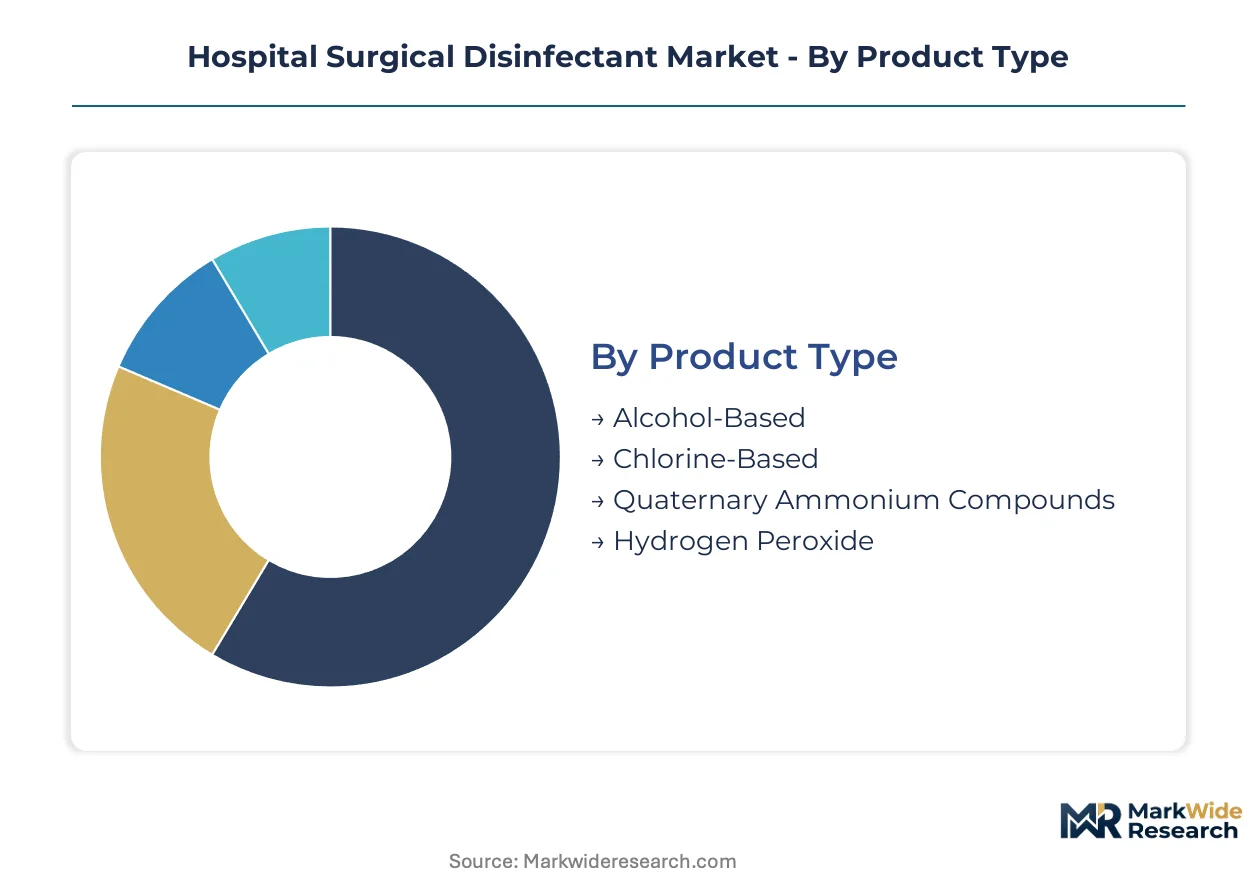
Segmentation in hospital surgical disinfectants reveals how procurement priorities diverge across clinical settings, chemistry preferences, and application methods. Understanding these fault lines exposes where formulation innovation meets operational constraints and where regulatory compliance reshapes supplier selection.
Product Type:
Buyers in this category differentiate primarily by contact time requirements, material compatibility constraints, and ventilation infrastructure limitations.
- Hydrogen Peroxide:Accelerated formulations achieve sporicidal efficacy with reduced ventilation downtime, making them preferred for operating room terminal cleaning where turnover pressure is acute. Demand concentrates in United States academic medical centers replacing legacy chemistries under Joint Commission pressure.
- Alcohol-Based:Ethanol and isopropanol blends dominate pre-procedural skin preparation and small-surface disinfection with rapid evaporation and minimal residue. Procurement clusters in ambulatory surgical centers prioritizing speed over broad-spectrum claims.
- Chlorine-Based:Sodium hypochlorite formulations retain cost-sensitive positioning for environmental surface disinfection in emergency departments.
- Quaternary Ammonium Compounds:Legacy QAC formulations face decommissioning as EPA emerging pathogen documentation requirements expose efficacy gaps against non-enveloped viruses.
Volume sits with quaternary ammonium compounds in legacy installed base; growth tilts toward hydrogen peroxide.
Application:
Clinical environment determines disinfection intensity, with criticality of surfaces and patient vulnerability dictating chemistry selection and documentation burden.
- Operating Rooms:Terminal cleaning protocols demand sporicidal efficacy against Clostridioides difficile and surgical site infection prevention. United States health systems are consolidating procurement around hydrogen peroxide systems with automated dispensing verification.
- Intensive Care Units:Complex equipment geometries and ventilator-dependent patients drive demand for spray delivery formats with aerosolized coverage reducing manual wiping labor. Procurement specifications increasingly mandate material compatibility with anodized aluminum and polymer housings.
- Emergency Departments:High-throughput, high-variability environments favor rapid-acting alcohol-based products for equipment turnover between cases.
- Recovery Rooms:Lower-risk surfaces accept intermediate-level disinfectants with shorter contact times prioritizing patient flow efficiency.
Revenue concentrates in operating rooms; expansion accelerates fastest in intensive care units.
Delivery Mode:
Operational labor costs and surface geometry complexity separate buyers willing to pay premium positioning from those optimizing per-application economics.
- Spray:Aerosolized delivery commands premium pricing in intensive care and operating room applications where equipment complexity defies efficient manual wiping. United States group purchasing organizations are unbundling spray formats from commodity wipe portfolios to capture true cost transparency.
- Wipe:Saturated nonwoven substrates dominate high-frequency, low-complexity surface disinfection in emergency departments and recovery rooms. Material science differentiation in substrate construction separates premium positioning from commodity alternatives.
- Liquid:Bulk concentrate formats serve automated dilution systems in large health systems with captive environmental services infrastructure.
- Tablet:On-site reconstitution formats address supply security concerns and shipping cost optimization for remote or international facilities.
Installed base favors liquid concentrates; spray formats gain share fastest in labor-constrained settings.
End User:
Capital intensity and regulatory scrutiny scale inversely with facility size, fragmenting procurement authority and supplier relationship structures.
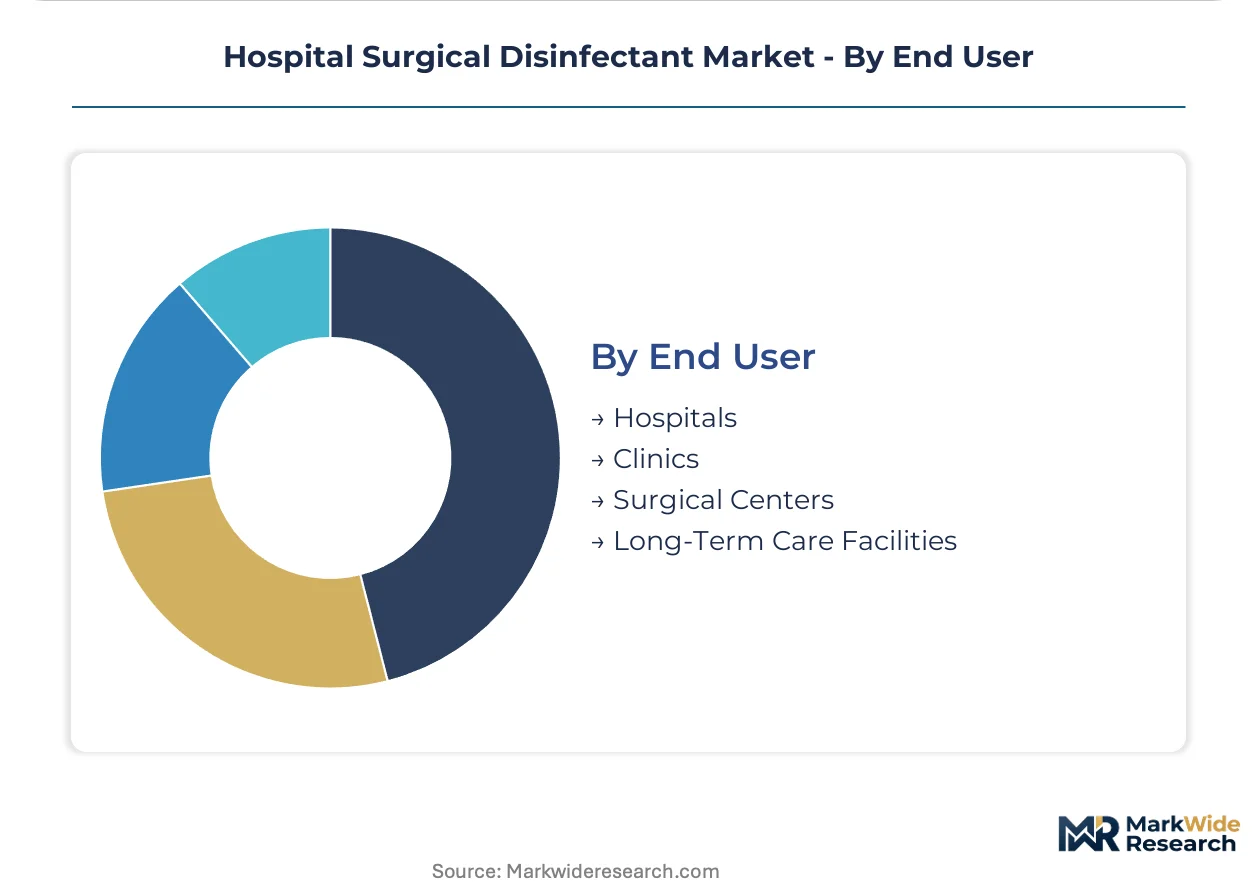
- Surgical Centers:Ambulatory facilities in the United States are scaling infection control procurement fastest as procedure migration from inpatient settings accelerates. Group purchasing organization consolidation is standardizing previously autonomous purchasing decisions.
- Hospitals:Large integrated delivery networks negotiate enterprise-wide infection prevention contracts bundling chemistries, equipment, and service verification. Joint Commission accreditation surveys enforce documentation compliance that drives premium product selection.
- Clinics:Lower-acuity settings prioritize cost efficiency and storage stability over broad-spectrum efficacy claims.
- Long-Term Care Facilities:Resident vulnerability to multidrug-resistant organisms drives demand, though reimbursement constraints limit chemistry premium tolerance.
Procurement volume aggregates in hospitals; surgical centers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial hydrogen peroxide production clusters in the United States Gulf Coast and Germany's Rhine-Ruhr corridor anchor raw material supply for hospital-grade disinfectant formulation. These feedstock localities shape regional manufacturing footprints and regulatory compliance specialization.
United States
Ambulatory surgical centers in Texas and Florida are scaling infection control procurement fastest as outpatient procedure volumes climb. EPA's emerging pathogen claims framework under FIFRA compresses efficacy documentation timelines for novel chemistries. The Houston-Galveston chemical manufacturing corridor concentrates hydrogen peroxide production capacity serving domestic hospital-grade formulation demand.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia drive demand for sporicidal formulations with automated dispensing verification. ECHA REACH compliance requirements for biocidal products under BPR reshape formulation portfolios and label claim documentation. The Ludwigshafen chemical cluster anchors industrial peroxide supply for sterilization-grade disinfectant manufacturing.
India
Central government health scheme expansion is creating first-mover positioning for hospital-grade disinfectant registration under CDSCO and BIS frameworks. Ayushman Bharat infrastructure buildout in tier-2 cities accelerates procurement standardization for infection control products. The Gujarat pharmaceutical manufacturing belt concentrates formulation capacity targeting domestic outpatient surgical center demand.
Japan
Metropolitan Tokyo hospital networks prioritize material compatibility specifications for anodized aluminum and polymer medical device surfaces. PMDA oversight of liquid chemical sterilants under Pharmaceuticals and Medical Devices Act enforces expanded biocompatibility data requirements. The Kansai industrial corridor around Osaka hosts specialty chemical production for healthcare disinfectant applications.
China
Provincial hospital procurement consolidation in Jiangsu and Guangdong provinces drives volume aggregation for infection prevention contracts. NMPA registration pathways for high-level disinfectants under medical device regulations tighten efficacy documentation standards. The Yangtze River Delta chemical manufacturing zone supplies hydrogen peroxide feedstock for domestic hospital-grade formulation production.
Hospital Surgical Disinfectant Market Key Industry Players
Global majors compete with regional champions across regulatory affairs infrastructure and institutional service networks. Market structure tilts toward consolidation among entities with dedicated EPA registration capabilities and FDA 510(k) submission experience. Three archetypes dominate: diversified chemical conglomerates with healthcare divisions, infection prevention specialists with bundled equipment-consumable offerings, and material science companies leveraging nonwoven substrate differentiation. Competitive moves concentrate on M&A for regulatory asset accumulation and geographic expansion through CDSCO and BIS registration in India.
Among diversified industrial players, 3M Company and Ecolab Inc. exemplify the regulatory-heavy archetype with institutional service infrastructure sustaining recurring revenue from large health systems. Steris plc anchors the infection prevention specialist tier through sterilization technology adjacencies extending into chemical disinfectant portfolios. Reckitt Benckiser Group plc occupies a position bridging consumer health branding with hospital-grade efficacy claims.
| Leading Market Players |
|---|
| 3M Company |
| Ecolab Inc. |
| Reckitt Benckiser Group plc |
| Steris plc |
| Johnson & Johnson |
| Cardinal Health |
| Kimberly-Clark Corporation |
| The Clorox Company |
| Getinge AB |
| Others |
Cost & Logistics Intelligence
Group purchasing organization consolidation in United States health systems is forcing suppliers to unbundle equipment-consumable contracts and absorb service verification costs, compressing margins on legacy quaternary ammonium formulations while creating premium capture opportunities for hydrogen peroxide systems with automated dispensing infrastructure.
Pricing Analysis
Service bundling and unbundling decisions separate premium positioning from commodity capture in this market. Three-tier pricing structure across premium, standard, and economy levels reflects EPA registration tier, material compatibility breadth, and after-sales technical support inclusion. Cost compression in economy-tier wipes is intensifying because GPOs are demanding line-item transparency previously obscured in bundled contracts. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while academic medical centers prioritize efficacy documentation over per-unit cost.
Supply Chain Analysis
Hydrogen peroxide feedstock supply rests on industrial chemical production clusters in the United States Gulf Coast and Germany's Rhine-Ruhr corridor. Concentrated acetic acid and hydrogen peroxide inputs draw from petrochemical and chlor-alkali co-production streams, with sterilization-grade formulations requiring pharmaceutical-grade purity certification. Single-source vulnerability concentrates in Texas-Louisiana corridor exposure to hurricane disruption. Distribution runs through institutional service networks and GPO contracts rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is executing a chemistry-transition phase as accelerated hydrogen peroxide systems displace legacy quaternary ammonium compounds under EPA emerging pathogen documentation pressure.
For Market Incumbents: Deploy regulatory affairs infrastructure as the primary defensive lever. Accumulate CDSCO and BIS registrations in India ahead of Ayushman Bharat infrastructure buildout completion. Secure backward integration into hydrogen peroxide feedstock through offtake agreements with Gulf Coast producers to defend margin position against commodity volatility. For New Entrants and Emerging Players: Direct-to-GPO digital procurement platforms offer the lowest-friction entry vector for specialty chemistry registrants. Target intensive care unit spray format applications where aerosolized coverage specifications remain underpenetrated by incumbent wipe-dominant portfolios. Lead with material compatibility data packages for anodized aluminum and polymer medical device surfaces. For Investors and Strategic Acquirers: Re-rating potential sits with infection prevention specialists possessing FDA 510(k) submission track records given accelerating liquid chemical sterilant review timelines. Long-term viability favors entities with parallel EPA-FDA regulatory capabilities across the analysis window. Watch EPA emerging viral pathogen designation velocity as the inflection signal for formulation portfolio turnover speed.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Accumulation | CDSCO and BIS registrations in India capture first-mover positioning under Ayushman Bharat expansion. |
| Backward Integration | Captive hydrogen peroxide supply agreements with Gulf Coast producers insulate margin from acetic acid volatility. |
| Automated Dispensing Partnership | Hardware-consumable bundles in orthopedic surgery suites compress turnover time and lock in recurring revenue. |
| Spray Format Development | Aerosolized coverage specifications for ICU equipment geometries address labor-constrained health system demand. |
| Material Compatibility Expansion | Anodized aluminum and polymer surface data packages differentiate against hydrogen peroxide compatibility limitations. |
Research Approach
EPA registration databases, FDA 510(k) premarket notification filings, and hospital procurement contract disclosures formed the secondary backbone for this analysis. Primary interviews with infection prevention directors, GPO contracts managers, environmental services executives, and regulatory affairs specialists at formulation manufacturers were synthesized with customs trade data and chemical industry capacity reports. Bottom-up facility-level procurement estimates and top-down chemical production volume analysis were triangulated to derive market sizing.
Bottom-up modeling anchored the analytical lens, with segmentation across chemistry type, delivery format, clinical application, and end-user facility tier. CAGRs were computed from installed base replacement cycles and outpatient surgical volume migration trends. EPA emerging pathogen claim velocity and FDA review timeline extension patterns served as industry-specific forecast inputs throughout the projection horizon.
The model holds under stable EPA-FDA regulatory convergence; deviation in emerging pathogen designation frequency or state-level peracetic acid exposure limit tightening would shift formulation portfolio demand. Forecasts reflect documented assumptions about outpatient procedure migration speed and GPO consolidation trajectory. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Global Mold Inhibitors Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market