
 Europe Agricultural Disinfectants Market | 2026-2036
Europe Agricultural Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Disinfectants Market Foresight
Peracetic acid is expanding its share in Europe's agricultural disinfectant formulations, displacing legacy chlorine-based chemistries in dairy and greenhouse applications. Lanxess leverages its integrated peracetic acid supply chain to anchor pricing power across German livestock operations. Kersia Group specializes in veterinary biosecurity protocols, sustaining premium positioning in French and Benelux dairy markets. Neogen Corporation competes through diagnostic-linked hygiene programs, extending its footprint beyond standalone disinfectant sales.
Europe agricultural disinfectants comprise antimicrobial formulations designed to eliminate or suppress pathogenic microorganisms on crop surfaces, livestock housing, and farm equipment, typically containing active concentrations of quaternary ammonium compounds, peracetic acid, or hydrogen peroxide measured in parts per million for efficacy validation. Their primary commercial purpose centers on preventing zoonotic and phytopathogenic transmission chains that threaten yield integrity and food safety compliance across integrated supply chains. Liquid formulations dominate volume throughput due to spray-application compatibility and dilution flexibility, while hydrogen peroxide-based chemistries capture the fastest growth trajectory as operators phase out chlorinated residuals ahead of REACH authorization reviews. Quaternary ammonium compounds retain entrenched positions in surface disinfection protocols where prolonged antimicrobial film persistence justifies higher unit dosing costs.
The European Chemicals Agency oversees biocidal product regulation under the BPR framework, conditioning market access on active substance approval timelines that now stretch across multiple review cycles. EFSA residue limits and the EU Green Deal's pesticide reduction targets are forcing reformulation investments, particularly for chlorine-dependent product lines facing authorization uncertainty. National regulators in Germany, France, and Spain enforce divergent veterinary hygiene inspection frequencies, creating compliance fragmentation that favors multi-registration portfolios. Stakeholders must monitor BPR renewal schedules for quaternary ammonium compounds and peracetic acid, as withdrawal or restriction decisions would trigger immediate portfolio restructuring across the continent's largest agricultural economies.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing biocide approval timelines and forcing active substance substitution across European livestock and horticulture operations. This regulatory pressure is restructuring procurement priorities and reformulation investments continent-wide.
Growth Catalysts
- REACH authorization pressure:Chlorine-based chemistries face withdrawal risk, redirecting R&D budgets toward peracetic acid and hydrogen peroxide platforms in German and Dutch manufacturing.
- Intensive dairy biosecurity:German, French, and Dutch livestock operations are mandating stricter housing disinfection protocols to suppress mastitis and zoonotic transmission chains.
- Greenhouse horticulture density:Netherlands concentration of protected cropping exceeds regional averages, sustaining concentrated demand for crop-surface sanitization.
Market Restraints
- Acetic acid feedstock volatility:Peracetic acid production costs fluctuate with petrochemical and bio-based acetic acid supply disruptions.
- BPR multi-cycle review timelines:European Chemicals Agency authorization processes now extend across sequential assessment periods, freezing portfolio decisions.
- Quaternary ammonium residue persistence:Prolonged environmental half-lives trigger EFSA scrutiny and limit application flexibility in water-sensitive catchments.
Strategic Opportunities
- Spanish livestock expansion:Underpenetrated intensive pork and poultry operations in Aragon and Catalonia present volume growth potential for veterinary hygiene protocols.
- Diagnostic-linked service models:Pathogen testing integration with disinfection scheduling creates subscription revenue streams beyond commodity chemical sales.
- EU Green Deal compliance premiums:Biocide products meeting Farm to Fork sustainability criteria command preferential positioning in public procurement frameworks.
Industry Challenges
- Multi-registration portfolio complexity:Divergent national veterinary inspection frequencies across Germany, France, and Spain fragment compliance workflows and inflate regulatory staffing.
- Legacy chlorine infrastructure lock-in:Existing dosing equipment and operator training investments slow transition timelines to peroxygen-based chemistries despite authorization risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Disinfectants Market |
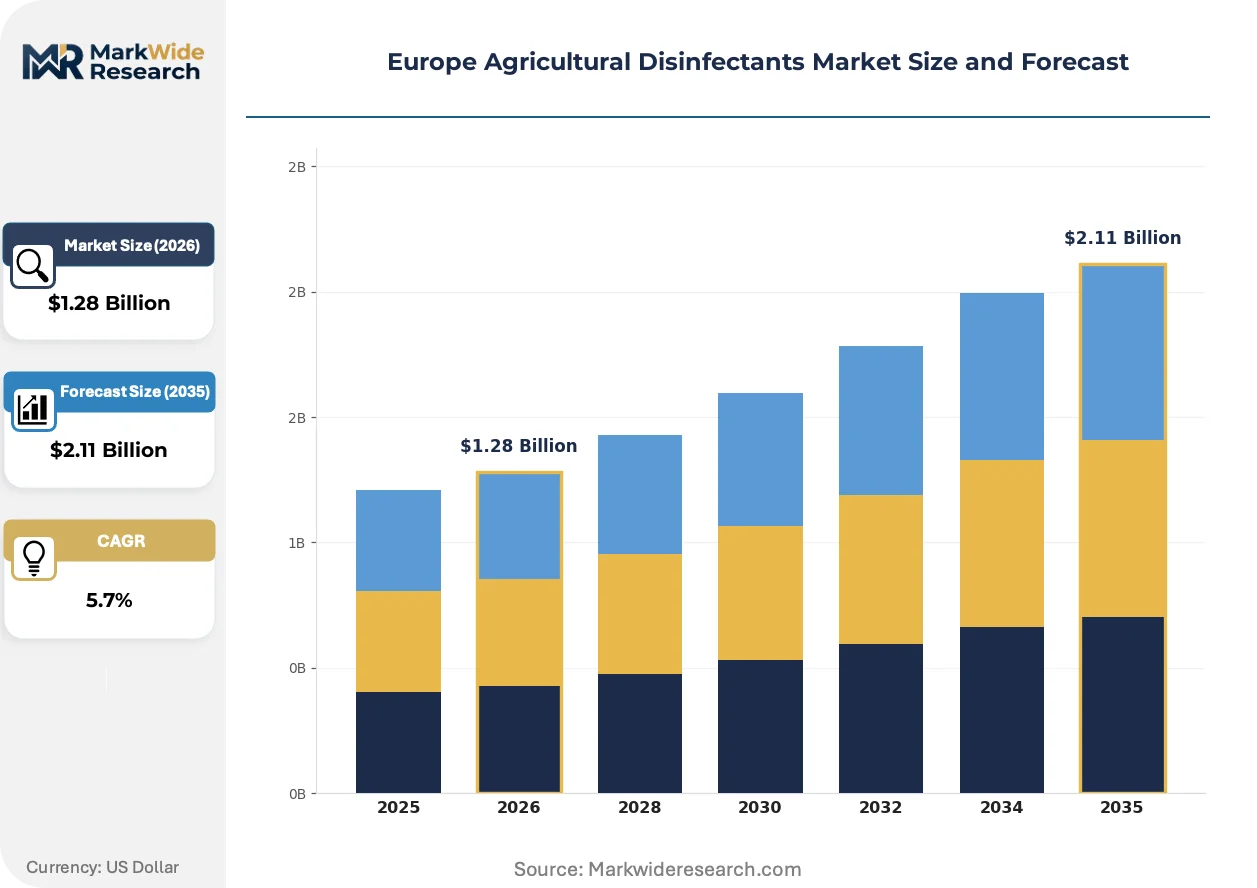
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Foam Application: Crop Protection, Surface Disinfection, Equipment Sanitization, Livestock Hygiene Active Ingredient: Quaternary Ammonium Compounds, Chlorine-Based, Peracetic Acid, Hydrogen Peroxide End User: Agricultural Producers, Greenhouses, Dairy Farms, Veterinary Clinics |
| Companies Covered | FINK TEC GmbH, Nufarm Ltd, Stepan Company, Entaco NV (Nerta), Neogen Corporation, Lanxess, The Chemours Company, Zoetis, Kersia Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Disinfectants Market Shifts & Advancements
Formulation chemistry and service delivery models are converging around sustainability credentials and precision application. Three developments are compressing competitive timelines and reshaping buyer-supplier relationships.
Peracetic acid-based formulations are overtaking legacy chlorine chemistries in dairy parlour and greenhouse applications. Dutch greenhouse operators and German dairy cooperatives are adopting these chemistries at accelerating rates to preempt REACH authorization uncertainty. This transition is compressing margin structures for commodity chlorine producers while rewarding integrated peroxygen manufacturers with pricing power.
ECHA's BPR renewal schedule for quaternary ammonium compounds is forcing portfolio diversification investments. Active substance review delays are extending commercial uncertainty for surface disinfection suppliers dependent on QAC persistence properties. French and Benelux formulators are accelerating hydrogen peroxide blend development to hedge against potential QAC restriction decisions.
Integrated hygiene service contracts are displacing standalone chemical procurement in large livestock operations. German dairy cooperatives and Dutch poultry integrators are bundling diagnostic testing, application equipment, and chemical supply under multi-year agreements. This bundling is most advanced in the Netherlands, where veterinary biosecurity standards exceed regional baselines and favor consolidated supplier relationships.
Europe Agricultural Disinfectants Market Segmentation
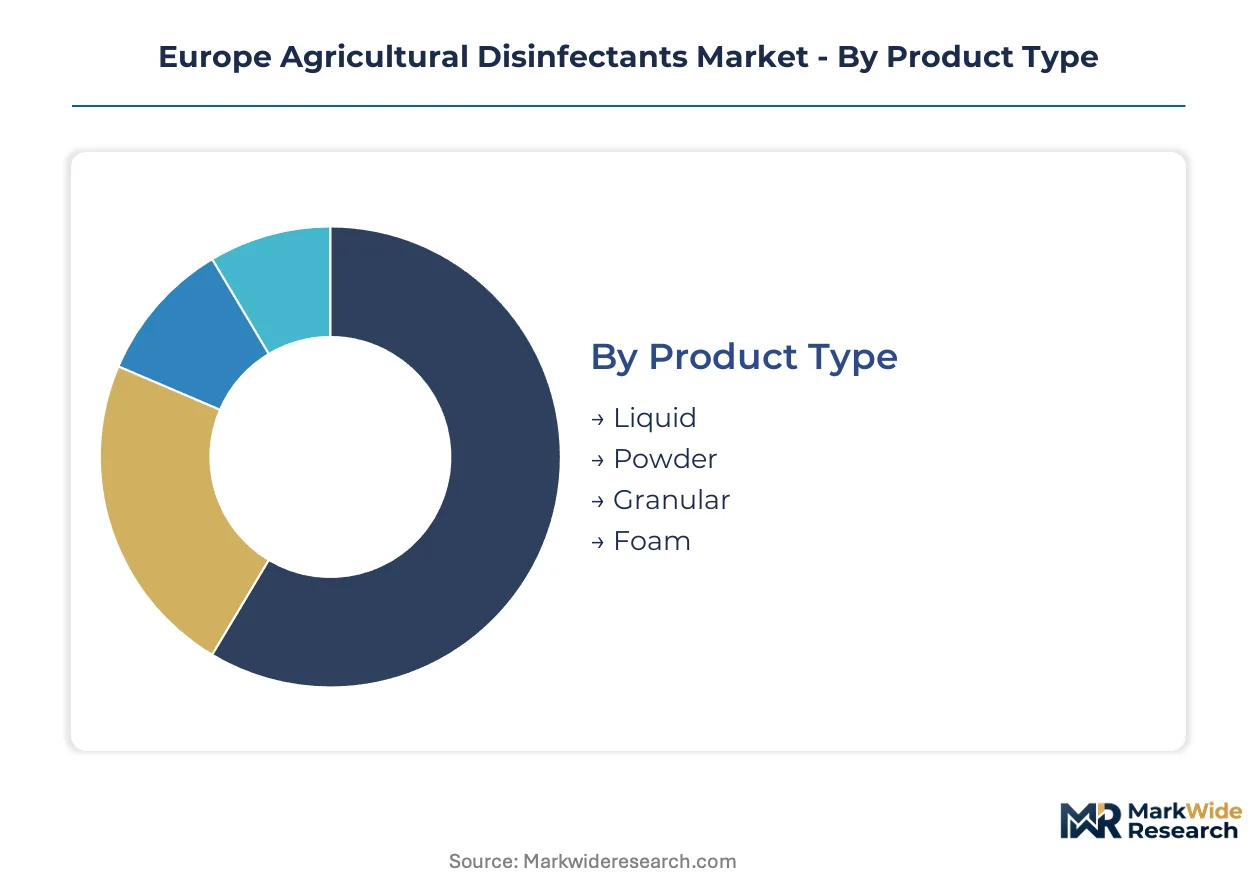
Segmentation in Europe's agricultural disinfectants market reveals how formulation chemistry, application protocol, and end-use biosecurity requirements intersect to determine procurement patterns. Dutch greenhouse operators, German dairy cooperatives, and French livestock integrators each demand distinct product configurations that resist one-size-fits-all positioning.
Product Type:
Standalone liquid formulations dominate procurement volumes through spray-application compatibility and dilution flexibility, while powder and granular chemistries embed into automated dosing systems where precise metering matters.
- Liquid:Aqueous solutions containing dissolved active ingredients enable variable dilution ratios and compatibility with existing farm spray infrastructure. German dairy parlours and Dutch greenhouse operations concentrate procurement here due to equipment retrofit avoidance and operator familiarity. REACH authorization pressure on chlorine residuals is accelerating peracetic acid liquid adoption ahead of equipment replacement cycles.
- Powder:Dry concentrate formulations require dissolution prior to application but offer transport cost advantages and extended shelf stability. French livestock operations in Brittany and Normandy favor powder chemistries for remote farm locations where liquid bulk delivery infrastructure remains underdeveloped. Storage footprint reduction drives procurement in space-constrained veterinary facilities.
- Granular:Slow-release solid formulations deliver sustained antimicrobial activity across extended surface contact periods. Spanish pork operations in Aragon deploy granular products in slurry pit and bedding applications where prolonged environmental persistence justifies higher unit dosing costs.
- Foam:Viscous expanded formulations cling to vertical surfaces and equipment crevices that liquid sprays fail to penetrate. Belgian poultry integrators specify foam chemistries for hatchery and processing facility deep cleans where complete surface coverage determines pathogen elimination efficacy.
Liquid leads volumes today; foam is gaining share fastest.
Application:
Cost tier differentiation separates commodity surface disinfection from premium livestock hygiene protocols where diagnostic-linked service bundles command pricing power.
- Crop Protection:Foliar and soil-surface treatments targeting phytopathogenic fungi, bacteria, and viruses in protected cropping environments. Netherlands greenhouse density sustains concentrated demand where EFSA residue limits and EU Green Deal pesticide reduction targets force active substance substitution toward peroxygen-based platforms.
- Surface Disinfection:Hard-surface treatments for farm buildings, storage facilities, and processing equipment using quaternary ammonium compounds or hydrogen peroxide blends. German and French dairy operations mandate frequent housing disinfection to suppress mastitis transmission chains and comply with national veterinary inspection frequencies.
- Equipment Sanitization:Cleaning-in-place and manual washdown protocols for milking machines, harvesting equipment, and processing lines. Dairy cooperatives across Denmark and Ireland prioritize equipment-focused chemistries that minimize corrosion damage to stainless steel infrastructure while maintaining microbial elimination standards.
- Livestock Hygiene:Direct animal housing, transport vehicle, and veterinary facility treatments addressing zoonotic pathogen reservoirs. French and Benelux markets sustain premium positioning here through bundled diagnostic testing and scheduled application services that extend beyond commodity chemical supply.
Surface disinfection commands the largest revenue pool; livestock hygiene climbs the fastest.
Active Ingredient:
Technology maturity curves separate entrenched chlorine and quaternary ammonium positions from peroxygen platforms capturing regulatory-driven substitution demand.
- Quaternary Ammonium Compounds:Cationic surfactants forming persistent antimicrobial films on treated surfaces through electrostatic binding mechanisms. Benelux surface disinfection protocols retain entrenched QAC dependence where prolonged residual activity justifies higher unit costs despite EFSA scrutiny over environmental half-lives.
- Chlorine-Based:Hypochlorite and chlorine dioxide formulations delivering rapid oxidative microbial kill across broad pathogen spectra. Legacy infrastructure lock-in slows transition timelines in Spanish and Italian livestock operations despite REACH authorization uncertainty and corrosive equipment damage concerns.
- Peracetic Acid:Peroxygen formulations combining acetic acid and hydrogen peroxide to generate potent antimicrobial action with minimal toxic residue persistence. Dutch greenhouse operators and German dairy cooperatives adopt at accelerating rates to preempt regulatory withdrawal of chlorine chemistries.
- Hydrogen Peroxide:Standalone or stabilized peroxide blends decomposing to water and oxygen without persistent environmental residues. French formulators accelerate hydrogen peroxide development to hedge against potential QAC restriction decisions under ECHA BPR renewal schedules.
Quaternary ammonium compounds anchor current volumes; peracetic acid expands most quickly.
End User:
Customer scale and biosecurity sophistication stratify procurement from commodity spot purchasing to multi-year integrated service contracts.
- Agricultural Producers:Broadacre crop and extensive livestock operations purchasing disinfectants through distributor channels with limited technical support integration. Polish and Romanian field crop producers represent volume opportunity where protected cropping expansion drives first-time sanitization protocol adoption.
- Greenhouses:Protected cropping facilities requiring continuous crop-surface and irrigation system sanitization to suppress endemic pathogen pressure. Netherlands concentration exceeds regional averages, sustaining specialized supplier relationships and precision application equipment investments.
- Dairy Farms:Intensive milk production operations with mandated housing, parlour, and equipment disinfection protocols tied to quality assurance schemes. German cooperative structures and French farm clusters consolidate procurement through veterinary service partnerships that bundle chemical supply with mastitis monitoring programs.
- Veterinary Clinics:Companion and production animal healthcare facilities requiring clinical-grade surface and instrument sterilization. Urban veterinary practices in Paris, Berlin, and Amsterdam specify premium formulations with documented efficacy against emerging zoonotic threats.
Dairy farms generate the largest absolute demand; greenhouses show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' greenhouse corridor generates Europe's most concentrated agricultural disinfectant demand, with Dutch protected cropping density and veterinary biosecurity standards exceeding regional baselines.
Netherlands
Greenhouse horticulture clustering around Westland and Venlo sustains specialized disinfectant procurement for crop-surface sanitization and irrigation system maintenance. EFSA residue limits and EU Green Deal pesticide reduction targets accelerate peracetic acid substitution in Dutch protected cropping. The country's veterinary biosecurity protocols exceed EU minimums, driving bundled diagnostic-linked hygiene service adoption among poultry integrators.
Germany
Intensive dairy operations across Lower Saxony and Bavaria mandate stricter housing disinfection protocols to suppress mastitis transmission chains. REACH authorization pressure on chlorine-based chemistries redirects R&D investment toward peroxygen platforms at German manufacturing sites. Cooperative procurement structures in the northern dairy belt consolidate chemical supply through veterinary service partnerships.
France
Livestock hygiene programs in Brittany and Normandy concentrate demand for surface disinfection and equipment sanitization formulations. ECHA BPR renewal schedules for quaternary ammonium compounds force French formulators to accelerate hydrogen peroxide blend development. Benelux-bordering regions sustain premium positioning for bundled diagnostic testing and scheduled application services.
Spain
Underpenetrated intensive pork and poultry operations in Aragon and Catalonia present volume growth potential for veterinary hygiene protocols. Divergent national veterinary inspection frequencies create compliance fragmentation that favors multi-registration portfolios. Spanish livestock operations retain legacy chlorine infrastructure despite REACH authorization uncertainty slowing transition timelines.
Belgium
Poultry integrators in Flanders specify foam chemistries for hatchery and processing facility deep cleans where complete surface coverage determines pathogen elimination efficacy. The country's dense livestock clustering supports concentrated demand for equipment sanitization and transport vehicle disinfection. Belgian operations mirror Dutch biosecurity standards, favoring consolidated supplier relationships over spot chemical procurement.
Europe Agricultural Disinfectants Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and service integration, creating a tiered structure where scale-driven manufacturers anchor commodity supply while specialized operators capture premium service margins. The vendor base stratifies between integrated peroxygen producers, veterinary-focused biosecurity specialists, and diagnostic-linked hygiene platforms. Three archetypes dominate: integrated chemical manufacturers with captive raw material supply, veterinary service companies bundling testing and disinfection protocols, and diversified life science operators extending from adjacent healthcare markets. Competitive moves concentrate on portfolio diversification toward peracetic acid platforms and geographic expansion into underpenetrated Spanish livestock regions.
Within the integrated manufacturing tier, Lanxess anchors pricing power through captive peracetic acid supply chain control. Kersia Group occupies the veterinary biosecurity specialist position, while Neogen Corporation exemplifies the diagnostic-linked platform archetype extending beyond standalone chemical sales. These three companies represent distinct competitive vectors: backward integration into active ingredient production, deep veterinary protocol expertise, and pathogen testing integration with disinfection scheduling.
| Leading Market Players |
|---|
| FINK TEC GmbH |
| Nufarm Ltd |
| Stepan Company |
| Entaco NV (Nerta) |
| Neogen Corporation |
| Lanxess |
| The Chemours Company |
| Zoetis |
| Kersia Group |
| Others |
Supply & Pricing Matrix
Acetic acid feedstock costs ripple through European agricultural disinfectant pricing tiers from German petrochemical corridors to Dutch greenhouse procurement desks. Peracetic acid producers anchored in integrated acetic acid supply chains capture margin expansion while chlorine-dependent formulators absorb volatility from energy-intensive chlor-alkali production.
Pricing Analysis
Input-cost pass-through from acetic acid and hydrogen peroxide feedstocks stratifies pricing across premium peroxygen formulations and commodity chlorine alternatives. Certification under ECHA BPR authorization timelines commands tiered premiums, with fully approved active substances pricing above transitional formulations. Pricing pressure stems from REACH-driven reformulation investments compressing margins for legacy chlorine portfolios. Small-scale Polish and Romanian agricultural producers exhibit acute price sensitivity, while Dutch greenhouse cooperatives prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics flows for empty disinfectant containers and spent chemical residues shape distribution economics across German dairy cooperatives and Benelux poultry integrators. Manufacturing concentrates in Germany, Belgium, and the Netherlands, drawing from Belgian and German petrochemical feedstocks. Supply chain risk centers on single-source acetic acid dependencies from integrated producers. Distribution runs through veterinary service partnerships in northern Europe and agricultural distributor networks in southern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's agricultural disinfectants market compounds returns through regulatory-driven substitution cycles, with ECHA BPR renewal schedules for quaternary ammonium compounds accelerating portfolio restructuring investments.
For Market Incumbents: Anchor pricing power through captive peracetic acid production or long-term hydrogen peroxide offtake agreements with German and Belgian suppliers. Defend against diagnostic-linked service competitors by bundling pathogen testing with scheduled application protocols in Dutch poultry and French dairy markets. Prioritize multi-registration portfolio maintenance across divergent national veterinary inspection frequencies in Germany, France, and Spain. For New Entrants and Emerging Players: Enter via underpenetrated Spanish intensive pork operations in Aragon and Catalonia, where legacy chlorine infrastructure lock-in delays incumbent transition timelines. Target greenhouse horticulture expansion in Poland and Romania for first-time sanitization protocol adoption. Pursue go-to-market partnerships with agricultural distributors possessing established relationships across fragmented eastern European field crop segments. For Investors and Strategic Acquirers: Consolidation pressure builds where veterinary biosecurity service capabilities fragment across regional champions in France and Benelux. Long-term viability favors platforms integrating diagnostic testing, application equipment, and chemical supply under subscription models. Acquisition candidates include peroxygen formulation specialists with ECHA BPR approval progress and established veterinary service relationships. Monitor ECHA active substance review announcements as inflection signals for portfolio restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Lanxess-style captive supply secures margin control against petrochemical volatility. |
| Diagnostic-Linked Service Bundling | Kersia and Neogen models create recurring revenue beyond commodity chemical sales. |
| Multi-Registration Portfolio Expansion | Spanning Germany, France, and Spain captures fragmented compliance workflows. |
| Peroxygen Formulation Diversification | Hydrogen peroxide blends hedge against potential quaternary ammonium restrictions. |
| Greenhouse Horticulture Geographic Expansion | Polish and Romanian protected cropping drives first-time sanitization demand. |
Research Methodology
Multiple input streams — executive interviews with disinfectant formulators, procurement managers at Dutch greenhouse cooperatives, veterinary biosecurity officers in German dairy operations, and regulatory affairs specialists tracking ECHA BPR timelines — were reconciled against secondary validation from customs trade data, Cefic chemical industry reports, and SEC filings from listed agricultural chemical producers. Bottom-up volume estimates from end-use segment sizing and top-down cross-checks against manufacturer revenue disclosures were triangulated to ensure consistency.
Historical shipment data and panel-based growth assumptions were cross-referenced across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, application protocol type, active ingredient technology maturity, and end-user scale sophistication. CAGRs were derived from regression analysis of correlated agricultural output indicators and biocide regulatory milestone impacts. Forecast inputs incorporated ECHA authorization timeline probabilities and livestock herd expansion projections from national veterinary statistics.
The model holds under stable ECHA review schedules and continued EU Green Deal implementation; deviation in active substance withdrawal decisions or feedstock supply disruptions would shift volume trajectories. Practitioners should monitor ECHA BPR renewal announcements and acetic acid spot pricing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Vaporized Hydrogen Peroxide Sterilization Systems Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Disinfectant Spray Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Disinfecting Wipes Market