
 Disinfectant Chemicals Market | 2026-2036
Disinfectant Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfectant Chemicals Market Analysis
Hospital procurement channels is narrowing as group purchasing organizations consolidate supplier lists across integrated delivery networks. Ecolab Inc. anchors its position through captive service contracts that bundle chemical supply with equipment leasing. Reckitt Benckiser Group plc differentiates via consumer brand equity that extends into professional segments. STERIS plc specializes in sterile processing workflows where disinfectant chemistry integrates with autoclave validation protocols.
Disinfectant chemicals comprise antimicrobial formulations typically containing active concentrations of quaternary ammonium compounds, chlorine-releasing agents, or accelerated hydrogen peroxide, manufactured through controlled exothermic reactions with stabilizing surfactant packages. These substances inactivate pathogens on non-porous surfaces across healthcare, food processing, and municipal water treatment operations. Quaternary ammonium compounds occupy the largest volume position due to their compatibility with plastics and residual activity on treated surfaces. Alcohol-based formulations lead growth in point-of-care applications where rapid evaporation and minimal residue prove clinically essential. Chlorine compounds retain cost-driven dominance in municipal water treatment and bulk institutional sanitation where oxidative potency outweighs material corrosion concerns.
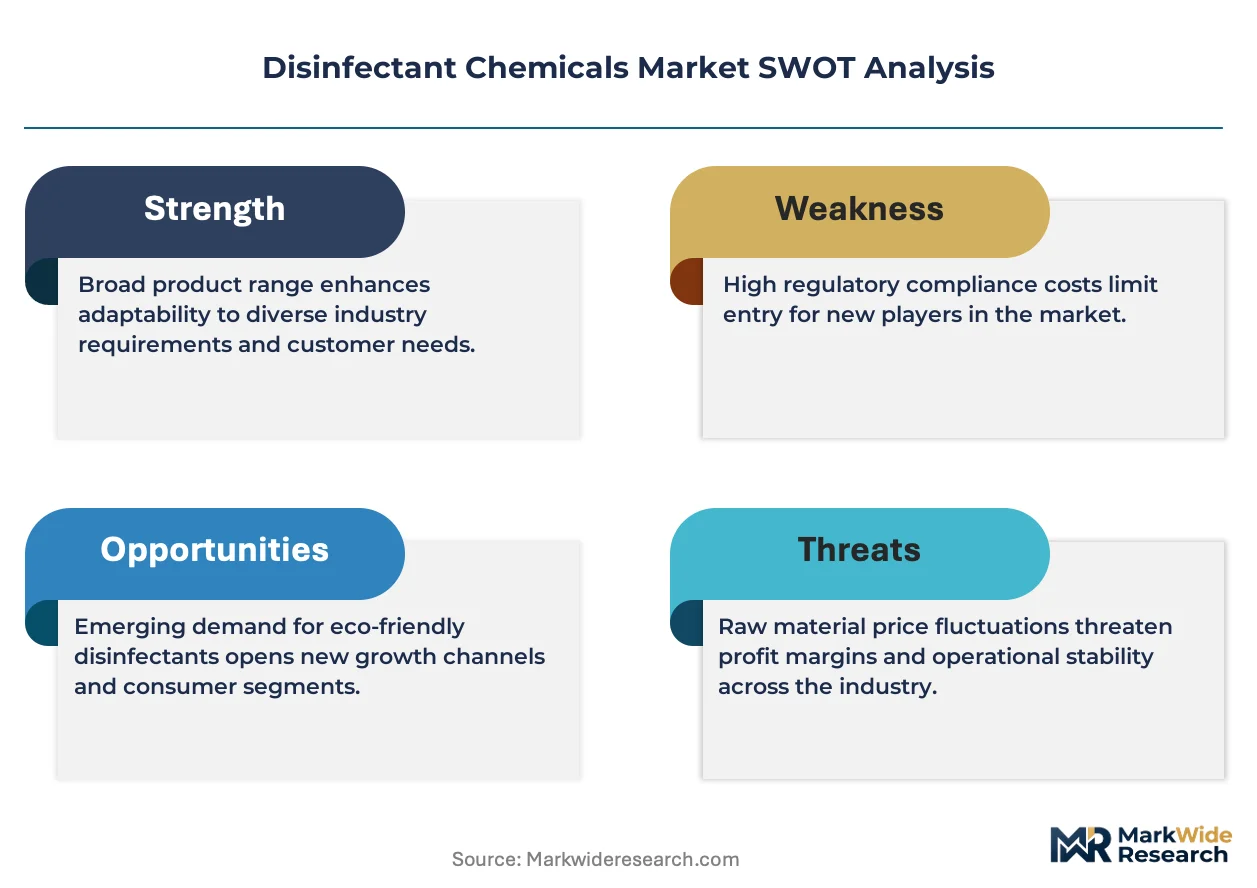
EPA registration under the Federal Insecticide, Fungicide, and Rodenticide Act governs efficacy claims and label instructions for all disinfectant products distributed in the United States. FDA oversight intersects at 510(k) clearances for disinfectants packaged as medical devices with specific intended-use claims. OSHA bloodborne pathogen standards and Joint Commission accreditation criteria collectively mandate minimum disinfection frequencies that institutional buyers must document. Stakeholders should monitor emerging state-level restrictions on quaternary ammonium compound discharges into wastewater systems, as these could force reformulation investments before federal rulemaking catches up.
Market Dynamics
Hospital-acquired infection prevention mandates are compressing procurement cycles while accelerating EPA registration requirements for emerging viral pathogens, forcing suppliers to validate efficacy claims against evolving pathogen threats before contract eligibility.
Growth Catalysts
- EPA Emerging Viral Pathogen Program:Registration requirements for SARS-CoV-2 and subsequent variants compel healthcare facilities to upgrade surface disinfection protocols, expanding institutional demand for validated chemistries.
- Food processing sanitation mandates:USDA inspection standards for ready-to-eat facilities drive adoption of no-rinse quaternary ammonium formulations in meat and poultry operations.
- Municipal water infrastructure investment:Aging distribution systems in the United States require continuous chloramination, sustaining bulk chlorine compound consumption.
Market Restraints
- Isopropyl alcohol feedstock volatility:Propylene supply disruptions from petrochemical refineries transmit directly to alcohol-based disinfectant manufacturing costs.
- Quaternary ammonium discharge restrictions:State-level wastewater discharge limits in California and New York impose reformulation costs before federal harmonization.
- Peracetic acid substitution pressure:Sporicidal efficacy claims in sterile processing favor peracetic acid systems over traditional glutaraldehyde chemistries.
Strategic Opportunities
- India healthcare infrastructure expansion:CDSCO streamlined medical device registration creates entry pathways for hospital-grade disinfectant suppliers.
- Electrostatic sprayer compatibility:Formulation modifications for charged particle application open facility-wide disinfection contracts.
- EU Green Deal chemical sustainability criteria:Biodegradable surfactant packages qualify for public procurement preference in member state healthcare systems.
Industry Challenges
- EPA registration timeline compression:Accelerated review demands for emerging pathogens strain toxicology submission capacity.
- Autoclave validation integration:Disinfectant chemistry must demonstrate compatibility with sterile processing equipment calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfectant Chemicals Market |
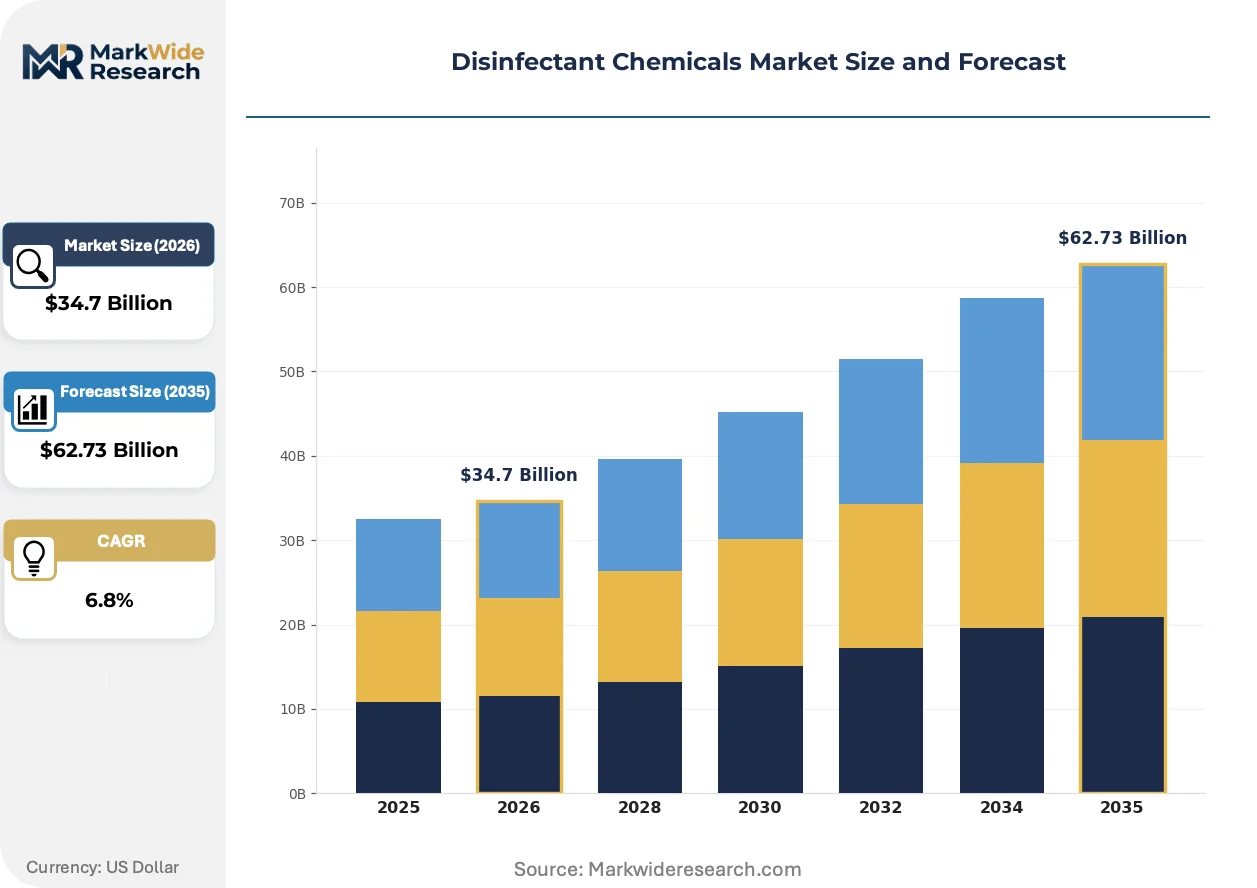
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
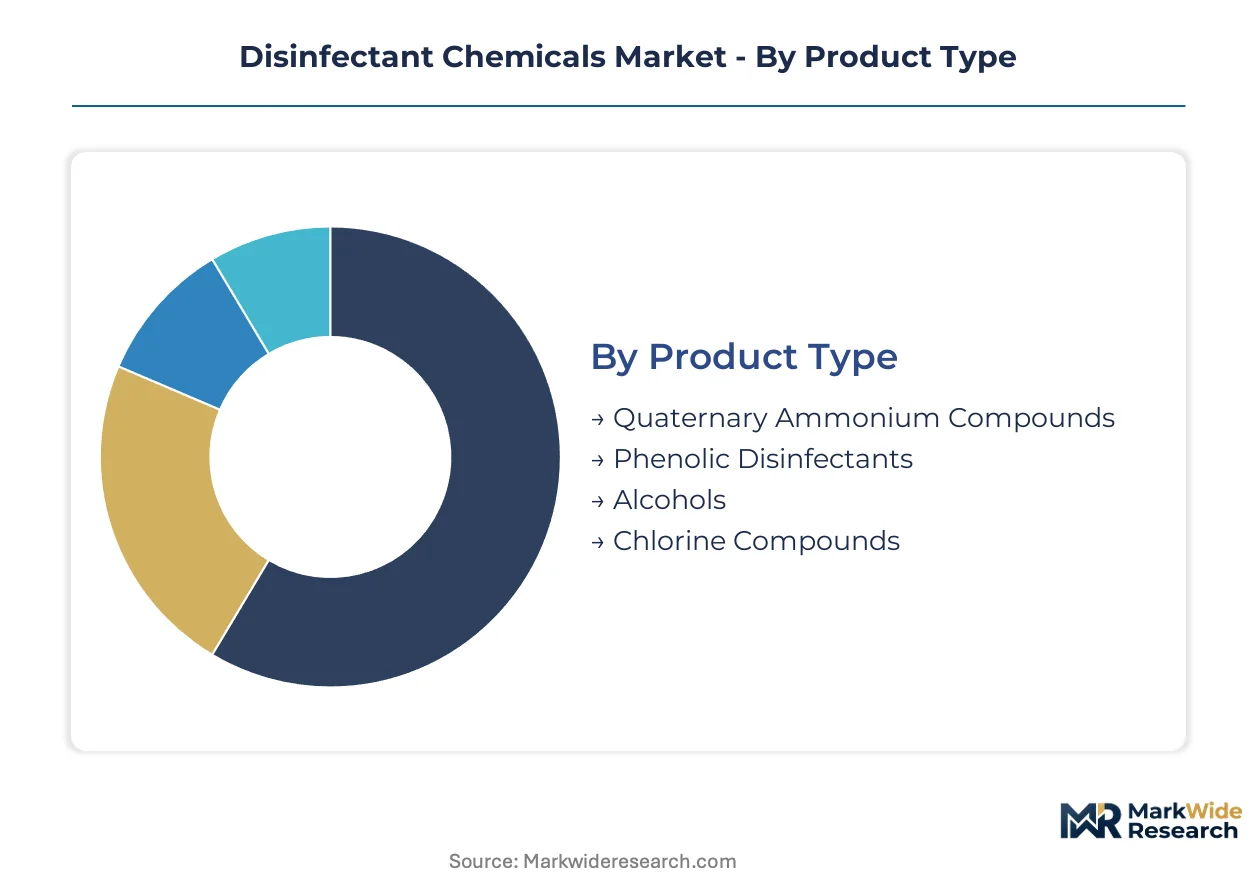
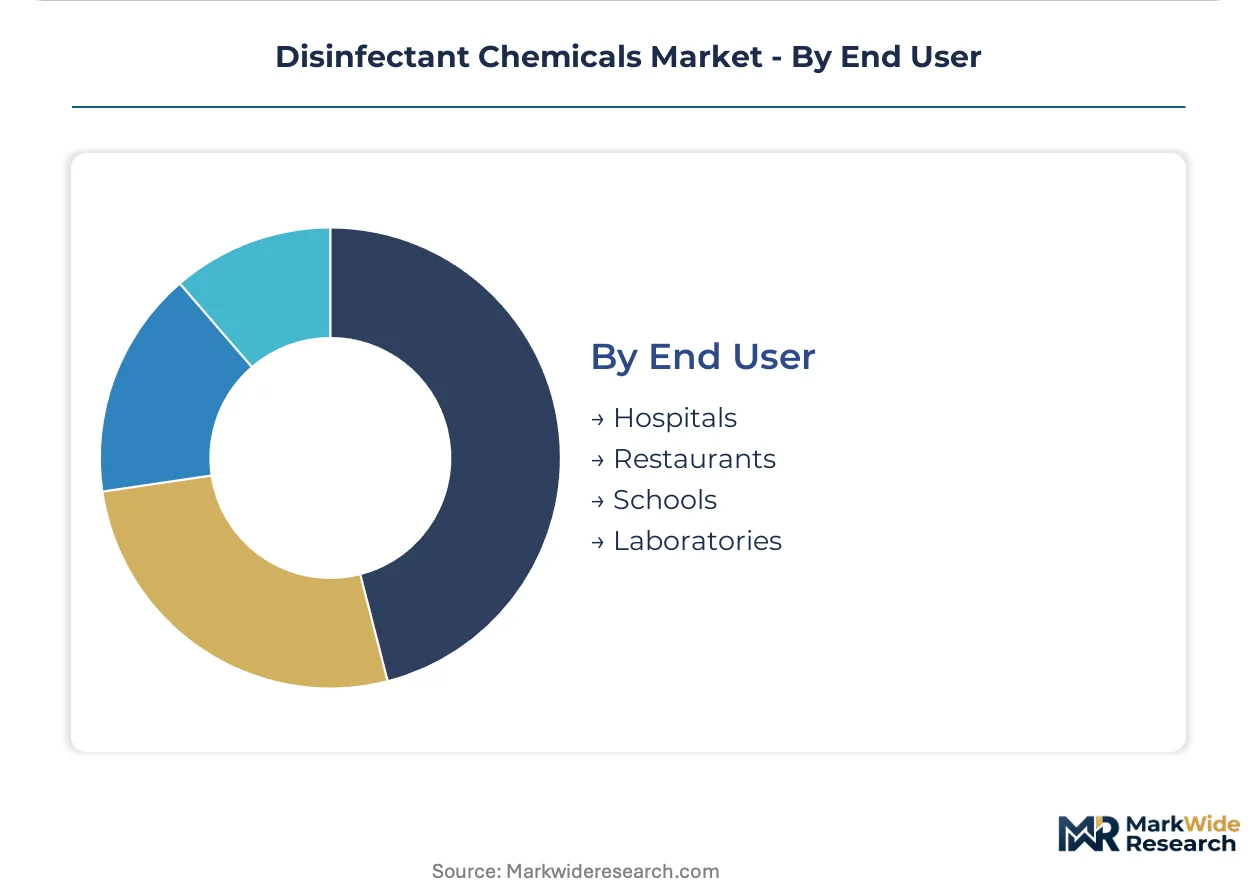
| Segmentation | Product Type: Quaternary Ammonium Compounds, Phenolic Disinfectants, Alcohols, Chlorine Compounds Application: Household, Healthcare, Industrial, Institutional Form: Aerosol, Liquid, Gel, Wipe End User: Hospitals, Restaurants, Schools, Laboratories |
| Companies Covered | Reckitt Benckiser Group plc, Ecolab Inc., 3M Company, The Clorox Company, STERIS plc, Procter & Gamble, S. C. Johnson & Son, Inc., Diversey, Solventum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfectant Chemicals Market Emerging Trajectories
Formulation science is converging with application technology, as chemistries adapt to new delivery mechanisms and regulatory frameworks tighten efficacy documentation requirements across institutional segments.
Accelerated hydrogen peroxide is hybridizing quaternary ammonium residual activity with rapid oxidative kill kinetics. Long-term care facilities adopt these formulations for terminal room disinfection where turnover time constraints previously favored alcohol wipes. The technology is hybridizing competitive positioning between speed-focused and persistence-focused product categories.
REACH authorization requirements for biocidal active substances are forcing substance-by-substance dossier submissions for quaternary ammonium compounds and aldehydes. ECHA evaluation timelines extend market access uncertainty for legacy chemistries. European hospital procurement is responding by diversifying supplier portfolios across multiple active ingredient classes.
Integrated delivery networks are consolidating vendor lists through group purchasing organization contracts that bundle chemical supply with compliance documentation services. Independent distributors lose share to captive service models. This concentration is most visible in United States metropolitan hospital systems where Joint Commission accreditation documentation requirements favor bundled accountability structures.
Disinfectant Chemicals Market Segmentation
Disinfectant chemical procurement varies sharply across use environments, with EPA registration tiers and surface compatibility requirements driving portfolio decisions. Formulation chemistry must align with both pathogen kill claims and material safety constraints that differ fundamentally between healthcare sterile processing and food service sanitation.
Product Type:
Cost tier determines procurement channel access and margin structure across active ingredient categories.
- Quaternary Ammonium Compounds:Cationic surfactant formulations provide residual antimicrobial activity on plastics and environmental surfaces. Demand concentrates in long-term care facilities and food processing operations where surface compatibility outweighs sporicidal requirements. EPA registration under emerging viral pathogen protocols sustains institutional contract eligibility.
- Alcohols:Ethanol and isopropanol solutions deliver rapid evaporation with minimal residue for point-of-care applications. Healthcare facilities prioritize these formulations for medical device disinfection where turnover time constraints dominate procurement criteria. Propylene feedstock volatility from petrochemical refineries transmits directly to manufacturing cost structures.
- Phenolic Disinfectants:Coal-tar derivative chemistries retain niche positions in veterinary and agricultural sanitation where broad-spectrum claims persist.
- Chlorine Compounds:Sodium hypochlorite and chloramine solutions dominate municipal water treatment and bulk institutional sanitation through oxidative potency at low unit cost.
Quaternary ammonium compounds hold installed capacity. Alcohols are rotating up the share rankings.
Application:
End-use environment dictates formulation specification, documentation burden, and compliance architecture.
- Healthcare:Terminal room disinfection and sterile processing workflows demand validated kill kinetics against bloodborne pathogens. Joint Commission accreditation criteria mandate minimum disinfection frequencies that institutional buyers must document. EPA registration under FIFRA governs all efficacy claims.
- Industrial:Food processing sanitation mandates from USDA inspection standards drive no-rinse quaternary ammonium adoption in meat and poultry operations. Ready-to-eat facility protocols require chemistry compatible with production line materials.
- Household:Consumer brand equity extends from retail shelf presence into professional segments through dual-use registration strategies.
- Institutional:Schools and municipal facilities balance cost constraints against emerging viral pathogen preparedness requirements.
Healthcare commands specification authority. Industrial applications are climbing the fastest.
Form:
Delivery mechanism determines coverage efficiency, dwell time control, and labor cost per treated surface area.
- Liquid:Bulk concentrate formulations enable dilution control across facility-wide disinfection programs. Electrostatic sprayer compatibility is opening contract opportunities for charged particle application systems.
- Wipe:Pre-saturated substrates eliminate dilution error and standardize contact time for terminal cleaning protocols in acute care settings.
- Aerosol:Pressurized delivery systems penetrate complex geometries in HVAC and equipment sanitation applications.
- Gel:Viscous formulations cling to vertical surfaces and extend contact time for stubborn biofilm disruption.
Liquid holds manufacturing scale. Wipe formats are gaining share fastest.
End User:
Customer procurement sophistication separates specification-driven buyers from price-sensitive volume purchasers.
- Hospitals:Group purchasing organization contracts consolidate supplier lists across integrated delivery networks. Bundled accountability structures favor vendors delivering compliance documentation alongside chemical supply.
- Restaurants:Health department inspection regimes drive consistent sanitation protocol adherence with limited formulation flexibility.
- Schools:Budget constraints and intermittent use patterns favor multi-purpose chemistries with broad label claims.
- Laboratories:Biosafety level requirements dictate sporicidal and virucidal validation standards exceeding general environmental sanitation needs.
Hospitals anchor contract value. Laboratories are rotating up the specification hierarchy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European disinfectant distribution, while the Houston Ship Channel underwrites North American chlorine compound supply chains. These logistical assets concentrate formulation manufacturing near feedstock terminals and institutional procurement hubs.
United States
Hospital-acquired infection prevention mandates from the Joint Commission drive institutional procurement across integrated delivery networks. EPA registration under FIFRA governs all emerging viral pathogen efficacy claims, compressing supplier validation timelines. The Texas-Louisiana Gulf Coast chemical corridor concentrates chlorine compound manufacturing near petrochemical feedstock sources.
Germany
REACH authorization requirements for biocidal active substances extend market access uncertainty for quaternary ammonium compound formulations. ECHA evaluation timelines force hospital procurement diversification across multiple active ingredient classes. The Rhine-Ruhr industrial cluster hosts sterile processing equipment manufacturers integrating disinfectant chemistry with autoclave validation protocols.
India
CDSCO streamlined medical device registration creates entry pathways for hospital-grade disinfectant suppliers targeting healthcare infrastructure expansion. Central government sanitation initiatives under the Swachh Bharat Mission sustain municipal procurement volume. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune anchors domestic formulation capacity for institutional buyers.
China
GB standards for disinfectant efficacy and safety documentation tighten as NMPA alignment with international norms accelerates. Municipal water treatment investment in aging distribution systems sustains bulk chlorine compound consumption. The Yangtze River Delta chemical parks around Shanghai concentrate quaternary ammonium compound manufacturing for both domestic and export markets.
Japan
METI industrial standards for healthcare facility sanitation drive specification authority for terminal room disinfection chemistries. PMDA oversight intersects with disinfectants packaged as medical devices requiring specific intended-use documentation. The Kansai industrial corridor around Osaka maintains specialty formulation capacity for biosafety-level laboratory applications.
Disinfectant Chemicals Market Vendor Landscape
On the supply side, the industry is consolidating through group purchasing organization contracts that narrow supplier lists across integrated delivery networks. Three strategic archetypes dominate: captive service integrators bundling chemical supply with equipment leasing, consumer brand equity players extending retail recognition into professional segments, and sterile processing specialists integrating chemistry with autoclave validation workflows. M&A activity concentrates on regional formulation assets, while strategic partnerships target electrostatic sprayer compatibility certification.
Among diversified chemical conglomerates, Ecolab Inc. and 3M Company exemplify the captive service archetype through bundled accountability structures. STERIS plc occupies the sterile processing specialization tier where disinfectant chemistry must demonstrate compatibility with equipment calibration protocols. These three entities anchor the competitive structure without exhaustive representation of the vendor landscape.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| Ecolab Inc. |
| 3M Company |
| The Clorox Company |
| STERIS plc |
| Procter & Gamble |
| S. C. Johnson & Son, Inc. |
| Diversey |
| Solventum Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese quaternary ammonium compound manufacturing is compressing export pricing while forcing European and North American producers toward specialized formulations with EPA and REACH compliance premiums. This utilization gap simultaneously erodes commodity margins and rewards suppliers who bundle regulatory documentation with chemical supply.
Pricing Analysis
Volume-discount tiering separates contract-based integrated delivery network procurement from spot-market municipal buyers. EPA registration tier and electrostatic sprayer compatibility certification drive price differentiation between premium validated chemistries and commodity concentrates. Cost compression in alcohol-based formulations is intensifying because propylene feedstock volatility from Gulf Coast refineries transmits directly to manufacturing economics. Municipal water treatment buyers exhibit highest price sensitivity, while sterile processing laboratories accept premiums for autoclave-validated chemistries.
Supply Chain Analysis
Export-control regimes on dual-use biocidal precursors limit flows of specified quaternary ammonium intermediates from China to certain destinations. Manufacturing concentrates in China, the United States, and Germany, with formulation drawing from isopropyl alcohol, chlorine gas, and specialty surfactant packages. Single-source vulnerability sits with propylene oxide derivatives for accelerated hydrogen peroxide production. Distribution runs through group purchasing organization contracts that consolidate vendor accountability across hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disinfectant chemicals represent a service-attach opportunity because compliance documentation and equipment leasing layers are expanding faster than standalone chemical volumes. Recurring revenue from captive service contracts now exceeds transactional chemical margins for leading suppliers.
For Market Incumbents: Build regulatory dossier moats by accelerating REACH authorization submissions and EPA emerging viral pathogen registrations ahead of harmonization deadlines. Consolidate regional formulation assets to defend against peracetic acid substitution in sterile processing. Deepen backward integration into surfactant manufacturing to offset feedstock volatility. For New Entrants and Emerging Players: Pursue CDSCO registration pathways for hospital-grade disinfectants targeting Maharashtra's pharmaceutical manufacturing belt expansion. Electrostatic sprayer compatibility certification offers the most penetrable wedge into facility-wide disinfection contracts previously held by bundled service incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract manufacturing and toll formulation segments as asset-light regulatory specialists capture margin from capital-heavy producers. Acquisition targets should combine EPA registration expertise with electrostatic application technology partnerships. The signal to watch is state-level quaternary ammonium discharge restriction adoption preceding federal rulemaking.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Manufacturing | Captive supply of stabilizing packages insulates margins from petrochemical volatility. |
| EPA Emerging Viral Pathogen Registration | Validated efficacy claims unlock integrated delivery network contract eligibility. |
| Electrostatic Sprayer Compatibility Certification | Charged particle application opens facility-wide terminal disinfection contracts. |
| REACH Authorization Dossier Submission | Substance-by-substance approval sustains European market access for legacy chemistries. |
| CDSCO Medical Device Registration | Streamlined pathway captures healthcare infrastructure expansion in Maharashtra and Pune clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA registration databases, SEC 10-K chemical segment disclosures, and customs trade data for disinfectant active ingredient flows. Interviews with hospital GPO contracts managers, sterile processing department heads, formulation plant managers, and distribution channel partners were combined with bottom-up and top-down triangulation. Secondary validation drew from FIFRA registration filings, ECHA biocidal substance evaluations, and CDSCO medical device approval records.
Forecast inputs incorporate active ingredient grade tier, end-use environment specification burden, packaging format dilution control, and regional regulatory cluster stringency across the modeling period. CAGRs were derived from segment-level volume build-ups calibrated to institutional procurement cycle data and municipal water infrastructure investment flows. Modeled outputs reflect EPA registration timeline compression effects and REACH authorization uncertainty premiums.
Sensitivities concentrate around propylene supply disruption severity, state-level discharge restriction adoption velocity, and electrostatic application technology penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Aerosol Disinfectants Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Hydrogen Peroxide Market
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market