
 Fumigant Products Market | 2026-2036
Fumigant Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fumigant Products Market Analytics
India's expanding phosphine tablet manufacturing corridor is rewriting supply dynamics for commodity preservation across South Asia and East Africa. Solvay S.A. leverages its integrated alkali chemistry chain to sustain cost leadership in sulfuryl fluoride precursors. FMC Corporation anchors North American soil fumigation through its deep distribution network with licensed applicators. Detia Degesch GmbH specializes in phosphine-based formulations, competing on precision-delivery systems that reduce handler exposure risk.
Fumigant products are volatile or gaseous biocidal formulations designed to permeate enclosed spaces, soil matrices, or commodity masses at concentrations measured in parts per million, typically deployed under sealed tarpaulins or within gastight structures to eliminate arthropod pests, nematodes, fungi, or rodents. Their primary commercial purpose centers on pre-shipment quarantine compliance, post-harvest loss prevention, and structural infestation remediation in trade-sensitive supply chains. Phosphine dominates volume flows across grain warehousing and shipping due to its residue-free breakdown and low cost per treated ton, while sulfuryl fluoride captures premium positioning in structural pest control where methyl bromide retreatment intervals have tightened. Chloropicrin occupies a narrower but defensible niche in soil fumigation combinations, where its warning properties and synergistic nematicidal action command formulation margins above standalone alternatives.
The EPA's methyl bromide phase-down under Clean Air Act obligations and the Montreal Protocol continues to reshape product registration priorities, pushing registrants toward alternative chemistries with shorter atmospheric lifetimes. ECHA's REACH authorization requirements and the EU's F-Gas Regulation impose parallel constraints on European formulation and import pathways, elevating compliance costs for legacy active ingredients. Brazil's national health surveillance agency, ANVISA, and China's Ministry of Agriculture and Rural Affairs are tightening maximum residue limits for export-oriented commodities, forcing applicators toward precision-delivery equipment and documented fumigation protocols. Stakeholders must monitor evolving equivalence determinations across destination markets, as regulatory divergence between major importing blocs threatens to fragment product registration strategies and strain centralized manufacturing footprints.
Market Dynamics
The EPA's methyl bromide phase-down under Montreal Protocol obligations is forcing registrants to rebuild formulation portfolios around shorter-lived chemistries, compressing development timelines and elevating sulfuryl fluoride's strategic priority across quarantine and structural applications.
Growth Catalysts
- ANVISA tightening in Brazil:Export certification protocols for soybeans and corn are mandating documented fumigation histories, pulling phosphine tablet volumes into the country's interior warehousing corridor.
- Phosphine tablet manufacturing expansion:India's production corridor is scaling capacity to serve South Asian grain preservation and East African commodity import requirements.
- Post-harvest loss protocols:Grain warehousing operators are adopting precision-delivery systems to meet tightening residue limits in destination markets.
Market Restraints
- Alkali chemistry supply concentration:Sulfuryl fluoride precursor production clusters in integrated chlor-alkali facilities, creating geographic supply vulnerability.
- REACH authorization costs:ECHA's requirements for legacy actives are elevating compliance expenditures for European formulation and import pathways.
- Handler exposure liability:Precision-delivery equipment mandates are raising capital thresholds for licensed applicator networks.
Strategic Opportunities
- East African import corridors:Kenya and Tanzania are expanding grain storage infrastructure without established fumigation protocols, creating first-mover positioning for phosphine tablet suppliers.
- Soil fumigation combinations:Chloropicrin's synergistic nematicidal action in combination formulations commands premium margins in specialty crop applications.
- China's MEE residue enforcement:Maximum residue limit tightening for export-oriented commodities is accelerating precision-equipment adoption.
Industry Challenges
- Applicator certification pipelines:Licensed fumigator training programs are failing to match demand growth in Brazil's expanding soybean belt.
- Equipment integration complexity:Precision-delivery systems require retrofitting legacy gastight structures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fumigant Products Market |
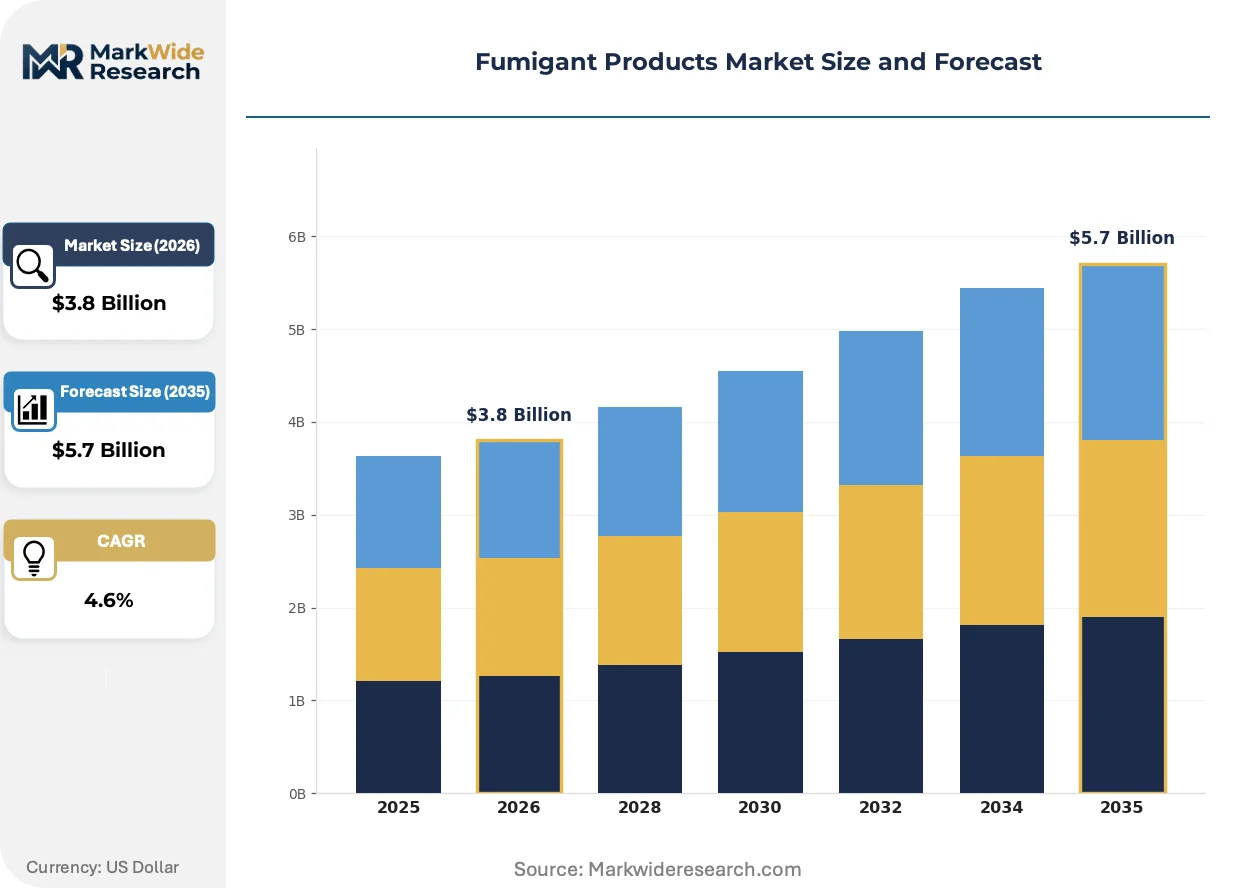
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Bromide, Phosphine, Sulfuryl Fluoride, Chloropicrin Application: Food Storage, Soil Fumigation, Structural Pest Control, Commodity Preservation End User: Agriculture, Warehousing, Shipping, Pest Control Operators Distribution Channel: Direct Sales, Online Stores, Distributors, Retail |
| Companies Covered | Solvay S.A., LANXESS AG, AMVAC Chemical Corporation, FMC Corporation, Ecolab Inc., Detia Degesch GmbH, Arkema, Nufarm Limited, UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fumigant Products Market Evolving Landscape
Formulation chemistry and application hardware are converging to address regulatory half-life requirements and handler safety mandates simultaneously. Equipment manufacturers and chemical registrants are co-developing integrated systems rather than standalone products.
Electrochemical phosphine generation systems are eliminating tablet handling and residue management burdens. Large-scale grain elevator operators in the US and Australia are retrofitting facilities with on-site generation capacity. This distributed production model is rendering obsolete the tablet supply chains that dominated commodity preservation for decades.
ECHA's F-Gas Regulation and the EU's REACH authorization framework are compressing registration timelines for alternative chemistries. Formulators are front-loading toxicology and environmental fate studies to secure market access before legacy product withdrawals. Sulfuryl fluoride structural fumigation is capturing share fastest in Germany and France where methyl bromide retreatment intervals have tightened most aggressively.
Commodity buyers are unbundling fumigation service contracts from logistics agreements, creating direct procurement relationships with licensed applicators. Grain trading houses in Brazil and Argentina are establishing preferred provider networks with documented protocol compliance. This disintermediation is most visible in export-oriented soybean operations where destination market residue documentation requirements have intensified.
Fumigant Products Market Segmentation
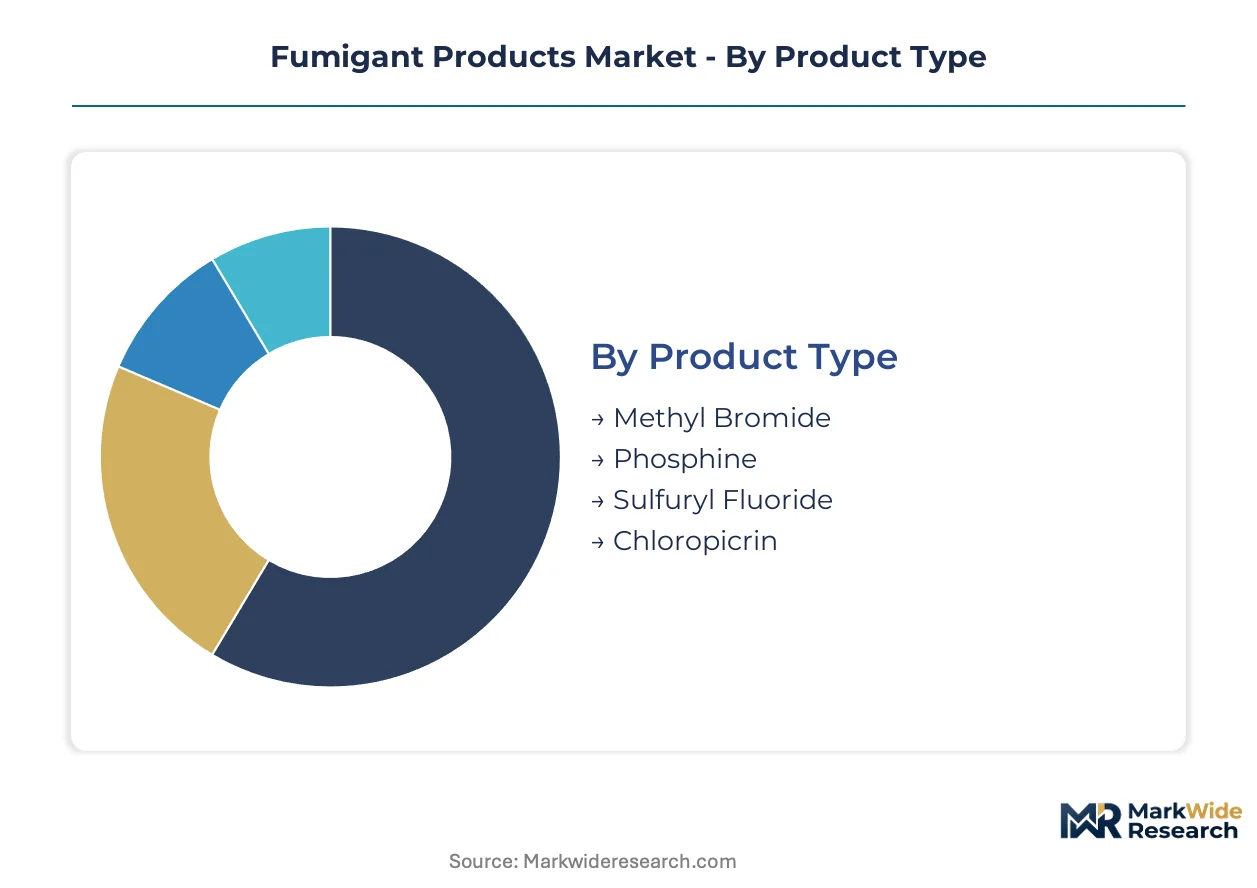
Fumigant product segmentation reflects divergent service intensity requirements across application contexts. Grain warehousing demands continuous technical support for phosphine monitoring systems, while structural pest control operates through episodic, high-value interventions.
Product Type:
After-sales service intensity varies sharply across chemistries, with phosphine tablet systems requiring ongoing handler training and residue monitoring support.
- Phosphine:Aluminum or magnesium phosphide formulations generate toxic gas through moisture-activated hydrolysis, demanding gastight sealing verification and concentration monitoring throughout the exposure period. India's manufacturing corridor is scaling tablet and pellet production to serve South Asian grain preservation and East African commodity import requirements.
- Sulfuryl Fluoride:This colorless, odorless gas penetrates structural wood matrices at low concentrations, requiring integrated warning agent systems and aeration clearance protocols. EPA's methyl bromide phase-down is redirecting quarantine and structural fumigation registrations toward this chemistry.
- Methyl Bromide:Ozone-depleting bromomethane formulations face Montreal Protocol production quotas, restricting use to critical quarantine pre-shipment applications.
- Chloropicrin:Tear gas-warning properties make this nitro compound ideal for soil combination formulations where applicator safety margins command premium positioning.
Phosphine holds the largest share; momentum sits with sulfuryl fluoride.
Application:
Cost tier differentiation separates commodity-scale preservation from premium structural interventions, with equipment and labor intensity driving margin structure.
- Commodity Preservation:Bulk grain, oilseed, and legume treatments in warehouses and shipping containers utilize phosphine at lowest cost per treated ton, with residue-free breakdown meeting tightening destination market limits. Brazil's soybean belt is pulling volumes into interior storage corridors ahead of ANVISA export certification requirements.
- Structural Pest Control:Building and vessel fumigation commands highest service fees due to sealing complexity, aeration safety protocols, and liability exposure. Sulfuryl fluoride captures share fastest in Germany and France where methyl bromide retreatment intervals have tightened.
- Soil Fumigation:Pre-plant nematicide and fungicide treatments combine chloropicrin with other actives, with specialty crop applications justifying premium formulation margins.
- Food Storage:Processed and packaged commodity treatments face strict residue thresholds, favoring precision-delivery equipment with documented protocol compliance.
Commodity preservation dominates volume; structural pest control delivers highest value per treatment.
End User:
Customer type determines procurement sophistication, with licensed applicator networks separating professional operators from direct agricultural purchasers.
- Warehousing:Grain elevator operators and third-party logistics providers are retrofitting facilities with electrochemical phosphine generation, eliminating tablet handling burdens.
- Agriculture:Farm-level soil fumigation and on-farm storage treatments rely on distributor-trained applicators with seasonal demand patterns.
- Pest Control Operators:Licensed fumigation specialists carry liability for structural treatments, with certification pipelines failing to match demand growth in Brazil's expanding soybean belt.
- Shipping:Container and vessel fumigation services face port authority oversight and destination market documentation requirements.
Warehousing generates the steadiest demand; pest control operators command premium pricing power.
Distribution Channel:
Supply concentration in alkali chemistry precursors shapes channel economics, with direct relationships dominating volume flows.
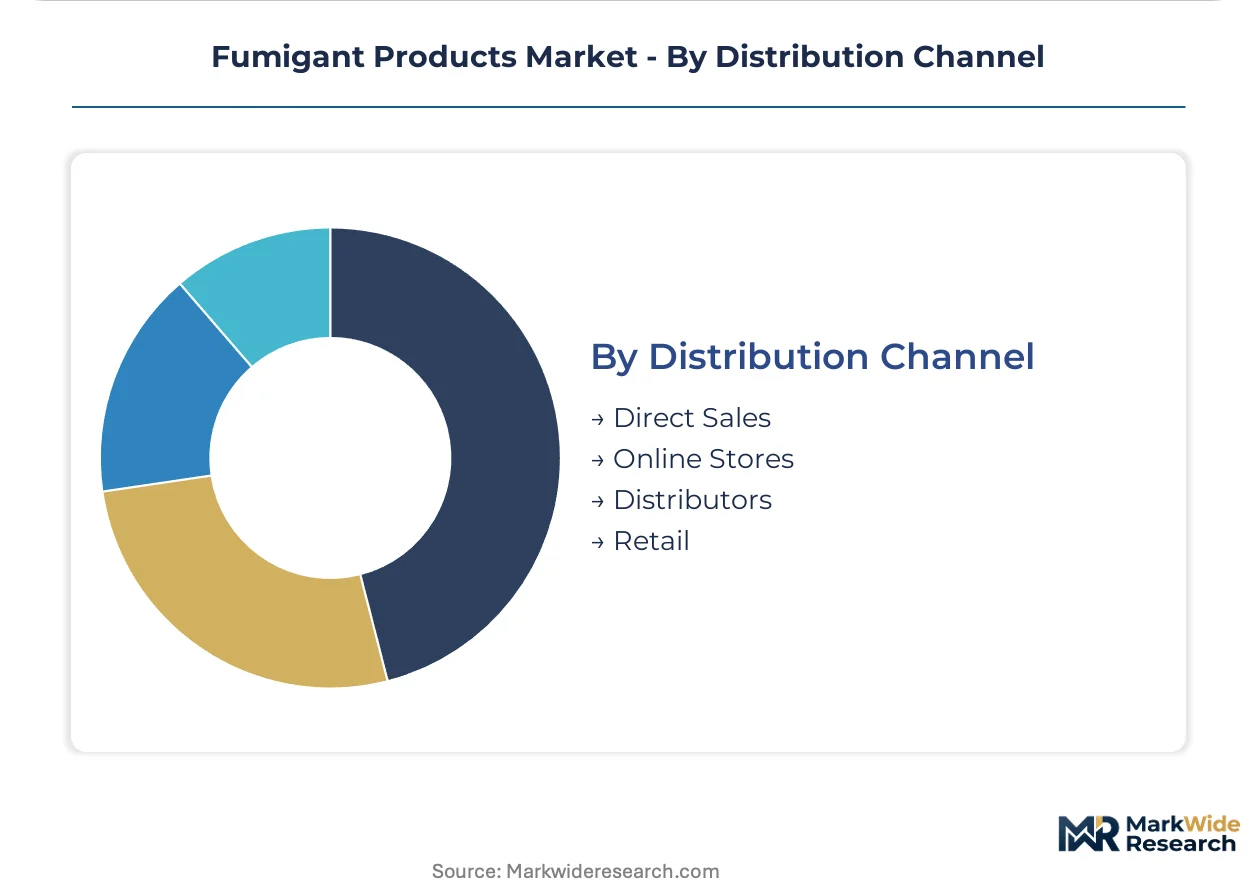
- Distributors:Licensed applicator networks and agricultural supply cooperatives move phosphine tablets and soil fumigation combinations through trained intermediary relationships.
- Direct Sales:Large grain trading houses and elevator operators procure electrochemical generation systems and bulk sulfuryl fluoride through manufacturer-direct contracts.
- Retail:Limited consumer-accessible formats for small-scale agricultural and residential applications face regulatory restriction in most jurisdictions.
- Online Stores:Professional equipment and monitoring accessories move through specialized B2B platforms with credential verification requirements.
Distributors anchor volume; direct sales is expanding most quickly among large operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's methyl bromide phase-down under Montreal Protocol obligations anchors strategic formulation decisions in the United States, redirecting investment toward sulfuryl fluoride alternatives while tightening quarantine compliance requirements across export corridors.
United States
Grain elevator operators in the Corn Belt are retrofitting facilities with electrochemical phosphine generation systems to eliminate tablet handling burdens. EPA's Clean Air Act enforcement continues compressing methyl bromide availability for critical use exemptions. Large-scale warehousing clusters in Iowa and Illinois are driving precision-delivery equipment adoption ahead of destination market documentation requirements.
Brazil
Soybean belt expansion into Mato Grosso and Goiás is pulling phosphine tablet volumes into interior storage corridors. ANVISA's tightening export certification protocols now mandate documented fumigation histories for corn and soybean shipments. Licensed applicator networks in Ribeirão Preto and Londrina are struggling to match certification pipeline demand growth.
Germany
Structural fumigation operators are capturing sulfuryl fluoride share fastest where methyl bromide retreatment intervals have tightened most aggressively. ECHA's REACH authorization requirements and F-Gas Regulation impose parallel constraints on legacy active ingredient formulations. Industrial chemical manufacturing in the Rhine-Ruhr corridor sustains integrated chlor-alkali precursor supply for sulfuryl fluoride production.
India
Phosphine tablet manufacturing corridors in Gujarat and Maharashtra are scaling capacity to serve South Asian grain preservation and East African commodity import requirements. BIS standards for fumigation equipment are tightening quality thresholds for precision-delivery system exports. Mumbai and Ahmedabad logistics hubs are consolidating distribution networks for phosphine-based formulations across the subcontinent.
Australia
Large-scale grain elevator operators in New South Wales and Victoria are deploying on-site electrochemical phosphine generation, rendering tablet supply chains obsolete. The country's national agricultural regulator maintains strict residue monitoring protocols for wheat and barley export certification. Port facilities in Adelaide and Fremantle are upgrading gastight infrastructure to meet tightening quarantine pre-shipment standards.
Fumigant Products Market Competitive Landscape
Integrated chemical conglomerates and specialized fumigation formulators split the market between scale-driven precursor supply and precision-delivery system innovation. The vendor base concentrates around alkali chemistry integration for sulfuryl fluoride production and phosphine tablet manufacturing corridors serving commodity preservation demand. Two strategic archetypes dominate: chlor-alkali-integrated diversified chemical producers and focused phosphine formulation specialists with precision-equipment partnerships. Competitive moves center on backward integration into precursor supply and geographic expansion into underpenetrated East African grain storage corridors.
Within the integrated chemical tier, Solvay S.A. and LANXESS AG occupy positions anchored by European chlor-alkali infrastructure. Among specialized formulators, Detia Degesch GmbH represents the precision-delivery archetype, while FMC Corporation exemplifies North American distribution network depth with licensed applicator relationships. These three named entities illustrate the competitive tension between scale-driven precursor control and service-intensive formulation expertise.
| Leading Market Players |
|---|
| Solvay S.A. |
| LANXESS AG |
| AMVAC Chemical Corporation |
| FMC Corporation |
| Ecolab Inc. |
| Detia Degesch GmbH |
| Arkema |
| Nufarm Limited |
| UPL Limited |
| Others |
Value Network & Pricing Analysis
Integrated chlor-alkali facilities in Belgium and Germany anchor sulfuryl fluoride precursor supply, concentrating margin capture upstream while downstream formulators compete on precision-delivery equipment bundling. This chemistry integration creates pricing power asymmetry between precursor producers and regional applicator networks.
Pricing Analysis
Brazil's interior warehousing corridors command 15-25% premiums over coastal ports due to logistics friction and ANVISA certification urgency. Three-tier pricing structure across premium precision-delivery systems, standard tablet-based protocols, and economy bulk treatments separates service intensity levels. Cost compression in commodity phosphine tablets is intensifying because India's manufacturing expansion adds capacity faster than East African demand materializes. Grain elevator operators exhibit highest price sensitivity, while structural pest control specialists absorb premium positioning for liability coverage.
Supply Chain Analysis
Aluminum phosphide feedstock draws from integrated alkali chemistry chains concentrated in Belgium, Germany, and coastal China. Magnesium phosphide production rests on foundry-grade magnesium sourcing from Shanxi province and Russian primary aluminum. Single-source vulnerability sits with sulfur hexafluoride electrolytic cell anodes, where two European suppliers control specialty graphite grades. Distribution runs through licensed applicator networks in Brazil and direct procurement relationships with Australian grain cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical phosphine generation is disrupting tablet supply chains that dominated commodity preservation for decades, with EPA enforcement accelerating the technology transition. This inflection compresses formulation margins while elevating equipment manufacturers.
For Market Incumbents: Harden backward integration into chlor-alkali precursor supply to defend against Solvay S.A. and LANXESS AG cost advantages. Lock in long-term supply agreements with Indian tablet manufacturers before Gujarat capacity expansion saturates South Asian pricing. Precision-delivery equipment certification investments represent the critical defensive lever against emerging electrochemical system competitors. For New Entrants and Emerging Players: Establish a beachhead in East African grain storage corridors where Kenya and Tanzania lack established fumigation protocols and licensed applicator networks. Target phosphine tablet distribution partnerships with Mumbai-based logistics consolidators serving Mombasa and Dar es Salaam import flows. Lead with precision-delivery equipment leasing rather than chemical supply to bypass capital barriers for warehouse operators. For Investors and Strategic Acquirers: Capital is best deployed toward electrochemical generation technology specialists with Australian or US elevator operator reference contracts over legacy tablet formulators facing obsolescence. The five-to-ten year viability window favors equipment-integrated service models. Monitor EPA methyl bromide critical use exemption renewal decisions as the signal for sulfuryl fluoride demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captures margin pools currently concentrated in Belgian and German chlor-alkali corridors. |
| Electrochemical Generation Deployment | Eliminates tablet handling burdens for Iowa and New South Wales grain elevator operators. |
| East African Distribution Partnership | Positions first-mover advantage ahead of Kenya and Tanzania storage infrastructure buildout. |
| Precision-Delivery Equipment Certification | Meets ANVISA and China's MEE tightening residue documentation requirements. |
| Licensed Applicator Network Expansion | Addresses certification pipeline gaps in Brazil's Mato Grosso soybean belt. |
Research Methodology
Cross-validation between regulatory filing analysis and field-level operational data anchors the qualitative findings in this study. Primary interviews with grain elevator operations managers, licensed fumigation applicators, EPA and ANVISA regulatory affairs officers, and chlor-alkali plant procurement directors combined with secondary validation from EPA enforcement dockets, ECHA REACH authorization registers, customs trade flow databases, and SEC chemical company disclosures. Bottom-up facility-level capacity estimates and top-down trade flow analysis provide triangulation.
Calibration against historical methyl bromide phase-down trajectories and phosphine tablet production volumes informs the projection framework. Segmentation dimensions modeled include chemistry type, application context, end-user procurement sophistication, and regional regulatory cluster across the analysis window. CAGRs derive from facility investment pipelines and import certification requirement schedules. Electrochemical system adoption curves and licensed applicator certification completion rates serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in grain commodity price cycles, Brazilian real exchange rates, or European natural gas costs would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and technology adoption timelines. Specific risks include faster-than-anticipated electrochemical generation deployment or ANVISA protocol reversals. Cross-checking against USDA grain storage capacity surveys and Brazilian export certification statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Vaporized Hydrogen Peroxide Sterilization Systems Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
Asia-Pacific Agricultural Disinfectants Market