
 Snow Boots Market | 2026-2036
Snow Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Boots Market Outlook
Buyer concentration across the snow boots category is recalibrating as outdoor enthusiasts fragment into specialized sub-communities while mass retailers consolidate procurement volumes. Columbia Sportswear Company leverages its Pacific Northwest manufacturing heritage to anchor premium positioning in technical waterproof lines. Sorel Corporation competes through heritage branding and cold-climate specialization that sustains pricing power in Canadian and northern US markets. The North Face dominates alpine-adjacent distribution, controlling shelf space at specialty outdoor retailers across mountain resort corridors.
Snow boots are technically defined as insulated footwear engineered with thermal barriers rated to sub-zero temperatures, waterproof membranes, and lug-pattern outsoles designed for traction on ice and packed snow, serving the primary commercial purpose of preventing cold injury during prolonged winter exposure. The insulated product type leads absolute volume while waterproof constructions command the widest margin pools due to membrane technology licensing costs. Leather and synthetic materials split the premium tier, with Gore-Tex laminates occupying the technical-performance niche where replacement cycles compress and brand loyalty intensifies.
The US Consumer Product Safety Commission enforces flammability standards on footwear materials, while the EPA oversees chemical disclosures in synthetic rubber compounds, and REACH in Europe restricts perfluorinated compounds common in legacy waterproof treatments. These frameworks elevate compliance costs for synthetic-dominant portfolios while creating market access barriers for unverified imports. Stakeholders must monitor evolving chemical restriction schedules and decide whether to absorb reformulation costs or cede price-sensitive segments to compliant regional producers.
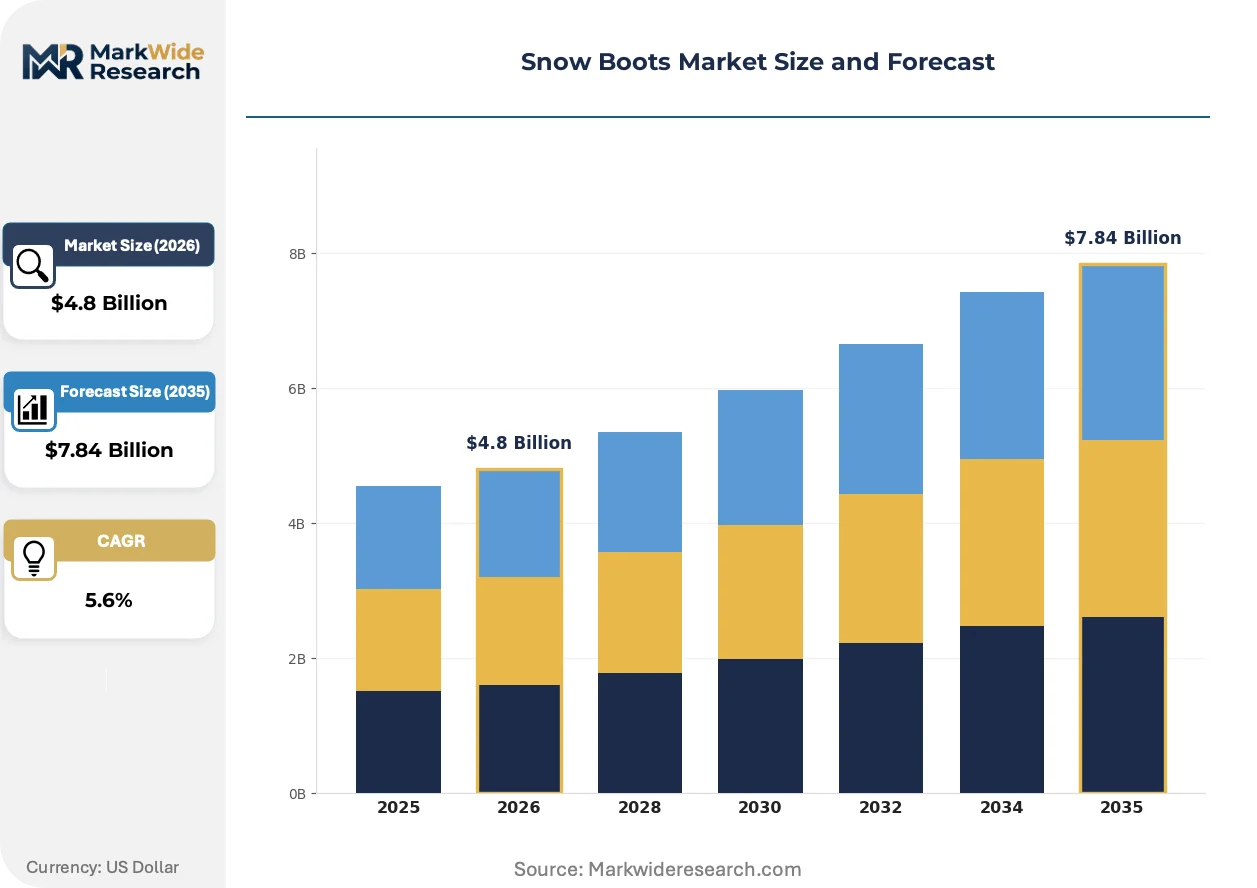
Market Dynamics
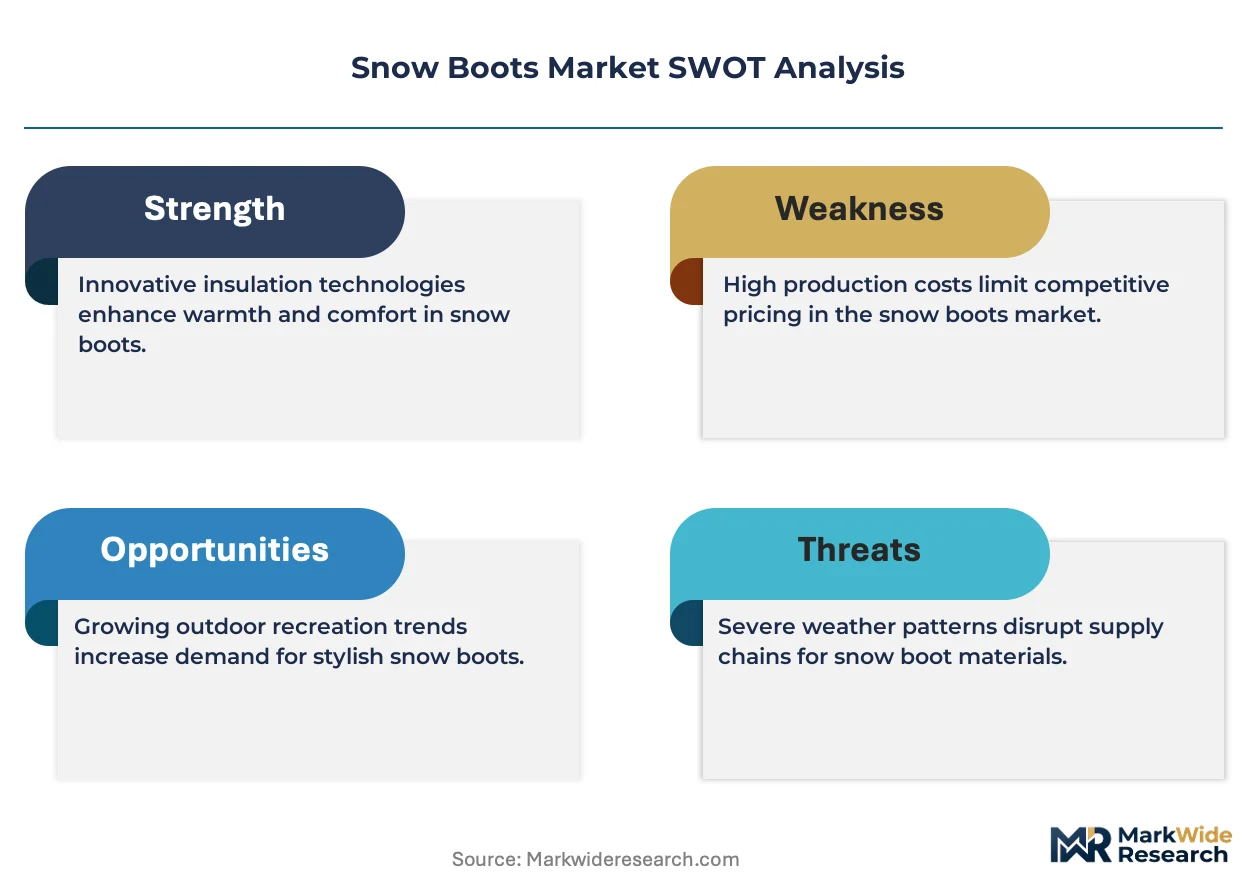
REACH chemical restrictions under the EU Green Deal are forcing reformulation of waterproof membrane chemistries, compressing margins for synthetic-dominant portfolios while opening premium positioning for bio-based insulation adopters.
Growth Catalysts
- Winter sports participation broadening:Outdoor enthusiasts fragment into specialized sub-communities beyond traditional skiing, expanding addressable demand for technical cold-weather footwear.
- REACH perfluorinated compound restrictions:European regulatory pressure on legacy waterproof treatments accelerates substitution toward bio-based membrane alternatives.
- Pacific Northwest manufacturing heritage:Technical waterproof production clusters in Oregon and Washington anchor premium supply chains for North American distribution.
Market Restraints
- Gore-Tex licensing cost concentration:Membrane technology royalties compress margin pools for waterproof constructions, favoring vertically integrated incumbents with captive laminate supply.
- Synthetic rubber compound disclosure requirements:EPA chemical oversight elevates compliance burdens for petroleum-derived outsole formulations.
- Canadian cold-climate specialization lock-in:Heritage brands dominate northern latitude positioning, creating brand equity barriers for new entrants in sub-zero performance tiers.
Strategic Opportunities
- Rocky Mountain metropolitan corridor expansion:Denver, Salt Lake City, and Boise clusters show concentrated premium turnover velocity for technical winter footwear.
- Bio-based insulation convergence:Mycelium-derived thermal barriers and aerogel composites enable differentiation from petroleum-dependent incumbents.
- Specialty outdoor retailer shelf space control:Alpine-adjacent distribution channels in mountain resort corridors reward exclusive technical partnerships.
Industry Challenges
- Flammability standard certification timelines:US Consumer Product Safety Commission testing protocols delay new material introductions by 8-14 months.
- Membrane-bonding technical talent scarcity:Skilled technicians for waterproof seam-sealing operations concentrate in legacy Pacific Northwest manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Boots Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated, Waterproof, Blister-proof, Lightweight End User: Men, Women, Kids, Outdoor Enthusiasts Material: Leather, Synthetic, Rubber, Gore-Tex Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Adidas AG, Nike Inc., Columbia Sportswear Company, PUMA SE, The North Face, UGG, Sorel Corporation, ASICS Corporation, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Boots Market Strategic Shifts
Bio-based material science is actively displacing petroleum-derived thermal barriers, while regulatory chemical restrictions compress legacy formulation options and specialized retail channels fragment mass-market consolidation.
Plant-derived insulation technologies are decentralizing thermal performance sourcing away from synthetic fiber concentration. Mycelium-based thermal barriers and cellulose aerogel composites now achieve R-values comparable to Thinsulate equivalents. Specialty outdoor retailers in Colorado and Utah are accelerating adoption curves for these alternatives. This decentralization is compressing royalty-dependent supply relationships with petroleum-chemistry incumbents.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy DWR treatments from European market access. Manufacturers must reformulate water-repellent chemistries using silicone or hydrocarbon alternatives before 2026 enforcement windows. Waterproof boot lines with Gore-Tex laminates face highest substitution pressure. European alpine retailers are prioritizing bio-based certified inventory to preempt compliance stockouts.
Buyer concentration patterns are fragmenting across specialized winter activity segments. Backcountry skiers, fat-bikers, and winter trail runners now demand segment-specific sole lug patterns and flex ratings. Mass sporting goods chains are ceding technical specification control to specialty outdoor retailers. This shift concentrates margin capture in mountain resort corridor storefronts across Montana, Wyoming, and Idaho.
Snow Boots Market Segmentation
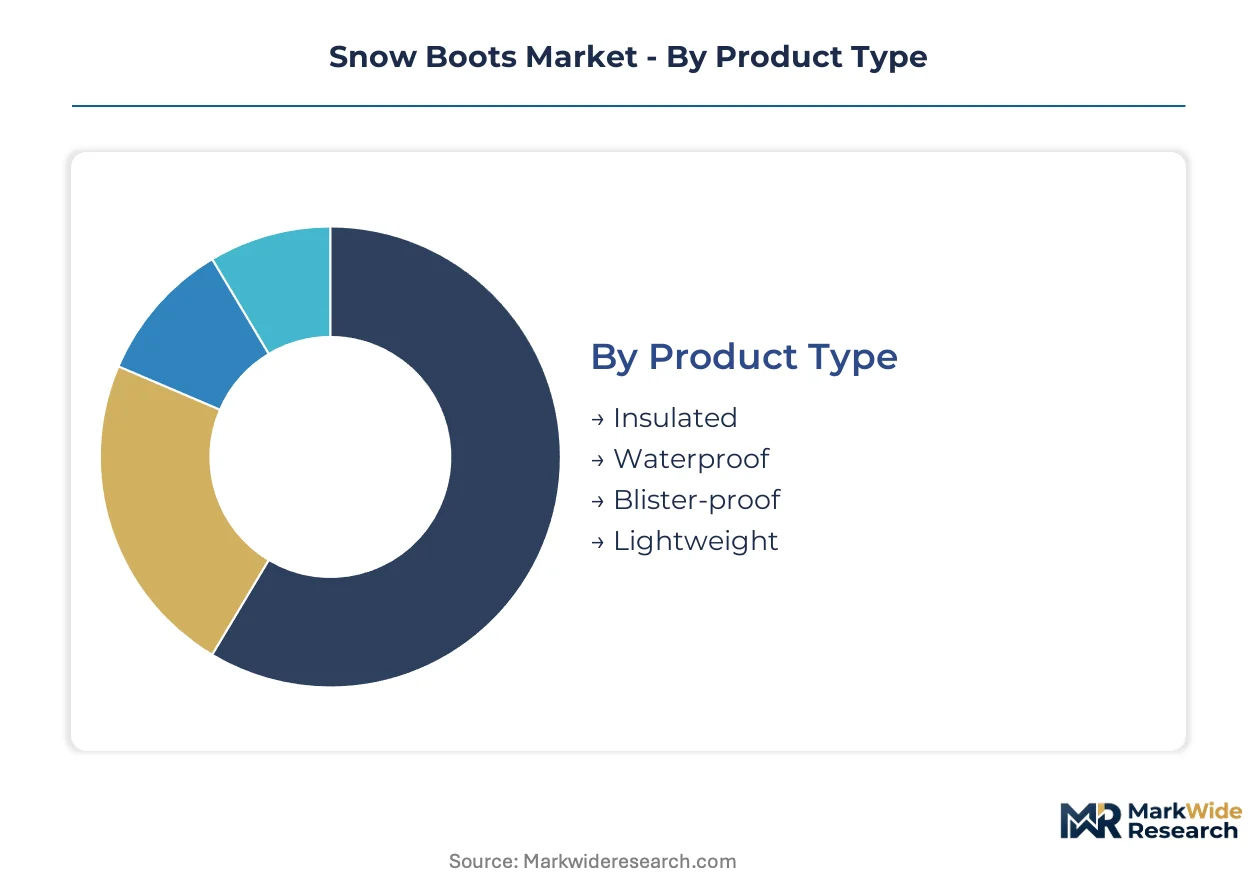
Snow boot purchasing decisions fragment across thermal performance requirements, waterproofing specifications, and activity-specific traction demands. Manufacturers must align product architecture with distinct buyer archetypes ranging from casual urban commuters to technical alpine specialists.
Product Type:
Thermal rating and moisture protection drive the primary purchase calculus across all climate zones and usage intensities.
- Insulated:Thermal barrier construction utilizing synthetic fiber batting or bio-based aerogel composites rated to sub-zero exposure. Demand concentrates in the Upper Midwest and Northeast corridors where prolonged cold snaps drive replacement cycles. EPA disclosure requirements on synthetic rubber compounds elevate compliance costs for petroleum-dependent thermal formulations.
- Waterproof:Membrane-laminated uppers with seam-sealed construction blocking liquid penetration while maintaining vapor transmission. Rocky Mountain metropolitan clusters in Denver and Salt Lake City generate premium turnover velocity for technical waterproof lines. REACH perfluorinated compound restrictions compress margin pools for legacy Gore-Tex laminate supply chains.
- Blister-proof:Ergonomic last design with friction-reducing liner interfaces engineered for extended wear durations. Long-distance winter hikers and snowshoe trekkers prioritize fit precision over thermal extremes.
- Lightweight:Reduced-mass construction through foam midsole substitution and synthetic upper panels targeting urban commuters and travel-oriented buyers. Pacific Northwest cities favor style-forward lightweight profiles for mixed-use winter wardrobes.
Insulated product types lead on scale; waterproof constructions lead on momentum.
End User:
Demographic segmentation reveals divergent price elasticity and feature prioritization patterns across household purchasing units.
- Men:Technical specification focus with higher willingness-to-pay for waterproof membrane ratings and lug depth measurements. Backcountry skiers and ice climbers drive premium tier concentration in specialty outdoor channels.
- Women:Design-forward thermal solutions balancing aesthetic versatility with cold-weather functionality. Urban professional segments in Minneapolis and Boston prioritize commuter-appropriate silhouettes.
- Kids:Rapid size-turnover segment with durability and growth-adjust features dominating parental purchase criteria. Value-tier concentration in mass sporting goods and department store channels.
- Outdoor Enthusiasts:Activity-specific technical demands spanning fat-biking, winter trail running, and backcountry skiing sub-communities. This segment is expanding most quickly as winter sports participation broadens beyond traditional alpine skiing.
Men's technical specifications lead on scale; outdoor enthusiasts lead on momentum.
Material:
Raw material selection determines regulatory compliance exposure, supply chain concentration, and end-of-life circularity pathways.
- Leather:Full-grain or nubuck uppers with natural water resistance and extended patina aging characteristics. Premium positioning in heritage brand portfolios with Canadian cold-climate specialization.
- Synthetic:Petroleum-derived textile uppers and thermal barriers subject to EPA chemical disclosure mandates and REACH restriction schedules. Cost concentration in mass-market waterproof constructions.
- Rubber:Natural or synthetic compound outsoles delivering ice traction through lug pattern geometry. Pacific Northwest manufacturing clusters anchor technical rubber formulation expertise.
- Gore-Tex:Proprietary expanded polytetrafluoroethylene membrane laminates commanding technology licensing royalties. Specialty outdoor retailers control distribution access for certified Gore-Tex product lines.
Synthetic materials lead on scale; leather constructions lead on momentum.
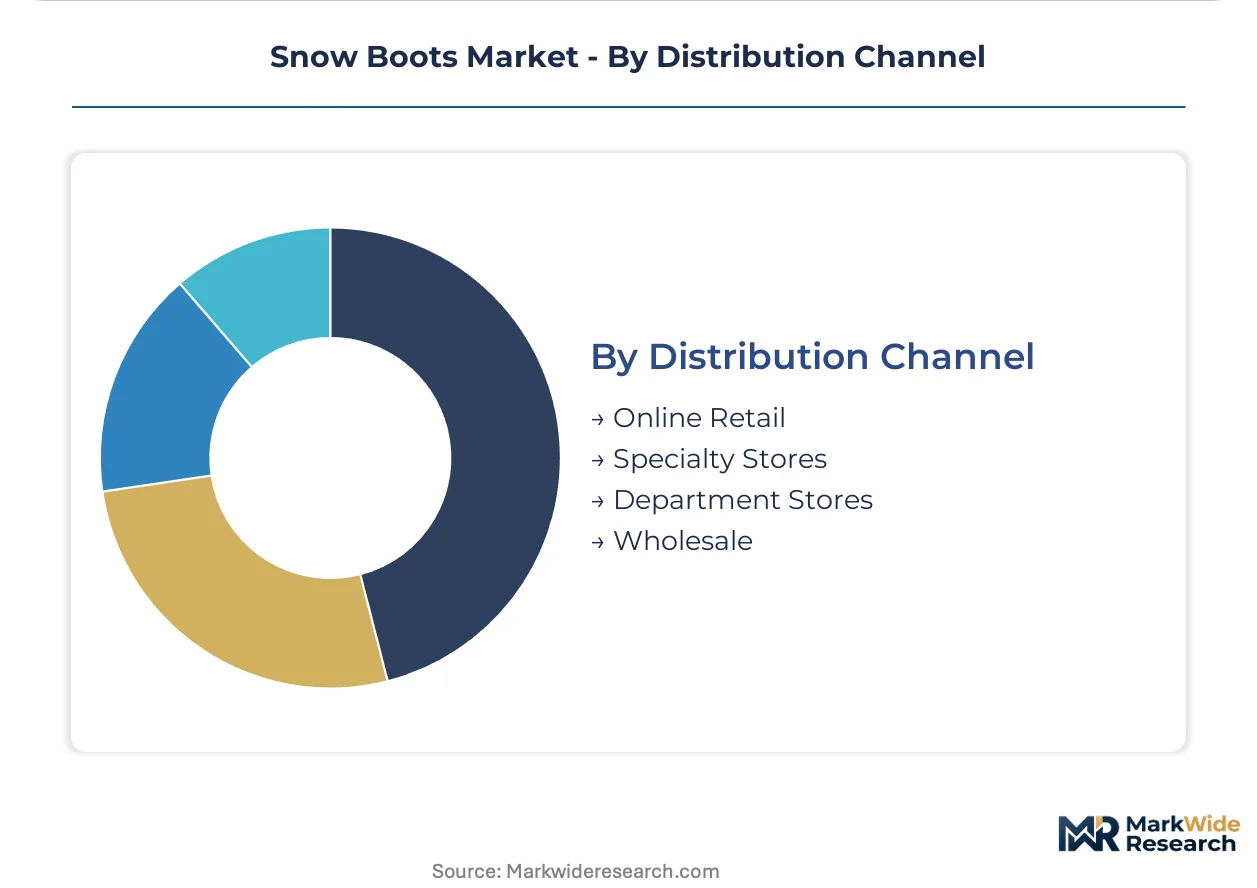
Distribution Channel:
Channel selection determines margin capture, technical specification control, and inventory velocity across seasonal demand curves.
- Online Retail:Direct-to-consumer and marketplace platforms enabling size-range breadth and return-policy flexibility. Urban buyers without specialty retail proximity default to digital channels for technical product research.
- Specialty Stores:Alpine-adjacent storefronts in mountain resort corridors with trained staff delivering fit consultation and activity-matching expertise. Exclusive brand partnerships concentrate margin capture in Colorado, Utah, and Idaho clusters.
- Department Stores:Seasonal promotional calendars and gift-giving occasion concentration drive volume in insulated and lightweight categories. Price-sensitive family segments prioritize accessibility over technical depth.
- Wholesale:Bulk procurement relationships with outfitters, ski resorts, and corporate uniform programs. Volume concentration in standardized specifications with limited customization.
Specialty stores lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for technical winter footwear outpaces Canadian volume by roughly three-to-one, yet Canadian heritage brands command stronger pricing power in sub-zero performance tiers. This divergence shapes how manufacturers allocate production capacity and brand positioning across North American distribution networks.
United States
Rocky Mountain metropolitan clusters in Denver, Salt Lake City, and Boise generate concentrated premium turnover velocity for waterproof technical lines. EPA disclosure requirements on synthetic rubber compounds elevate compliance costs for petroleum-dependent outsole formulations. Pacific Northwest manufacturing facilities in Oregon and Washington anchor seam-sealing expertise for membrane-laminated constructions.
Canada
Cold-climate specialization heritage sustains brand equity barriers for new entrants targeting sub-zero performance tiers. Health Canada and PMRA oversee chemical safety standards for footwear materials entering domestic distribution. Quebec and Ontario manufacturing corridors concentrate leather tanning and thermal barrier assembly operations serving northern latitude markets.
Germany
REACH Annex XVII restrictions on perfluorinated compounds eliminate legacy DWR treatments from European market access by 2026 enforcement windows. KBA and ECHA coordinate chemical compliance verification for imported footwear formulations. Bavaria-based alpine equipment distributors control specialty retail shelf space for certified bio-based membrane alternatives.
Japan
Winter sports participation broadens beyond traditional skiing into backcountry and snowshoe trekking sub-communities. METI governs product safety standards for insulated footwear under Consumer Product Safety Act provisions. Nagoya and Osaka manufacturing clusters specialize in lightweight foam midsole substitution for urban commuter segments.
South Korea
Outdoor enthusiast fragmentation creates demand for segment-specific sole lug patterns targeting fat-biking and winter trail running. MFDS regulates chemical safety disclosures in synthetic textile uppers under consumer goods frameworks. Seoul Capital Area retail corridors concentrate style-forward lightweight profiles for mixed-use winter wardrobes.
Snow Boots Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Columbia Sportswear Company and The North Face leverage Pacific Northwest manufacturing heritage to anchor premium technical waterproof lines. Sorel Corporation occupies heritage cold-climate specialization positioning. Competitive moves concentrate on bio-based insulation material substitution and exclusive specialty retail partnerships in mountain resort corridors.
Within the heritage-brand tier, Columbia Sportswear Company, Sorel Corporation, and The North Face represent distinct geographic anchoring strategies. Columbia Sportswear Company exemplifies Pacific Northwest technical production clustering. Sorel Corporation occupies Canadian cold-climate specialization positioning. The North Face sits within alpine-adjacent distribution control archetypes. These three anchors demonstrate how manufacturing heritage and regional climate exposure shape competitive differentiation in thermal performance footwear.
| Leading Market Players |
|---|
| Adidas AG |
| Nike Inc. |
| Columbia Sportswear Company |
| PUMA SE |
| The North Face |
| UGG |
| Sorel Corporation |
| ASICS Corporation |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Seam-sealing technician scarcity in Oregon and Washington manufacturing clusters widens labor-cost differentials between technical waterproof tiers and commodity insulated lines. Pacific Northwest wage premiums for membrane-bonding specialists compress margins at standard-tier price points while reinforcing pricing power for Gore-Tex-certified premium constructions.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for synthetic-dominant insulated boots while Pacific Northwest technical production sustains premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates Gore-Tex-laminate alpine lines from Thinsulate commuter boots from basic rubber-shell utility footwear. Price differentiation stems from certification grade and geographic delivery cost, with REACH-compliant bio-based membranes commanding modest premiums. Pricing pressure stems from synthetic rubber compound disclosure requirements elevating compliance burdens. Value-tier family buyers show highest price sensitivity; backcountry skiers and ice climbers demonstrate lowest.
Supply Chain Analysis
Gore-Tex membrane supply rests on proprietary ePTFE production concentrated in Delaware and Japan facilities. Raw material dependencies span Chinese synthetic fiber batting, Malaysian natural rubber, and Italian full-grain leather. Single-source vulnerability concentrates in membrane technology licensing where captive supply advantages favor vertically integrated incumbents. Distribution runs through specialty outdoor retailers in mountain resort corridors, department store seasonal promotions, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential as bio-based insulation substitution reduces royalty-dependent petroleum chemistry exposure and enables premium-tier repositioning.
For Market Incumbents: Anchor Pacific Northwest manufacturing heritage through exclusive seam-sealing technician retention programs and captive membrane-laminate supply investments. Defend against bio-based insulation substitutes by accelerating mycelium-derived thermal barrier R&D partnerships. Prioritize certification investment in REACH-compliant water-repellent chemistries to preempt European compliance stockouts. For New Entrants and Emerging Players: Capture Rocky Mountain metropolitan corridor specialty retail shelf space through exclusive technical partnerships with Denver and Salt Lake City storefronts. Penetrate the outdoor enthusiast segment fastest through segment-specific sole lug patterns for fat-biking and winter trail running sub-communities. Pursue direct-to-consumer digital launch with size-range breadth and return-policy flexibility to bypass incumbent wholesale relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among synthetic-dependent mass-market manufacturers facing REACH reformulation cost compression. Long-term viability favors bio-based insulation adopters with technical certification pipelines and specialty channel control. Watch mycelium-thermal-barrier adoption velocity at Colorado and Utah specialty retailers as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Insulation Transition | Mycelium-derived thermal barriers displace Thinsulate royalty structures and unlock REACH-compliant European market access. |
| Specialty Retail Partnership Expansion | Exclusive shelf-space agreements in mountain resort corridors concentrate margin capture away from mass sporting goods chains. |
| Seam-Sealing Technical Talent Acquisition | Pacific Northwest technician retention secures membrane-bonding capacity advantages for waterproof construction tiers. |
| REACH-Compliant DWR Reformulation | Silicone and hydrocarbon water-repellent chemistries replace perfluorinated compounds before enforcement windows eliminate legacy formulations. |
| Direct-to-Consumer Channel Launch | Digital platforms bypass wholesale margin compression and enable urban commuter segment penetration without specialty retail proximity. |
Study Parameters
Multiple input streams — primary interviews with brand managers and category buyers at specialty outdoor retailers, technical R&D directors at membrane suppliers, and supply planners at Pacific Northwest manufacturing facilities — were reconciled against secondary validation from customs records, SEC 10-K footwear segment disclosures, and ECHA REACH restriction schedules. Bottom-up product-line volume estimates and top-down category spending analysis were triangulated to anchor market sizing.
Historical volume trajectories were cross-referenced against panel input from procurement leads and channel sales heads to model demand curves across the projection horizon. Segmentation dimensions included thermal performance tier, waterproofing specification, end-user demographic, material composition, and distribution channel type. CAGRs were derived from fitted growth curves incorporating winter sports participation indices, regulatory compliance cost schedules, and metropolitan cluster income elasticity estimates for technical footwear.
Regulatory enforcement delays, bio-based material scale-up failures, and specialty retail consolidation are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Platform Boots Market
Footwear
Training Shoes Market
Footwear
Sneaker Boots Market
Footwear
E-Commerce Footwear Market
Footwear
Europe Athletic Footwear Market
Footwear
Premium Shoes Market
Footwear
Winter Footwear Market
Footwear
Shoe Rental Service Market
Footwear
Western Boots Market
Footwear
United States Footwear Market
Footwear
Men Formal Shoe Market
Footwear
High Heels Footwear Market
Footwear
Lace Up Boots Market
Footwear
Self-Lacing Shoes Market
Footwear
Asia Pacific Footwear Market
Footwear
Protective Footwear Market