
 Men Formal Shoe Market | 2026-2036
Men Formal Shoe Market Size, Share, and Industry Trends Forecast 2026-2036
Men Formal Shoe Market Foresight
Synthetic microfiber is pivoting toward premium formal shoe uppers as tanneries face volatile hide costs and consistency demands. Alden Shoe Company sustains its position through captive leather sourcing and bench-grade construction standards. Hugo Boss AG leverages vertical control over European finishing facilities to maintain color-matching precision across seasonal lines.
Men formal shoes are closed-toe footwear constructed with leather or leather-alternative uppers, stacked leather or synthetic soles, and structured lasts designed for business, ceremonial, and professional environments; Goodyear welt construction remains the benchmark for durability and resoleability in premium tiers. Oxford styles dominate boardroom and black-tie applications due to their closed-lacing formality, while loafer variants capture share in business-casual workplaces where slip-on convenience outweighs traditional dress codes. Patent leather commands concentrated margin pools in event-rental and bridal-party channels despite narrow everyday adoption.
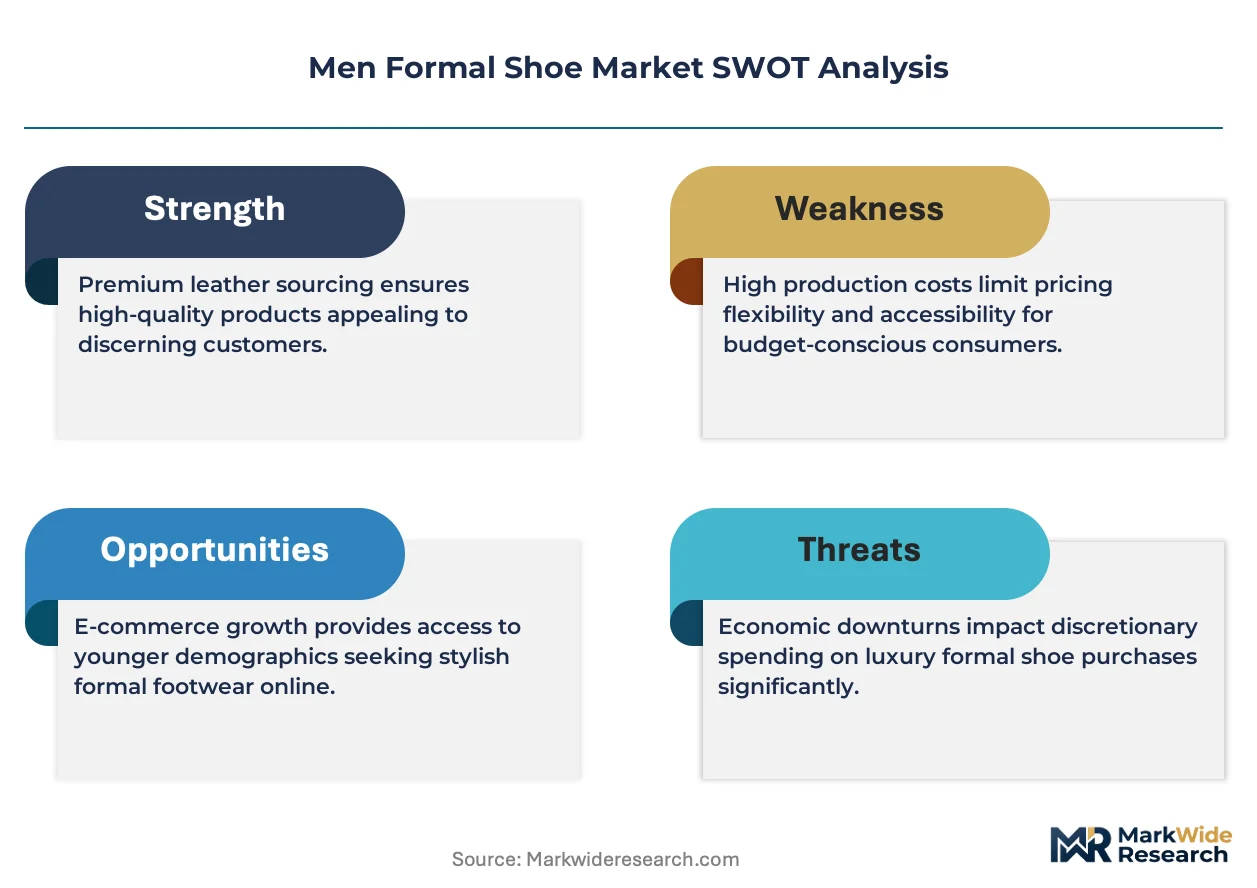
REACH and RoHS frameworks in Europe restrict hazardous substances in footwear finishing, while the US EPA monitors volatile organic compound emissions from adhesive-intensive cemented construction; these standards elevate compliance costs for synthetic-sole producers but create preference pull toward verified vegetable-tanned leather supply chains. Stakeholders must monitor how bio-based polyurethane advances alter the cost gap between leather and synthetic uppers before committing to multi-year material contracts.
Market Dynamics
REACH restrictions on chromium-based tanning agents are forcing tanneries across Europe and export-dependent clusters to retool finishing lines, compressing lead times for vegetable-tanned leather while elevating input costs for conventional chrome-tanned uppers.
Growth Catalysts
- Corporate Uniform Programs:Fortune 500 procurement teams are expanding executive footwear allowances and standardized boardroom dress codes, creating predictable volume commitments for bench-grade manufacturers.
- REACH Compliance Premium:European environmental frameworks now mandate verified chemical-free finishing, pulling brand positioning toward vegetable-tanned supply chains with traceable audit trails.
- Wedding-Season Concentration:India's domestic manufacturing clusters sustain peak demand cycles through ceremonial consumption patterns and gift-economy purchase traditions.
Market Restraints
- Hide Cost Volatility:Beef production fluctuations and dairy herd reductions in Brazil and Australia transmit directly to raw material pricing for full-grain uppers.
- Tannery Geographic Concentration:Over half of premium vegetable-tanned leather originates from Tuscan and Spanish clusters, creating single-source vulnerability for color-matched seasonal lines.
- Synthetic Microfiber Substitution Ceiling:Breathability limitations and heat retention in closed-toe formal constructions cap adoption rates despite cost advantages.
Strategic Opportunities
- Underpenetrated Southeast Asia:Vietnam and Indonesia's emerging white-collar workforce lacks established domestic bench-grade suppliers, opening channel development for imported premium lines.
- Bio-Based Polyurethane Convergence:Castor-oil derived midsoles combined with recycled rubber outsoles enable carbon-neutral positioning without leather dependency.
- Rental-Channel Expansion:Event-rental platforms for black-tie occasions create recurring revenue streams bypassing retail inventory risk for patent leather and opera pump styles.
Industry Challenges
- Master Craftsman Shortage:Goodyear welt construction requires multi-year apprenticeship pipelines that collapsed in post-industrial economies, constraining bench-grade production scaling.
- Dual Certification Timelines:Simultaneous ISO 9001 quality management and LWG leather working group audits extend supplier onboarding by eight to fourteen months.
- Last Digitization Costs:3D foot-scanning infrastructure for bespoke fitting demands capital outlays that fragment between automated and hand-carved last traditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Men Formal Shoe Market |
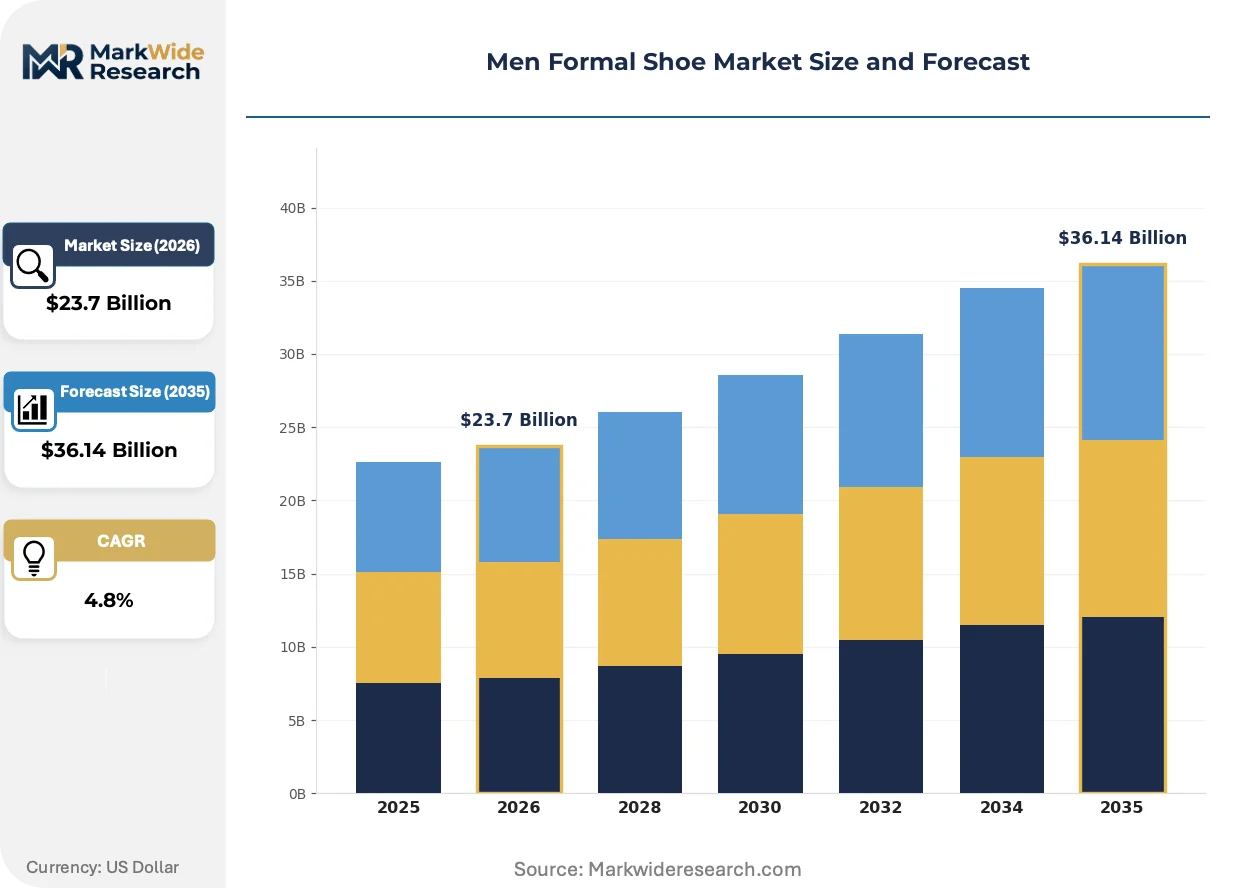
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxford, Derby, Loafers, Monk Straps Material: Leather, Suede, Synthetic, Patent Leather Closure Type: Lace-Up, Slip-On, Buckle, Zipper Price Range: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Guccio Gucci S.p.A, Hugo Boss AG, Burberry Group Plc, Cole Haan, Alden Shoe Company, Allen Edmonds Corporation, C. & J. Clark International Ltd., Prada S.p.A., LVMH Moët Hennessy Louis Vuitton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Men Formal Shoe Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are compressing the performance gap between traditional leather uppers and engineered alternatives, while procurement centralization in corporate channels rewards suppliers with traceable compliance documentation.
Water-based polyurethane microfiber with embossed grain patterns is overtaking split leather in mid-tier Oxford constructions. Corporate procurement teams in financial services and legal sectors are adopting these uppers for daily-wear programs where durability requirements exceed aesthetic prestige. This material transition is compressing tannery margins on lower-grade hides while elevating finish consistency demands on synthetic producers.
REACH Annex XVII restrictions on chromium VI compounds now prohibit residues above three parts per million in leather articles placed on the European market. Tanneries in Italy and Spain have invested in vegetable tanning pits and synthetic retanning agents to maintain market access. Exporters from India and Pakistan face elevated testing costs and border detention risks as ECHA enforcement intensifies through 2026.
Centralized corporate footwear allowances are displacing individual expense reimbursement for white-collar employees. Human resources departments in technology and consulting verticals now negotiate direct supplier contracts for standardized sizing and bulk replacement programs. This concentration is most visible in London, New York, and Singapore where hybrid work policies have formalized "office day" dress code requirements.
Men Formal Shoe Market Segmentation
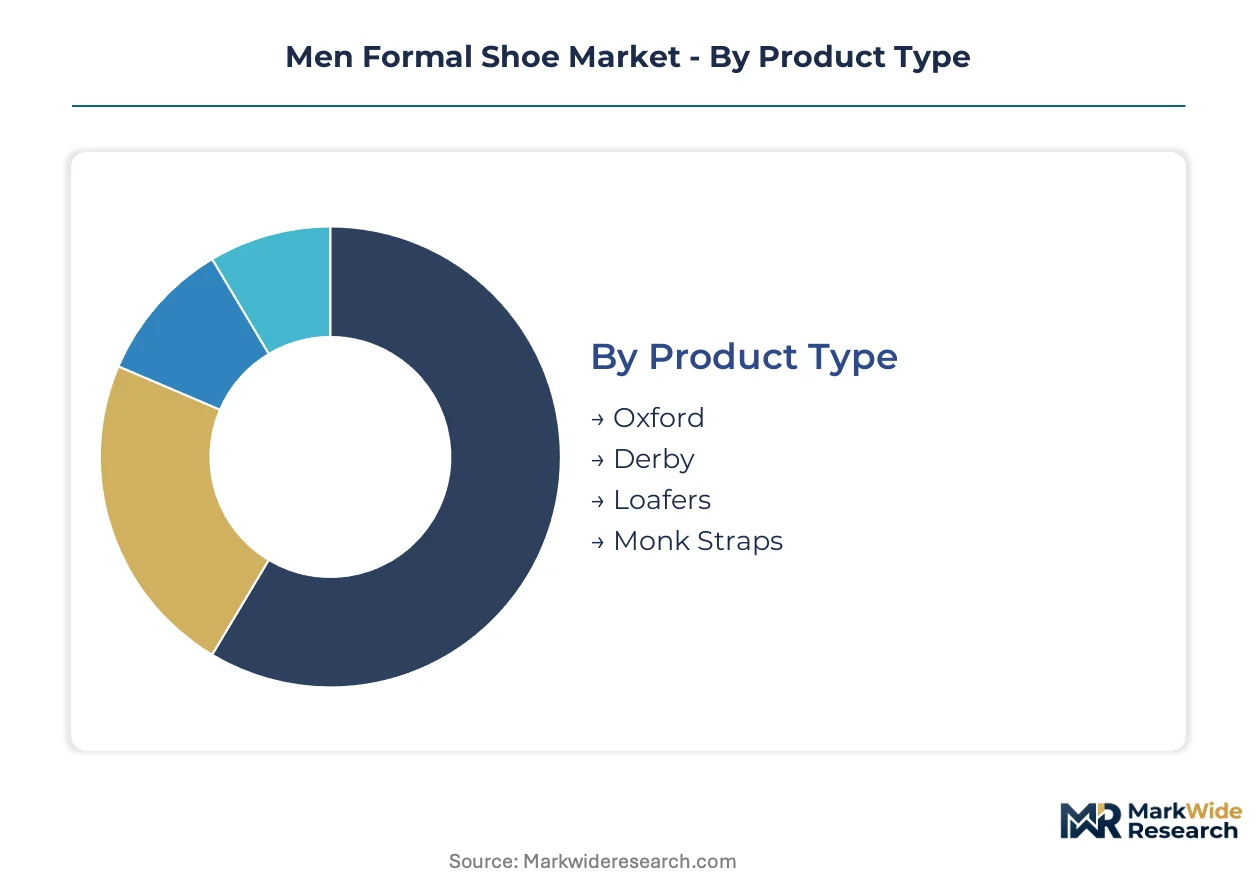
Formal shoe procurement divides sharply between ceremonial gift economies and corporate uniform programs, with construction method and material traceability now outweighing aesthetic tradition in contract decisions. Buyers sort across price tiers based on resoleability guarantees, chemical compliance documentation, and seasonal color-matching precision rather than style alone.
Product Type:
Purchase frequency and occasion specificity separate buyers more than workplace dress code stringency, with wedding-season bulk orders driving entirely different sourcing logic than executive allowance programs.
- Oxford:Closed-lacing construction with quarters stitched under the vamp creates the most formal silhouette. Boardroom procurement in London and Singapore concentrates here, driven by black-tie rental channel demand and law firm partnership traditions.
- Derby:Open-lacing construction permits wider foot entry and accommodates orthotic inserts. German automotive executives and Japanese salarymen favor this style for daily office wear where comfort requirements override pure formality.
- Loafers:Venetian and penny variants capture business-casual workplaces in US technology corridors where slip-on convenience outweighs lace-up tradition.
- Monk Straps:Single and double-buckle closures appeal to fashion-forward professionals in Milan and Paris seeking differentiation within conservative dress codes.
Volume sits with Oxford; growth tilts toward Loafers.
Material:
Hide grade and tanning chemistry now determine supplier eligibility before price negotiation, with REACH-compliant vegetable tanning mandatory for European market access regardless of end-use.
- Leather:Full-grain and top-grain hides from Tuscan tanneries dominate premium bench-grade construction. Indian wedding-season consumption and Italian export orders sustain volume for chrome-free vegetable-tanned supply chains facing ECHA enforcement.
- Suede:Napped reverse-side finishes from calfskin or goatskin require specialized brushing equipment and humidity-controlled storage. Summer event rentals in Spain and Portugal favor this material for lightweight ceremony footwear.
- Synthetic:Water-based polyurethane microfiber with embossed grain patterns displaces split leather in mid-tier corporate programs. Breathability limitations cap adoption despite cost advantages over hide-based uppers.
- Patent Leather:High-gloss lacquered finishes command concentrated margin pools in bridal-party and black-tie rental channels despite narrow everyday adoption.
Revenue concentrates in Leather; synthetic alternatives are expanding most quickly.
Closure Type:
Construction labor intensity and bespoke fitting infrastructure separate procurement channels, with automated sizing programs favoring standardized closure mechanisms over artisan-adjusted alternatives.
- Lace-Up:Five to seven eyelet configurations permit width adjustment across instep variations. Traditional bench-grade manufacturers in Northampton, England and Almansa, Spain anchor production for this closure type requiring hand-stitched facings.
- Slip-On:Elastic goring or unconstructed vamps enable entry without fasteners. Southeast Asian white-collar adoption in Vietnam and Indonesia drives import demand for this convenience-oriented construction.
- Buckle:Monk strap and kiltie variants demand precise hole punching and hardware attachment. Smaller production runs from Portuguese workshops serve this stylistically distinctive segment.
- Zipper:YKK or Riri hardware integration appears primarily in fashion-forward and accessibility-oriented designs rather than traditional formal applications.
Shipments favor Lace-Up; fastest share gains belong to Slip-On.
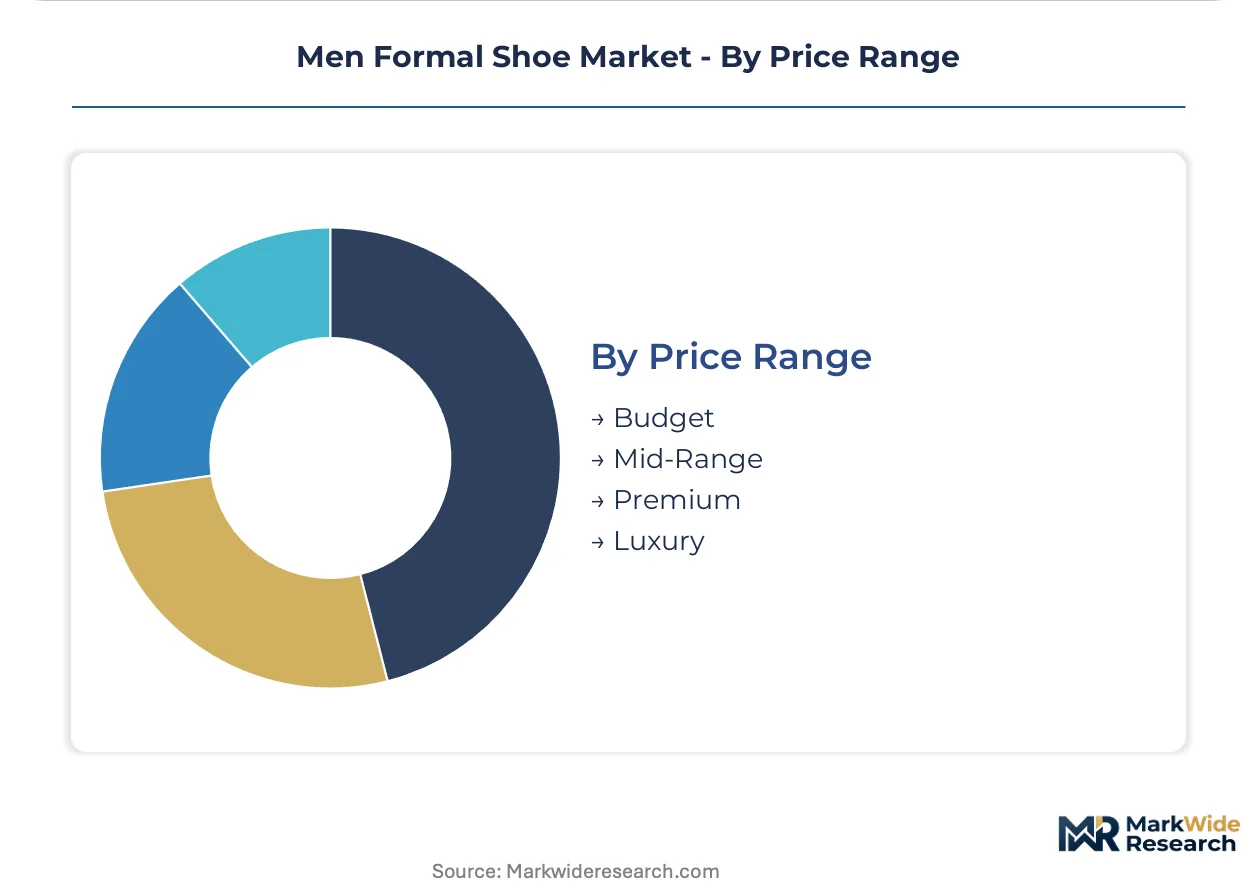
Price Range:
Resoleability guarantees and construction documentation separate tiers more than material cost alone, with Goodyear welt certification commanding persistent premiums despite synthetic upper convergence.
- Budget:Cemented construction with polyurethane soles and corrected-grain or synthetic uppers. Mass retail in India's tier-two cities and Southeast Asian department stores sustains volume for disposable-wear cycles.
- Mid-Range:Blake-stitched or combination construction with leather soles and full-grain uppers. US and UK corporate uniform programs concentrate procurement here for two-year replacement cycles.
- Premium:Verified Goodyear welt construction from Northampton or Almansa workshops with LWG-certified leather. Fortune 500 executive allowances and Japanese gift-economy purchases drive demand.
- Luxury:Bespoke last creation, hand-painted patina, and museum calf exclusivity. Paris and Milan flagship boutiques serve ultra-high-net-worth collectors with multi-month fulfillment timelines.
Unit volume flows through Budget; value expansion concentrates in Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates ceremonial and wedding-season demand through domestic manufacturing clusters, while corporate procurement programs in London, New York, and Singapore drive premium bench-grade volume. Regulatory divergence across tanning chemistry standards fragments supplier compliance requirements.
India
Wedding-season consumption and gift-economy traditions sustain peak demand cycles for ceremonial footwear. The Bureau of Indian Standards enforces quality specifications for leather goods through mandatory ISI certification. Domestic manufacturing clusters in Agra and Kanpur supply volume for both export markets and domestic ceremonial channels.
United Kingdom
Corporate uniform programs in London's financial services sector standardize boardroom dress codes for hybrid office requirements. REACH enforcement through ECHA restricts chromium VI residues in imported leather articles. Northampton's bench-grade workshops anchor Goodyear welt production for Fortune 500 executive allowances.
Italy
Milan and Paris fashion-forward professionals drive demand for monk strap and differentiated formal styles. ECHA's Annex XVII restrictions on hazardous substances elevate compliance costs for conventional chrome-tanned uppers. Tuscan tanneries in Santa Croce sull'Arno retool toward vegetable tanning pits to maintain European market access.
United States
Technology and consulting verticals centralize footwear allowances through direct supplier contracts. EPA monitoring of volatile organic compound emissions from adhesive-intensive construction elevates compliance documentation requirements. New York and Chicago procurement teams negotiate standardized sizing programs for white-collar replacement cycles.
Vietnam
Emerging white-collar workforce in Ho Chi Minh City and Hanoi lacks established domestic bench-grade suppliers. Import channels from European and Japanese manufacturers fill premium segment gaps. Local distributors develop sizing infrastructure for corporate uniform programs targeting financial services expansion.
Men Formal Shoe Market Competitive Landscape
Vertical integration into captive leather sourcing dominates the current landscape as tannery cost volatility compresses margins on conventional procurement models. The vendor base stratifies across three tiers: heritage bench-grade workshops with multi-decade craftsmanship pipelines, mid-tier specialists leveraging synthetic microfiber convergence, and luxury houses controlling finishing facilities for color-matching precision. Strategic archetypes include compliance-forward suppliers with traceable vegetable-tanned supply chains, scale-driven manufacturers serving corporate uniform programs, and bespoke ateliers preserving hand-carved last traditions. M&A activity concentrates on tannery acquisitions securing hide supply, while geographic expansion targets underpenetrated Southeast Asian white-collar channels.
Among heritage American bench-grade specialists, Alden Shoe Company and Allen Edmonds Corporation exemplify the craftsmanship-preservation archetype through multi-year apprenticeship pipelines. Hugo Boss AG occupies a position within the European vertical-integration tier, leveraging in-house finishing facility control. Guccio Gucci S.p.A and Prada S.p.A sit within the luxury house segment where museum calf exclusivity and hand-painted patina command multi-month fulfillment timelines. These named entities represent distinct competitive positioning vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Guccio Gucci S.p.A |
| Hugo Boss AG |
| Burberry Group Plc |
| Cole Haan |
| Alden Shoe Company |
| Allen Edmonds Corporation |
| C. & J. Clark International Ltd. |
| Prada S.p.A. |
| LVMH Moët Hennessy Louis Vuitton |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between Goodyear welt bench-grade and cemented construction creates a pricing ladder that tracks backward into tannery sourcing decisions and forward into corporate procurement contract structures. Premium tiers command resoleability guarantees through captive Tuscan vegetable-tanned supply chains, while mid-market synthetic microfiber programs compete on two-year replacement cycles and standardized sizing.
Pricing Analysis
Volume flows through budget cemented constructions with polyurethane soles and synthetic uppers, while value concentrates in premium Goodyear welt tiers with LWG-certified leather and resoleability documentation. Price differentiation hinges on construction certification grade and traceable compliance documentation rather than material cost alone. Pricing pressure stems from hide cost volatility transmitting through Brazilian and Australian beef production fluctuations. Corporate uniform programs exhibit lowest price sensitivity given standardized replacement cycles, whereas Indian wedding-season bulk buyers negotiate aggressively on volume.
Supply Chain Analysis
Full-grain hide supply rests on Tuscan and Spanish tanning clusters, with vegetable-tanned output increasingly favored for REACH Annex XVII compliance. Raw material dependencies center on calfskin grades, chromium-free retanning agents, and water-based polyurethane microfiber feedstocks. Single-source vulnerability concentrates in color-matched seasonal lines dependent on Santa Croce sull'Arno tanneries. Distribution runs through corporate procurement direct contracts, bridal-party rental platforms, and flagship boutique channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master craftsman apprenticeship pipeline collapse constrains bench-grade production scaling, propping pricing power for heritage workshops with intact training infrastructure. Supply scarcity in verified vegetable-tanned channels reinforces margin capture for compliant suppliers.
For Market Incumbents: Extend compliance-forward positioning by securing captive vegetable-tanned supply through tannery acquisition or long-term offtake agreements with Tuscan clusters. Invest in ISO 9001 and LWG dual certification infrastructure to compress supplier onboarding timelines. Synthetic microfiber substitution threatens mid-market leather share; defend through breathability innovation in closed-toe constructions.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Southeast Asian white-collar channels offers white-space entry for imported bench-grade lines with localized sizing programs. Target Vietnam's financial services expansion in Ho Chi Minh City through corporate uniform direct contracts. Exploit rental-channel expansion for patent leather event footwear with recurring revenue models bypassing retail inventory risk.
For Investors and Strategic Acquirers: Re-rating potential sits with vegetable-tanned supply chain owners given ECHA enforcement intensification and brand pull toward traceable audit trails. Long-term viability favors tannery assets with REACH-compliant retooling completion. Monitor bio-based polyurethane cost convergence as inflection signal for synthetic upper displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Tannery Acquisition | Captive vegetable-tanned supply secures REACH compliance and color-matching precision for seasonal lines. |
| Corporate Uniform Direct Contract | Centralized procurement in London and Singapore creates predictable volume commitments for bench-grade manufacturers. |
| Rental Channel Partnership | Event-rental platforms for black-tie occasions generate recurring revenue bypassing retail inventory exposure. |
| 3D Foot-Scanning Infrastructure | Bespoke fitting technology bridges automated sizing with hand-carved last traditions for premium positioning. |
| Bio-Based Polyurethane Development | Castor-oil derived midsoles enable carbon-neutral positioning without leather dependency in mid-tier segments. |
Research Methodology
Trade databases, tannery association publications, and customs records formed the secondary backbone, supplemented by primary interviews with bench-grade workshop managers, corporate procurement leads at Fortune 500 firms, bridal-party rental platform operators, and ECHA compliance officers. Bottom-up triangulation across product-type volume estimates converged with top-down macroeconomic drivers to validate market sizing.
Historical trendline analysis tracked construction method shifts, material substitution patterns, and regional demand concentration across the projection horizon. Segmentation modeling incorporated product type, material chemistry, closure mechanism, price tier, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves adjusted for wedding-season cyclicality and corporate procurement centralization trends.
Underlying measurement precision varies by segment; premium bench-grade channels with documented LWG certification carry tighter precision than fragmented budget tier estimates. Forecasts reflect assumptions regarding REACH enforcement intensity and bio-based material cost convergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Self-Lacing Shoes Market
Footwear
Desert Boots Market
Footwear
Tactical Footwear Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Snow Boots for Women Market
Footwear
High Heels Footwear Market
Footwear
Tennis Shoes Market
Footwear
Loafers Market
Footwear
Sneaker Identification Service Market
Footwear
E-Commerce Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
United States Footwear Market
Footwear
Trail Running Shoes Market
Footwear
North America Footwear Market
Footwear
PVC Footwear Market
Footwear
Footwear Manufacturing Machinery Market