
 Premium Shoes Market | 2026-2036
Premium Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Shoes Market Analytics
Artisan leather craftsmanship is unwinding across European supplier networks, constraining production capacity for hand-finished dress shoes. Nike Inc. leverages advanced automated knitting to reduce labor dependency in performance footwear. Adidas AG anchors its premium positioning through proprietary Boost foam chemistry and controlled distribution. LVMH Moët Hennessy Louis Vuitton SE dominates ultra-luxury leather goods integration, extending atelier techniques into limited footwear editions.
Premium shoes denote footwear engineered with superior materials, precision construction, and elevated aesthetic standards, typically incorporating full-grain leather uppers, Blake or Goodyear welted soles, and cushioning systems exceeding baseline comfort metrics for extended wear. Luxury Sneakers now command the fastest expansion within the product type dimension, driven by streetwear crossover and resale platform liquidity. Leather sustains margin concentration across the material split, though textile innovation in knit uppers is capturing athlete and collector segments simultaneously.
EU REACH restrictions on chromium tanning compounds are reshaping material sourcing decisions for European manufacturers, while the US Consumer Product Safety Commission monitors phthalate content in synthetic youth-oriented lines. China's GB standards for footwear durability and the EU Green Deal's embodied carbon tracking requirements are converging to elevate compliance costs for synthetic-heavy portfolios. Stakeholders must weigh captive leather processing against third-party certified alternatives as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
EU REACH restrictions on chromium tanning compounds are forcing European tanneries to abandon century-old processing methods, triggering a supply chain reconfiguration that favors bio-alternatives and certified leather imports from South America.
Growth Catalysts
- 3D Knitting Automation:Advanced robotic knitting systems reduce labor hours per upper while enabling mass customization at premium price points.
- Resale Platform Liquidity:Secondary market infrastructure validates limited-edition releases as alternative assets, sustaining primary market price premiums.
- EU Green Deal Embodied Carbon Tracking:Mandatory lifecycle disclosure requirements favor manufacturers with verified low-carbon material sourcing.
Market Restraints
- Artisan Capacity Bottleneck:Hand-finished Blake and Goodyear welt construction depends on aging European craft networks with minimal apprentice pipelines.
- Raw Hide Price Volatility:Brazilian and Argentinian cattle supply fluctuations transmit directly to full-grain leather input costs.
- Substitution by Technical Knits:Performance-oriented buyers increasingly accept engineered textile uppers as adequate replacements for leather in casual contexts.
Strategic Opportunities
- India Formal Footwear Penetration:Underdeveloped premium distribution in tier-two cities creates first-mover positioning for quality-focused entrants.
- Biomaterial Certification Gap:Early adopters of mycelium leather and algae-based foams can establish proprietary testing standards ahead of regulatory harmonization.
- Direct-to-Collector Channels:Bypassing wholesale accounts through membership-based drops deepens margin capture and demand forecasting precision.
Industry Challenges
- Last-Making Expertise Attrition:The specialized craft of hand-sculpting shoe lasts is disappearing as automated 3D scanning reduces reliance on traditional pattern makers.
- Multi-Jurisdiction Chemical Compliance:Simultaneous adherence to EU REACH, US CPSC phthalate limits, and China GB standards strains formulation consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Shoes Market |
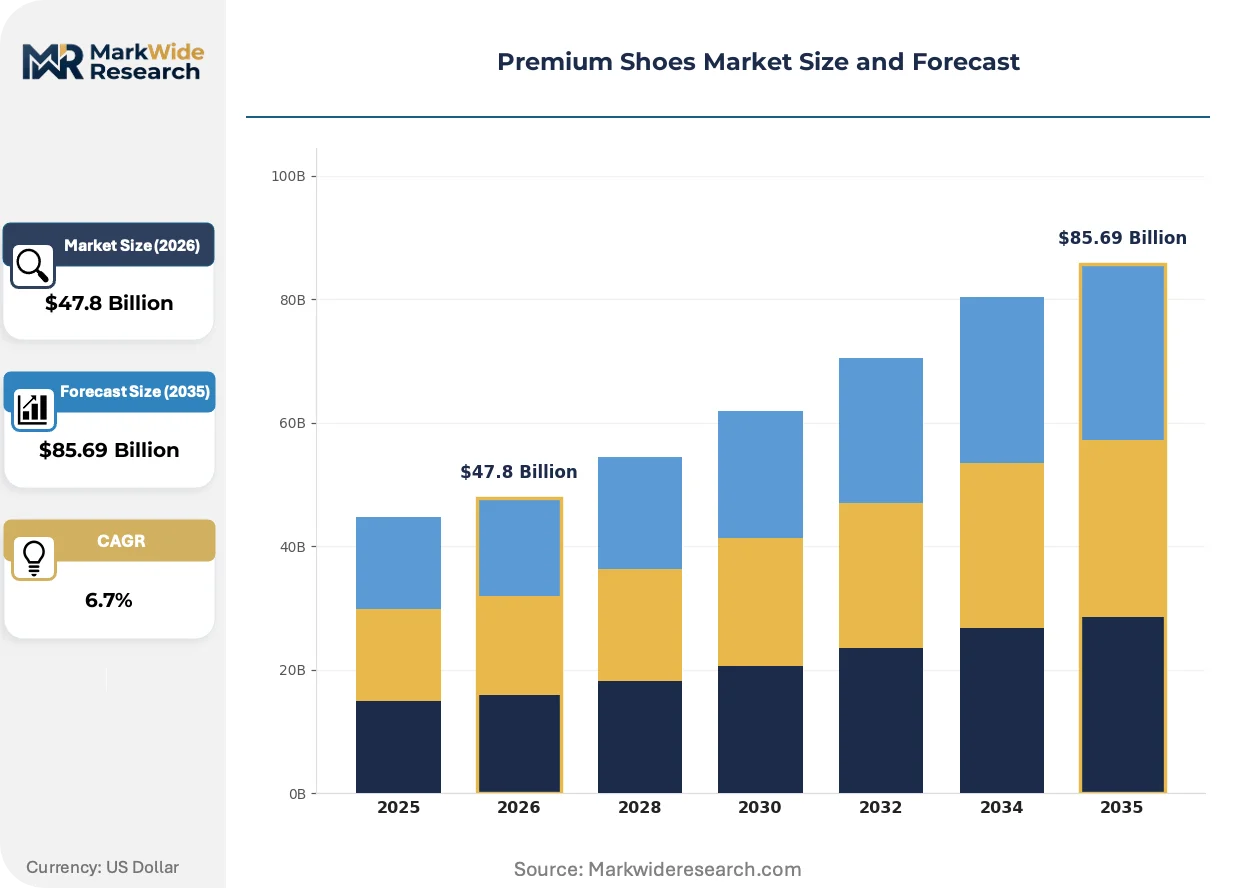
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $85.69 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Sneakers, Dress Shoes, Sports Shoes, Casual Footwear Material: Leather, Suede, Textile, Synthetic Price Tier: High-End, Mid-Range, Affordable Luxury, Designer Customer Type: Fashion Enthusiasts, Athletes, Collectors, Professionals |
| Companies Covered | Kering SA, Under Armour Inc., Nike Inc., Guccio Gucci SpA, New Balance Athletics Inc., Adidas AG, PUMA SE, ASICS Corp., LVMH Moët Hennessy Louis Vuitton SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Shoes Market Evolving Landscape
Biofabrication and automated production systems are rewriting material hierarchies and manufacturing economics simultaneously, compressing the traditional advantage held by heritage craft methods.
Digital light synthesis is displacing conventional foam midsole molding in performance categories. Elite running specialists adopt lattice-structured cushioning platforms for tuned energy return. This additive approach is displacing injection-molded EVA as the default premium cushioning architecture.
REACH authorization requirements for chromium VI compounds are eliminating chrome-tanned leather from EU-origin product lines. Tanneries in Italy and Spain face forced retooling toward vegetable tanning or alternative mineral processes. Premium dress shoe collections are responding with accelerated sourcing shifts to certified vegetable-tanned hides from Tuscany and Argentina.
Collector behavior now prioritizes verified provenance and resale liquidity over traditional retail accessibility. Authentication services and blockchain-linked ownership records are replacing physical receipt documentation as trust mechanisms. This pattern concentrates transaction volume on platforms with embedded verification infrastructure, particularly visible in North American and Japanese metropolitan markets.
Premium Shoes Market Segmentation
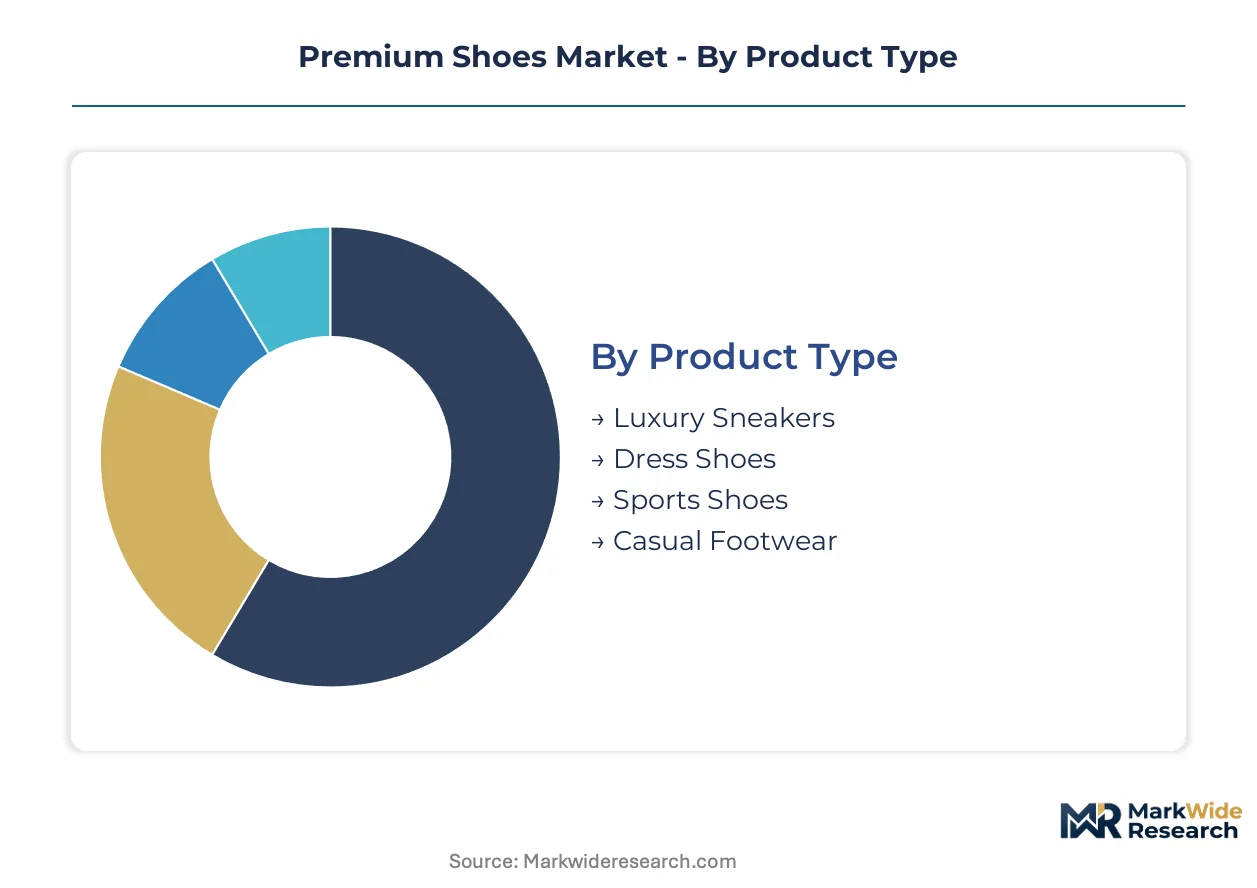
Premium footwear segmentation reveals divergent compliance burdens and margin architectures across material and construction categories. Distinct customer psychographics—collectors seeking resale liquidity versus professionals prioritizing durability—demand fundamentally different product specifications and channel strategies.
Product Type:
EU REACH chromium restrictions and resale platform authentication requirements create divergent regulatory exposure across construction categories.
- Luxury Sneakers:Engineered knit uppers bonded to foam midsoles with blockchain-linked provenance verification. Demand concentrates in Tokyo, Los Angeles, and New York metropolitan markets where StockX and GOAT infrastructure validates limited releases as alternative assets; secondary market liquidity sustains 40-60% premiums above retail.
- Dress Shoes:Full-grain leather uppers with Blake or Goodyear welted soles requiring hand-finished construction. Italian and Spanish atelier networks face forced retooling away from chrome-tanned inputs under ECHA authorization timelines; vegetable-tanned alternatives from Tuscany and Argentina command sourcing premiums.
- Sports Shoes:Performance-oriented constructions integrating carbon fiber plates and tuned foam densities for elite running and court sports.
- Casual Footwear:Hybrid constructions blending sneaker comfort systems with heritage leather finishing techniques for everyday wear contexts.
Established volume favors Dress Shoes; emerging adoption favors Luxury Sneakers.
Material:
Cost tier differentiation separates captive-processed inputs from certified third-party alternatives as compliance thresholds tighten.
- Leather:Full-grain hides processed through vegetable, chrome, or synthetic tanning sequences. EU-origin production shifts decisively toward vegetable and metal-free processes under REACH authorization pressure; Brazilian and Argentinian supply fluctuations transmit directly to input cost volatility.
- Textile:Engineered knit uppers produced via 3D robotic knitting systems enabling mass customization at reduced labor hours per unit. Adidas AG and Nike Inc. deployment of automated knitting is capturing athlete and collector segments simultaneously.
- Suede:Split-hide constructions with napped surfaces requiring specialized finishing equipment and dust-controlled production environments.
- Synthetic:Polyurethane and petroleum-derived alternatives subject to US CPSC phthalate monitoring and EU Green Deal embodied carbon tracking requirements.
Margin concentration remains with Leather; steepest expansion trajectory belongs to Textile.
Price Tier:
Customer type alignment determines channel architecture and authentication infrastructure investment levels.
- High-End:Hand-finished constructions with limited production runs and atelier-level quality control. Collectors and fashion enthusiasts drive demand through direct-to-consumer drops bypassing wholesale accounts.
- Designer:Fashion house licensing arrangements with seasonal runway alignment and celebrity placement strategies. LVMH Moët Hennessy Louis Vuitton SE integration of leather goods atelier techniques into limited footwear editions anchors positioning.
- Mid-Range:Automated production with heritage aesthetic references and certified material sourcing for professional daily wear.
- Affordable Luxury:Diffusion lines and collaborative capsules extending brand reach into entry-premium price bands.
Authentication infrastructure investment favors High-End; volume scaling favors Mid-Range.
Customer Type:
Application context shapes performance specifications and replacement cycle expectations.
- Collectors:Provenance-verified limited editions acquired for holding periods and secondary market realization. Blockchain-linked ownership records and platform-embedded authentication replace physical documentation as trust mechanisms.
- Athletes:Biomechanically tuned constructions with lattice-structured cushioning platforms displacing injection-molded EVA as default premium architecture.
- Fashion Enthusiasts:Streetwear crossover styles with rapid seasonal turnover and collaborative release calendars.
- Professionals:Durability-focused specifications with extended wear comfort metrics and formal environment appropriateness.
Platform liquidity development favors Collectors; replacement frequency favors Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian consumers favor hand-finished Blake construction for formal occasions, while Japanese collectors drive authenticated limited-edition sneaker premiums through platform-based resale infrastructure.
United States
Los Angeles and New York metropolitan areas concentrate authenticated luxury sneaker resale through StockX and GOAT infrastructure. The US Consumer Product Safety Commission monitors phthalate content in synthetic youth-oriented lines, elevating compliance costs for petroleum-derived portfolios. Portland, Oregon anchors Nike Inc.'s automated knitting R&D deployment for performance footwear mass customization.
Italy
Tuscany's vegetable-tanned hide suppliers command sourcing premiums as EU REACH authorization timelines eliminate chrome-tanned alternatives. ECHA restrictions on chromium VI compounds force retooling across Spanish and Italian atelier networks. Florence and Milan maintain concentration of hand-finished Goodyear welt construction despite aging craft pipelines with minimal apprentice replacement.
China
GB standards for footwear durability intersect with dual carbon goals to elevate synthetic portfolio compliance burdens. Shanghai and Beijing metropolitan markets concentrate fashion enthusiast demand for streetwear crossover releases. The Ministry of Ecology and Environment tracks embodied carbon across manufacturing supply chains, favoring verified low-carbon material sourcing.
Japan
Tokyo's collector segment validates blockchain-linked provenance verification as a trust mechanism replacing physical documentation. METI standards for product safety align with platform authentication infrastructure development. Osaka and Nagoya metropolitan clusters concentrate secondary market liquidity for limited-edition releases as alternative assets.
India
Tier-two cities present underdeveloped premium distribution creating first-mover positioning for quality-focused entrants. BIS certification requirements for footwear quality create regulatory entry thresholds for imported collections. Maharashtra and Karnataka sub-regions concentrate emerging professional demand for durability-focused formal footwear with extended wear specifications.
Premium Shoes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated control over automated production systems and bio-based material pipelines. The middle tier fragments across regional atelier networks and certified leather processors with limited scale. Three archetypes dominate: heritage luxury houses with leather goods integration, performance specialists with robotic knitting deployment, and platform-native brands with direct-to-collector channel architecture. Competitive moves concentrate on captive biofabrication partnerships and authentication infrastructure licensing.
Within the heritage luxury tier, LVMH Moët Hennessy Louis Vuitton SE and Kering SA occupy positions defined by atelier technique extension into limited footwear editions. Among performance specialists, Nike Inc. and Adidas AG exemplify divergent automation strategies—advanced robotic knitting versus proprietary foam chemistry. ASICS Corp. anchors the biomechanical tuning archetype with lattice-structured cushioning platforms displacing conventional midsole molding. These three groupings represent distinct margin architectures: resale liquidity premiums, manufacturing efficiency capture, and athlete-specific performance validation.
| Leading Market Players |
|---|
| Kering SA |
| Under Armour Inc. |
| Nike Inc. |
| Guccio Gucci SpA |
| New Balance Athletics Inc. |
| Adidas AG |
| PUMA SE |
| ASICS Corp. |
| LVMH Moët Hennessy Louis Vuitton SE |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for full-grain leather inputs concentrate pricing power with Tuscan and Argentinian tanneries, while automated knit production compresses lead times to fourteen days and erodes traditional margin capture in performance tiers. Contract structures stratify across long-term offtake agreements for vegetable-tanned hides, spot-market exposure for Brazilian raw hides, and project-based drops for limited-edition releases.
Pricing Analysis
Long-term offtake contracts dominate premium leather procurement, locking in volume commitments with certified Tuscan suppliers before ECHA authorization timelines eliminate chrome-tanned alternatives. Price differentiation rests on certification grade—EU REACH-compliant vegetable tanning commands substantial premiums over conventional inputs—and brand heritage anchored in atelier technique. Pricing pressure intensifies in mid-range tiers as technical knits substitute for leather in casual contexts, compressing margins for synthetic-heavy portfolios. Collectors demonstrate lowest price sensitivity, accepting 40-60% premiums above retail for blockchain-verified limited editions, while professional buyers in India and tier-two Chinese cities resist escalation beyond entry-premium thresholds.
Supply Chain Analysis
Strategic stockpiling of full-grain hides buffers against Argentinian cattle supply volatility, while just-in-time knit production enables rapid response to collector demand spikes in Tokyo and Los Angeles metropolitan markets. Geographic concentration centers on Italy and Spain for hand-finished construction, China for automated knitting systems and foam midsole molding, and Brazil for raw hide extraction. Supply chain risk hinges on single-source vulnerability in European atelier networks where last-making expertise attrition outpaces apprentice replacement. Distribution runs through authenticated resale platforms for collector segments, direct-to-consumer drops for fashion enthusiasts, and heritage wholesale accounts for professional formal wear.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment: EU REACH compliance timelines and ECHA authorization requirements create insurmountable retooling costs for challengers lacking certified supply relationships.
For Market Incumbents: Consolidate captive supply of vegetable-tanned hides through backward integration into Tuscan tannery partnerships before authorization deadlines eliminate chrome-tanned alternatives. Expand automated knitting capacity in Portugal or Vietnam to offset European labor cost escalation. Threat substitution by mycelium leather and algae-based foam entrants demands accelerated biofabrication R&D investment to maintain material hierarchy control. For New Entrants and Emerging Players: EU REACH certification fast-tracks for metal-free tanning processes open positioning in dress shoe segments abandoned by retooling-challenged incumbents. White-space targets include India's tier-two formal footwear distribution and direct-to-collector channels bypassing wholesale margin capture. Go-to-market execution should anchor in blockchain-linked provenance infrastructure to validate resale liquidity from launch. For Investors and Strategic Acquirers: Carve-out targets emerge from luxury conglomerates divesting non-core footwear labels lacking atelier integration or biofabrication pipelines. Long-term viability favors specialists with captive material science capabilities and platform-authenticated distribution. Watch for inflection when secondary market liquidity premiums compress below 25%, signaling collector saturation and primary demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Biofabrication Partnership | Mycelium leather alliances with Bolt Threads or Modern Meadow establish proprietary material pipelines ahead of regulatory harmonization. |
| Authentication Infrastructure Licensing | Blockchain provenance platforms like those embedded in StockX and GOAT deepen margin capture through verification fee structures. |
| Direct-to-Collector Channel Buildout | Membership-based drops bypass wholesale accounts and improve demand forecasting precision for limited releases. |
| Backward Integration into Tannery Supply | Captive vegetable-tanning capacity insulates against ECHA authorization disruptions and raw hide price volatility. |
| Automated Knitting Scale-Up | Robotic upper production in lower-cost geographies compresses labor hours per unit while enabling mass customization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, SEC footwear segment filings, and EU ECHA authorization databases. Primary interviews engaged supply chain directors at European atelier networks, procurement leads at automated knitting specialists, platform authentication engineers at resale infrastructure providers, and brand managers at heritage luxury houses. Secondary validation drew from trade data on Brazilian and Argentinian hide exports, REACH compliance disclosure filings, and retail audit data from metropolitan collector markets. Bottom-up unit economics triangulate against top-down category spend estimates.
Segmentation dimensions modeled include construction type, material category, price tier, and customer psychographic across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating substitution effects between leather and technical knit alternatives. Industry-specific forecast inputs encompass ECHA authorization timeline assumptions for chromium VI compounds and platform liquidity velocity indices for collector segment transaction volume.
Decision-makers should treat outputs as directional under sustained secondary market premium assumptions and stable Brazilian cattle supply; material deviation would warrant model refresh. Revision becomes warranted when EU Green Deal embodied carbon tracking thresholds tighten beyond current vegetable-tanning compliance baselines or when mycelium leather achieves cost parity with full-grain alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Men Formal Shoe Market
Footwear
Sneaker Boots Market
Footwear
North America Footwear Market
Footwear
Flip Flops Market
Footwear
Women's Luxury Footwear Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Second Hand Designer Shoes Market
Footwear
Sustainable Footwear Market
Footwear
Football Shoes Market
Footwear
Driving Footwear Market
Footwear
Running Shoes Market
Footwear
Trail Running Shoes Market
Footwear
Footwear Testing Services Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
GCC Footwear Market