
 High Heels Footwear Market | 2026-2036
High Heels Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
High Heels Footwear Market Outlook
The gap between artisan-crafted luxury heels and mass-produced fast-fashion alternatives is broadening into a structural divide. Guccio Gucci Spa leverages its Florentine leather workshops to sustain pricing power at the apex tier. Christian Louboutin anchors its position through signature red-sole recognition and controlled wholesale distribution. Prada Spa differentiates via nylon innovation and vertically integrated tanneries that competitors struggle to replicate.
High heels footwear denotes elevated-heel constructions engineered with arch support systems, heel heights typically spanning 2 to 6 inches, and load-bearing structures of steel shanks or molded polymer cores designed to redistribute body weight for formal and professional wear. Leather dominates material segmentation due to breathability and patina development, though synthetic alternatives gain share as vegan formulations improve tensile performance. Pumps occupy the mature core of product type segmentation with stable replenishment cycles, while stilettos capture margin concentration through occasion-driven purchasing and bridal applications. Price tier segmentation reveals luxury brackets extracting disproportionate profitability through scarcity mechanics and atelier servicing, whereas mid-range tiers face compression from private-label competition.
REACH governs chemical restrictions across European supply chains, limiting chromium VI in tanning processes and compelling reformulation of adhesives and dyes. The EU Green Deal extends accountability to scope-three emissions, pressuring brands to audit subcontracted heel fabrication and finishing facilities in Southern Europe. In the United States, California's Proposition 65 mandates warning labels on products containing listed chemicals, affecting heel cap and insole compositions imported through West Coast ports. Stakeholders must monitor evolving biodegradability mandates and traceability requirements that will determine supplier qualification and market access eligibility.
Market Dynamics
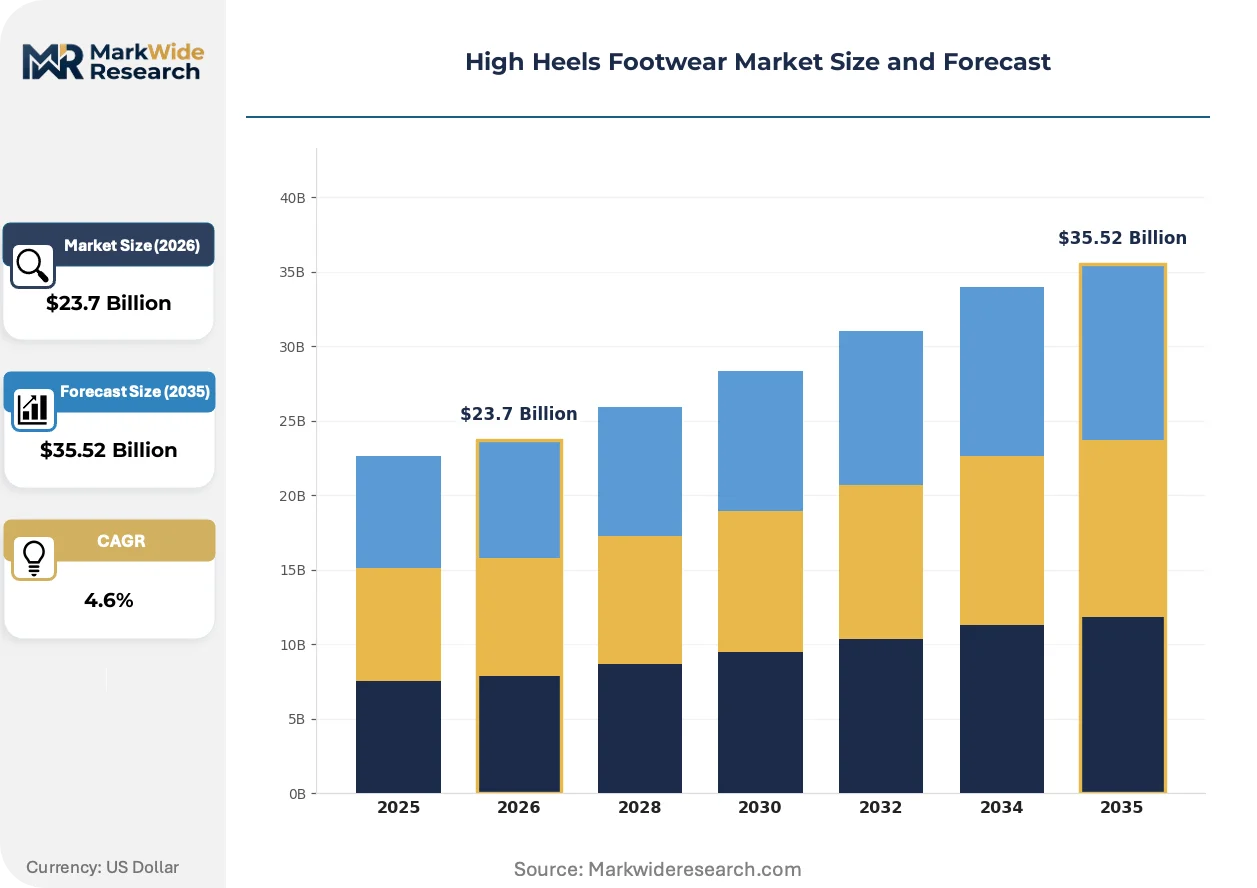
The High Heels Footwear Market is experiencing a structural bifurcation as REACH chemical restrictions and EU Green Deal carbon accounting force tanneries and heel fabricators to reconfigure supply chains, while professional women's workplace dress codes sustain demand for elevated construction footwear despite ergonomic scrutiny.
Growth Catalysts
- REACH compliance mandates:European chemical restrictions on chromium VI tanning processes are accelerating reformulation investments that yield premium-positioned eco-leather lines with traceable supply chains.
- Corporate professional wear:Financial services and legal sectors in London, New York, and Shanghai maintain formal dress codes that institutionalize pump and stiletto replenishment cycles.
- Molded polymer core engineering:Advanced load-bearing structures with steel shank alternatives are reducing unit weight while maintaining arch support specifications for extended wear applications.
Market Restraints
- Raw material concentration:Italian and Spanish tanneries control premium vegetable-tanned leather supply, creating bottleneck vulnerability for artisan-grade heel production.
- Ergonomic health litigation:Workplace injury claims related to prolonged high-heel wear are elevating employer liability exposure and softening bulk corporate procurement.
- Sneaker substitution:Athleisure acceptance in professional environments is compressing occasion-based heel purchasing frequency among younger workforce entrants.
Strategic Opportunities
- India domestic market expansion:Rising female workforce participation in Mumbai and Bangalore corporate centers is creating first-time demand for professional heel categories previously underdistributed.
- EU Green Deal scope-three incentives:Carbon audit subsidies for subcontracted heel fabrication facilities are enabling margin recovery through certified low-emission production claims.
- Direct-to-consumer 3D scanning:Custom fit algorithms paired with made-to-order manufacturing are collapsing inventory risk while capturing premium pricing for personalized arch support configurations.
Industry Challenges
- Specialized pattern engineering talent:Shortage of technicians capable of integrating biomechanical pressure mapping with aesthetic last design is constraining innovation velocity at mid-tier manufacturers.
- Multi-jurisdiction certification lag:Simultaneous compliance with California Proposition 65 warning requirements and REACH substance restrictions is extending product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Heels Footwear Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Stilettos, Wedges, Ankle Straps Material: Leather, Suede, Synthetic, Satin Customer Type: Women, Teens, Professionals, Brides Price Tier: Luxury, Mid-Range, Affordable, Discounted |
| Companies Covered | Guccio Gucci Spa, Prada Spa, Christian Louboutin, Stuart Weitzman, Salvatore Ferragamo, Jimmy Choo, Hermes International SA, Christian Dior SE, Manolo Blahnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Heels Footwear Market Strategic Shifts
Material science breakthroughs and regulatory transparency mandates are converging to reshape how high heels are engineered, sourced, and sold across professional and occasion-wear segments.
Biomechanical insole systems with pressure-distributing gel matrices and carbon-fiber shank reinforcement are rewriting comfort-performance tradeoffs in elevated footwear. Corporate legal and consulting professionals in London and Singapore are adopting these constructions for twelve-hour wear cycles. The technology is compressing the traditional premium-comfort segmentation by enabling mid-tier brands to claim ergonomic specifications previously exclusive to orthopedic specialists.
REACH authorization requirements for chromium VI and phthalate-based plasticizers are forcing tanneries in Veneto and Alicante to retool finishing lines. Compliance costs are concentrating production among vertically integrated houses with captive chemical laboratories. Bridal and luxury occasion segments face the steepest reformulation timelines due to strict color-fastness requirements that bio-based alternatives struggle to match.
Corporate procurement departments are unbundling footwear from bundled uniform allowances and instituting individual ergonomic stipends. This shift is redirecting volume from centralized bulk orders toward employee-directed selection through specialized e-commerce portals. The pattern is most pronounced in German automotive and pharmaceutical headquarters, where works councils have negotiated explicit heel-height guidelines and subsidy frameworks.
High Heels Footwear Market Segmentation
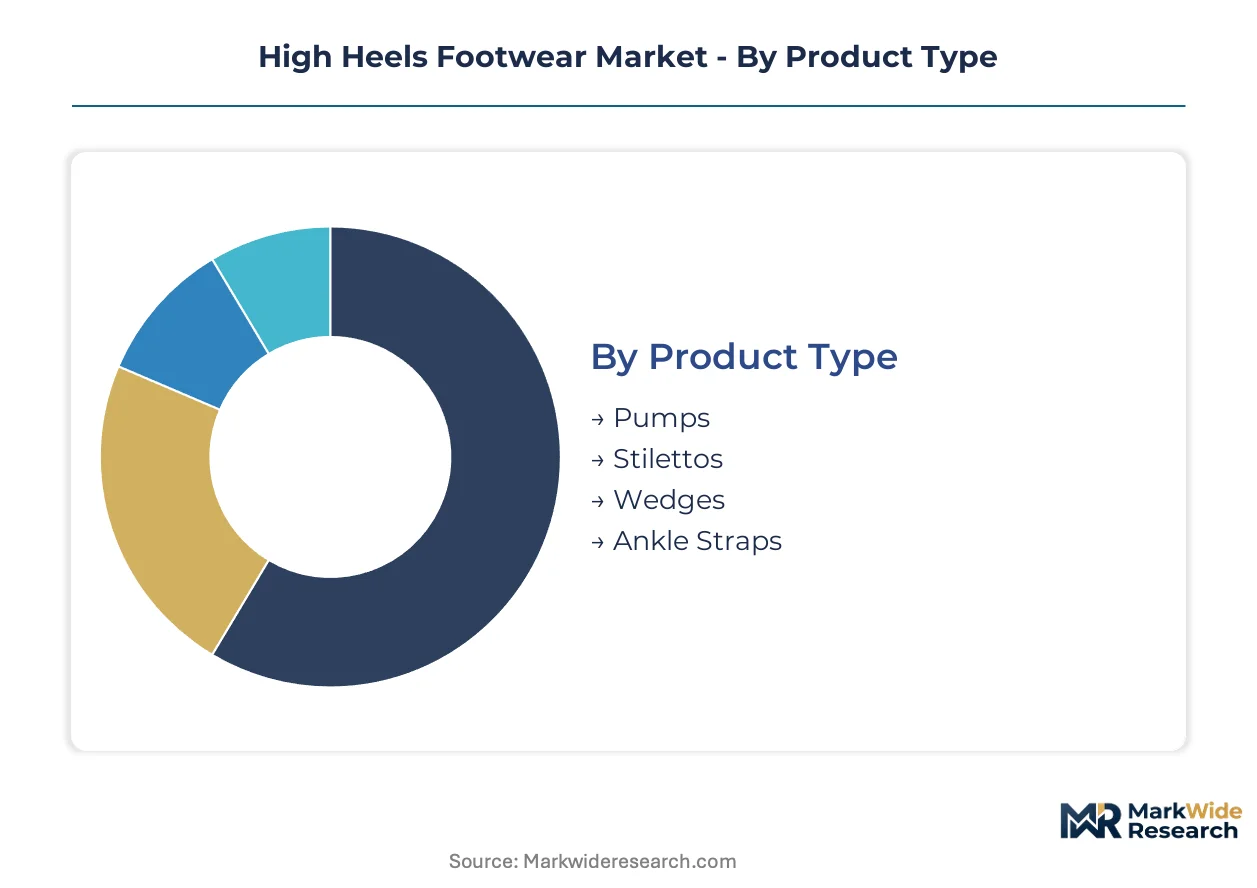
Segmentation in high heels footwear reveals how construction choices, material provenance, and buyer occasion interact to determine margin capture. Understanding these divides exposes where pricing power concentrates and where supply chain investments yield differentiation.
Product Type:
Workplace dress codes and social occasion requirements drive selection between stability-focused constructions and statement silhouettes.
- Pumps:Closed-toe designs with moderate heel heights and reinforced vamps dominate corporate replenishment cycles. Financial services professionals in London and New York maintain steady demand for calf leather constructions that pair with tailored suiting.
- Stilettos:Needle-thin heels exceeding three inches concentrate margin in bridal and evening segments where occasion-driven purchasing overrides wear-frequency calculations. Italian ateliers capture disproportionate value through hand-finished sole attachments.
- Wedges:Continuous heel-to-sole platforms distribute weight across broader surface areas for outdoor and daytime events. Mediterranean resort markets sustain seasonal production runs.
- Ankle Straps:Secured closure systems with buckle or tie fastenings address fit variability across narrow heel widths. Dance and performance applications drive specialized flexibility requirements.
Pumps lead on scale; stilettos lead on momentum.
Material:
Tannery location and finishing chemistry determine both regulatory compliance posture and patina development characteristics that buyers associate with quality.
- Leather:Full-grain vegetable-tanned hides from Italian and Spanish tanneries command premium positioning through breathability and aging characteristics. REACH chromium VI restrictions are accelerating reformulation investments among Veneto-based suppliers.
- Suede:Napped surface treatments from split hides or reverse-side full grain create textural differentiation for autumn-winter collections. Specialized brushing equipment requirements limit supplier pools.
- Synthetic:Polyurethane and microfiber formulations are displacing animal-derived materials in vegan-positioned lines as tensile strength and surface finishing improve.
- Satin:Silk or polyester woven uppers with high thread counts serve bridal and formal occasion segments where surface luster outweighs durability considerations.
Leather dominates current volume; synthetic alternatives are expanding most quickly.
Customer Type:
Life-stage and professional status shape heel height tolerance, arch support requirements, and replenishment frequency.
- Women:Core demographic spanning ages 25-55 with established brand loyalties and fit preferences that resist private-label substitution. Corporate professionals in Shanghai and Mumbai drive pump category stability.
- Teens:Entry-level purchasers prioritizing occasion flexibility over construction longevity, with social media discovery patterns accelerating trend cycles.
- Professionals:Workplace-bound buyers with explicit ergonomic requirements and employer subsidy access through restructured uniform allowances.
- Brides:Single-occasion purchasers accepting premium pricing for customization and photographic durability, with six-to-nine-month planning horizons.
Women anchor absolute volume; professionals show the steepest expansion trajectory as workforce participation rises.
Price Tier:
Manufacturing location, material grade, and distribution channel density stratify accessible entry points from scarcity-engineered luxury positioning.
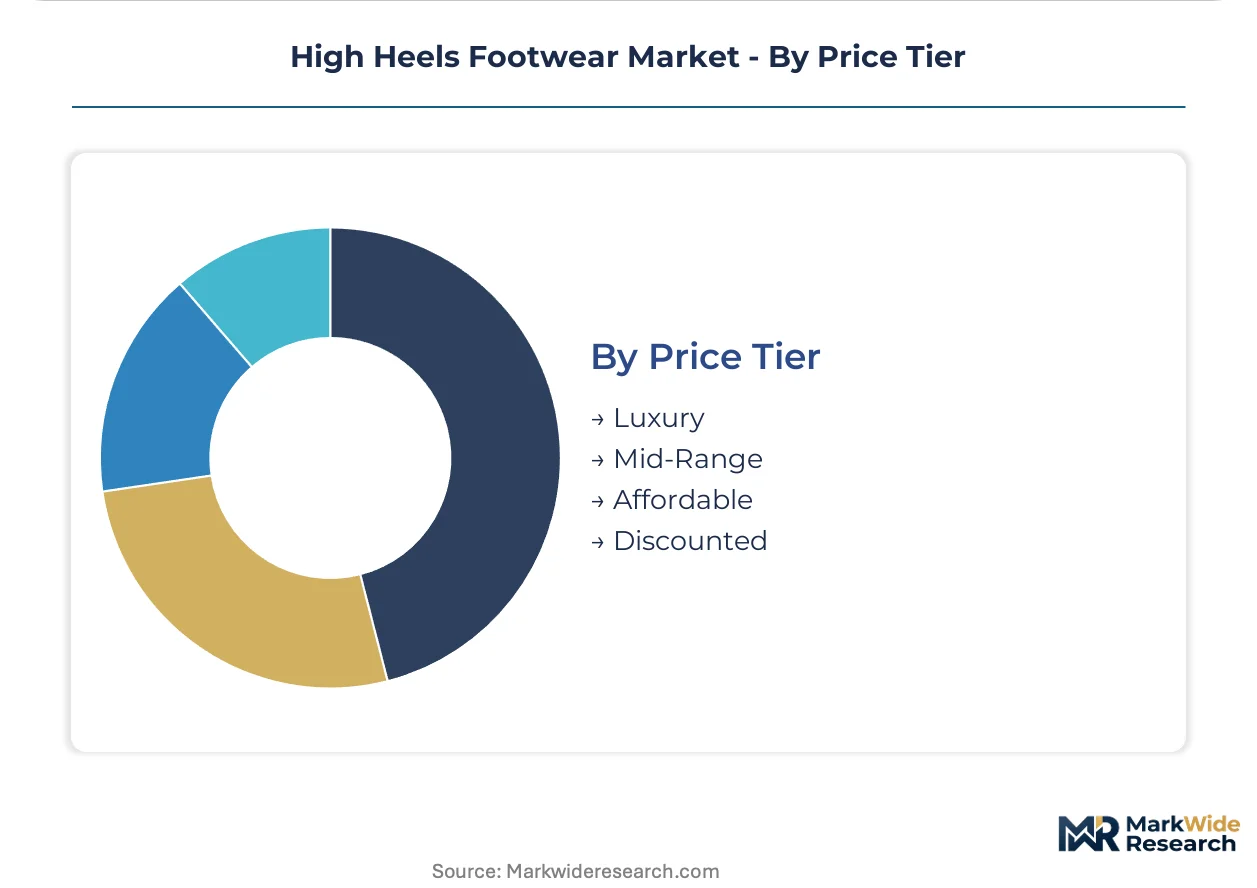
- Luxury:Hand-finished constructions from captive tanneries with controlled wholesale distribution and atelier servicing protocols. Florentine workshops sustain pricing power through artisan narrative and limited production runs.
- Mid-Range:Mechanized assembly with partial hand-finishing faces compression from private-label competition and direct-to-consumer challengers.
- Affordable:Volume manufacturing in Portuguese and Romanian facilities serves fast-fashion replenishment cycles with compressed margin structures.
- Discounted:Off-price channel overflow and previous-season liquidation through outlet malls and digital flash platforms.
Luxury commands margin concentration; affordable tiers absorb volume pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional women in corporate finance and legal services clusters across London, New York, and Shanghai generate concentrated demand for elevated footwear engineered for extended wear cycles. These talent pools sustain premium pricing for artisan-grade constructions despite ergonomic scrutiny from workplace safety regulators.
United States
Financial services professionals in Manhattan and Chicago maintain formal dress codes that institutionalize pump replenishment cycles. California's Proposition 65 mandates warning labels on products containing listed chemicals, affecting heel cap and insole compositions imported through West Coast ports. Los Angeles-based design studios are pioneering biomechanical insole systems with pressure-distributing gel matrices for twelve-hour wear applications.
China
Domestic luxury consumption and local designer growth reshape regional purchasing patterns in Shanghai and Beijing corporate centers. The country's national quality regulator enforces GB standards for footwear safety and material composition that importers must satisfy for market access. Guangzhou's manufacturing clusters are retooling finishing lines to meet dual carbon goals while serving both export and rapidly expanding domestic professional segments.
United Kingdom
Legal and consulting sectors in London sustain demand for hand-finished constructions from Florentine workshops. REACH chemical restrictions on chromium VI tanning processes accelerate reformulation investments among suppliers serving UK-based luxury retailers. Birmingham's heritage leatherworking district is experiencing capacity constraints as brands seek traceable supply chains for eco-leather lines.
Italy
Captive tanneries in Veneto and Tuscany supply full-grain vegetable-tanned hides that command premium positioning through breathability and aging characteristics. EU Green Deal scope-three emissions accountability pressures brands to audit subcontracted heel fabrication facilities in Southern Europe. Milan's design houses leverage vertically integrated production to sustain pricing power at the apex tier through limited artisan runs.
India
Rising female workforce participation in Mumbai and Bangalore corporate centers creates first-time demand for professional heel categories previously underdistributed. The Bureau of Indian Standards enforces quality benchmarks for footwear materials and construction safety that both domestic and imported products must satisfy. Delhi-NCR's emerging retail corridors are attracting mid-range international brands seeking expansion into professional segments.
High Heels Footwear Market Competitive Environment
Top-tier vendors anchor the luxury tier through controlled wholesale distribution and atelier servicing protocols, while mid-range manufacturers face compression from private-label competition and direct-to-consumer challengers. The market structure stratifies across three archetypes: vertically integrated heritage houses with captive tanneries, design-led specialists emphasizing signature recognition, and scale-driven operators serving fast-fashion replenishment cycles. Dominant competitive moves include strategic partnerships with biomechanical engineering firms and geographic expansion into underpenetrated professional workforce clusters.
Within the heritage house archetype, Guccio Gucci Spa and Prada Spa exemplify vertically integrated positioning through Florentine leather workshops and controlled supply chains. Christian Louboutin occupies a distinctive position anchored by signature red-sole recognition and disciplined distribution management. These three entities represent the apex tier where artisan narrative and scarcity mechanics sustain disproportionate profitability.
| Leading Market Players |
|---|
| Guccio Gucci Spa |
| Prada Spa |
| Christian Louboutin |
| Stuart Weitzman |
| Salvatore Ferragamo |
| Jimmy Choo |
| Hermes International SA |
| Christian Dior SE |
| Manolo Blahnik |
| Others |
Value Chain & Pricing Dynamics
Corporate procurement departments in London, New York, and Shanghai sustain premium pricing for artisan-grade constructions while compressing mid-tier margins through unbundled uniform allowances and employee-directed selection portals.
Pricing Analysis
Bundled corporate procurement contracts versus unbundled employee stipends split the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates Florentine atelier servicing from Portuguese mechanized assembly and Romanian fast-fashion volume. Price differentiation centers on certification grade and after-sales servicing protocols. Cost compression in affordable tiers is intensifying because private-label competition and direct-to-consumer challengers erode brand premiums. Fast-fashion purchasers show highest price sensitivity; bridal segments demonstrate lowest.
Supply Chain Analysis
REACH authorization and EU Green Deal carbon auditing gate supplier qualification, concentrating production among vertically integrated houses with captive chemical laboratories. Italian and Spanish tanneries supply premium vegetable-tanned leather, while Portuguese and Romanian facilities handle volume manufacturing. Raw material dependencies center on full-grain hides, chromium-free tanning agents, and molded polymer heel cores. Single-source vulnerability in Veneto-based finishing lines poses structural risk. Distribution runs through controlled wholesale networks for luxury tiers and specialized e-commerce portals for professional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Heels Footwear Market functions as a stable compounder, with professional women's workplace dress codes in financial and legal services generating predictable replenishment cycles across economic conditions.
For Market Incumbents: Hedge against sneaker substitution and athleisure encroachment by deepening biomechanical R&D partnerships and securing captive tannery capacity in Southern Europe. Channel control through disciplined wholesale distribution protects margin structure from direct-to-consumer challengers. For New Entrants and Emerging Players: Capture white-space in India's Mumbai and Bangalore corporate centers where rising female workforce participation creates first-time demand for professional heel categories. Direct-to-consumer 3D scanning and made-to-order manufacturing offer the most penetrable entry angle against inventory-heavy incumbents. For Investors and Strategic Acquirers: Luxury conglomerates with existing leather goods portfolios are the most active acquirer in this space, seeking tuck-in targets with captive tannery access and signature design recognition. Five-to-ten-year viability hinges on regulatory compliance infrastructure and traceable supply chains. Watch for REACH reformulation cost spikes as inflection indicator for margin compression at mid-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Biomechanical Insole Integration | Pressure-distributing gel matrices from Los Angeles studios enable twelve-hour wear claims for corporate professionals. |
| Captive Tannery Acquisition | Backward integration into Veneto vegetable-tanning secures REACH-compliant supply and patina-quality differentiation. |
| Direct-to-Consumer 3D Launch | Custom fit algorithms collapse inventory risk while capturing premium pricing for personalized arch support configurations. |
| EU Green Deal Certification | Scope-three carbon auditing qualifies subcontracted heel fabricators for margin-recovery subsidy claims in Southern Europe. |
| India Market Entry | Delhi-NCR retail corridor expansion targets first-time professional demand from Mumbai and Bangalore workforce clusters. |
Study Parameters
Direct dialogue with brand managers, category buyers at luxury retailers, tannery technical directors, and corporate procurement officers grounded the qualitative foundation. Secondary validation drew from customs records, SEC 10-K filings, REACH substance restriction databases, and EU Green Deal implementation guidance. Bottom-up demand modeling across product type, material, customer segment, and price tier combined with top-down macroeconomic triangulation.
Segment-level volume and value trajectories emerged from cross-referencing replenishment cycle data, workforce participation trends, and regulatory compliance cost curves. Modeled dimensions spanned construction type, material provenance, buyer life-stage, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to base-year sizing, with explicit treatment of bridal occasion purchasing and corporate uniform policy evolution as industry-specific inputs.
Regulatory enforcement variance, raw material cost spikes, and workplace dress code relaxation are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in employer liability exposure or ergonomic litigation trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
White Sneakers Market
Footwear
Sustainable Footwear Market
Footwear
North America Athletic Footwear Market
Footwear
Europe Barefoot Shoes Market
Footwear
Sports Shoes Market
Footwear
Sneaker Identification Service Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Global Recovery Footwear Market
Footwear
Snow Boots Market
Footwear
Loafers Market
Footwear
Riding Boots Market
Footwear
Hiking Footwear Market
Footwear
Second Hand Designer Shoes Market
Footwear
United States Footwear Market
Footwear
Leather Footwear Market