
 United States Footwear Market | 2026-2036
United States Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
United States Footwear Market Intelligence
California's SB 657 supply chain transparency mandate is consolidating ethical sourcing expectations across domestic footwear procurement. Nike leverages its vertically controlled manufacturing network to sustain compliance visibility from raw material to finished goods. Deckers Outdoor Corporation anchors its premium positioning through specialized shearling and wool-blend construction techniques that differentiate UGG and HOKA product lines.
Footwear encompasses finished goods engineered with defined upper, midsole, and outsole assemblies, where ethylene-vinyl acetate (EVA) foam densities typically range from 45 to 65 Shore C for athletic cushioning applications, serving consumer mobility, occupational safety, and fashion expression needs. Athletic Footwear dominates volume throughput due to performance innovation cycles and sneaker culture monetization, while Online Retailers capture margin expansion through direct-to-consumer inventory precision and reduced wholesale dependency. Leather commands premium pricing in work and fashion boots, though Synthetic materials gain share in waterproof trail and vegan-positioned casual lines.
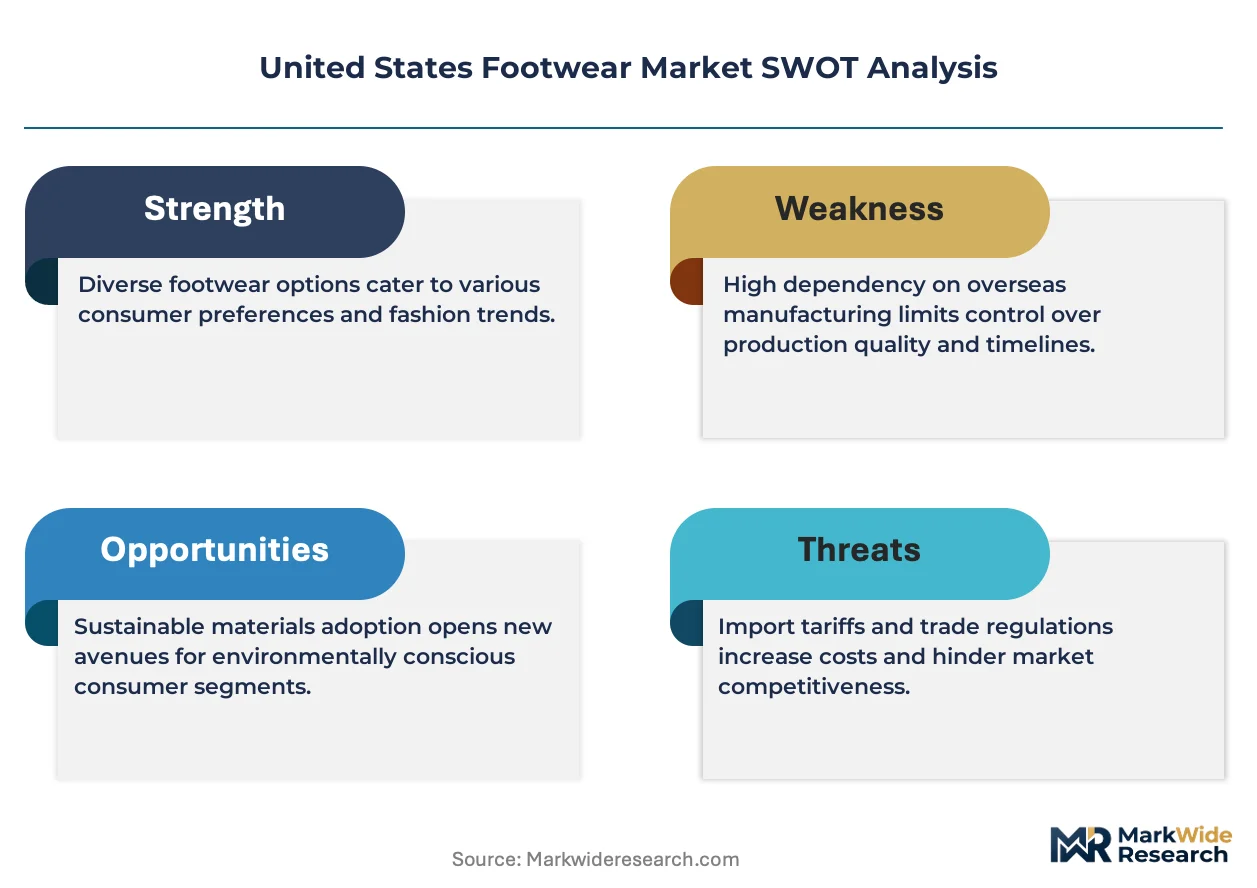
Federal oversight from the Consumer Product Safety Commission governs chemical exposure limits in children's footwear, while OSHA's 29 CFR 1910.136 mandates protective toe caps for occupational applications, and California's Proposition 65 enforcement continues tightening phthalate disclosure requirements for PVC components. ASTM International publishes F2412 and F2413 standards that define impact and compression resistance for safety footwear sold into industrial end uses. Stakeholders must monitor evolving state-level extended producer responsibility proposals and biomaterial certification pathways that will determine next-generation competitive positioning.
Market Dynamics
California's SB 657 supply chain transparency mandate is consolidating ethical sourcing expectations across domestic footwear procurement. Nike leverages its vertically controlled manufacturing network to sustain compliance visibility from raw material to finished goods.
Growth Catalysts
- Youth sports league expansion:Athletic footwear adoption is accelerating among organized youth athletics programs and school-sponsored fitness initiatives across Texas, Florida, and metropolitan New York corridors.
- OSHA 29 CFR 1910.136 enforcement:Occupational safety mandates for protective toe caps are driving replacement cycles in manufacturing, logistics, and construction end-uses.
- EVA foam density optimization:Advanced ethylene-vinyl acetate formulations ranging 45-65 Shore C are enabling performance differentiation in athletic cushioning applications.
Market Restraints
- Petrochemical input volatility:Synthetic rubber and polyurethane precursor costs fluctuate with crude oil derivatives, compressing margin predictability for mid-tier producers.
- California Proposition 65 litigation exposure:Phthalate disclosure requirements for PVC components create compliance cost burdens and label redesign cycles.
- Leather tanning capacity concentration:Domestic hide processing infrastructure has consolidated around fewer facilities, constraining premium work boot supply elasticity.
Strategic Opportunities
- Texas metropolitan corridor density:Houston-Dallas-Austin population growth supports premium and performance segment expansion through retail infrastructure investment.
- Biomaterial certification pathways:Emerging ASTM standards for bio-based midsole compounds offer first-mover positioning for plant-derived cushioning technologies.
- Direct-to-consumer channel precision:Online retailers capture margin expansion through inventory optimization and reduced wholesale dependency in athletic and casual segments.
Industry Challenges
- ASTM F2413 certification timeline compression:Safety footwear testing protocols for impact and compression resistance require extended laboratory validation, delaying product launches.
- Shearling and wool-blend sourcing expertise:Specialized material construction techniques for premium positioning face talent scarcity in domestic technical design functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Footwear Market |
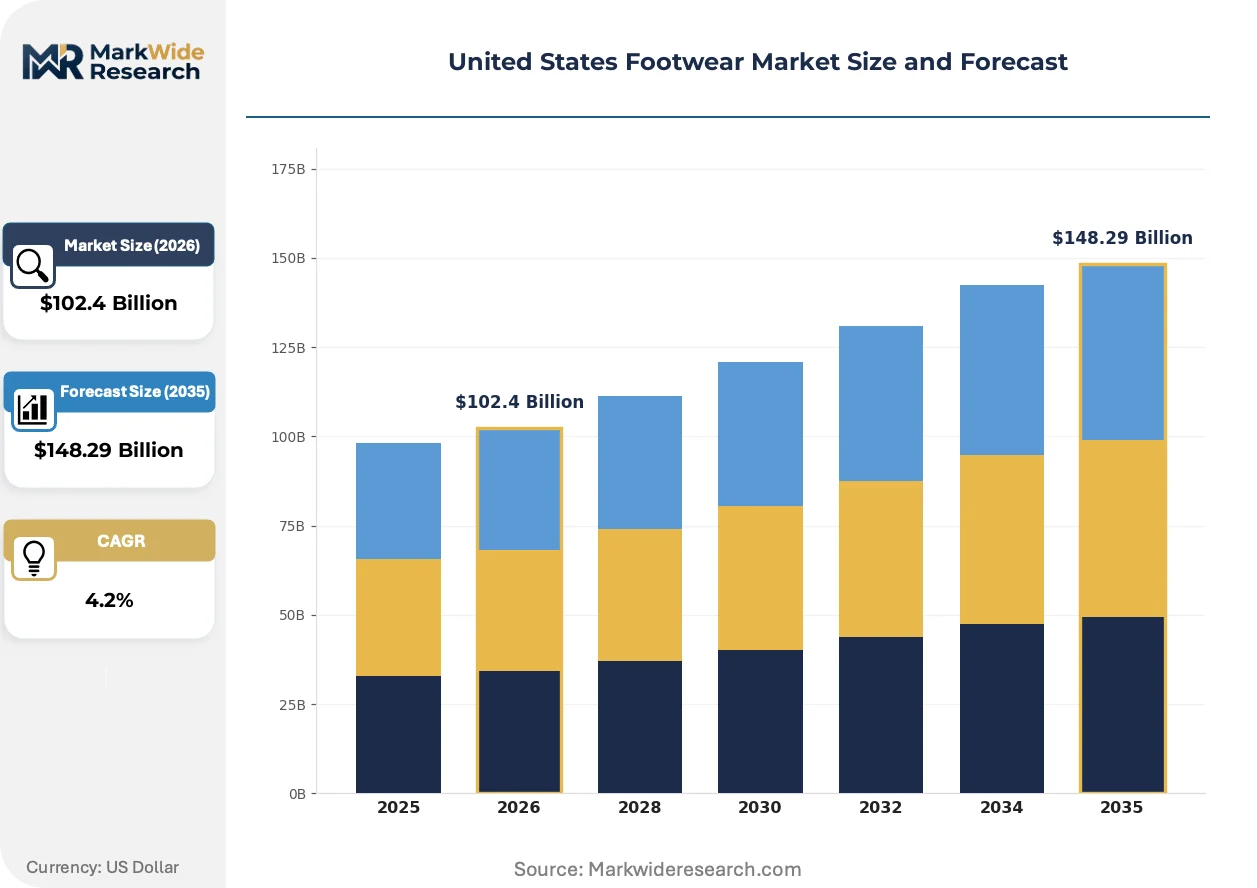
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $148.29 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual Shoes, Athletic Footwear, Sandals, Boots Material: Leather, Synthetic, Canvas, Rubber Gender: Men's, Women's, Children's, Unisex Distribution Channel: Specialty Stores, Online Retailers, Department Stores, Supermarkets |
| Companies Covered | Crocs, Foot Locker, Nike, Caleres, Wolverine World Wide, Deckers Outdoor Corporation, Steven Madden, Weyco Group, Skechers U.S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Footwear Market Strategic Shifts & Innovations
Material science convergence with regulatory compliance requirements is redefining competitive differentiation in domestic footwear manufacturing. Three active developments are restructuring product development cycles and procurement patterns.
Plant-derived midsole compounds derived from algae and agricultural waste streams are absorbing petroleum-based EVA displacement in performance athletic lines. Marathon runners and trail athletes in Colorado and Pacific Northwest markets are adopting these alternatives at accelerating rates. This absorption is compressing R&D timelines for fossil-fuel-dependent formulations while opening premium pricing tiers.
OSHA's 29 CFR 1910.136 protective toe cap mandates are expanding beyond traditional steel to composite and alloy alternatives. Industrial purchasers in manufacturing and warehousing verticals are specifying lighter-weight safety components. The construction segment across the Sun Belt is driving fastest adoption of carbon-fiber-reinforced toe protection.
Consumer preference for supply chain visibility is redirecting purchase decisions toward brands with documented ethical sourcing. Athletic and casual buyers in California and New York metropolitan areas are prioritizing SB 657 compliance disclosures over traditional brand loyalty. This rotation is forcing wholesale account restructuring and direct-to-consumer infrastructure investment.
United States Footwear Market Segmentation
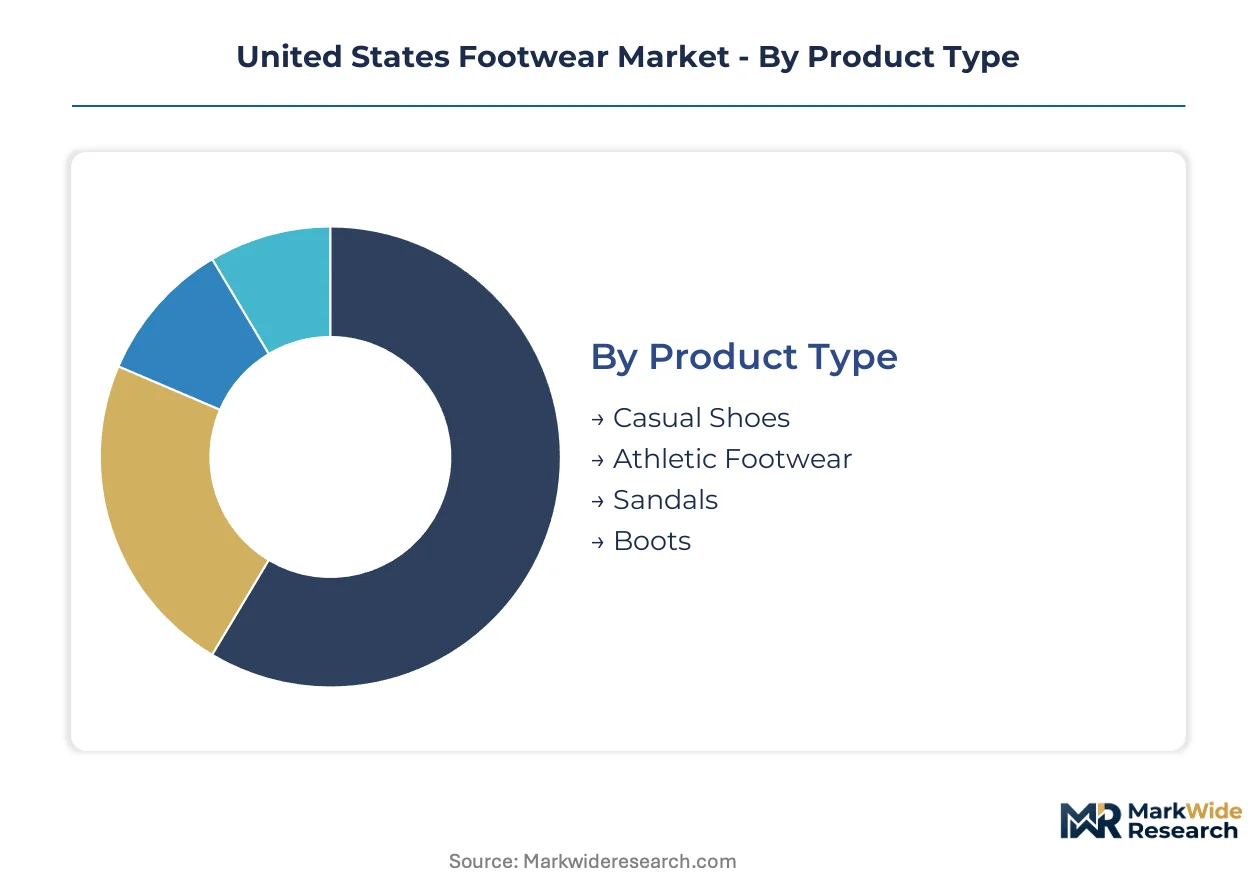
Segmentation in the United States footwear market reveals how capital deployment, regulatory exposure, and channel economics concentrate profit pools. Manufacturers align product architecture with specific material specifications and distribution infrastructure to defend margin positions.
Product Type:
Athletic and boot categories demand the heaviest upfront investment in specialized tooling, testing certification, and performance R&D.
- Athletic Footwear:Engineered with defined upper, midsole, and outsole assemblies where EVA foam densities range 45-65 Shore C for cushioning. Demand concentrates among youth sports leagues and fitness enthusiasts across Texas, Florida, and metropolitan New York corridors, driven by performance innovation cycles and sneaker culture monetization.
- Boots:Leather-upper construction with steel or composite protective toe caps meeting OSHA 29 CFR 1910.136 mandates. Work boot procurement clusters in manufacturing and logistics verticals across the Sun Belt, where occupational safety enforcement drives replacement cycles.
- Casual Shoes:Versatile styling bridging fashion and function, serving everyday mobility needs across suburban and urban demographics.
- Sandals:Open-heel construction prioritizing breathability and warm-weather utility, with seasonal demand spikes in Florida and southwestern states.
Athletic Footwear absorbs the bulk of installed capacity; Boots are expanding most quickly.
Material:
Material selection directly determines compliance burden and pricing tier, with leather and synthetic carrying distinct regulatory profiles.
- Synthetic:Petroleum-derived polymers enabling waterproof trail performance and vegan-positioned casual lines. Adoption accelerates in Pacific Northwest outdoor markets where plant-derived midsole compounds from algae and agricultural waste displace fossil-fuel formulations.
- Leather:Premium hide processing for work and fashion boots, constrained by domestic tanning capacity consolidation that limits supply elasticity for premium construction.
- Canvas:Woven cotton uppers offering lightweight breathability for casual and seasonal applications.
- Rubber:Natural and synthetic compounds dominating outsole construction for durability and traction across all product categories.
Synthetic materials command the steepest expansion trajectory as bio-based certification pathways open premium pricing tiers; Leather retains pricing power in safety-critical and heritage-positioned segments.
Gender:
Product development cycles and sizing granularity create distinct capital efficiency profiles across gender segments.
- Men's:Occupational safety and athletic performance drive specification intensity, with work boot and running shoe sub-segments requiring dedicated lasts and testing protocols.
- Women's:Fashion-forward styling and athleisure crossover create shorter design-to-shelf timelines, concentrating demand in metropolitan retail corridors.
- Children's:CPSC chemical exposure limits govern phthalate and heavy metal thresholds, adding compliance layers to material sourcing decisions.
- Unisex:Simplified sizing matrices reducing SKU complexity for casual and outdoor categories, capturing efficiency in direct-to-consumer channels.
Men's footwear anchors volume throughput; Women's segments are climbing the fastest on athleisure crossover demand.
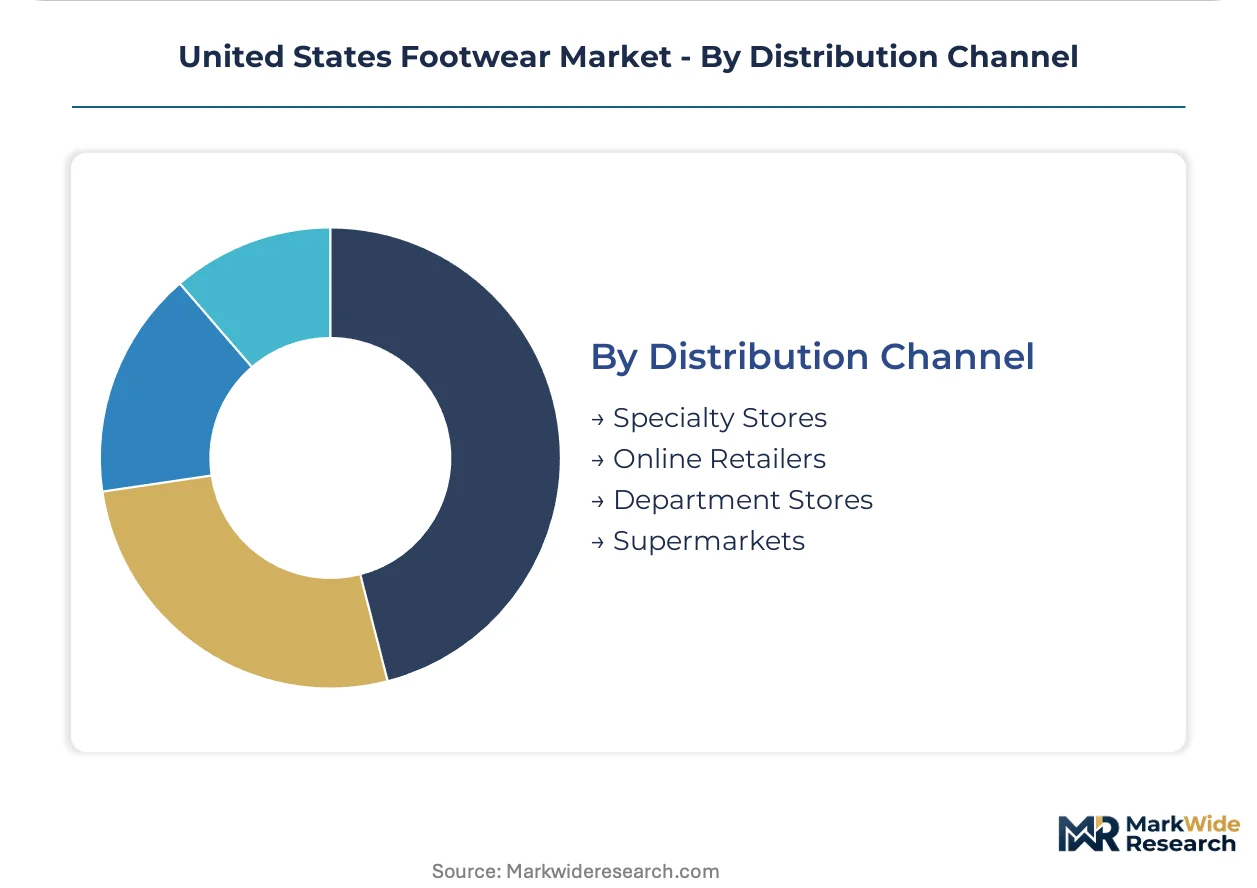
Distribution Channel:
Channel selection determines working capital intensity and margin capture, with digital infrastructure requiring distinct capability investment versus physical retail.
- Online Retailers:Direct-to-consumer inventory precision and reduced wholesale dependency enable margin expansion in athletic and casual segments. California and New York metropolitan buyers prioritize SB 657 compliance disclosures, forcing brands to invest in supply chain visibility infrastructure.
- Specialty Stores:Curated assortment and technical staff expertise supporting performance athletic and outdoor categories, with fitting services defending premium price points.
- Department Stores:Broad reach and promotional calendar dependency creating volume concentration for fashion and casual lines.
- Supermarkets:Convenience positioning and impulse purchase dynamics serving basic footwear needs with compressed margin structures.
Online Retailers absorb the bulk of growth investment; Specialty Stores retain pricing power in technical performance categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston-Dallas-Austin corridor anchors the nation's fastest-growing footwear demand concentration, with metropolitan population expansion driving premium athletic and work boot procurement across Texas retail infrastructure.
Texas
Youth sports league proliferation and energy sector occupational safety mandates propel athletic and work boot volumes. OSHA 29 CFR 1910.136 enforcement intensifies across manufacturing and logistics verticals. Houston-Dallas-Austin corridor concentrates premium segment expansion through population-driven retail infrastructure investment.
California
SB 657 supply chain transparency requirements redirect procurement toward documented ethical sourcing. Proposition 65 litigation exposure tightens phthalate disclosure thresholds for PVC components. Los Angeles-San Francisco corridor dominates direct-to-consumer channel development and biomaterial certification pathway investment.
New York Metropolitan Area
Sneaker culture monetization and fashion-forward styling accelerate athleisure crossover demand. CPSC chemical exposure limits govern children's footwear material thresholds. New York City and surrounding counties concentrate specialty retail infrastructure and premium brand flagship positioning.
Florida
Warm-weather utility and seasonal tourism drive sandal and casual shoe throughput. Youth athletics program expansion supports organized sports footwear procurement. Miami-Orlando-Tampa corridor absorbs bulk of southeastern demand concentration with compressed wholesale dependency.
Pacific Northwest
Trail running and outdoor performance adoption accelerate plant-derived midsole compound absorption. ASTM F2413 safety standards govern industrial footwear certification requirements. Seattle-Portland corridor leads algae and agricultural waste stream material integration in waterproof trail categories.
United States Footwear Market Key Industry Players
The competitive structure tilts toward diversified portfolio holding companies with multi-brand architectures spanning athletic, casual, and work boot categories. Market concentration reflects vertical manufacturing control advantages and direct-to-consumer channel infrastructure scale. Three archetypes dominate: integrated sportswear conglomerates with captive supply networks, specialty outdoor and comfort-focused brand houses, and retail-centric distribution platforms with private label development capabilities. Consolidation activity concentrates on supply chain visibility technology and biomechanical R&D assets.
Within the integrated sportswear tier, Nike anchors vertically controlled manufacturing network advantages. Among specialty brand houses, Deckers Outdoor Corporation occupies premium positioning through technical material expertise. At the retail-distribution vector, Foot Locker exemplifies channel infrastructure scale with direct-to-consumer precision capabilities. These entities represent distinct competitive positioning vectors rather than overlapping market contestation.
| Leading Market Players |
|---|
| Crocs |
| Foot Locker |
| Nike |
| Caleres |
| Wolverine World Wide |
| Deckers Outdoor Corporation |
| Steven Madden |
| Weyco Group |
| Skechers U.S.A. |
| Others |
Cost & Logistics Intelligence
Performance-grade certification ladders separate ASTM F2413-compliant safety footwear from uncertified imports, compressing margin structures at the commodity tier while amplifying pricing power for domestic producers with laboratory validation capabilities. This bifurcation concentrates procurement budgets toward verified supply chains, forcing mid-tier brands to absorb compliance costs or exit industrial segments entirely.
Pricing Analysis
Value-based pricing anchored to occupational safety outcomes dominates industrial procurement, with ASTM F2413 certification tier and composite toe cap technology serving as primary differentiation drivers. Price erosion runs through uncertified import channels as tariff exposure intensifies cost competition, while brand-premium segments in athletic footwear demonstrate lowest price sensitivity among sneaker culture collectors and marathon enthusiasts.
Supply Chain Analysis
Workforce availability constraints in Vietnam, Indonesia, and China's Pearl River Delta are reshaping manufacturing geography as footwear production seeks labor pool alternatives. EVA foam formulations, shearling hides, and synthetic rubber compounds constitute critical input dependencies, with single-source vulnerability in domestic leather tanning capacity creating bottleneck risk. Distribution runs through direct-to-consumer platforms and specialty retail networks serving metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's SB 657 supply chain transparency mandate constructs a compliance moat that elevates capital requirements for market participation, consolidating advantage among incumbents with documented ethical sourcing infrastructure.
For Market Incumbents: Anchor defensive positioning through captive control over shearling and wool-blend material streams, insulating UGG and HOKA-tier premium lines from raw material scarcity. Deepen laboratory certification partnerships to compress ASTM F2413 validation timelines against emerging composite toe competitors. Prioritize direct-to-consumer channel investment in Texas and Florida corridors where population density supports margin expansion.
For New Entrants and Emerging Players: Plant-derived midsole compound buyers in Pacific Northwest trail running communities represent an underserved archetype with premium pricing tolerance. Target this segment through algae-based cushioning technology and SB 657 compliance documentation as entry credentials. Build go-to-market presence through specialty outdoor retailers with technical staff expertise before scaling online.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically controlled manufacturing networks given OSHA enforcement expansion across Sun Belt construction verticals. Multi-brand holding companies with safety footwear certification capabilities offer superior long-term viability within a five-to-ten-year window. Monitor biomaterial ASTM standard finalization as inflection signal for plant-derived compound adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Reduces wholesale dependency and captures margin in Texas metropolitan corridors. |
| Biomaterial Certification Investment | Positions first-mover advantage for algae-based midsole compounds in Pacific Northwest markets. |
| ASTM F2413 Laboratory Partnership | Compresses safety footwear validation timelines against composite toe alternatives. |
| Supply Chain Visibility Infrastructure | Meets California SB 657 disclosure requirements for ethical sourcing documentation. |
| Shearling Sourcing Integration | Secures premium material streams for UGG-tier positioning against tanning capacity consolidation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across brand managers, category buyers at specialty retailers, supply planners, and channel sales heads. OSHA enforcement documentation, CPSC chemical exposure guidelines, California Proposition 65 litigation records, and ASTM International standards publications provided regulatory validation. Bottom-up product segmentation and top-down market sizing underwent cross-verification.
Reconciliation of shipment volumes, retail audit data, and import statistics informed analytical framework construction across the projection horizon. Segmentation dimensions spanned product type, material composition, gender category, and distribution channel, with EVA foam density specifications and certification tier modeled as industry-specific variables. CAGRs derived from trend extrapolation against demographic and regulatory catalyst trajectories.
Revisions become necessary when OSHA enforcement intensity, petrochemical input volatility, or biomaterial ASTM standard finalization timelines deviate from baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Shoe Insoles Market
Footwear
South America Athletic Footwear Market
Footwear
Athletic Footwear Market
Footwear
Custom Shoes Market
Footwear
Light Up Shoes Market
Footwear
Shoe Rental Service Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Women's Luxury Footwear Market
Footwear
Ankle Boots Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Womens Footwear Market
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Sports Shoes Market
Footwear
Slip Resistant Shoes Market
Footwear
North America Footwear Market
Footwear
UGG Boots Market