
 Europe Barefoot Shoes Market | 2026-2036
Europe Barefoot Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Barefoot Shoes Market Insights
The buyer base for barefoot footwear is broadening beyond dedicated athletes to encompass office workers, children, and rehabilitation patients across Europe. Vivobarefoot leverages its direct-to-consumer platform to control pricing and customer data across multiple EU markets. Bohempia anchors its production in the Czech Republic with hemp-based uppers that differentiate its sustainability credentials. Xero Shoes competes through a wider size range and podiatrist partnerships that sustain clinical credibility.
Barefoot shoes are footwear engineered with zero-drop soles, thin flexible outsoles, and anatomically shaped toe boxes that permit natural foot mechanics without structural support or cushioning. Most designs employ 3-5mm rubber or EVA outsoles paired with breathable knit, hemp, or full-grain leather uppers manufactured through cemented or stitch-down construction. Minimalist footwear leads volume due to its cross-occasion versatility from commuting to light training. Trail running shoes capture the fastest expansion as alpine and coastal running communities in Austria, Switzerland, and Portugal demand lugged outsoles with puncture resistance. Leather materials command premium positioning among Scandinavian consumers who prioritize durability and formal-workplace compatibility.
REACH restricts phthalates and heavy metals in synthetic fabrics and rubber compounds, compelling reformulation of outsoles and adhesives across the supply chain. The EU Green Deal's textile strategy and impending digital product passports will force disclosure of material origins and recyclability, raising compliance costs for smaller brands. ECHA's ongoing microplastics restrictions affect synthetic mesh uppers, pushing some manufacturers toward canvas and hemp alternatives. Stakeholders must monitor how France's AGEC anti-waste law and extended producer responsibility schemes reshape distribution economics for online retail and direct sales channels.
Market Dynamics
REACH chemical compliance and the EU Green Deal's textile strategy are forcing wholesale reformulation of rubber outsoles and synthetic uppers across European manufacturing, compressing margins for brands dependent on conventional petroleum-based materials.
Growth Catalysts
- Physiotherapist endorsement networks:Clinical recommendation systems in Germany and Austria drive patient-to-consumer conversion for rehabilitation and preventive foot health applications.
- REACH regulatory alignment:Reformulation of phthalate-free compounds and heavy-metal-free dyes creates first-mover advantage for compliant suppliers in EU distribution channels.
- Alpine trail running communities:Puncture-resistant lugged outsoles gain traction among organized running clubs in Switzerland and Austria seeking technical terrain performance.
Market Restraints
- Natural rubber price volatility:Thin-margin outsole production faces input cost pressure from Southeast Asian supply disruptions and climate-affected harvest cycles.
- Extended producer responsibility schemes:France's AGEC anti-waste law imposes end-of-life collection costs on direct-to-consumer brands without established reverse logistics infrastructure.
- Conventional cushioned footwear substitution:Established running brands with hybrid minimalist lines retain shelf space in multi-brand retail, limiting pure barefoot brand access.
Strategic Opportunities
- Portuguese coastal running expansion:Technical trail models with drainage features and salt-resistant compounds address underpenetrated Atlantic terrain segments.
- Digital product passport readiness:Early compliance with EU Green Deal material disclosure requirements secures preferential placement in sustainability-curated retail.
- Pediatric podiatry channel development:Anatomically shaped children's models distributed through Scandinavian physiotherapy clinics capture preventive-care positioning.
Industry Challenges
- Biomechanical assessment skill gaps:Retail staff training for proper fitting of zero-drop footwear lags behind product complexity in multi-brand stores.
- CE marking timeline compression:New Medical Device Regulation classifications for therapeutic footwear extend certification cycles for rehabilitation-focused models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Barefoot Shoes Market |
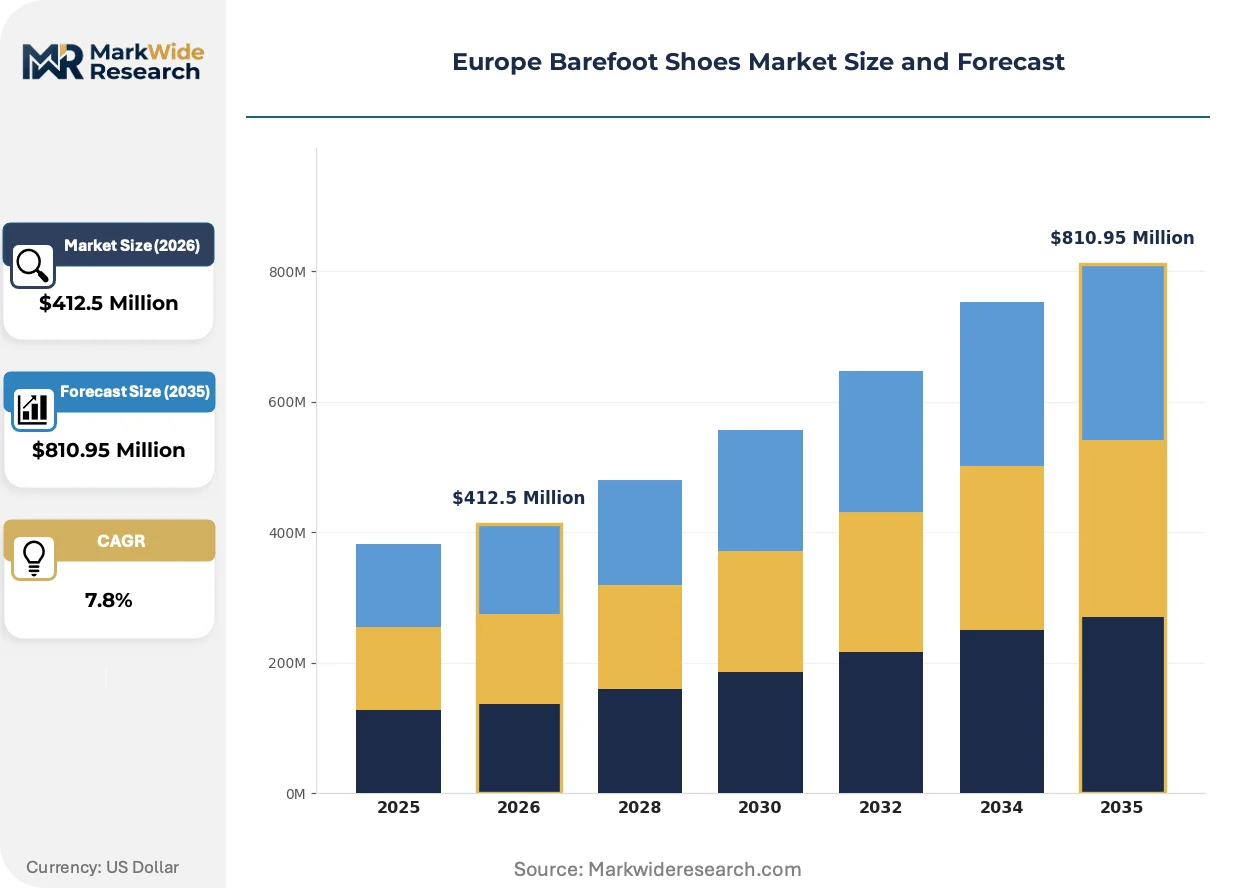
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minimalist Footwear, Trail Running Shoes, Casual Sneakers, Performance Shoes End User: Men, Women, Children, Athletes Material: Rubber, Canvas, Leather, Synthetic Fabrics Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Bohempia, Ethletic, Vivobarefoot, Baabuk, Giesswein, Xero Shoes, El Naturalista, Ahinsa, Be Lenka, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Barefoot Shoes Market Trends and Innovations
Material traceability systems and automated production methods are converging with regulatory disclosure mandates to reshape how European barefoot footwear is engineered, sourced, and sold across direct and retail channels.
3D foot-scanning technology integrated with parametric design software is automating last development and size grading for anatomically accurate toe boxes. Custom orthopedic clinics in the Netherlands and Belgium adopt these systems for made-to-measure rehabilitation footwear. The technology is automating what previously required manual pattern-making, compressing development cycles from months to weeks for small-batch production.
The EU Green Deal's impending digital product passport mandate requires granular disclosure of material origins, chemical composition, and recyclability pathways for all textile products sold in member states. Manufacturers must restructure supplier contracts to capture chain-of-custody documentation from rubber plantations through finished goods. Hemp and canvas upper suppliers gain preference over synthetic mesh producers unable to meet microplastics restriction thresholds.
Running club collective purchasing is displacing individual retail transactions as organized groups in Germany negotiate direct volume agreements with specialized brands. These arrangements bypass traditional sporting goods retail markup structures while delivering fit-consistency across member cohorts. The pattern concentrates most visibly in Bavaria and Baden-Württemberg where physiotherapist-affiliated clubs maintain membership rolls exceeding five hundred athletes.
Europe Barefoot Shoes Market Segmentation
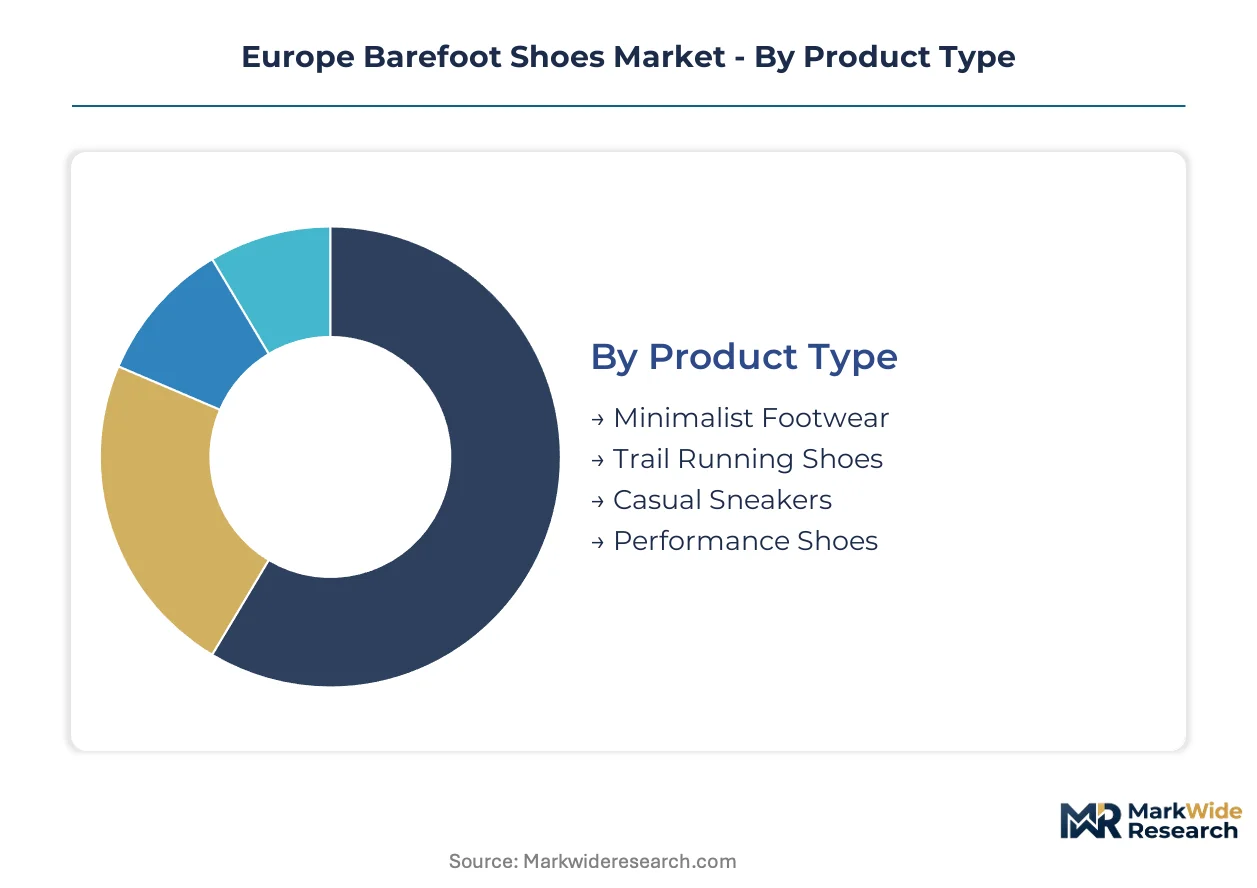
Segmentation in the European barefoot footwear market reveals how technical specifications, user biomechanics, and regulatory material constraints create distinct commercial battlegrounds. Each axis exposes different margin structures and compliance burdens under REACH and the EU Green Deal.
Product Type:
Zero-drop sole construction and outsole thickness specifications differentiate performance tiers across usage occasions.
- Minimalist Footwear:Designs employ 3-5mm rubber or EVA outsoles with anatomically shaped toe boxes, prioritizing ground feel and proprioceptive feedback. Demand concentrates among office workers in Germany and the Netherlands seeking cross-occasion versatility from commuting to light training, constrained by biomechanical assessment skill gaps in multi-brand retail.
- Trail Running Shoes:Lugged outsoles with puncture-resistant compounds address technical terrain requirements. Alpine running communities in Switzerland and Austria drive adoption, with organized clubs negotiating direct volume agreements that bypass traditional sporting goods markup structures.
- Casual Sneakers:Breathable knit or canvas uppers paired with flexible thin soles serve everyday urban mobility. Scandinavian consumers prioritize formal-workplace compatibility.
- Performance Shoes:Competition-oriented builds emphasize weight reduction and ground contact precision. Podiatrist partnerships in Austria sustain clinical credibility for rehabilitation applications.
Mature deployment sits with Minimalist Footwear. Newer deployment is concentrated in Trail Running Shoes.
End User:
Anatomical variation and biomechanical adaptation requirements shape product development priorities across demographic cohorts.
- Men:Wider forefoot dimensions and higher average body mass drive reinforcement requirements in outsole compounds. German running-club culture sustains repeat purchase rates among male athletes.
- Women:Narrower heel-to-ball ratios and distinct arch profiles necessitate dedicated last development. French and Italian markets show concentration in fashion-forward minimalist designs.
- Children:Anatomically shaped models address developmental podiatry needs. Scandinavian physiotherapy clinics capture preventive-care positioning through clinical distribution channels.
- Athletes:Technical performance specifications dominate with puncture resistance and drainage features for competitive trail environments. Portuguese coastal running communities represent an underpenetrated Atlantic segment.
Volume concentration rests with Men. Steepest expansion trajectory belongs to Children.
Material:
REACH chemical compliance and ECHA microplastics restrictions are forcing wholesale reformulation of upper and outsole compositions.
- Rubber:Natural and synthetic compounds form thin flexible outsoles. Southeast Asian supply disruptions and climate-affected harvest cycles create input cost volatility for thin-margin production.
- Canvas:Woven cotton or hemp alternatives gain preference as synthetic mesh faces microplastics restriction thresholds. Czech Republic-based production anchors sustainable supply.
- Leather:Full-grain uppers command premium positioning through cemented or stitch-down construction. Scandinavian durability priorities sustain formal-workplace market share.
- Synthetic Fabrics:Knit mesh uppers face digital product passport disclosure requirements for material origins and recyclability pathways. Reformulation of phthalate-free compounds creates first-mover advantage for compliant EU suppliers.
Supply security concentrates with Canvas. Regulatory pressure is accelerating fastest against Synthetic Fabrics.
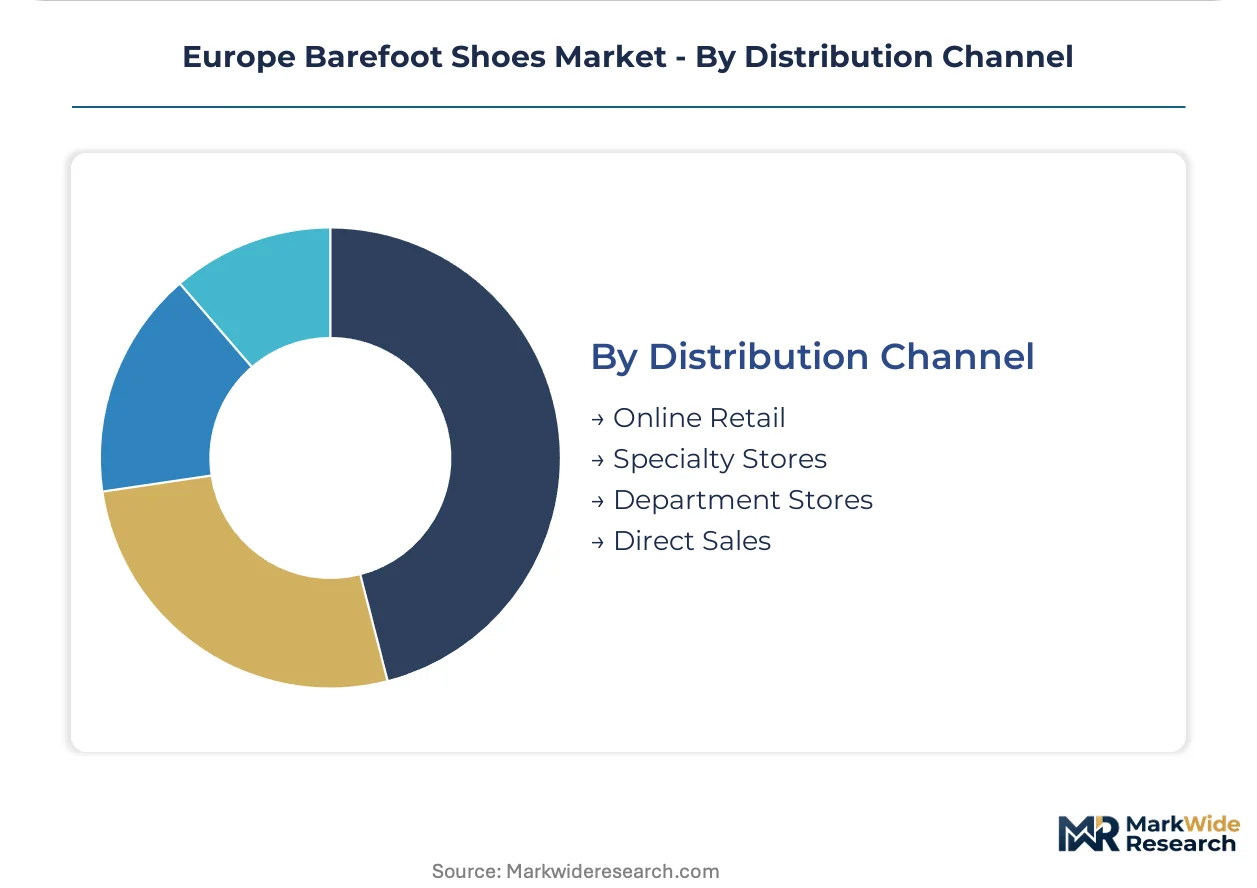
Distribution Channel:
Margin compression from extended producer responsibility schemes and collective purchasing patterns reshape route-to-market economics.
- Online Retail:Direct-to-consumer platforms control pricing and customer data across multiple EU markets. France's AGEC anti-waste law imposes end-of-life collection costs on brands without established reverse logistics infrastructure.
- Specialty Stores:Podiatrist-affiliated retail in Germany and Austria provides clinical endorsement conversion for rehabilitation applications. Staff training gaps for zero-drop fitting constrain expansion.
- Department Stores:Multi-brand retail shelf space favors established running brands with hybrid minimalist lines, limiting pure barefoot brand access.
- Direct Sales:Running club collective purchasing in Bavaria and Baden-Württemberg displaces individual transactions through volume agreements exceeding five hundred member cohorts.
Established infrastructure sits with Specialty Stores. Channel shift is advancing fastest through Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portuguese rubber plantations and Czech hemp fields supply the raw material foundation for European barefoot shoe manufacturing, with finished goods assembly concentrating in Central European industrial corridors.
Germany
Physiotherapist endorsement networks and running-club culture in Bavaria and Baden-Württemberg drive patient-to-consumer conversion for rehabilitation applications. REACH chemical compliance requirements for phthalate-free compounds reshape rubber outsole sourcing. Berlin-Brandenburg hosts direct-to-consumer platform operations that control pricing across multiple EU markets.
Switzerland
Alpine trail running communities in the Bernese Oberland and Valais demand puncture-resistant lugged outsoles for technical terrain. ECHA microplastics restrictions push manufacturers toward canvas and hemp alternatives for uppers. Zurich anchors organized running clubs negotiating direct volume agreements that bypass traditional sporting goods markup structures.
France
Fashion-forward minimalist designs gain traction in Paris and Lyon among office workers seeking cross-occasion versatility. France's AGEC anti-waste law imposes end-of-life collection costs on direct-to-consumer brands without established reverse logistics infrastructure. The Île-de-France region concentrates specialty retail distribution for podiatrist-affiliated clinical channels.
Czech Republic
Hemp-based upper production anchors sustainable supply chains for canvas alternatives facing synthetic mesh restrictions. CE marking timeline compression under new Medical Device Regulation classifications extends certification cycles for therapeutic footwear models. Prague serves as the manufacturing base for Bohempia's stitch-down construction operations.
Scandinavia
Full-grain leather uppers command premium positioning among Swedish and Norwegian consumers prioritizing durability and formal-workplace compatibility. Pediatric podiatry channel development through physiotherapy clinics captures preventive-care positioning for anatomically shaped children's models. Copenhagen and Stockholm host clinical distribution networks for developmental foot health applications.
Europe Barefoot Shoes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustainability differentiation and direct-to-consumer channel control. The vendor base clusters around three strategic archetypes: heritage European manufacturers with regional production footprints, digitally native brands leveraging direct sales platforms, and sustainability-focused specialists exploiting hemp and natural rubber supply chains. Competitive moves concentrate on M&A for material traceability capabilities and strategic partnerships with physiotherapy clinic networks.
Among UK-based operators, Vivobarefoot exemplifies the direct-to-consumer archetype through platform-based pricing control. Bohempia anchors the sustainability specialist tier with Czech Republic-based hemp production. Xero Shoes represents the clinical credibility vector through podiatrist partnership structures. These three occupy distinct positioning vectors without overlapping core competencies.
| Leading Market Players |
|---|
| Bohempia |
| Ethletic |
| Vivobarefoot |
| Baabuk |
| Giesswein |
| Xero Shoes |
| El Naturalista |
| Ahinsa |
| Be Lenka |
| Others |
Pricing and Supply Chain Analysis
Natural rubber compound costs originating in Southeast Asian plantations cascade through three distinct pricing tiers before reaching end consumers, with thin-margin outsole manufacturers absorbing volatility while premium leather-upper brands in Scandinavia pass through durability premiums.
Pricing Analysis
Warranty and return policy bundling separates premium barefoot brands from direct-to-consumer discounters, with clinical-channel partners in Germany and Austria commanding service-inclusive pricing for rehabilitation applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under REACH compliance and after-sales fitting support. Cost compression in economy-tier synthetic uppers is intensifying because ECHA microplastics restrictions force rapid material reformulation. Running club collective purchasers in Bavaria exhibit lowest price sensitivity due to volume-negotiated terms, while individual online retail buyers in France face highest sensitivity amid AGEC compliance cost passthrough.
Supply Chain Analysis
Regional distribution centers in Berlin-Brandenburg and Prague operate hub-and-spoke patterns radiating into German, Swiss, and Austrian retail networks. Manufacturing concentrates in the Czech Republic, Portugal, and Romania, with hemp canvas and natural rubber as critical raw material inputs. Single-source vulnerability in Southeast Asian rubber supply creates exposure to climate-affected harvest cycles and logistics disruption. Distribution runs through direct-to-consumer platforms and physiotherapist-affiliated specialty stores, bypassing conventional sporting goods markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into hemp cultivation and rubber processing capabilities is accelerating as brands seek insulation from input cost volatility and regulatory material disclosure mandates.
For Market Incumbents: Acquire Portuguese rubber plantation offtake agreements and Czech hemp fiber processing assets to secure REACH-compliant material pipelines. Incumbent brands must consolidate physiotherapy clinic endorsement networks in Germany and Austria against emerging direct-to-consumer entrants bypassing clinical channels. Capacity addition in Central European assembly facilities strengthens responsiveness to Alpine trail running demand spikes.
For New Entrants and Emerging Players: EU Green Deal digital product passport requirements in France and Germany open a window for compliance-native brands to capture sustainability-curated retail placement ahead of legacy reformulation cycles. Pediatric podiatry channels in Scandinavia represent the most penetrable white-space target, with preventive-care positioning through anatomically shaped children's models. Go-to-market execution should prioritize running club collective purchasing agreements in Switzerland and Austria over conventional retail shelf competition.
For Investors and Strategic Acquirers: First-mover REACH reformulation completion among synthetic fabric suppliers is the leading indicator that material traceability capabilities will command acquisition premiums. Long-term viability favors vertically integrated specialists controlling hemp supply chains and clinical distribution networks. Monitor ECHA microplastics restriction enforcement timelines as the inflection signal for canvas and leather upper demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hemp Cultivation | Czech Republic-based fiber sourcing secures ECHA-compliant canvas alternatives ahead of synthetic mesh restrictions. |
| Direct-to-Consumer Platform Launch | Berlin-Brandenburg operations enable pricing control and customer data capture across multiple EU member states. |
| Clinical Channel Partnership Development | Physiotherapist-affiliated retail in Bavaria drives patient-to-consumer conversion for rehabilitation applications. |
| Digital Product Passport Compliance | Early material disclosure readiness secures preferential placement in sustainability-curated retail networks. |
| Pediatric Podiatry Distribution Expansion | Scandinavian physiotherapy clinic networks capture preventive-care positioning for developmental foot health. |
Research Methodology
Multi-period observation of running club membership growth, REACH compliance investment patterns, and material substitution rates anchored the trend analysis, supplemented by interviews with brand supply chain directors, Czech and Portuguese raw material suppliers, German physiotherapy clinic operators, and specialty retail buyers. Secondary validation drew from ECHA regulatory filings, EU Green Deal textile strategy documentation, customs trade data for rubber and hemp imports, and barefoot footwear brand sustainability disclosures. Bottom-up segment sizing triangulated against top-down market value estimates derived from direct-to-consumer platform transaction analysis and clinical channel prescription volume indicators.
Segment-weighting approaches distributed value and volume across product type, end user demographic, material composition, and distribution channel dimensions throughout the forecast period. CAGRs were computed from modeled annual progression rates applied to base-year estimates, with growth trajectories calibrated against Alpine trail running community expansion, pediatric podiatry channel development velocity, and collective purchasing agreement penetration in organized running clubs. Industry-specific inputs included natural rubber price volatility indices and ECHA enforcement timeline scenarios for microplastics restrictions.
The model assumes a particular technology adoption path for 3D foot-scanning and parametric design automation; alternative pathways for custom orthopedic manufacturing scalability would alter the outlook for made-to-measure rehabilitation footwear penetration. Forecasts reflect documented assumptions regarding regulatory implementation schedules, raw material supply stability, and clinical endorsement network expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Waterproof Sneakers Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Equestrian Footwear Market
Footwear
PVC Footwear Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Sneakers Market
Footwear
Tactical Footwear Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Formal Shoes Market
Footwear
Chunky Sneaker Market
Footwear
Self-Lacing Shoes Market
Footwear
Kids Barefoot Shoes Market
Footwear
Sandals Market
Footwear
Driving Footwear Market
Footwear
Sneaker Boots Market