
 Water Shoes Market | 2026-2036
Water Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Water Shoes Market Analytics
Adventure tourism operators is reorganizing procurement patterns away from casual beachgoers toward guided activity providers. Nike anchors its position through R&D intensity in quick-drain mesh uppers for multi-terrain use. Merrell dominates technical water sports shoes with aggressive outsole geometries for canyon environments. Teva competes through sandal architectures that bridge river-crossing function with post-activity wearability.
Water shoes are engineered footwear combining hydrophobic materials, perforated drainage systems, and zero-drop or low-profile soles designed for submersion, traction on wet substrates, and rapid drying. Neoprene uppers provide thermal insulation for cold-water immersion, while rubber compounds with siped lug patterns deliver grip on algae-coated rocks. Aqua socks lead volume through low unit cost and packability for travel-centric casual users. Water sports shoes capture premium margins from athletes requiring reinforced toe caps and ankle stabilization for surfing and rafting. Synthetic materials face substitution pressure as mesh blends gain share for tropical-climate breathability.
REACH in Europe restricts phthalates in synthetic rubber compounds, redirecting formulation work toward bio-based alternatives. The EU Green Deal's product durability requirements extend to footwear categories, affecting replacement-cycle economics for mesh-construction models. Australia's Great Barrier Reef Marine Park Authority enforces reef-safe sole compounds that exclude zinc-based antibacterials. Stakeholders must track how regional chemical registries diverge on acceptable polymer additives, as compliance fragmentation threatens centralized manufacturing strategies.
Market Dynamics
Adventure tourism operators are consolidating procurement volumes for guided excursions, redirecting manufacturing capacity away from fragmented retail channels toward bulk contract fulfillment with specialized technical specifications.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on phthalates in synthetic rubber compounds are accelerating bio-based neoprene formulation R&D across European manufacturing facilities.
- Reef-safe sole mandates:Australia's Great Barrier Reef Marine Park Authority enforcement of zinc-free antibacterial compounds is creating certified product categories with premium positioning.
- Quick-drain mesh engineering:Hydrophobic perforated uppers are displacing solid synthetic constructions in tropical-climate product lines due to breathability advantages.
Market Restraints
- Petrochemical input volatility:Synthetic rubber and petroleum-derived mesh blends face price instability tied to crude oil fluctuations, compressing margin predictability for mid-tier manufacturers.
- Regional compliance fragmentation:Divergent chemical registries across EU REACH, Australian reef-safe mandates, and US state-level restrictions threaten centralized production economics.
- Neoprene thermal limitations:Bio-based alternatives currently underperform petroleum-derived neoprene in cold-water insulation, constraining substitution in sub-15°C immersion applications.
Strategic Opportunities
- Indonesia coastal tourism corridors:Underdeveloped domestic supply chains for technical water sports footwear present first-mover advantages for reef-safe certified manufacturing partnerships.
- Multi-terrain hybrid architectures:Convergence of trail-running midsole geometries with drainage-optimized uppers is opening crossover categories for canyon trekking and river-crossing activities.
- EU Green Deal durability requirements:Extended product lifecycle mandates are incentivizing repairable construction methods and modular sole replacement systems.
Industry Challenges
- Polymer chemistry specialization:Shortage of formulation scientists with dual expertise in bio-based materials and footwear biomechanics is delaying compliant product pipelines.
- Reef-safe certification timelines:Australian authority testing protocols for sole compound biodegradability extend commercialization cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Shoes Market |
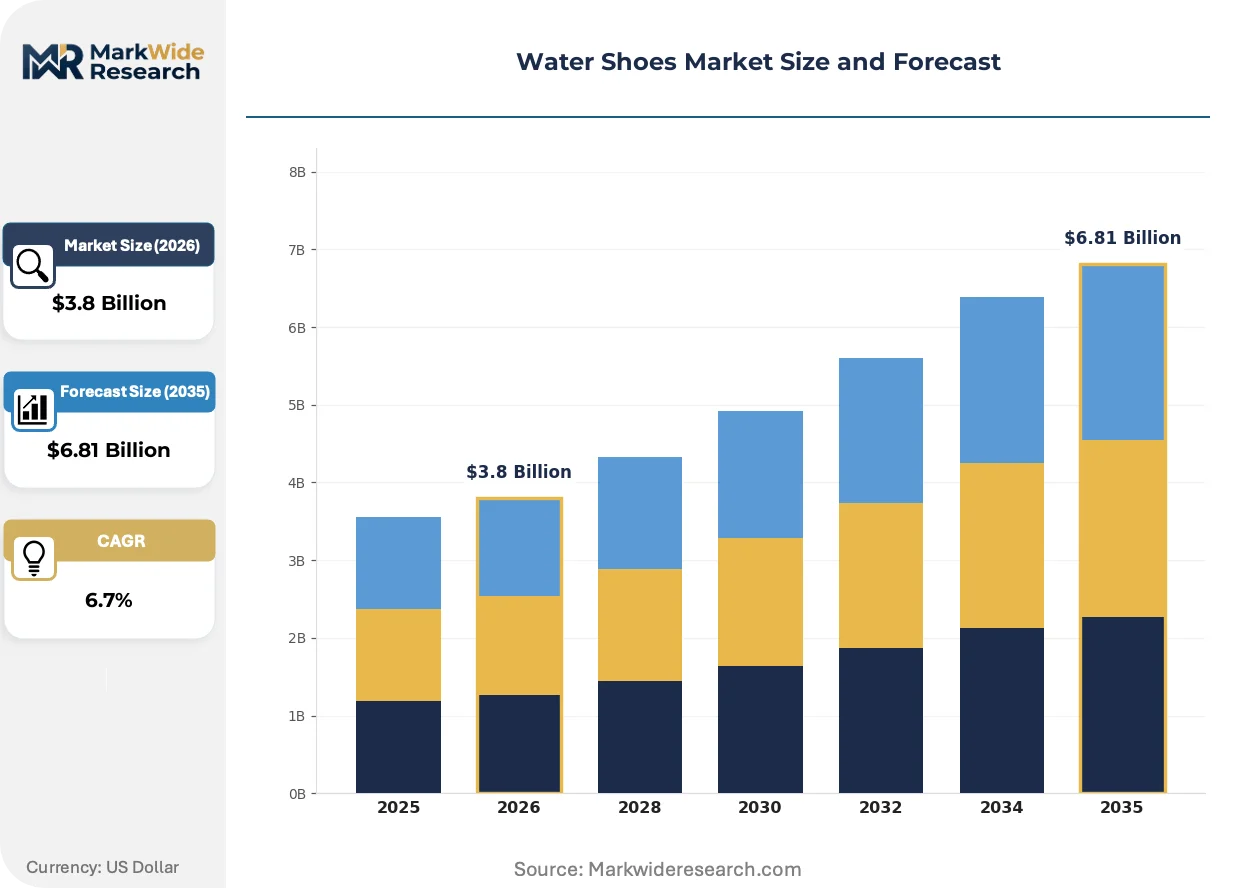
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqua Socks, Slip-On, Sandals, Water Sports Shoes Material: Neoprene, Mesh, Rubber, Synthetic End User: Adults, Children, Athletes, Casual Users Activity: Swimming, Surfing, Rafting, Beach Volleyball |
| Companies Covered | Adidas, Nike, Crocs, Merrell, Teva, Salomon, Skechers, Keen, Columbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Shoes Market Evolving Landscape
Material substitution and regulatory chemistry are compressing traditional manufacturing assumptions, while procurement consolidation among adventure operators is rewriting distribution economics for technical footwear categories.
Siped lug geometries with algae-optimized traction patterns are displacing conventional rubber outsoles in premium water sports lines. Canyon guiding operators in Utah and Colorado are specifying these compounds for client safety liability reduction. The shift is compressing demand for standard non-siped constructions in North American technical segments.
ECHA's evolving REACH annex XVII restrictions on synthetic rubber additives are forcing reformulation of mesh-bonding adhesives and sole compounds simultaneously. Manufacturers serving EU distribution channels must maintain parallel inventory streams or absorb retooling costs for unified bio-based lines. Cold-water immersion products face the steepest compliance penalties due to neoprene dependency.
Adventure tourism operators are consolidating vendor relationships into multi-year technical supply agreements with volume guarantees and specification lock-ins. This procurement concentration is marginalizing traditional retail-driven SKU proliferation. Australia's reef tourism corridor exhibits the most advanced contract structures, with operators mandating sole-source arrangements for reef-safe certified product lines.
Water Shoes Market Segmentation
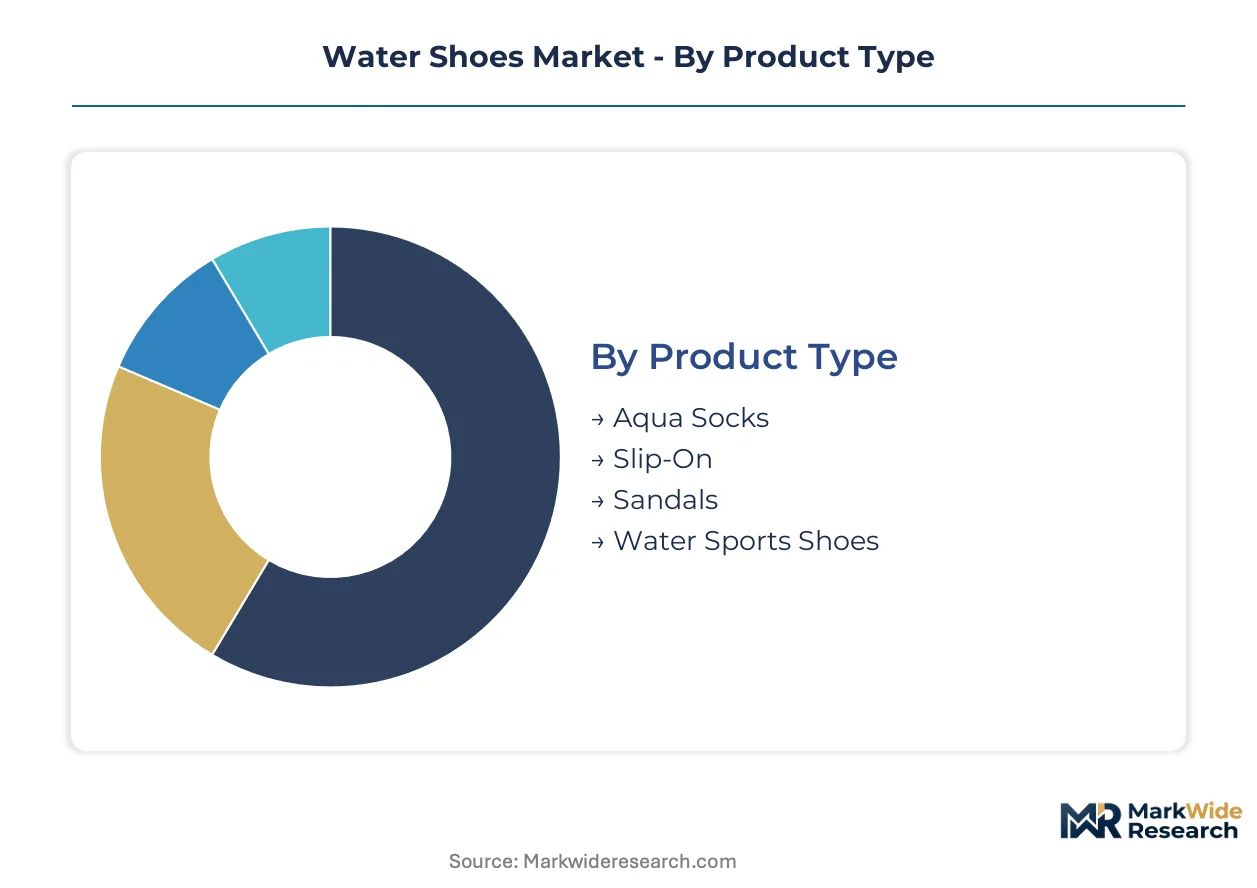
Water shoes segment across functional purpose, material chemistry, user physiology, and activity intensity. Each dimension carries distinct margin profiles and regulatory exposure, forcing manufacturers to prioritize portfolio depth over breadth.
Product Type:
Margin pools concentrate in technical performance categories where specification lock-ins from adventure operators create pricing power.
- Water Sports Shoes:Reinforced toe caps, ankle stabilization systems, and aggressive outsole geometries define this category. Australia's reef tourism corridor drives premium procurement through sole-source contracts with certified suppliers.
- Aqua Socks:Ultra-lightweight hydrophobic knit constructions prioritize packability and low unit cost for travel-centric casual users. Volume concentrates in Southeast Asian coastal tourism gateways where disposable purchase patterns dominate.
- Slip-On:Elasticized collars and collapsible heels enable rapid donning for beach-to-water transitions. European REACH compliance costs compress margins for synthetic rubber formulations in this mid-tier category.
- Sandals:Open-strap architectures with river-crossing traction bridge post-activity wearability. Canyon guiding operators in Utah specify siped lug variants for client safety liability reduction.
The dominant share belongs to Aqua Socks, while Water Sports Shoes is closing the gap fastest.
Material:
Raw material selection determines thermal performance boundaries and regulatory compliance pathways simultaneously.
- Neoprene:Closed-cell synthetic rubber delivers sub-15°C thermal insulation through trapped nitrogen gas cells. ECHA REACH annex XVII restrictions on petroleum-derived formulations accelerate bio-based R&D investment cycles.
- Mesh:Hydrophobic perforated uppers with quick-drain engineering displace solid constructions in tropical climates. Australia's Great Barrier Reef Marine Park Authority mandates exclude zinc-based antibacterials from bonded mesh compounds.
- Rubber:Natural and synthetic compounds with siped lug patterns provide algae-optimized traction on wet substrates. Cold-water variants face steepest substitution pressure from bio-based alternatives.
- Synthetic:Petroleum-derived solid constructions face demand erosion as perforated architectures gain share. Phthalate restrictions under EU Green Deal durability requirements extend replacement-cycle economics.
Mesh constructions command expanding share through breathability advantages, though Neoprene retains pricing power in cold-water immersion segments.
End User:
User physiology and activity intensity create divergent biomechanical specification requirements.
- Athletes:Competition-grade products demand reinforced toe protection, torsional rigidity, and drainage-optimized midsole geometries. Bulk procurement from adventure tourism operators concentrates volume in this high-specification tier.
- Adults:General-purpose constructions balance packability with multi-terrain functionality. European durability mandates under EU Green Deal incentivize repairable design features.
- Children:Rapid outgrowth patterns drive replacement frequency and price elasticity. Safety-focused parents prioritize closed-toe architectures over sandal variants.
- Casual Users:Travel-centric purchase patterns favor disposable price points and minimal pack volume. Southeast Asian coastal corridors exhibit highest per-capita consumption intensity.
Casual Users generate highest unit volume, yet Athletes capture steepest margin expansion through technical specification premiums.
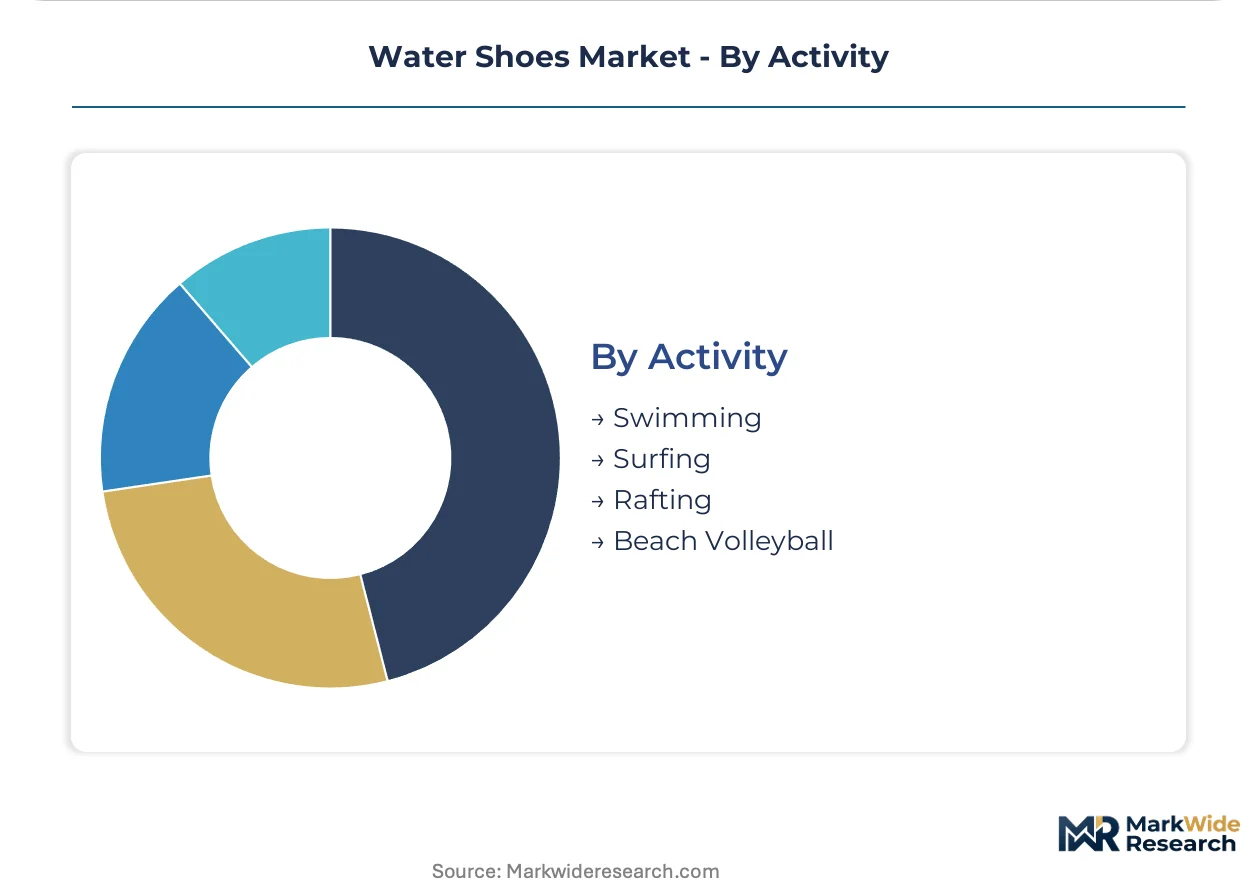
Activity:
Activity-specific biomechanical loads dictate outsole geometry, upper construction, and thermal management requirements.
- Rafting:High-impact protection demands reinforced toe caps and ankle stabilization for paddle entrapment scenarios. Guided excursion operators in Colorado and Utah mandate siped lug compounds for liability reduction.
- Surfing:Split-toe configurations and board-feel sensitivity prioritize thin sole profiles with maximum flexibility. Reef-safe sole mandates in Australia create certified product categories with premium positioning.
- Swimming:Minimalist aqua sock architectures emphasize hydrodynamic efficiency and rapid donning. Chlorine resistance specifications differentiate pool from open-water variants.
- Beach Volleyball:Lateral stability and sand-shedding uppers combine with court-legal non-marking outsoles. Multi-terrain hybrid designs increasingly cannibalize dedicated volleyball-specific constructions.
Rafting applications anchor technical specification development, while Surfing climbs fastest on reef-safe certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adventure tourism operators concentrate procurement volumes in coastal corridors with active reef protection mandates, while REACH compliance redirects European manufacturing toward bio-based formulations. Procurement patterns fragment across regulatory zones, forcing parallel inventory strategies.
United States
Canyon guiding operators in Utah and Colorado drive technical specification demand for siped lug outsoles that reduce client safety liability. The EPA maintains oversight of antimicrobial compound runoff from manufacturing facilities. Industrial concentration clusters around Denver-Boulder outdoor gear corridors where contract manufacturing serves adventure tourism procurement.
Australia
The Great Barrier Reef Marine Park Authority enforces reef-safe sole mandates that exclude zinc-based antibacterials, creating certified premium product categories. TGA alignment with marine park regulations streamlines product registration for reef-adjacent commercial operators. Queensland's coastal tourism corridors from Cairns to Port Douglas anchor certified manufacturing partnerships with guided excursion providers.
Germany
ECHA REACH annex XVII restrictions on phthalates in synthetic rubber accelerate bio-based neoprene R&D investment cycles across Bavarian manufacturing facilities. The EU Green Deal's product durability requirements extend replacement-cycle economics for mesh-construction models. Industrial concentration centers on Munich-anchored outdoor equipment supply chains serving Alpine rafting and canyoning operators.
Indonesia
Underdeveloped domestic supply chains for technical water sports footwear present first-mover advantages in Bali-Lombok coastal tourism corridors. The national pharmaceutical regulator maintains oversight of antimicrobial compounds in bonded materials. Jakarta-anchored distribution networks currently import certified reef-safe products from Australian manufacturing partners.
Japan
METI standards for marine equipment safety influence product specifications for commercial diving and snorkeling operations. PMDA-aligned testing protocols for skin-contact materials extend certification timelines for neoprene formulations. Osaka-Kobe industrial corridors concentrate small-batch manufacturing for domestic adventure tourism operators.
Water Shoes Market Competitive Landscape
Player mix skews toward diversified sportswear conglomerates with technical outdoor subsidiaries, creating tiered competition between mass-market volume and specialized performance positioning. Three strategic archetypes dominate: global sportswear houses with water-specific R&D divisions, technical outdoor specialists with canyon-river expertise, and casual comfort brands bridging beach-to-street transitions. Competitive moves concentrate on portfolio diversification into reef-safe certified lines and strategic partnerships with adventure tourism operators for bulk procurement lock-ins.
Within the technical performance tier, Merrell and Teva exemplify specialized positioning, while Nike anchors mass-market R&D intensity. Merrell occupies a position emphasizing aggressive outsole geometries for canyon environments. Teva represents sandal architecture specialists bridging river-crossing function with post-activity wearability. Nike sits within the diversified conglomerate archetype, channeling sportswear scale toward quick-drain mesh engineering.
| Leading Market Players |
|---|
| Adidas |
| Nike |
| Crocs |
| Merrell |
| Teva |
| Salomon |
| Skechers |
| Keen |
| Columbia |
| Others |
Value Network & Pricing Analysis
Multi-year technical supply agreements with volume guarantees and specification lock-ins anchor procurement relationships between adventure tourism operators and certified manufacturers, binding supply access to predictable unit economics across reef-safe and REACH-compliant product lines. These contract structures compress spot-market exposure while transferring formulation compliance costs upstream.
Pricing Analysis
Cost-plus contracts with petroleum-indexed raw material adjustments dominate bulk procurement between adventure operators and technical manufacturers, passing through neoprene and synthetic rubber volatility. Price differentiation separates reef-safe certified premium tiers from standard synthetic constructions, with Australian Great Barrier Reef Marine Park Authority compliance adding certification premiums. Pricing pressure intensifies in mid-tier mesh constructions as REACH reformulation costs compress margins. Casual users in Southeast Asian coastal corridors exhibit highest price sensitivity, while Australian reef tourism operators accept premium positioning for liability reduction.
Supply Chain Analysis
Inbound logistics costs from Vietnam and Indonesia manufacturing clusters through Singapore transshipment hubs constrain margin flexibility for European and North American distributors. Raw material supply concentrates in China for petroleum-derived neoprene, Thailand for natural rubber compounds, and Germany for bio-based formulation R&D. Manufacturing draws from synthetic rubber and hydrophobic mesh dependencies, with zinc-free antibacterial compound sourcing creating single-source vulnerability for reef-safe lines. Distribution runs through Jakarta-anchored import networks for Indonesian coastal tourism corridors and Denver-Boulder contract manufacturing clusters serving Utah canyon operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as adventure tourism procurement consolidation displaces traditional retail SKU proliferation, redirecting manufacturing capacity toward technical specification contracts.
For Market Incumbents: Consolidate vendor relationships into exclusive reef-safe certified partnerships with Australian Great Barrier Reef Marine Park Authority-approved suppliers, locking out competitors from Queensland's coastal tourism corridors. Deepen backward integration into bio-based neoprene formulation R&D to offset ECHA REACH annex XVII compliance penalties in cold-water immersion segments. Prioritize multi-year capacity reservations with Indonesian manufacturing partners to secure first-mover positioning in Bali-Lombok tourism expansion zones. For New Entrants and Emerging Players: Differentiate on reef-safe certification speed-to-market by establishing direct testing relationships with Australian authority protocols, bypassing incumbent 8-14 month commercialization cycles. Target Indonesia's underdeveloped domestic supply chains through Jakarta-anchored distribution partnerships, importing technical expertise while capturing coastal tourism growth. Pursue white-label manufacturing contracts with European adventure operators seeking REACH-compliant alternatives to petroleum-derived neoprene. For Investors and Strategic Acquirers: Capital is best deployed toward technical outdoor specialists with canyon-river expertise and established adventure operator procurement relationships, given the segment's pricing power and specification lock-in durability. Long-term viability hinges on bio-based material transition capabilities and regulatory chemistry specialization. Watch ECHA REACH annex XVII expansion timelines as inflection indicators for accelerated petroleum-neoprene substitution mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Reef-Safe Certification Investment | Great Barrier Reef Marine Park Authority compliance unlocks premium positioning in Queensland tourism corridors. |
| Bio-Based Neoprene R&D Partnership | ECHA REACH restrictions on phthalates accelerate formulation collaboration with Bavarian chemical facilities. |
| Adventure Operator Contract Manufacturing | Utah and Colorado canyon guiding specifications create multi-year volume guarantees with technical lock-ins. |
| Indonesian Coastal Distribution Expansion | Jakarta-anchored networks capture Bali-Lombok tourism growth with reef-safe certified import partnerships. |
| Quick-Drain Mesh Engineering Scale-Up | Hydrophobic perforated uppers displace solid synthetic constructions in tropical-climate product lines. |
Research Methodology
Initial hypotheses were tested against primary input from adventure tourism procurement directors, footwear manufacturing plant managers, regulatory affairs specialists at ECHA and Australian marine park authorities, and neoprene formulation chemists, then refined through secondary validation. Primary intelligence combined structured interviews with bulk contract negotiators at guided excursion operators and technical R&D leads at performance footwear manufacturers. Secondary sources included ECHA REACH annex XVII regulatory filings, Great Barrier Reef Marine Park Authority certification databases, customs trade records for synthetic rubber and mesh imports, and EU Green Deal durability requirement documentation. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across product type, material chemistry, end user physiology, and activity intensity dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by reef-safe certification penetration rates and REACH compliance cost pass-through assumptions. Forecast inputs incorporated adventure tourism operator procurement consolidation patterns, bio-based neoprene substitution elasticity, and regional chemical registry divergence timelines.
Forecasts assume regulatory continuity in EU REACH and Australian reef-safe regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Football Shoes Market
Footwear
Shoe Insoles Market
Footwear
Global Recovery Footwear Market
Footwear
Second Hand Designer Shoes Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Equestrian Footwear Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Trail Running Shoes Market
Footwear
Refurbished Running Shoes Market
Footwear
Golf Footwear Market
Footwear
Snow Boots for Women Market
Footwear
Snow Boots Market
Footwear
Protective Footwear Market
Footwear
Western Boots Market
Footwear
Kids Barefoot Shoes Market
Footwear
Riding Boots Market