
 South America Athletic Footwear Market | 2026-2036
South America Athletic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
South America Athletic Footwear Market Analytics
Brazil's updated consumer protection framework is shifting import compliance costs for athletic footwear, prompting brands to reassess local assembly strategies. Nike Inc. leverages its established Rio de Janeiro distribution infrastructure to sustain premium positioning. Adidas AG anchors its regional supply through São Paulo logistics hubs. Puma SE differentiates via localized design studios serving Andean markets.
Athletic footwear comprises engineered upper materials, midsole cushioning systems, and outsole traction compounds designed for biomechanical performance during sport-specific movements. Manufacturing integrates injection-molded EVA foam, thermoplastic polyurethane stabilizers, and knitted textile uppers to achieve weight reduction and energy return. Running Shoes dominate volume across South America while Premium price tiers capture disproportionate margin pools in metropolitan Brazil. Online Retail channels are expanding fastest in Argentina and Chile as last-mile logistics mature.
ANVISA in Brazil and Argentina's national consumer protection administration enforce chemical safety and labeling standards that shape product entry requirements. ISO 9001 quality certifications and local content stipulations under Brazil's industrial policy further condition market access. Stakeholders must monitor evolving customs classifications and sustainability disclosure obligations as regional integration deepens.
Market Dynamics
Brazil's updated consumer protection framework and local content stipulations are forcing athletic footwear brands to reconfigure assembly strategies, compressing import-dependent supply models while amplifying domestic manufacturing incentives.
Growth Catalysts
- ANVISA chemical safety mandates:Stricter labeling and material disclosure requirements are accelerating certified supplier partnerships, elevating quality standards across Brazilian distribution channels.
- Knitted textile uppers:Automated knitting systems are reducing material waste and enabling rapid style rotation, resonating with metropolitan Brazilian retailers seeking inventory agility.
- Colombia's fitness infrastructure expansion:Government-backed sports facility investments in Bogotá and Medellín are expanding organized running participation, driving replacement cycle compression.
Market Restraints
- EVA foam price volatility:Petrochemical input fluctuations are compressing margin pools for mid-tier manufacturers dependent on injection-molded midsole production.
- Southeast Asian supply concentration:Thermoplastic polyurethane stabilizer sourcing remains concentrated in Vietnam and Indonesia, exposing brands to shipping cost spikes and customs delays.
- Argentina's import substitution policies:Local content ratios and foreign exchange restrictions are creating compliance friction for brands maintaining centralized regional inventory.
Strategic Opportunities
- Chile's e-commerce logistics maturation:Last-mile infrastructure investments in Santiago are enabling direct-to-consumer channel expansion, bypassing traditional retail markups.
- Bio-based midsole compounds:Convergence of algae-derived foams and castor oil elastomers is opening premium positioning for sustainability-certified product lines.
- Peru's underpenetrated Andean markets:Cusco and Arequipa present whitespace for technical trail running categories adapted to high-altitude terrain.
Industry Challenges
- ISO 9001 certification timelines:Extended audit backlogs at Brazilian accreditation bodies are delaying product launches for new market entrants.
- Biomechanical engineering talent scarcity:Specialized footwear design expertise concentrates in São Paulo, constraining regional design studio expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Athletic Footwear Market |
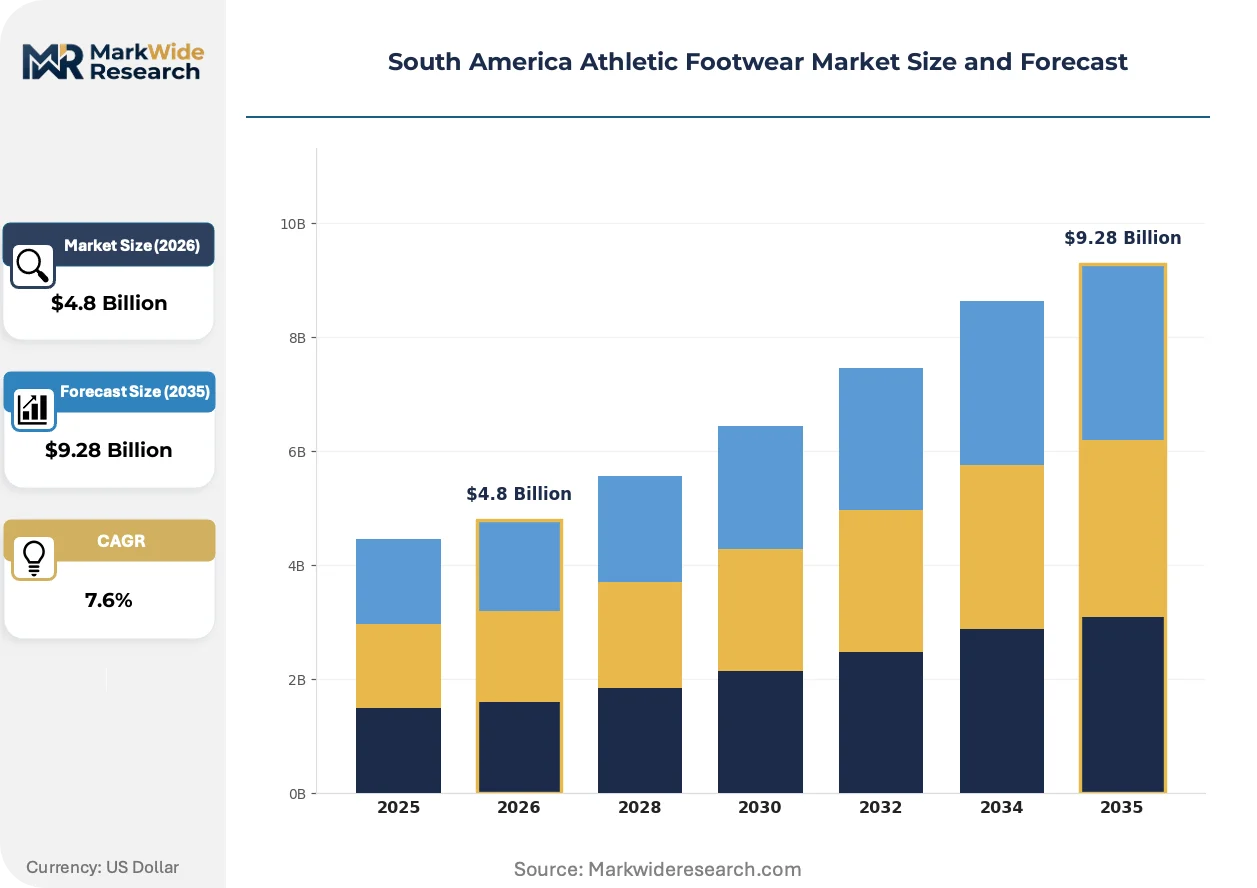
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Shoes, Training Shoes, Sports Sandals, Casual Sneakers Customer Type: Professional Athletes, Recreational Runners, Fitness Enthusiasts, Kids Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Nike Inc., Adidas AG, Puma SE, Under Armour Inc., ASICS Corporation, New Balance, Decathlon SA, Skechers, VF Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Athletic Footwear Market Evolving Landscape
Sustainable material science and digital distribution infrastructure are actively compressing traditional manufacturing and retail paradigms across South American markets. Three developments are restructuring competitive positioning.
Algae-derived foam midsoles are electrifying performance footwear engineering. Brazilian marathon training communities are adopting these compounds at accelerating rates due to weight reduction and energy return metrics. This material transition is compressing petroleum-dependent supply relationships while enabling premium pricing for certified sustainable product tiers.
ANVISA's updated chemical disclosure protocols are mandating granular supply chain documentation for athletic footwear imports. Manufacturers must now map thermoplastic polyurethane and textile dye sources through tier-three suppliers. Running shoe categories face the steepest compliance burden, prompting brands to consolidate supplier bases and pre-qualify Brazilian-certified material vendors.
Subscription-based footwear replacement programs are disrupting traditional retail purchase cycles in Argentina's urban centers. Fitness enthusiasts in Buenos Aires are shifting from episodic buying to automated delivery models tied to mileage tracking apps. This behavioral pivot is compressing brand loyalty dynamics while elevating logistics infrastructure requirements for same-day fulfillment networks.
South America Athletic Footwear Market Segmentation
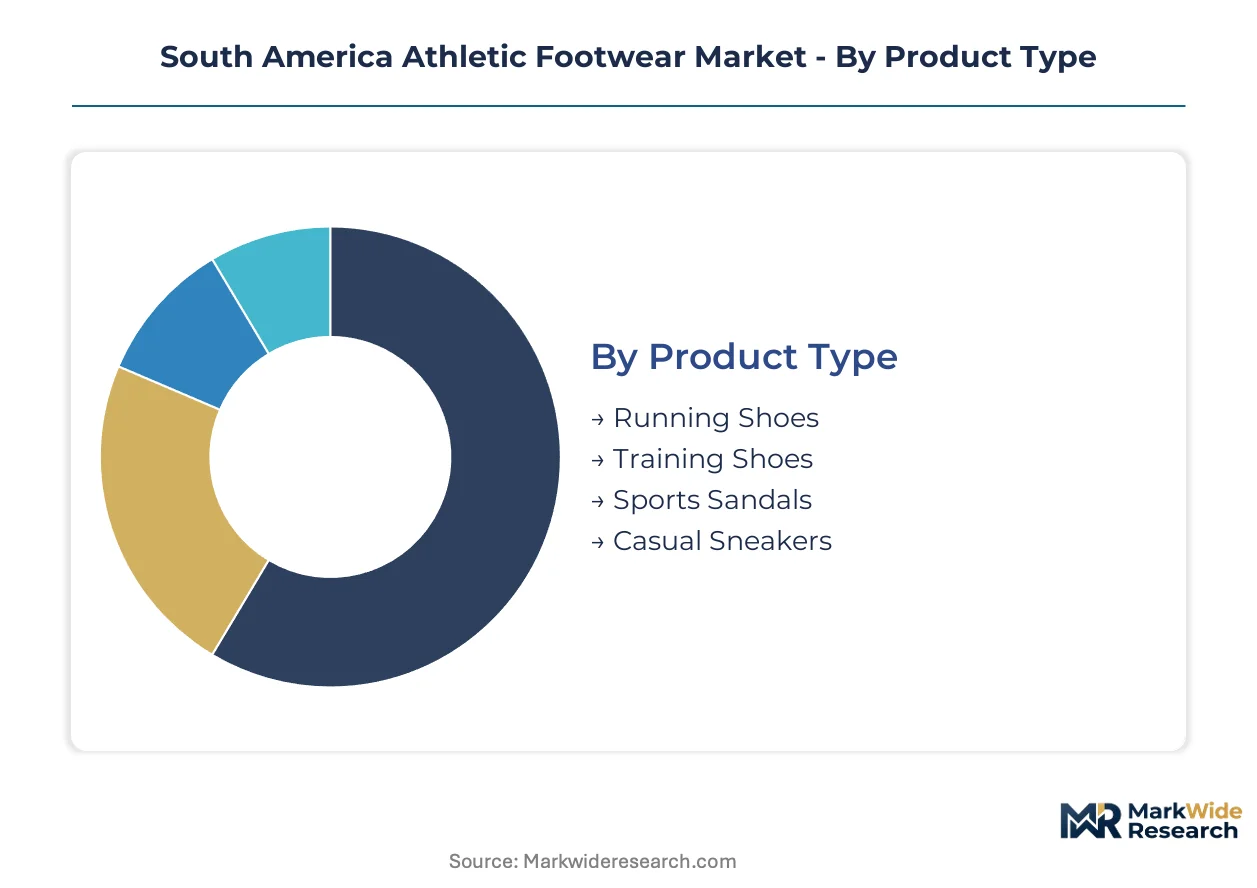
Segmentation in South America's athletic footwear market reveals distinct capital requirements, customer loyalty patterns, and margin architectures that shape how brands allocate manufacturing and distribution resources across Brazil, Argentina, and Colombia.
Product Type:
Capital intensity varies sharply across product categories, with specialized midsole engineering and biomechanical testing facilities demanding the heaviest upfront investment.
- Running Shoes:Engineered with injection-molded EVA foam midsoles and thermoplastic polyurethane stabilizers for energy return and gait correction. Demand concentrates in São Paulo and Rio de Janeiro's marathon training communities, where replacement cycles compress as organized racing participation expands.
- Training Shoes:Multi-directional traction outsoles and reinforced upper construction accommodate cross-training and gym environments. Colombian fitness infrastructure investments in Bogotá and Medellín are accelerating category uptake among recreational athletes seeking versatile performance footwear.
- Sports Sandals:Open-toe designs with contoured footbeds target warm-climate recreational use across Brazil's coastal cities.
- Casual Sneakers:Lifestyle-oriented silhouettes with simplified cushioning systems dominate volume in Argentina's price-sensitive urban markets.
Most installed capacity flows through Running Shoes. Expansion is steepest in Training Shoes.
Customer Type:
Purchase frequency and price elasticity diverge substantially across user profiles, with professional segments exhibiting inelastic demand and concentrated geographic clustering.
- Professional Athletes:Custom-fitted performance footwear with carbon-fiber plates and proprietary foam compounds. Brazil's southeastern industrial corridor hosts the densest concentration of sponsored athletes driving technical specification requirements.
- Recreational Runners:Standardized sizing with moderate cushioning upgrades and mileage-tracking compatibility. Subscription-based replacement programs in Buenos Aires are compressing traditional retail purchase cycles for this segment.
- Fitness Enthusiasts:Cross-training versatility prioritizes durability over specialization in Chile's expanding gym culture.
- Kids:Growth-accommodating designs with simplified closure systems and reinforced toe caps target family purchasing decisions in Colombia's emerging middle-class households.
Professional Athletes command the highest per-unit margins. Recreational Runners are gaining share fastest.
Distribution Channel:
Logistics infrastructure maturity determines channel viability, with last-mile density requirements favoring distinct geographic rollout sequences.
- Online Retail:Direct-to-consumer platforms with virtual fitting tools and same-day fulfillment networks. Santiago's logistics maturation is enabling channel expansion that bypasses traditional retail markups.
- Specialty Stores:Gait analysis services and expert fitting consultations anchor premium positioning in São Paulo's specialized retail corridors.
- Department Stores:Multi-brand assortments with seasonal promotional calendars dominate Argentina's centralized inventory model.
- Supermarkets:Mass-market accessibility with limited size ranges serves budget-conscious purchasers in Brazil's peripheral urban zones.
Specialty Stores retain the deepest customer relationships. Online Retail is climbing the fastest.
Price Tier:
Raw material certification costs and local content compliance burdens create divergent margin structures across pricing strata.
- Premium:ANVISA-certified sustainable materials with algae-derived foams and traceable supply chain documentation. Metropolitan Brazil captures disproportionate margin pools as certified product tiers command pricing power.
- Mid-Range:Standardized EVA construction with regional supplier qualification meeting basic chemical disclosure requirements. Argentina's import substitution policies create compliance friction that compresses effective pricing flexibility.
- Budget:Simplified injection-molding processes with domestic Brazilian material sourcing to satisfy local content stipulations.
- Discount:Unbranded or private-label offerings with minimal biomechanical engineering and limited durability warranties.
Premium tier absorbs the majority of innovation investment. Budget tier is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered large-scale athletic footwear manufacturing in South America during the 1970s industrial expansion, establishing the continent's first integrated supply chains for synthetic upper materials and rubber outsole compounds. This historical foundation created technical expertise clusters that persist in São Paulo's eastern industrial zones today.
Brazil
Marathon training communities in São Paulo and Rio de Janeiro drive replacement cycle compression for technical running categories. ANVISA chemical disclosure mandates now require tier-three supplier mapping for all imported footwear components. The southeastern industrial corridor between São Paulo and Campinas hosts the densest concentration of certified material vendors serving premium product tiers.
Argentina
Buenos Aires fitness enthusiasts are shifting toward subscription-based replacement programs tied to mileage tracking applications. The national consumer protection administration enforces labeling standards that create compliance friction for centralized regional inventory models. Córdoba's emerging logistics networks are enabling direct-to-consumer channel experiments bypassing traditional retail markups.
Colombia
Government-backed sports facility investments in Bogotá and Medellín are expanding organized running participation among middle-class households. Local content stipulations under industrial policy frameworks condition import duty advantages for brands establishing domestic assembly. The Aburrá Valley manufacturing zone is attracting regional distribution center investments from multinational athletic brands.
Chile
Santiago's last-mile infrastructure maturation is enabling same-day fulfillment networks for online retail channels. The country's national consumer protection regulator maintains chemical safety standards aligned with broader South American trade bloc harmonization efforts. The capital's logistics parks are becoming regional e-commerce hubs serving cross-border Andean markets.
Peru
Technical trail running demand is emerging in Cusco and Arequipa as high-altitude terrain sports gain participation. Import compliance requirements follow regional trade agreement frameworks with additional phytosanitary controls on natural rubber components. The central Andean corridor presents whitespace for category specialists adapting products to altitude-specific biomechanical stresses.
South America Athletic Footwear Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and distribution infrastructure dimensions, creating a tiered competitive structure. The vendor base clusters around three strategic archetypes: integrated multinationals with captive regional logistics, specialized performance brands with biomechanical engineering competencies, and value-oriented retailers with private-label manufacturing relationships. Capacity expansion and strategic partnerships dominate competitive moves as brands navigate local content requirements.
Within the integrated multinational tier, Nike Inc., Adidas AG, and Puma SE occupy positions defined by geographic distribution infrastructure depth. Nike Inc. exemplifies the logistics-anchored archetype through its established Rio de Janeiro distribution presence. Adidas AG represents supply chain regionalization strategies centered on São Paulo hub operations. Puma SE sits within the design-localization archetype with studio capabilities serving Andean market adaptation requirements.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Puma SE |
| Under Armour Inc. |
| ASICS Corporation |
| New Balance |
| Decathlon SA |
| Skechers |
| VF Corporation |
| Others |
Value Network & Pricing Analysis
Petrochemical input fluctuations for injection-molded EVA foam cascade through South American athletic footwear pricing tiers, with volatility in thermoplastic polyurethane stabilizer costs compressing margin pools for mid-tier manufacturers while amplifying premium positioning for brands sourcing certified sustainable alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified sustainable product lines with algae-derived compounds from standardized EVA construction and simplified domestic Brazilian material sourcing. Price differentiation hinges on certification grade for chemical disclosure compliance and volume scale of automated knitting production. Cost compression in mid-range tiers is intensifying because Argentina's import substitution policies create compliance friction for centralized regional inventory. Budget-conscious purchasers in Brazil's peripheral urban zones exhibit highest price sensitivity, while professional athletes in São Paulo's southeastern corridor show least elasticity.
Supply Chain Analysis
Regional distribution centers in São Paulo and Rio de Janeiro anchor hub-and-spoke patterns that feed specialty retail corridors and emerging direct-to-consumer channels. Manufacturing draws from Vietnam and Indonesia for thermoplastic polyurethane stabilizers, Brazil for injection-molded EVA foam assembly, and domestic textile suppliers for knitted uppers. Single-source vulnerability concentrates in Southeast Asian stabilizer sourcing, exposing brands to shipping cost spikes and customs delays. Distribution runs through São Paulo logistics hubs serving metropolitan Brazil, with Santiago emerging as a secondary node for Andean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's athletic footwear market compounds steadily as marathon training participation and organized fitness infrastructure expand replacement cycles across Brazil, Argentina, and Colombia.
For Market Incumbents: Deepen certification investment in ANVISA-compliant material partnerships to defend against emerging local assembly competitors capitalizing on Brazil's industrial policy incentives. Anchor channel control through São Paulo specialty retail relationships while adding capacity in Campinas-certified vendor zones. Vertical integration into algae-derived foam sourcing mitigates petrochemical price volatility threatening mid-tier margin pools. For New Entrants and Emerging Players: ANVISA's updated chemical disclosure protocols in Brazil open a window for pre-qualified domestic material vendors to capture share from import-dependent incumbents facing compliance friction. Peru's underpenetrated Andean markets in Cusco and Arequipa present whitespace for technical trail running categories adapted to high-altitude terrain. A direct-to-consumer launch through Santiago's maturing last-mile infrastructure bypasses traditional retail markups and subscription-based replacement models gaining traction in Buenos Aires. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 9001 certification timelines extend audit backlogs at Brazilian accreditation bodies, delaying product launches for new market entrants and favoring established players with pre-cleared supplier relationships. Long-term viability favors vertically integrated specialists with captive regional logistics and biomechanical engineering competencies concentrated in São Paulo. Watch subscription-based replacement program adoption rates in Argentina's urban centers as an inflection indicator for channel disruption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Pre-qualifies Brazilian material vendors ahead of tier-three supplier mapping mandates. |
| Algae-Derived Foam Sourcing | Secures premium positioning as marathon communities adopt sustainable compounds. |
| Santiago Distribution Hub Expansion | Enables same-day fulfillment networks for direct-to-consumer Andean penetration. |
| Automated Knitting System Deployment | Reduces material waste while accelerating style rotation for metropolitan retailers. |
| Subscription Program Partnership | Aligns with Buenos Aires fitness enthusiasts shifting from episodic buying models. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand supply chain directors, ANVISA regulatory consultants, specialty retail buyers in São Paulo, and marathon training community organizers with secondary validation through customs trade records, ANVISA chemical disclosure filings, and retail audit data from metropolitan Brazilian distribution channels. Bottom-up manufacturing capacity assessments and top-down demand modeling triangulated volume estimates.
Comparable historical periods anchored the projection horizon across product type, customer segment, distribution channel, and price tier dimensions, with additional granularity for regional regulatory cluster variations. CAGRs were derived through segment-level growth rate aggregation and cross-reference against macroeconomic indicators. Forecast inputs incorporated petrochemical price volatility indices and fitness infrastructure investment pipelines in Bogotá and Medellín.
Revisions become necessary when ANVISA extends chemical disclosure mandates beyond current tier-three supplier requirements, when Argentina intensifies foreign exchange restrictions on regional inventory models, or when Southeast Asian stabilizer sourcing disruptions exceed baseline shipping cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Sustainable Footwear Market
Footwear
Platform Boots Market
Footwear
Sneaker Boots Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Europe Athletic Footwear Market
Footwear
Protective Footwear Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
PVC Footwear Market
Footwear
Football Shoes Market
Footwear
Hiking Footwear Market
Footwear
Europe Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Leather Sneakers Market
Footwear
Luxury Footwear Market
Footwear
United States Footwear Market
Footwear
Orthopedic Footwear Market