
 Human Identification Analysis Software Market | 2026-2036
Human Identification Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Human Identification Analysis Software Market Outlook
North American software vendors is expanding cloud-native biometric infrastructure to serve federal and state identification contracts. IBM leverages its Watson AI stack to anchor large-scale government fingerprint and facial recognition deployments. Palantir Technologies competes in secure intelligence-sector identity fusion, while SAS Institute specializes in analytics-heavy forensic DNA matching workflows for public safety agencies.
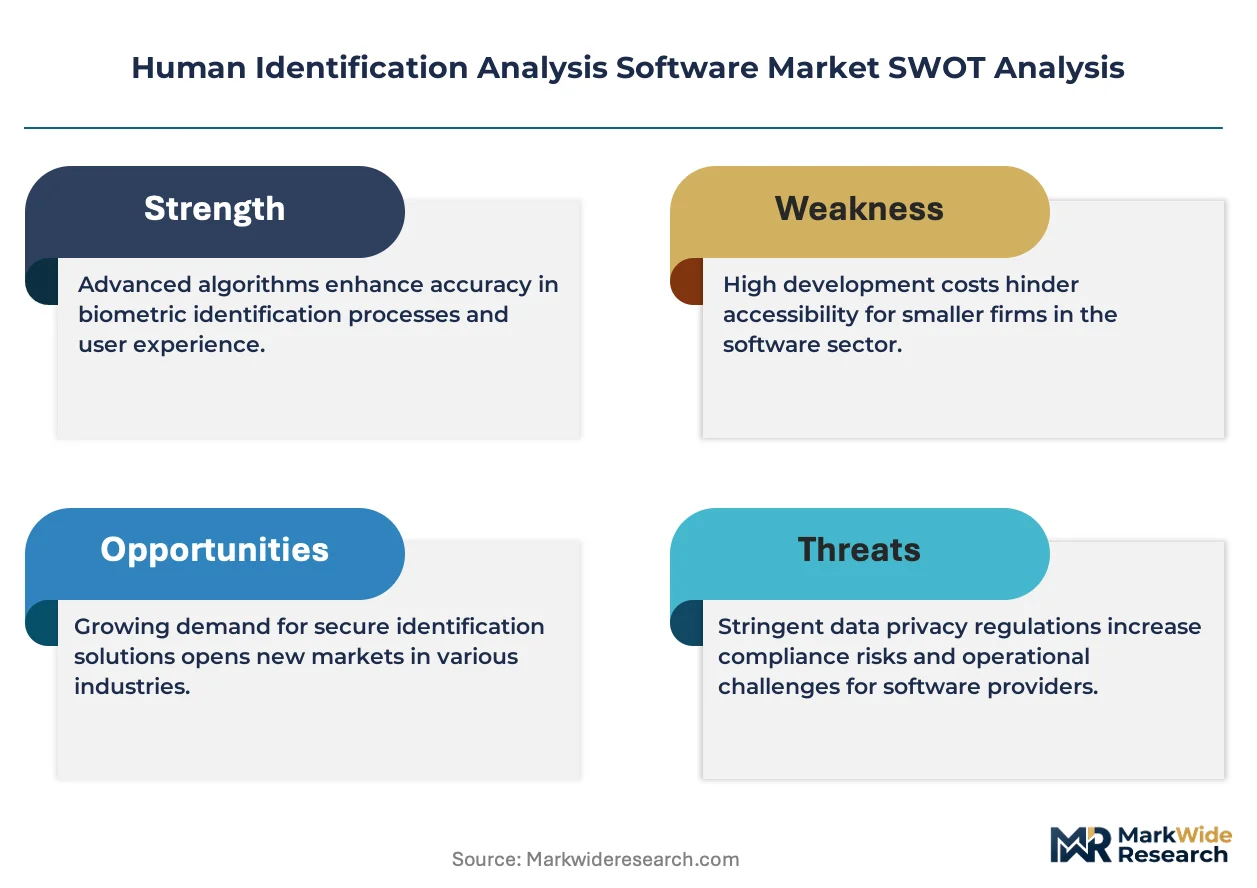
Human identification analysis software encompasses algorithmic platforms that process biometric modalities—fingerprint minutiae, facial geometry, voice spectrograms, and iris patterns—through machine learning pipelines to establish or verify individual identity against enrolled databases. The primary commercial purpose centers on enabling deterministic identity resolution for security, forensic, and access-control applications. Facial recognition systems lead product type revenue due to their deployment flexibility across surveillance and mobile onboarding contexts, while machine learning and neural network technologies capture the fastest expansion as vendors replace legacy rule-based matchers with deep learning architectures. Cloud-based deployment is gaining structural share among financial institutions seeking elastic capacity for customer identity verification.
FDA oversight applies where identification software integrates with clinical diagnostic workflows, while the EU AI Act imposes conformity obligations on biometric systems deployed in European jurisdictions. The FBI's Next Generation Identification program and DHS biometric entry-exit mandates shape procurement specifications for vendors serving United States government accounts. Stakeholders must monitor evolving algorithmic auditing requirements and cross-border data residency rules that will determine which platform architectures qualify for restricted national security and healthcare contracts.
Market Dynamics
Deep learning architectures are displacing legacy rule-based biometric matchers across law enforcement and border control deployments, compressing algorithm development cycles and elevating computational infrastructure requirements for vendors serving government contracts.
Growth Catalysts
- FBI Next Generation Identification mandates:Federal procurement specifications for fingerprint and facial recognition systems are accelerating platform modernization across state criminal justice agencies in the United States.
- Cloud-native infrastructure migration:Financial institutions are deploying elastic biometric verification capacity to support mobile customer onboarding and real-time identity proofing workflows.
- EU AI Act risk classification:Conformity obligations for high-risk biometric systems are creating compliance-driven replacement cycles among European public safety software vendors.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for neural network-based matchers depend on concentrated semiconductor supply from Taiwan and South Korea foundries.
- Cross-border data residency rules:National security contracts in the United States, Germany, and India require localized server infrastructure, fragmenting vendor cloud architectures.
- Algorithmic audit requirements:Emerging standards for bias testing and demographic performance validation are extending procurement timelines for government biometric platforms.
Strategic Opportunities
- Healthcare diagnostic integration:FDA-regulated clinical workflows for patient identification and specimen tracking represent an underpenetrated vertical for biometric software vendors.
- Voice spectrogram authentication:Convergence of natural language processing and speaker recognition is opening contact center and telehealth application channels.
- State-level criminal justice upgrades:Fragmented procurement across United States county and municipal jurisdictions creates white space for modular, API-first platform architectures.
Industry Challenges
- Forensic data science talent scarcity:Vendors face acute competition for machine learning engineers with domain expertise in biometric feature extraction and latent print analysis.
- Legacy matcher integration complexity:Government agencies require seamless interoperability between new deep learning pipelines and decades-old AFIS (Automated Fingerprint Identification System) database formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Identification Analysis Software Market |
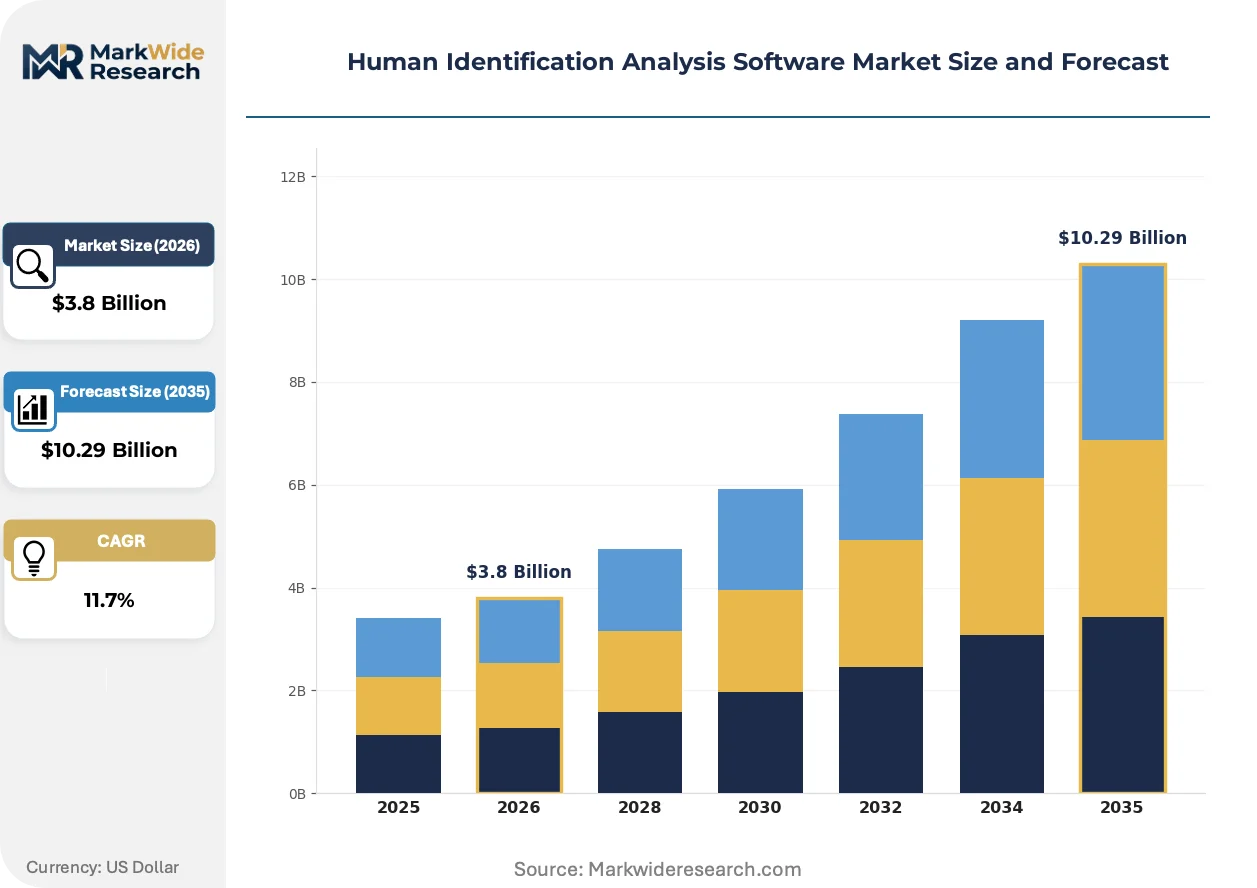
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Software, Facial Recognition, Voice Recognition, Fingerprint Scanning Technology: Machine Learning, Neural Networks, Optical Character Recognition, Image Processing End User: Government Agencies, Financial Institutions, Healthcare Providers, Retailers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | IBM, Deloitte, Agilent Technologies, Palantir Technologies, SAS Institute, Laboratory Corporation of America, Accenture, DataRobot, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Identification Analysis Software Market Strategic Shifts
Transformer-based neural architectures are rewriting performance benchmarks across facial recognition and voice biometrics, while regulatory fragmentation between jurisdictions is forcing vendors into multi-modal compliance engineering.
Self-supervised learning for biometric feature extraction is rewriting how vendors train matchers without labeled datasets. United States defense and intelligence agencies are piloting these techniques for low-enrollment scenarios. The approach is compressing development timelines while raising questions about explainability requirements under emerging algorithmic auditing standards.
The EU AI Act's conformity assessment framework for remote biometric identification systems is mandating third-party testing and CE marking for European deployments. Vendors must document risk management systems and post-market monitoring protocols. Law enforcement procurement in Germany, France, and the Netherlands now prioritizes platforms with pre-certified compliance packages.
Subscription-based platform licensing is displacing perpetual software licenses in financial services identity verification. Tier-one banks in the United States and United Kingdom are negotiating consumption-based contracts tied to monthly active verification volumes. This shift is compressing vendor revenue recognition cycles while aligning pricing with actual biometric query throughput.
Human Identification Analysis Software Market Segmentation
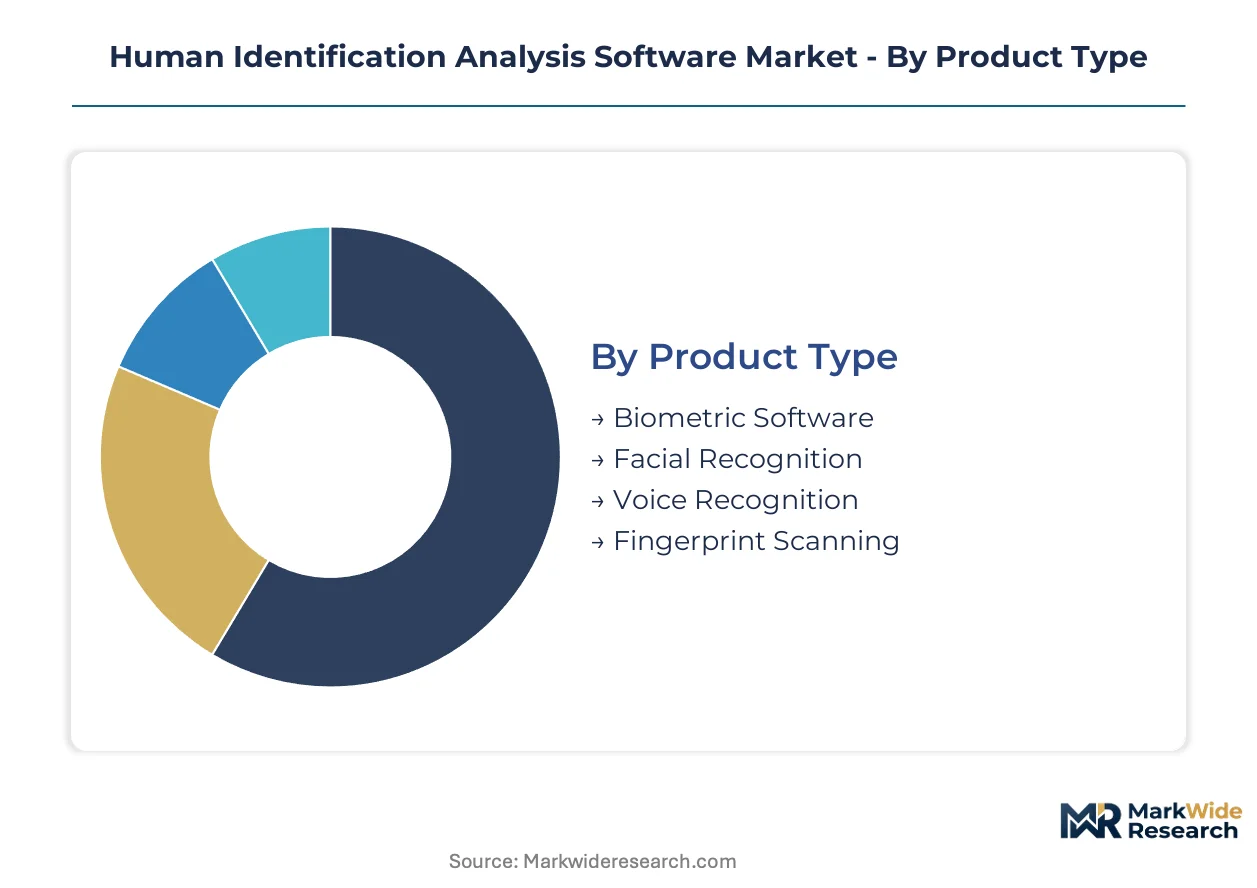
Segmentation in human identification analysis software reveals how technical architecture, procurement constraints, and regulatory exposure fragment vendor opportunity. Buyers select platforms based on biometric modality, inference infrastructure, compliance jurisdiction, and integration legacy.
Product Type:
Standardization dominates facial and fingerprint matching where NIST benchmarks drive commoditization, while voice and multimodal fusion retain customization premiums for specialized deployments.
- Facial Recognition:Algorithms map facial geometry through deep convolutional networks for surveillance and mobile onboarding. United States federal border modernization programs and state-level criminal justice upgrades concentrate procurement volume here.
- Biometric Software:Multi-modal platforms orchestrate fingerprint, iris, and facial matchers through unified APIs. Financial institutions in the United States deploy these for elastic customer identity verification, driving cloud-native infrastructure migration.
- Voice Recognition:Speaker identification systems analyze spectrograms for contact center authentication and telehealth workflows.
- Fingerprint Scanning:Minutiae extraction and latent print matching remain anchored to FBI Next Generation Identification specifications for state and local law enforcement.
Most installed capacity flows through Facial Recognition. Expansion is steepest in Biometric Software.
Technology:
Cost tiers separate legacy rule-based systems from deep learning architectures that demand GPU clusters and specialized ML engineering talent.
- Neural Networks:Deep learning matchers displace legacy algorithms across law enforcement and border control, compressing development cycles while elevating computational infrastructure requirements. United States government contracts now specify neural architectures for new procurements.
- Machine Learning:Supervised and self-supervised training pipelines enable biometric feature extraction without labeled datasets. Defense and intelligence agencies pilot these techniques for low-enrollment scenarios.
- Image Processing:Traditional computer vision methods persist in resource-constrained edge deployments and legacy system interoperability.
- Optical Character Recognition:Document authentication modules extract identity data from passports and driver's licenses for KYC workflows.
Neural Networks capture the dominant share of new procurement spend. Machine Learning shows the steepest expansion trajectory as vendors adopt self-supervised training.
End User:
Application context determines compliance burden — government agencies face algorithmic audit mandates while financial institutions prioritize throughput elasticity.
- Government Agencies:Law enforcement, border control, and national security organizations procure deterministic identity resolution platforms. FBI and DHS procurement specifications shape vendor roadmaps for United States federal contracts.
- Financial Institutions:Banks and payment processors deploy real-time biometric verification for mobile onboarding and transaction authentication. Subscription-based licensing is displacing perpetual contracts as tier-one United States and United Kingdom banks negotiate consumption-based pricing.
- Healthcare Providers:FDA-regulated clinical workflows for patient identification and specimen tracking represent emerging demand for biometric software vendors.
- Retailers:Loss prevention and customer analytics drive deployment of facial recognition in physical store environments.
Government Agencies anchor current installed base. Financial Institutions are gaining share fastest as cloud-native verification scales.
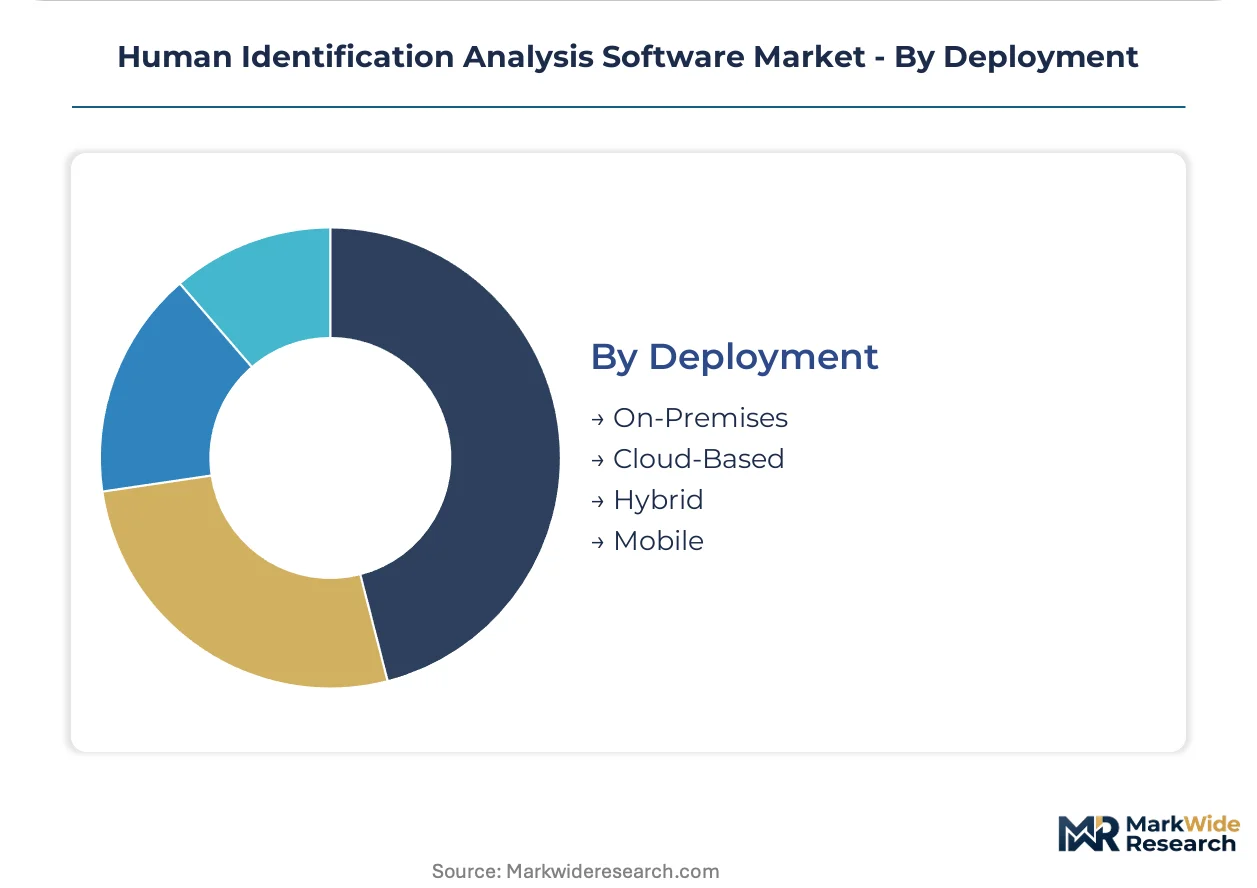
Deployment:
Customer type dictates infrastructure choice — national security contracts require localized servers while financial services prioritize elastic cloud capacity.
- Cloud-Based:Elastic biometric verification capacity supports variable query volumes for financial services and retail applications. United States and European financial institutions lead migration here.
- On-Premises:Air-gapped infrastructure satisfies cross-border data residency rules for national security and sensitive government contracts in the United States, Germany, and India.
- Hybrid:Split architectures process enrollment on-premises and verification through cloud inference, balancing latency with compliance.
- Mobile:Edge-deployed matchers on smartphones and tablets enable field-based law enforcement and remote customer onboarding.
On-Premises retains the largest legacy footprint. Cloud-Based deployment is climbing the fastest as financial institutions modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting vendor investment toward compliance-friendly architectures. The United States maintains procurement primacy through federal biometric modernization programs, while European conformity obligations under the EU AI Act compress deployment timelines for high-risk identification systems.
United States
FBI Next Generation Identification mandates and DHS biometric entry-exit programs drive federal procurement volume. The FBI shapes vendor roadmaps through fingerprint and facial recognition specifications for state and local law enforcement agencies. California and Texas host concentrated cloud-native infrastructure deployments serving financial services identity verification contracts.
Germany
Bundesdruckerei procurement standards and federal police modernization fund biometric platform replacements. The EU AI Act's conformity assessment framework mandates third-party testing and CE marking for remote biometric identification systems. Berlin and Munich anchor vendor engineering centers focused on high-risk system compliance engineering.
United Kingdom
Home Office biometric procurement and Financial Conduct Authority digital identity guidance accelerate financial services adoption. The UK Information Commissioner's Office enforces algorithmic transparency requirements for public sector facial recognition. London's fintech cluster drives consumption-based licensing negotiations for real-time verification platforms.
India
Unique Identification Authority of India integration requirements and state-level criminal justice digitization expand addressable market. The Digital Personal Data Protection Act imposes data localization obligations on biometric system operators. Bangalore and Hyderabad concentrate vendor delivery centers serving government and banking sector contracts.
Japan
Ministry of Justice immigration system upgrades and Financial Services Agency digital identity guidelines stimulate platform demand. METI standards for biometric authentication in financial transactions shape vendor product specifications. Tokyo anchors domestic vendor headquarters while Osaka hosts specialized forensic DNA analysis software development.
Human Identification Analysis Software Market Competitive Environment
United States producers anchor the government-contract tier; European specialists hold compliance-engineering positions. The vendor base separates into consolidated platform providers serving federal agencies and modular specialists addressing state-level fragmentation. Three archetypes dominate: full-stack AI platforms, secure intelligence-sector integrators, and analytics-heavy forensic specialists. Competitive moves center on cloud-native infrastructure migration and multi-modal compliance engineering for cross-border contracts.
Within the full-stack platform tier, IBM leverages its Watson AI stack for large-scale government biometric deployments. Palantir Technologies occupies a position in secure intelligence-sector identity fusion, while SAS Institute exemplifies the analytics-specialist archetype for forensic DNA matching workflows. These three anchors represent divergent strategic postures: horizontal AI platform extension, vertical intelligence-community focus, and deep domain specialization in public safety analytics.
| Leading Market Players |
|---|
| IBM |
| Deloitte |
| Agilent Technologies |
| Palantir Technologies |
| SAS Institute |
| Laboratory Corporation of America |
| Accenture |
| DataRobot |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Federal law enforcement procurement programs in the United States concentrate buyer power and anchor subscription-based SaaS pricing for biometric matching platforms. This procurement concentration elevates price sensitivity among state and municipal agencies while allowing full-stack vendors to capture premium margins through compliance bundling.
Pricing Analysis
Direct-to-government discounts dominate large federal contracts, with tier-one vendors offering volume-scaled SaaS tiers tied to monthly active verification volumes. Pricing stratifies across premium neural-network architectures, standard rule-based matchers, and economy-grade API access for smaller jurisdictions. Cost compression in cloud inference tiers is intensifying because GPU compute volatility from Taiwan and South Korea foundries squeezes vendor margins. State-level criminal justice agencies exhibit highest price sensitivity; intelligence-sector integrators face lowest sensitivity due to security-clearance barriers.
Supply Chain Analysis
Domestic-content mandates in United States national security contracts and India's Digital Personal Data Protection Act are reshaping sourcing toward localized server infrastructure. Semiconductor supply concentrates in Taiwan, South Korea, and the United States for GPU clusters powering neural network training. Raw material dependencies span advanced silicon wafers, specialized cooling systems, and high-bandwidth memory modules. Single-source vulnerability in Taiwan foundry capacity presents structural risk. Distribution runs through direct federal procurement channels, systems integrators, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement specifications from the FBI and DHS are elevating algorithmic audit and compliance requirements toward premium-tier platform investments.
For Market Incumbents: Cement platform stickiness through backward integration into specialized forensic data science talent pipelines and captive GPU cluster capacity in United States sovereign cloud zones. Emerging modular specialists threaten margin compression in state-level fragmented procurement; defend through certification pre-engineering for EU AI Act conformity packages. For New Entrants and Emerging Players: Begin with voice spectrogram authentication for telehealth and contact center verticals where incumbent footprint remains thin. Healthcare diagnostic integration represents the most penetrable application layer; pursue FDA-regulated clinical workflow partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Defense and intelligence contractors are the most active acquirer in this space, seeking identity fusion capabilities for cross-border security contracts. Long-term viability hinges on multi-modal compliance engineering spanning EU AI Act, FBI NGI specifications, and emerging algorithmic audit standards. Watch for self-supervised learning breakthroughs in low-enrollment scenarios as the inflection signal for platform displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Elastic capacity aligns vendor pricing with financial services verification volumes in United States and United Kingdom. |
| EU AI Act Compliance Engineering | Pre-certified conformity packages accelerate procurement timelines for German, French, and Dutch law enforcement agencies. |
| Healthcare Diagnostic Integration | FDA-regulated patient identification workflows open underpenetrated vertical beyond traditional security applications. |
| Self-Supervised Learning Investment | Low-enrollment training techniques compress development cycles for United States defense and intelligence pilot programs. |
| State-Level Criminal Justice Modularization | API-first architectures address fragmented county and municipal procurement across United States jurisdictions. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with biometric software engineering directors, federal procurement officers, and financial services IT security leads. Secondary validation draws from FBI procurement databases, EU AI Act implementation guidance, SEC filings of publicly traded platform vendors, and NIST biometric benchmark publications. Bottom-up segment modeling and top-down macro triangulation cross-verify volume and value outputs.
Granularity extends to biometric modality, deployment architecture, and end-use compliance tier across the projection horizon. Neural network and machine learning technology segments were modeled separately from legacy rule-based systems. CAGRs derive from algorithmic performance improvement curves, federal budget authorization trajectories, and cloud infrastructure capex disclosures from hyperscale providers. Industry-specific inputs include FBI NGI modernization schedules and EU conformity assessment timeline assumptions.
Caveats apply where GPU supply chain disruptions, algorithmic audit standard revisions, or cross-border data residency rule changes could materially shift the outlook. Forecasts reflect documented assumptions about federal procurement continuity and financial services cloud migration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Audit Management Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Email Optimization Software Market
Software & Services
Software Licensing Market
Software & Services
Test Management Software Market
Software & Services
HR Tech Market
Software & Services
Lab Automation Software Market
Software & Services
Collaborative Applications Market
Software & Services
Global User Interface Service Market
Software & Services
Global Inspection Management Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Job Description Management Software Market
Software & Services
Kennel Management Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
PCB CAD Software Market
Software & Services
Airline Route Profitability Software Market