
 Smart/AI Toys Market | 2026-2036
Smart/AI Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Smart/AI Toys Market Analytics
Educational institutions is unwinding the traditional parent-dominant purchase pattern as school districts and therapy centers procure AI toys at institutional scale. Mattel, Inc. leverages its established retail relationships to secure shelf space for its learning-oriented product lines. UBTECH Robotics Corp. anchors its position through in-house production of servo motors and proprietary motion-control chipsets. Sphero, Inc. differentiates by specializing in programmable robotics curricula that align with K-12 computer science standards.
Smart/AI Toys encompass electronically enhanced play products incorporating microprocessors, sensors, and cloud-connected software to enable adaptive responses, personalized content delivery, and remote data analytics for developmental assessment. These products typically integrate ARM Cortex or equivalent low-power processors, lithium-polymer cells, and Bluetooth 5.0 or Wi-Fi modules within child-safe ABS or silicone enclosures. Machine Learning applications command the deepest engineering investment as adaptive algorithms enable toys to personalize difficulty curves and emotional responses based on longitudinal interaction data. Learning Robots capture the steepest growth trajectory among product types, driven by institutional procurement and parental preference for tangible STEM skill-building over passive screen entertainment.
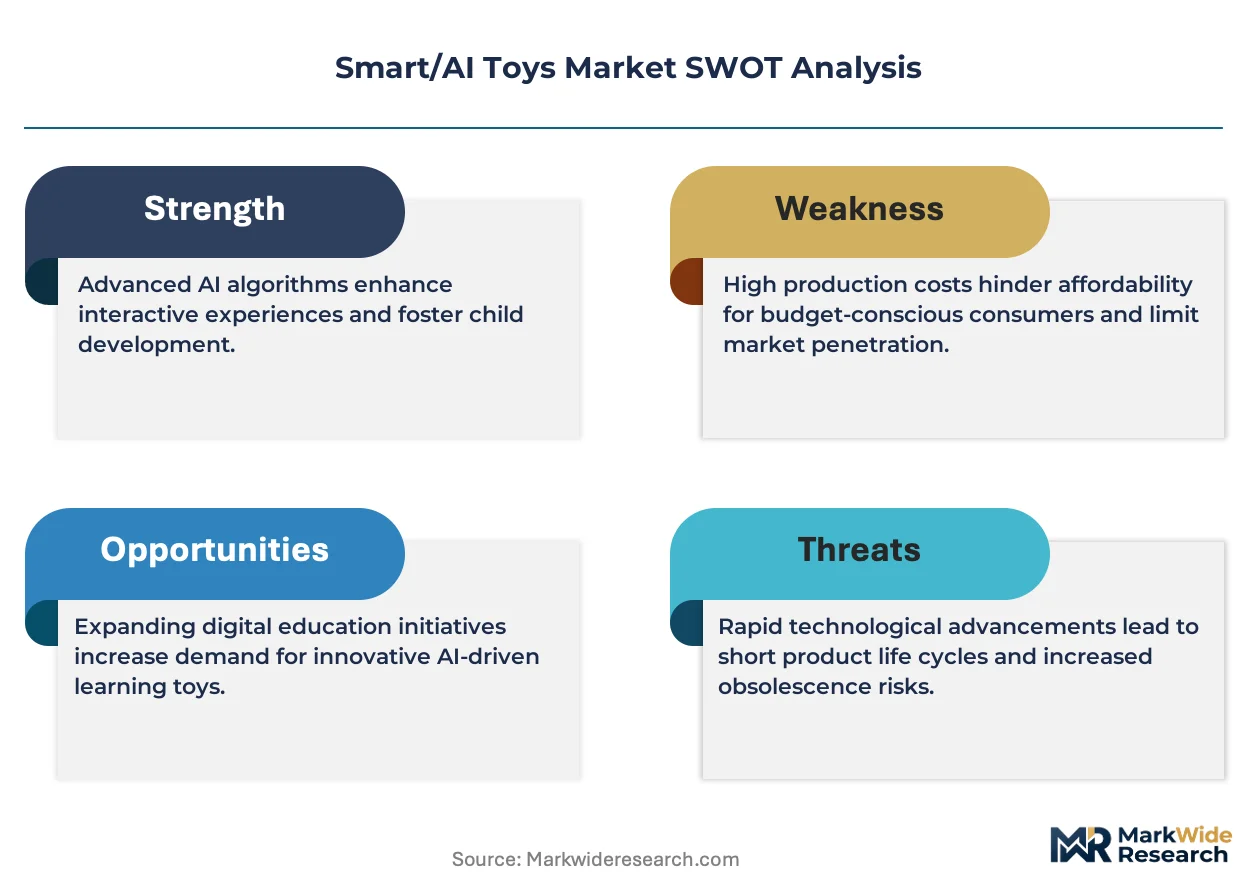
The Federal Trade Commission enforces COPPA compliance for data collection from children under thirteen, while the EU AI Act imposes risk-classification requirements on AI systems interacting with minors, forcing redesigns of cloud-dependent voice features. China's SAMR and GB standards mandate cybersecurity certification for connected children's products, creating divergent testing protocols for multi-regional launches. Stakeholders must monitor whether fragmented regulatory architectures fragment product development or create first-mover advantages for firms that architect modular compliance from inception.
Market Dynamics
Machine learning inference at the edge is compressing cloud dependency costs while COPPA and EU AI Act enforcement are forcing architectural redesigns of voice-interactive features for minors.
Growth Catalysts
- STEM curriculum mandates:School districts in South Korea and China now require programmable robotics modules in primary education, institutionalizing procurement channels that bypass traditional retail.
- EU AI Act risk-classification framework:Manufacturers achieving compliance early gain first-mover shelf access across 27 member states as retailers delist non-conforming connected products.
- LiDAR and time-of-flight sensors:Falling component costs enable spatial awareness features in sub-premium price tiers, expanding addressable household segments.
Market Restraints
- Neodymium magnet supply concentration:Servo motor production depends on Chinese rare-earth processing, exposing margins to export quota volatility.
- COPPA compliance friction:The FTC's 13-and-under data prohibition forces dual-SKU strategies—one cloud-connected, one offline—doubling inventory carrying costs.
- Screen-based entertainment substitution:Tablets and gaming consoles retain lower price points and broader content libraries, limiting price elasticity for AI toy premiums.
Strategic Opportunities
- Speech therapy and autism intervention centers:Clinical settings in the United States and Germany seek FDA/CE-marked adaptive companions for developmental assessment, commanding reimbursement-linked pricing.
- SAMR cybersecurity certification:China's mandatory pre-market testing creates a compliance moat for firms with in-country testing facilities.
- Edge AI + biodegradable PLA enclosures:Converging technologies enable fully offline operation with reduced end-of-life environmental liability, aligning with EU Green Deal procurement criteria.
Industry Challenges
- Firmware security audit talent scarcity:Embedded systems engineers with child-data privacy expertise command 40% compensation premiums, constraining R&D scaling.
- Multi-regional certification timelines:Simultaneous FCC, CE, and SRRC radio approvals extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart/AI Toys Market |
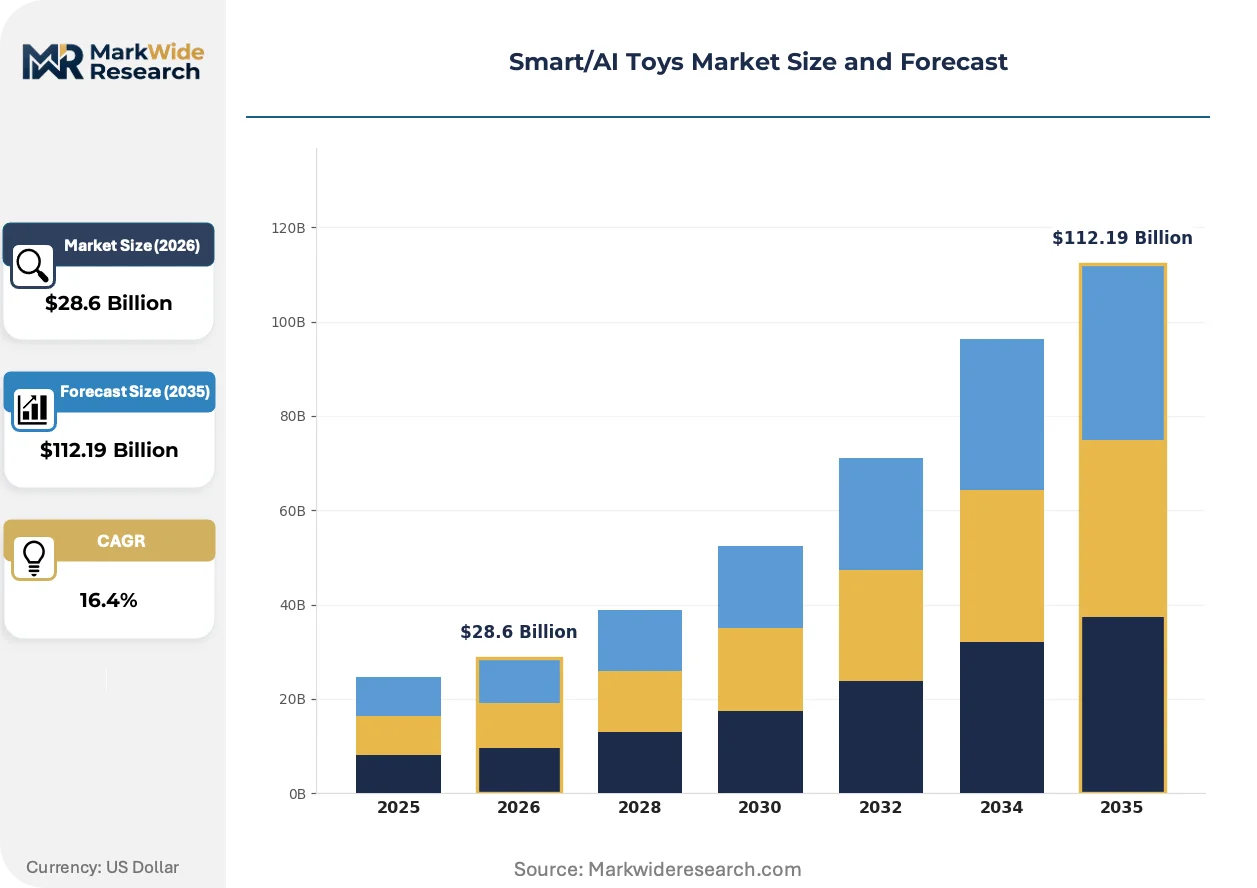
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Dolls, Learning Robots, Smart Plush Toys, Educational Games Technology: Voice Recognition, Machine Learning, Augmented Reality, IoT Connectivity End User: Parents, Educational Institutions, Therapy Providers, Childcare Facilities Age Group: Preschool, Early School Age, Preteens, Teens |
| Companies Covered | VTech Holdings Limited, Sphero, Inc., Mattel, Inc., Playmobil, UBTECH Robotics Corp., LEGO System A/S, Spin Master Corp., WowWee Group Limited, Hasbro, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart/AI Toys Market Evolving Landscape
Adaptive algorithm deployment is migrating from cloud inference to on-device processing, reducing latency and regulatory exposure while enabling offline functionality in institutional settings.
ARM Cortex-M55 neural processing units are miniaturizing sufficiently for integration in sub-100 gram plush form factors. Preschool therapy centers in Denmark and the Netherlands are piloting these chips for real-time emotional state classification. The shift is miniaturizing the hardware footprint required for personalized difficulty adjustment, collapsing the cost barrier between consumer and clinical-grade devices.
The EU AI Act's high-risk system designation for AI interacting with children is forcing voice-feature redesigns across product lines. Manufacturers must now implement local processing or obtain explicit parental consent for cloud transmission, adding engineering overhead but creating compliance-based segmentation. Learning robots with emotional response capabilities face the steepest re-certification requirements in France and Germany.
Institutional procurement through education ministry frameworks is displacing parent-driven holiday purchasing in East Asian markets. South Korea's EBS digital textbook initiative now bundles AI companion licenses with curriculum subscriptions. District-level buyers in Gyeonggi Province negotiate volume pricing that undercuts retail channels by 30-45%, compressing margin structures for brands without direct government sales teams.
Smart/AI Toys Market Segmentation
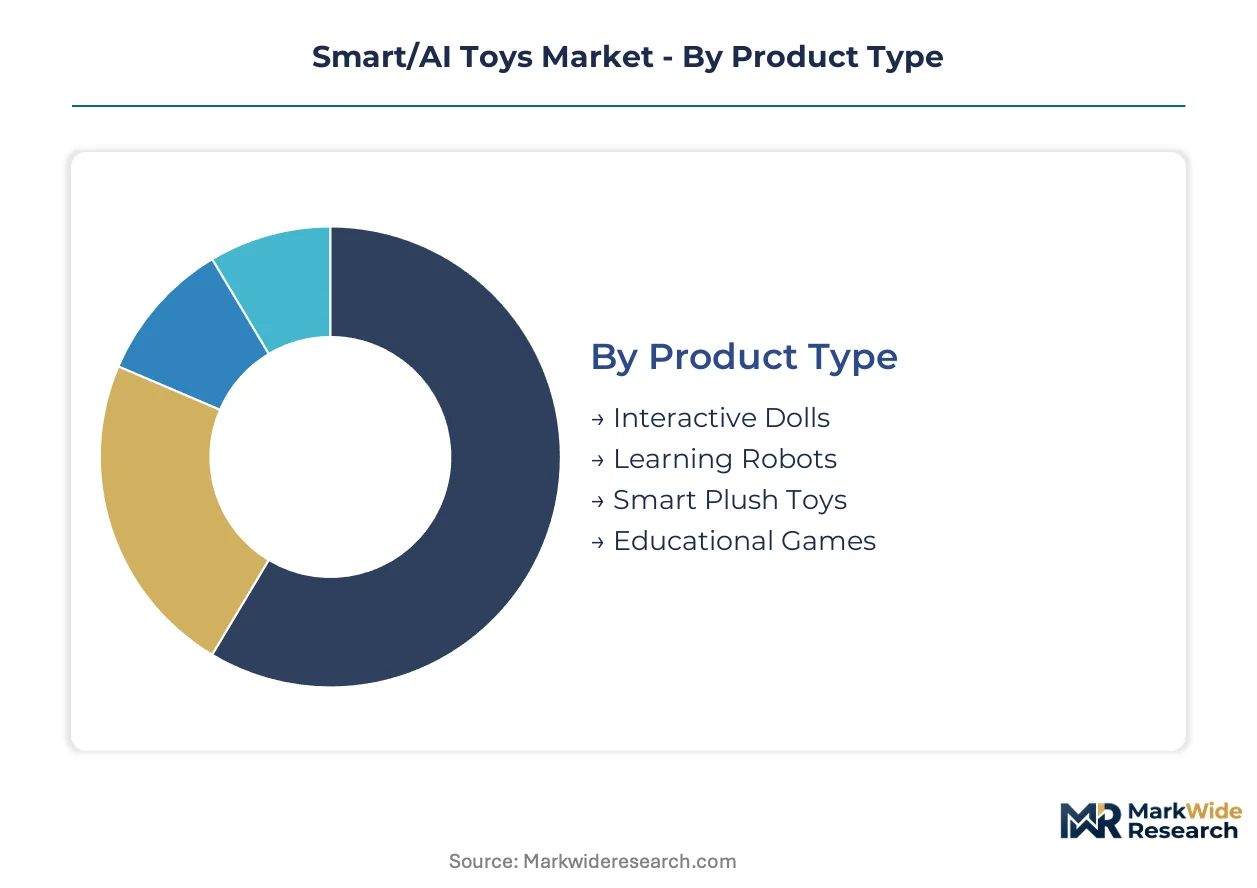
Segmentation in the Smart/AI Toys Market reveals divergent engineering requirements and procurement pathways across buyer types. Product architecture, connectivity protocols, and content licensing all shift dramatically between institutional purchasers and household consumers.
Product Type:
Learning Robots and Interactive Dolls concentrate export-led manufacturing from Shenzhen and Dongguan, while Smart Plush Toys and Educational Games retain stronger domestic production footprints in North America and Europe.
- Learning Robots:Programmable chassis integrating servo motors, time-of-flight sensors, and ARM Cortex-M55 processors enable spatial navigation and adaptive curriculum delivery. Demand concentrates in South Korean primary schools through Education Ministry procurement frameworks and in Chinese district-level STEM mandates.
- Interactive Dolls:Cloud-connected voice-interactive figures with embedded NLP engines and biometric response sensors. The FTC's COPPA enforcement and EU AI Act high-risk classification are forcing edge-computing redesigns for US and European markets.
- Smart Plush Toys:Soft-form wearables with haptic feedback and emotional state classification running on-device. Denmark and Netherlands therapy centers pilot clinical-grade deployments.
- Educational Games:Tablet-integrated or standalone board systems with AR markers and adaptive difficulty algorithms. Parental purchases dominate through retail channels.
Learning Robots commands the established base. The steepest expansion runs through Interactive Dolls as voice-feature compliance redesigns create premium pricing tiers.
Technology:
Cost tier stratification separates premium on-device inference from economy cloud-dependent architectures, with regulatory pressure accelerating the shift toward local processing.
- Machine Learning:Edge-deployed neural networks enabling personalized difficulty curves and longitudinal developmental assessment without data transmission. EU AI Act risk-classification and COPPA constraints are driving architectural migration from cloud to on-device inference across all price tiers.
- Voice Recognition:Natural language processing engines with speaker identification and emotional tone analysis. Cloud-dependent implementations face delisting pressure in France and Germany under tightened minor-interaction protocols.
- Augmented Reality:Marker-based or SLAM-enabled visual overlays for interactive storytelling and spatial reasoning exercises. Content licensing costs fragment margin structures.
- IoT Connectivity:Bluetooth 5.0 and Wi-Fi modules enabling parental monitoring dashboards and firmware updates. China's SAMR cybersecurity certification creates compliance moats for domestic manufacturers.
Voice Recognition retains the largest installed base. The steepest expansion trajectory belongs to Machine Learning as edge-computing hardware costs collapse and regulatory exposure intensifies.
End User:
Volume concentration tilts toward institutional procurement in East Asia, while North American and European markets sustain stronger household purchase patterns.
- Educational Institutions:District-level buyers in Gyeonggi Province and Shanghai negotiate volume pricing 30-45% below retail through ministry framework agreements. STEM curriculum mandates institutionalize procurement channels that bypass traditional toy retail.
- Parents:Holiday-driven purchasing concentrated in Q4, with premium sensitivity shaped by tablet and gaming console substitution effects. COPPA compliance labeling influences brand selection.
- Therapy Providers:FDA and CE-marked adaptive companions for autism intervention and speech therapy command reimbursement-linked pricing in US and German clinical settings.
- Childcare Facilities:Bulk procurement of durable, sanitizable form factors with offline functionality requirements. EU Green Deal procurement criteria favor biodegradable enclosure materials.
Parents command the established base. The steepest expansion runs through Educational Institutions as ministry-level frameworks displace retail channels.
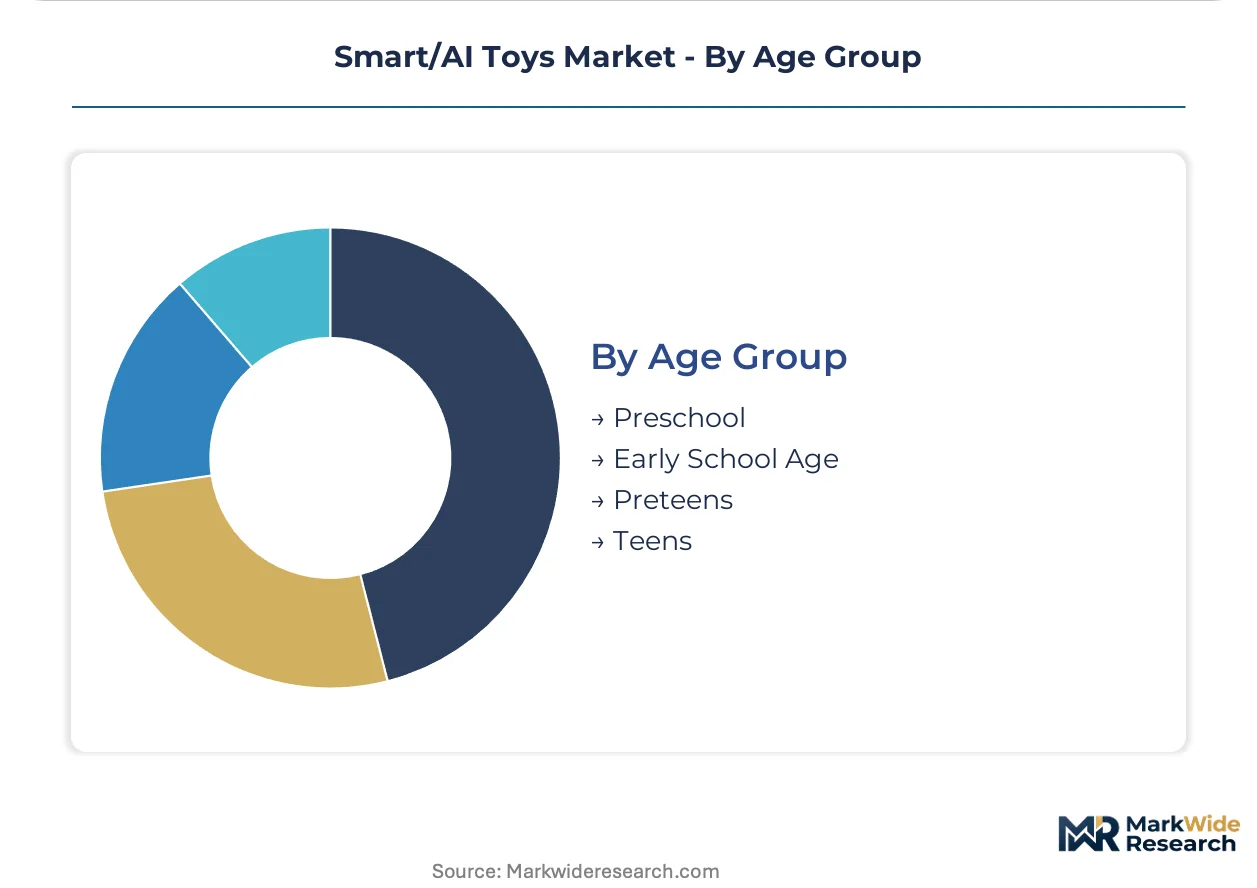
Age Group:
Application maturity separates preschool segments with established clinical validation from preteen categories still negotiating content relevance against gaming platforms.
- Preschool:ARM Cortex-M55 neural processing units now miniaturize for sub-100 gram plush form factors with real-time emotional state classification. Denmark and Netherlands therapy centers pilot clinical-grade deployments.
- Early School Age:Programmable robotics curricula aligned with K-12 computer science standards. South Korea's EBS digital textbook initiative bundles AI companion licenses with subscription models.
- Preteens:STEM skill-building platforms competing directly with tablet-based entertainment. Price elasticity constraints limit premium positioning.
- Teens:Advanced coding and robotics kits with open-source extensibility. Niche volume concentrated in competitive robotics leagues and maker communities.
Early School Age commands the established base. The steepest expansion runs through Preschool as edge-AI hardware miniaturization collapses cost barriers between consumer and clinical-grade devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen-Dongguan manufacturing corridor anchors Asia-Pacific production capacity for servo motors and ARM Cortex processors. Rotterdam's port infrastructure handles EU import consolidation for connected children's products. The Panama Canal expansion underwrites Americas distribution efficiency for lithium-polymer supply chains.
United States
FTC COPPA enforcement drives architectural redesigns of cloud-dependent voice features for minors under thirteen. District-level procurement in Gyeonggi Province-style frameworks is emerging through California and Texas education technology pilots. Clinical validation centers in Boston and San Francisco anchor FDA-marked adaptive companion development for autism intervention.
China
SAMR cybersecurity certification and GB standards mandate pre-market testing for connected children's products. Yangtze River Delta cities concentrate servo motor production with rare-earth processing dependencies. Shanghai district buyers negotiate volume pricing through ministry framework agreements that bypass traditional retail channels.
Germany
EU AI Act high-risk system designation forces voice-feature redesigns for AI interacting with children. ANSM and BfArM oversight shapes CE-marked therapeutic device pathways for clinical-grade deployments. Berlin-Brandenburg clusters host edge-AI firmware development for emotional state classification in preschool therapy applications.
South Korea
EBS digital textbook initiative bundles AI companion licenses with curriculum subscriptions through Education Ministry frameworks. Seoul Capital Area manufacturers supply ARM Cortex-M55 neural processing units for sub-100 gram plush form factors. Gyeonggi Province institutional procurement undercuts retail channels by 30-45% through volume pricing negotiations.
Netherlands
GDPR and EU AI Act convergence creates dual compliance requirements for cloud-connected play products. Randstad logistics hubs distribute biodegradable PLA enclosure materials aligned with EU Green Deal procurement criteria. Amsterdam and Rotterdam therapy centers pilot clinical-grade edge-AI deployments for real-time emotional state classification.
Smart/AI Toys Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D velocity dimensions. The vendor base stratifies into three tiers: multinational toy conglomerates with retail shelf leverage, robotics specialists with captive component production, and programmable curriculum developers with education ministry relationships. Competitive positioning hinges on compliance-first product architecture and direct government sales team deployment.
Within the conglomerate tier, Mattel, Inc. and Hasbro, Inc. occupy positions defined by established retail network access. Among robotics specialists, UBTECH Robotics Corp. exemplifies vertical integration through in-house servo motor production. Sphero, Inc. represents the curriculum-aligned archetype with K-12 computer science standard integration. Each anchors distinct competitive vectors: shelf space, component autonomy, and institutional procurement pathways respectively.
| Leading Market Players |
|---|
| VTech Holdings Limited |
| Sphero, Inc. |
| Mattel, Inc. |
| Playmobil |
| UBTECH Robotics Corp. |
| LEGO System A/S |
| Spin Master Corp. |
| WowWee Group Limited |
| Hasbro, Inc. |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month certification timelines for multi-regional launches concentrate inventory carrying costs among tier-one manufacturers while compressing pricing power for late entrants lacking direct ministry sales relationships in East Asia.
Pricing Analysis
Volume-discount tiering separates institutional procurement through Gyeonggi Province-style frameworks from household retail purchases. Pricing stratifies across premium, standard, and economy tiers based on certification grade and edge-AI processing capability. Cost compression in mid-tier learning robots is intensifying because South Korean education ministry bundling undercuts retail channels. Parents remain most price-sensitive versus therapy providers commanding reimbursement-linked premiums.
Supply Chain Analysis
China anchors servo motor production with rare-earth processing dependencies while South Korea supplies ARM Cortex-M55 neural processing units. Component sourcing draws from lithium-polymer cells in the Yangtze River Delta and time-of-flight sensors from Shenzhen-Dongguan corridors. Single-source vulnerability in neodymium magnet supply exposes margins to export quota volatility. Distribution runs through Rotterdam port consolidation for EU markets and Panama Canal routing for Americas lithium-polymer supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as district-level education ministries in South Korea and China disaggregate parent-driven holiday purchasing into consolidated framework agreements.
For Market Incumbents: Shield market position by deepening in-house production of servo motors and proprietary motion-control chipsets to offset rare-earth supply volatility. Invest in SAMR cybersecurity certification infrastructure to create compliance moats against emerging domestic Chinese competitors. Prioritize direct government sales team deployment over retail channel expansion. For New Entrants and Emerging Players: Anchor in speech therapy and autism intervention centers in the United States and Germany where FDA and CE-marked adaptive companions command reimbursement-linked pricing. Target clinical-grade edge-AI deployments for preschool emotional state classification where hardware miniaturization has collapsed cost barriers. Pursue institutional validation partnerships before retail distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge-AI firmware development as EU AI Act compliance forces architectural redesigns. Long-term viability favors firms with modular compliance architecture spanning COPPA, EU AI Act, and SAMR requirements. Watch for delisting waves in France and Germany as indicators of compliance-based consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Architecture Migration | Reduces COPPA and EU AI Act regulatory exposure while enabling offline institutional functionality. |
| Ministry Framework Direct Sales | Bypasses retail margin compression in South Korea's EBS digital textbook bundling ecosystem. |
| SAMR Certification Infrastructure | Creates compliance moat for China market access against non-domestic testing capabilities. |
| Clinical Validation Partnerships | Unlocks reimbursement-linked pricing in FDA and BfArM therapeutic device pathways. |
| Biodegradable Enclosure Transition | Aligns with EU Green Deal procurement criteria for childcare facility bulk purchasing. |
Research Methodology
Operator-level perspectives from education ministry procurement officers, robotics curriculum developers, embedded systems engineers, and therapy center clinical directors anchored the qualitative base. Secondary validation drew from SAMR certification databases, FTC COPPA enforcement records, EU AI Act implementation guidance, and South Korean EBS initiative documentation. Bottom-up segment sizing triangulated with top-down macroeconomic anchors across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory timeline slippage and rare-earth supply disruption scenarios. The modeling framework segmented by product type, technology architecture, end-user procurement channel, and age-group application maturity. CAGRs derived from longitudinal interaction data monetization trajectories and institutional subscription conversion rates.
Material uncertainties — firmware security audit talent scarcity, multi-regional certification timeline extensions, and screen-based entertainment substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about edge-AI hardware cost collapse and ministry procurement framework expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Global Blind Boxes Market
Toys and Games
Model Train Market
Toys and Games
Animation Toys Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Baby Toys Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Games and Puzzles Market
Toys and Games
Bubble Tubes Market
Toys and Games
Sustainable Toys Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Connected Toys Market
Toys and Games
Bounce House Market
Toys and Games
Bath Toy Market
Toys and Games
Drone for Kids Market