

Orbital Action Jigsaw Market Size, Share, and Industry Trends Forecast 2026-2036
Orbital Action Jigsaw Market Insights
A shift from single-source motor procurement to multi-source supplier strategies is repositioning how manufacturers secure brushless motor assemblies. Bosch leverages captive production networks to sustain margin control across European distribution channels. Makita competes through geographic dominance in Asia-Pacific professional channels. Festool differentiates via precision-focused product specialization that commands premium positioning in German carpentry workshops.
An orbital action jigsaw is a reciprocating power tool whose blade moves in an elliptical orbital pattern during the cutting stroke, typically achieving stroke rates between 500 and 3,000 SPM depending on material density. This orbital mechanism reduces blade wear and accelerates cutting speed in wood and composite materials compared to straight reciprocating motion. The cordless product category captures the fastest expansion as lithium-ion battery platforms mature, while brushless motor technology concentrates margin pools through reduced maintenance demands and extended duty cycles. Woodworking applications anchor volume demand, though composite fabrication represents an emerging growth corridor driven by marine and aerospace material processing needs.
The Occupational Safety and Health Administration enforces permissible exposure limits for respirable crystalline dust that directly shape dust blower integration and extraction port design requirements in the United States. CE marking under the EU Machinery Directive governs vibration emission thresholds and electrical safety standards that determine market access across European member states. Stakeholders must monitor evolving battery transportation regulations and carbon footprint disclosure frameworks that will increasingly influence cordless platform investment decisions and supplier qualification criteria.
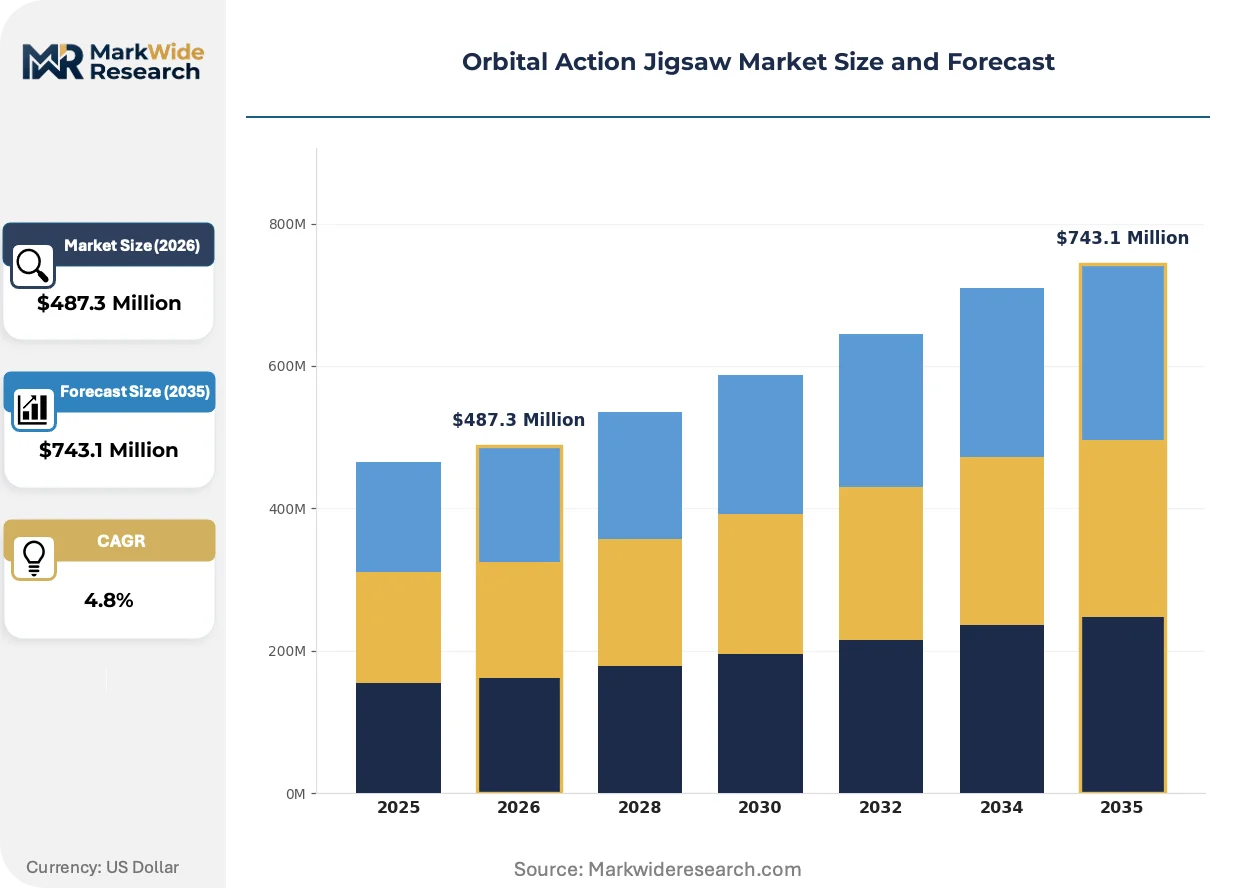
Market Dynamics
Brushless motor technology is compressing maintenance cycles and extending duty ratings, forcing manufacturers to reconfigure supplier relationships and captive production investments. This shift is redistributing margin pools across cordless platform ecosystems while reshaping how professional trades evaluate total cost of ownership.
Growth Catalysts
- OSHA Permissible Exposure Limits:Stricter respirable crystalline dust thresholds in the United States mandate integrated dust blower systems and extraction port designs, accelerating equipment replacement cycles among professional contractors.
- Composite Fabrication:Marine and aerospace material processing requirements are expanding addressable demand beyond traditional woodworking into specialized cutting applications requiring precision orbital mechanics.
- Lithium-Ion Platform Maturation:Battery chemistry advances are enabling cordless units to match corded performance specifications, unlocking jobsite flexibility for renovation and installation trades.
Market Restraints
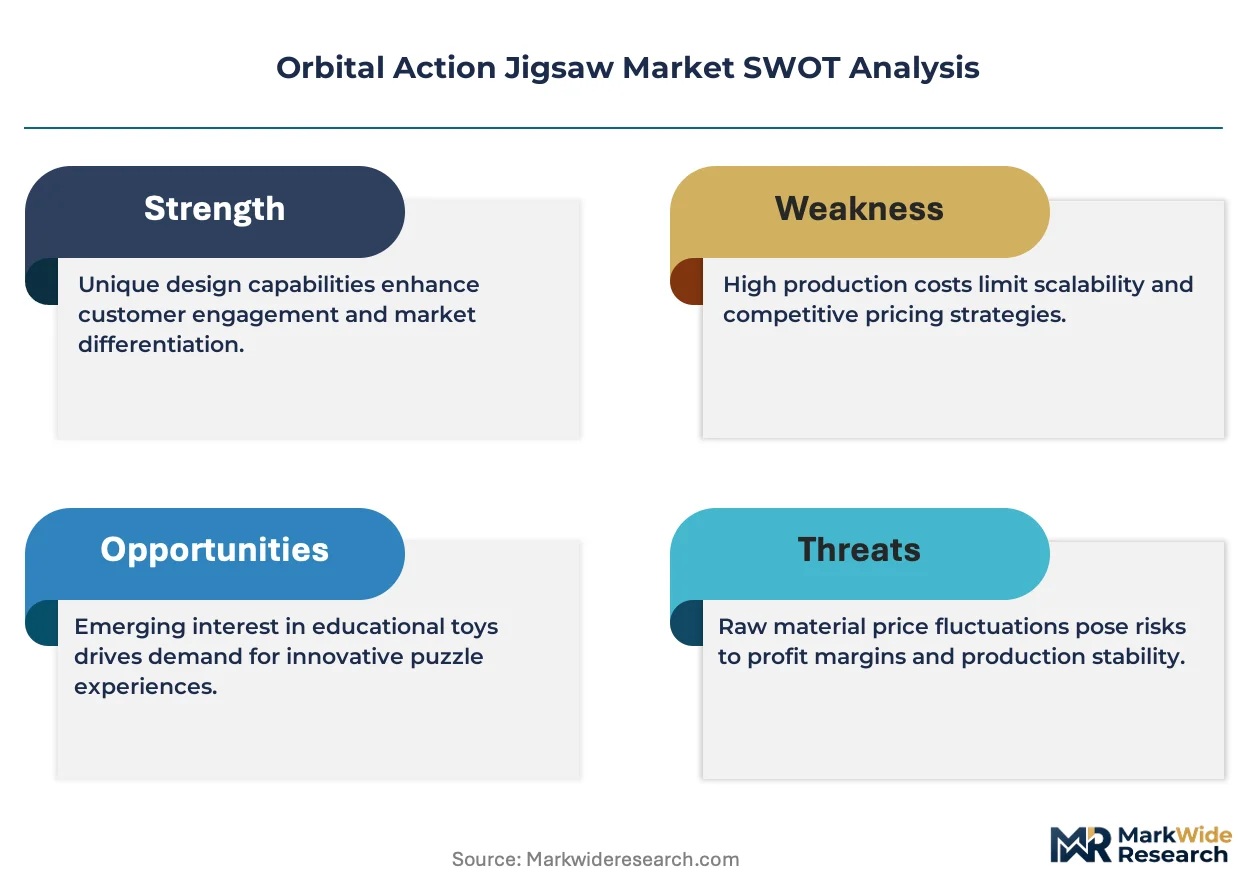
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium sourcing dependence on concentrated overseas refining capacity creates input cost volatility and qualification timeline risk for brushless motor assembly.
- CE Marking Vibration Thresholds:EU Machinery Directive emission limits require redesign of counterbalance mechanisms, adding engineering validation costs that compress margins on standard-tier product lines.
- Fixed-Base Band Saw Substitution:Workshop environments with dedicated cutting stations favor stationary equipment for repetitive straight cuts, limiting orbital jigsaw penetration in high-volume production settings.
Strategic Opportunities
- Underpenetrated German Craft Workshop Segment:Precision-focused carpentry cooperatives represent premium positioning potential for specialized orbital mechanisms with enhanced blade guidance systems.
- Battery Transportation Regulation Harmonization:UN 38.3 testing standard alignment across jurisdictions reduces platform certification duplication, enabling faster geographic expansion of cordless product lines.
- Smart Tool Ecosystem Convergence:Integration of torque feedback sensors with Bluetooth-enabled inventory management systems creates service-revenue attachment opportunities for fleet operators.
Industry Challenges
- Brushless Motor Controller Firmware Development:Embedded systems engineering talent scarcity extends product validation timelines and increases recruitment costs for mid-tier manufacturers.
- Multi-Jurisdictional Certification Parallel Processing:Simultaneous UL, CE, and GB standard compliance requires dedicated regulatory affairs capacity that strains smaller competitor resources.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orbital Action Jigsaw Market Trends and Innovations
Equipment specification is pivoting toward connected functionality and emissions compliance, compressing development cycles while fragmenting buyer requirements across professional and industrial segments. This evolution favors suppliers with modular platform architectures and captive regulatory expertise.
Brushless motor technology is consolidating performance-tier boundaries by delivering corded-equivalent cutting speed in cordless form factors. Professional renovation contractors in Germany and the United States are adopting these platforms at replacement-cycle velocity. The technology is consolidating supplier power toward motor-controller integrated manufacturers and away from discrete component assemblers.
EU Machinery Directive vibration emission thresholds are mandating redesigned counterbalance systems and isolation mounting configurations. Equipment manufacturers face extended type-testing timelines and third-party validation costs to maintain CE marking access. German and Austrian professional channels are responding by prioritizing low-vibration certified units in fleet procurement specifications.
After-sales service unbundling is fragmenting traditional distributor value capture. Independent repair networks and direct-to-user parts portals are displacing authorized service dependencies for brush replacement and switch module failures. This pattern is most visible in United States construction trades where tool fleet operators internalize maintenance capabilities to minimize downtime exposure.
Orbital Action Jigsaw Market Segmentation
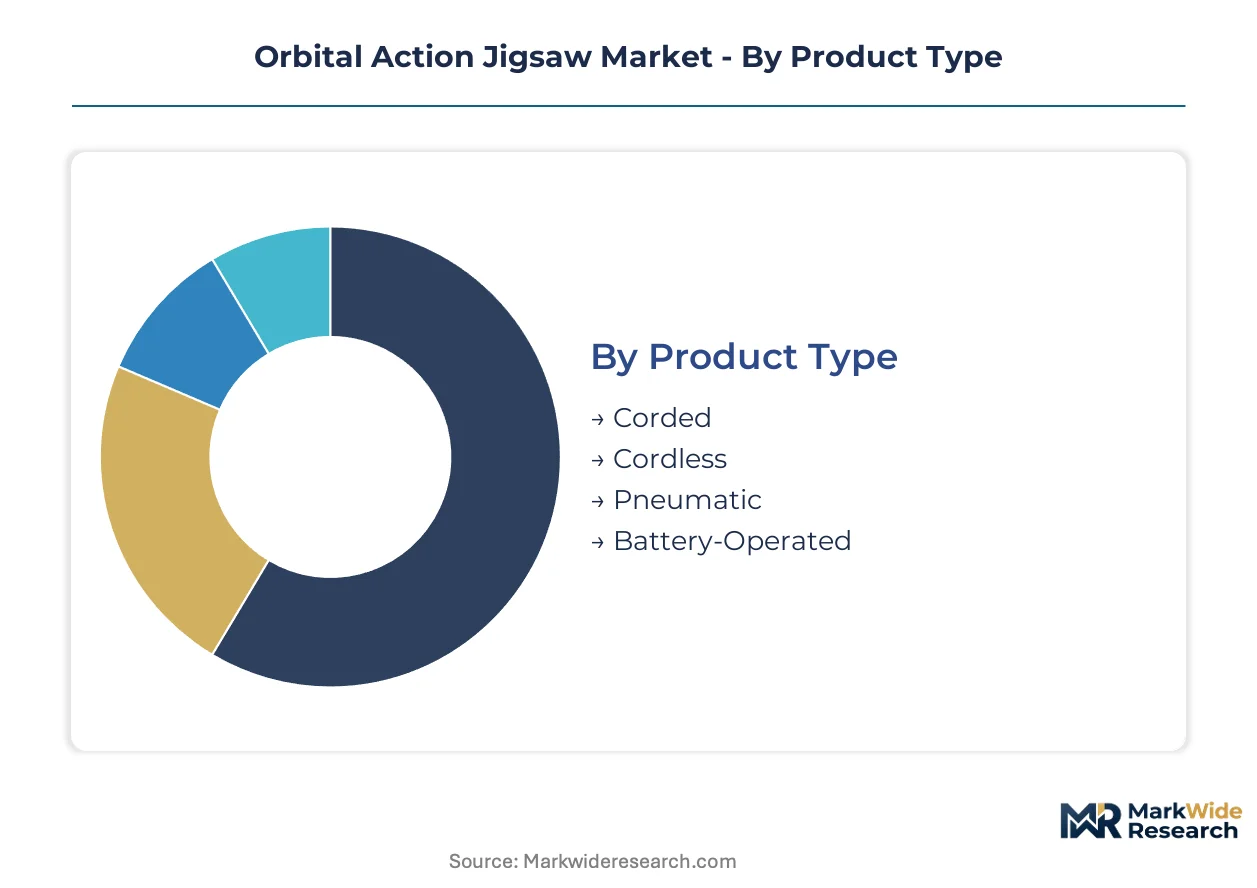
Equipment replacement cycles and technology migration patterns reshape how manufacturers prioritize platform investments across orbital action jigsaw categories. Segmentation reveals divergent margin structures between cordless expansion and pneumatic stability in professional channels.
Product Type:
Upgrade momentum from corded legacy units to cordless platforms concentrates procurement decisions around battery ecosystem compatibility and total cost of ownership calculations.
- Corded:Continuous power delivery suits stationary workshop environments where uninterrupted duty cycles outweigh portability requirements. German carpentry cooperatives and US construction firms sustain replacement demand for high-amperage units in fixed cutting stations.
- Cordless:Lithium-ion platform maturation enables stroke rates matching corded specifications while unlocking jobsite mobility for renovation contractors. Battery chemistry advances and brushless motor integration are compressing performance gaps fastest in this category.
- Pneumatic:Compressed-air operation eliminates electrical hazard exposure in wet marine fabrication environments.
- Battery-Operated:Lower-voltage platforms serve hobbyist price sensitivity with reduced duty ratings.
Corded units sit at the top of the volume ranking, with cordless climbing the fastest.
Technology:
Cost tier stratification separates premium-feature integration from baseline functionality, with firmware-enabled capabilities commanding supplier power consolidation.
- Brushless Motor:Eliminated brush friction extends duty cycles and reduces thermal degradation in sustained cutting operations. Professional trades in China and Germany are prioritizing these units at replacement velocity due to maintenance interval compression.
- Variable Speed:Dial-based or electronic stroke rate adjustment enables material-specific optimization from 500 SPM in metals to 3,000 SPM in softwoods. Metal cutting specialists and composite fabricators drive specification requirements here.
- Keyless Blade Change:Tool-free blade swap mechanisms minimize downtime exposure in multi-material job environments.
- Laser Guide:Line-projected cutting path alignment addresses precision demands in furniture manufacturing.
- Dust Blower:Integrated debris clearance satisfies OSHA respirable crystalline dust exposure mandates in US professional channels.
Brushless motor technology anchors the premium tier by margin, with dust blower integration expanding most quickly on regulatory compulsion.
Application:
Volume concentration in mature woodworking segments contrasts with margin expansion potential in specialized material processing requiring precision orbital mechanics.
- Woodworking:Curved and beveled cutting in hardwoods, softwoods, and engineered lumber products constitutes the foundational demand base. German and US professional workshops sustain replacement cycles through precision-focused equipment specifications.
- Composite Fabrication:Marine hull construction and aerospace component trimming require specialized blade geometries and reduced vibration profiles. This application is gaining share fastest on carbon-fiber and fiberglass processing expansion.
- Metal Cutting:Thin-gauge steel and aluminum trimming in HVAC installation and electrical enclosure fabrication.
- Plastic Shaping:Thermoplastic and acrylic cutting in signage and display manufacturing.
- Ceramic Trimming:Tile and stone edge finishing in residential renovation applications.
Woodworking sits at the top of the volume ranking, with composite fabrication climbing the fastest.
End User:
Customer type determines pricing tolerance, service expectation, and platform ecosystem lock-in intensity across procurement channels.
- Carpentry Workshops:German precision-focused cooperatives and US custom cabinetry operations demand low-vibration certification and extended warranty terms. These users prioritize blade guidance accuracy and dust extraction integration over initial acquisition cost.
- Construction Firms:Fleet operators in United States commercial renovation internalize maintenance capabilities and standardize on single-battery platforms to minimize downtime exposure. Procurement concentrates on durability certification and parts availability.
- Furniture Manufacturers:High-volume production environments with dedicated cutting stations favor equipment redundancy and service-response guarantees.
- Hobbyists:Price-sensitive occasional users drive entry-level cordless and corded volume through retail channels.
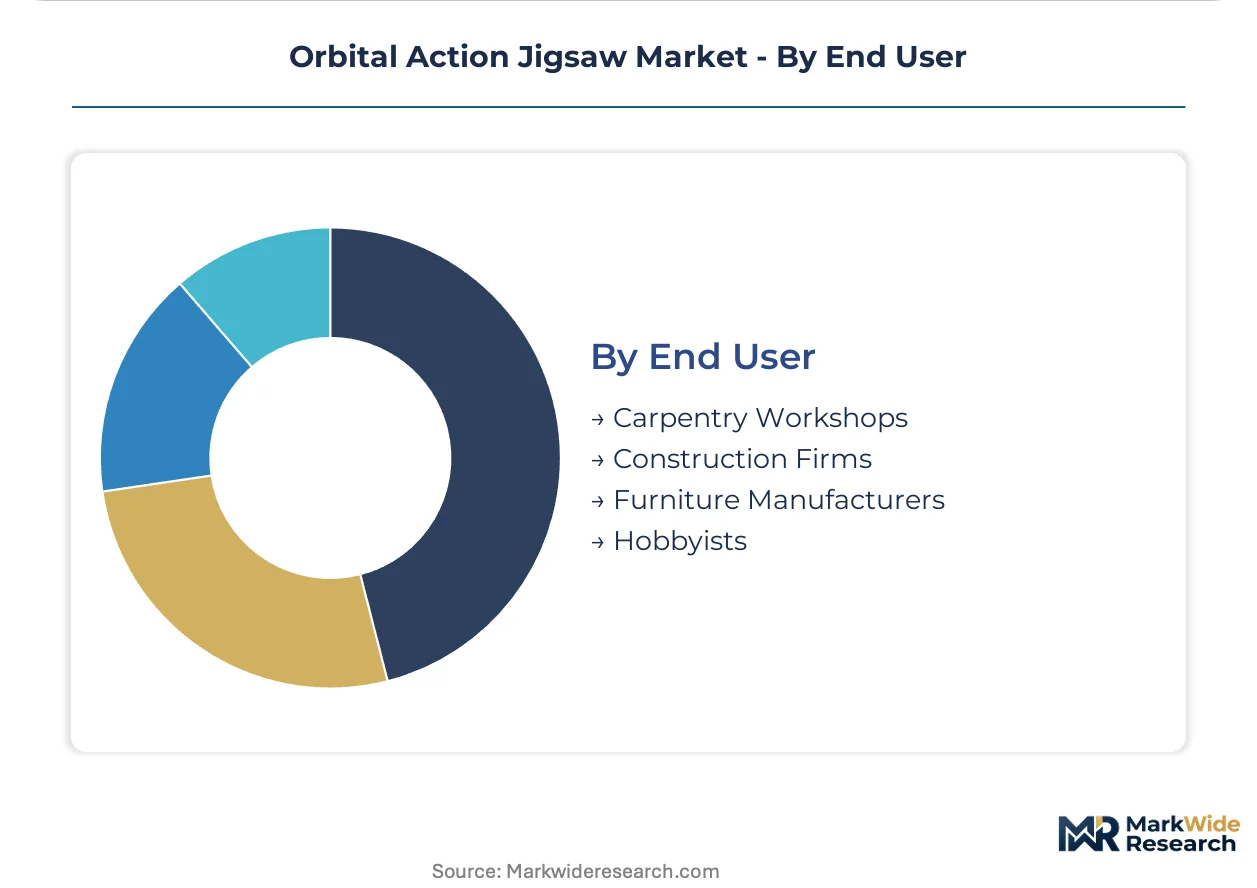
Construction firms sit at the top of the volume ranking, with carpentry workshops climbing the fastest on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German carpentry cooperatives anchor professional-grade demand through precision-focused procurement specifications and extended replacement cycles. OSHA dust exposure mandates in the United States accelerate equipment turnover among renovation contractors. Chinese manufacturing clusters supply motor assemblies and blade systems to global OEM networks.
United States
Construction fleet operators drive cordless platform adoption through battery ecosystem standardization across commercial renovation sites. OSHA permissible exposure limits for respirable crystalline dust mandate integrated dust blower systems and extraction port configurations. Chicago and Dallas-Fort Worth metropolitan areas concentrate contractor procurement decisions for high-amperage corded units in fixed cutting stations.
Germany
Precision carpentry workshops prioritize low-vibration certification and blade guidance accuracy in equipment specifications. CE marking under the EU Machinery Directive governs vibration emission thresholds and electrical safety standards for market access. Stuttgart and Munich industrial corridors host specialized distributors serving custom cabinetry operations with premium-tier orbital mechanisms.
China
Domestic brushless motor production scales to serve both local OEM assembly and export component demand. GB standards and MIIT regulations shape product certification requirements for cordless platform distribution. Yangtze River Delta manufacturing clusters concentrate lithium-ion battery pack assembly and motor controller firmware development capacity.
Japan
Professional trades emphasize compact form factors and reduced vibration profiles for precision finishing applications. METI industrial standards and JIS certification requirements influence product development timelines for domestic and export markets. Osaka-Kobe manufacturing belt maintains specialized machining capabilities for high-precision blade guidance systems.
United Kingdom
Independent contractor segments favor mid-tier cordless platforms with multi-material cutting versatility. CE marking alignment post-Brexit transition maintains regulatory continuity with EU Machinery Directive requirements. Midlands manufacturing region sustains aftermarket parts distribution and independent repair network density for fleet operators.
Orbital Action Jigsaw Market Competitive Landscape
Global majors compete with regional champions across motor technology integration and distribution channel depth. The vendor base separates into three tiers: vertically integrated motor producers, platform ecosystem specialists, and component-focused assemblers. Consolidation pressure concentrates among brushless motor controller developers and lithium-ion battery platform architects. Dominant competitive moves include captive production investments in rare earth magnet supply chains and strategic partnerships with professional trade associations for specification influence.
Within the vertically integrated tier, Bosch and Makita exemplify archetypes of captive motor production networks and geographic channel dominance respectively. Festool occupies a position representing precision-focused specialization for premium workshop segments. Stanley Black & Decker anchors the scale-driven end through multi-brand portfolio architecture spanning professional and consumer price tiers. These three company structures illustrate how supplier power concentrates toward integrated motor-controller manufacturers and away from discrete component assemblers.
| Leading Market Players |
|---|
| Bosch |
| Stanley Black & Decker |
| Makita |
| Techtronic Industries |
| Festool |
| Metabo |
| Hilti |
| Hikoki Power Tools |
| Skil |
| Others |
Pricing and Supply Chain Analysis
Family-owned German mid-cap specialists anchor premium-tier pricing discipline through captive blade guidance system production and direct distribution to Stuttgart carpentry cooperatives. Their ownership structure insulates margin pools from quarterly earnings pressure while enabling long-term counterbalance R&D investment that OEM assemblers cannot match.
Pricing Analysis
Neodymium and dysprosium cost pass-through from concentrated overseas refining capacity is compressing margins on brushless motor tiers fastest. Three-tier pricing structure across premium, standard, and economy levels separates Festool-positioned units with CE vibration certification from unbranded Asian imports. Pricing pressure stems from lithium-ion cell commodity volatility and firmware development talent scarcity. Hobbyist retail channels exhibit highest price sensitivity; German precision carpentry workshops demonstrate lowest sensitivity due to total cost of ownership calculations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns serving construction fleet operators with 48-hour parts availability guarantees. Motor assembly concentrates in China, Germany, and Japan; rare earth magnet processing feeds from concentrated overseas refining capacity. Supply chain risk centers on single-source vulnerability for neodymium-dysprosium alloys and UN 38.3 battery transportation certification delays. Distribution runs through authorized industrial distributors in professional channels and big-box retail for hobbyist segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA respirable crystalline dust exposure mandates function as a regulatory compounder, accelerating replacement cycles among US renovation contractors and embedding dust blower integration as a non-negotiable specification.
For Market Incumbents: Hedge against rare earth supply concentration by qualifying secondary magnet suppliers in Australia and developing iron-nitride motor architectures as brushless alternatives. Defend margin position through captive production of vibration-isolation counterbalance systems that mid-tier assemblers cannot source externally. Priority lever: CE marking regulatory affairs capacity expansion to compress type-testing timelines. For New Entrants and Emerging Players: Launch via direct-to-user parts portals targeting US construction fleet operators who have internalized maintenance capabilities. White-space targets include underpenetrated German craft workshop segments demanding precision-focused orbital mechanisms, and marine composite fabrication yards in Pacific Northwest requiring pneumatic configurations. Go-to-market angle: Bluetooth-enabled inventory management system bundling with torque feedback sensors. For Investors and Strategic Acquirers: Valuations sit cheapest among brushless motor controller firmware developers with embedded systems engineering talent pipelines. Long-term viability favors suppliers with modular platform architectures spanning cordless, corded, and pneumatic form factors. Signal to watch: harmonization of UN 38.3 testing standards across jurisdictions as inflection indicator for cordless platform geographic expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Qualification | Secondary sourcing from Australian refining capacity reduces neodymium-dysprosium exposure to concentrated overseas supply. |
| Firmware Development Talent Acquisition | Embedded systems engineering pipelines compress brushless motor controller validation timelines for mid-tier manufacturers. |
| CE Marking Regulatory Affairs Expansion | Dedicated EU Machinery Directive compliance capacity accelerates vibration emission threshold certification access. |
| Bluetooth Ecosystem Integration | Torque feedback sensor connectivity creates service-revenue attachment opportunities for fleet operators. |
| Marine Composite Fabrication Partnership | Pneumatic platform specialization captures aerospace and hull construction material processing demand. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with maintenance directors at construction firms, procurement leads at German carpentry cooperatives, OEM motor assembly plant managers, and aftermarket service heads at industrial distributors. Secondary validation draws from OSHA enforcement databases, EU Machinery Directive type-testing registries, customs trade data for rare earth magnet flows, and SEC filings from listed power tool manufacturers. Bottom-up unit shipment estimates triangulate against top-down equipment replacement cycle modeling.
Rate-of-change decomposition separates volume expansion from mix-shift effects across the projection horizon. Segmentation dimensions modeled include product type, motor technology tier, application material, and end-user procurement channel. CAGRs derive from equipment replacement velocity analysis and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporate lithium-ion platform maturation curves and brushless motor duty rating improvements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios or accelerated EU vibration threshold tightening. Forecasts reflect assumptions about professional trade replacement cycle stability and cordless platform performance convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.