
 Dildo Sex Toy Market | 2026-2036
Dildo Sex Toy Market Size, Share, and Industry Trends Forecast 2026-2036
Dildo Sex Toy Market Insights
Online retail purchasing among millennial and Gen Z consumers is consolidating, shifting volume away from brick-and-mortar adult stores toward direct-to-consumer platforms. Lelo leverages Scandinavian design credentials to command premium positioning in European and North American e-commerce channels. Doc Johnson anchors its competitive stance through decades of manufacturing scale and broad SKU coverage across multiple price tiers. Shenzhen Hejiamei Technology Co., Ltd competes aggressively on cost-engineered silicone production, supplying private-label programs for Western distributors.
A dildo is a non-vibrating or vibrating penetrative device, typically molded from medical-grade silicone, borosilicate glass, or thermoplastic elastomers, designed for sexual stimulation through manual or harness-assisted insertion. Silicone formulations dominate premium manufacturing due to hypoallergenic properties and compatibility with autoclave sterilization protocols. Realistic product styling captures sustained volume in mainstream retail, while vibrating variants command higher margin pools through integrated motor technology and app-connectivity features. The LGBTQ+ target audience segment represents the fastest-growing demand category, driven by inclusive marketing and gender-affirming product development.
FDA oversight of medical device classifications and EU REACH chemical compliance frameworks govern material safety standards, restricting phthalate content and mandating biocompatibility testing for intimate contact applications. The EU AI Act and GDPR indirectly shape smart-connected product development by limiting data collection from app-enabled devices. Stakeholders must monitor evolving chemical disclosure requirements in California's Proposition 65 and Germany's BfR recommendations, as regulatory fragmentation between jurisdictions complicates unified product certification strategies.
Market Dynamics
Millennial and Gen Z purchasing consolidation through direct-to-consumer platforms is restructuring channel economics and forcing legacy adult retail networks to reposition toward experiential services or exit entirely.
Growth Catalysts
- EU REACH chemical compliance:Mandatory phthalate restrictions and biocompatibility testing protocols are filtering substandard manufacturers from Western supply chains, creating certification-based competitive moats for compliant producers.
- Medical-grade silicone formulations:Hypoallergenic properties and autoclave sterilization compatibility are elevating material standards across premium and mid-tier product lines, expanding clinical-adjacent positioning.
- Germany:Erosion of cultural stigma combined with strong BfR safety recommendations is establishing the country as the EU's highest per-capita demand concentration for premium intimate products.
Market Restraints
- Raw material concentration:Medical-grade silicone supply chains cluster among specialized German and Japanese chemical suppliers, exposing manufacturers to input bottlenecks during polymer shortages.
- FDA medical device classification ambiguity:Uncertain regulatory boundaries between wellness products and medical devices create compliance cost uncertainty for vibrating and therapeutic-positioned SKUs.
- Glass and metal substitutes:Borosilicate glass and surgical steel alternatives capture price-sensitive segments with lower production complexity and minimal motor failure risk.
Strategic Opportunities
- Japan:Underdeveloped direct-to-consumer penetration relative to per-capita purchasing power presents whitespace for localized e-commerce platforms with discrete logistics partnerships.
- EU AI Act data governance:Restrictions on app-enabled device data collection create first-mover advantage for manufacturers investing in edge-computing architectures that process biometric feedback locally.
- Gender-affirming product development:Specialized form factors and inclusive marketing frameworks are unlocking LGBTQ+ segment demand at premium price positioning with lower price elasticity.
Industry Challenges
- Biocompatibility certification timelines:Extended testing protocols for new silicone formulations and colorant additives delay product launch cycles and compress seasonal revenue windows.
- Cross-border fulfillment complexity:Customs classification inconsistencies for intimate products between the United States, Germany, and Japan generate inventory detention risk and customer service overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dildo Sex Toy Market |
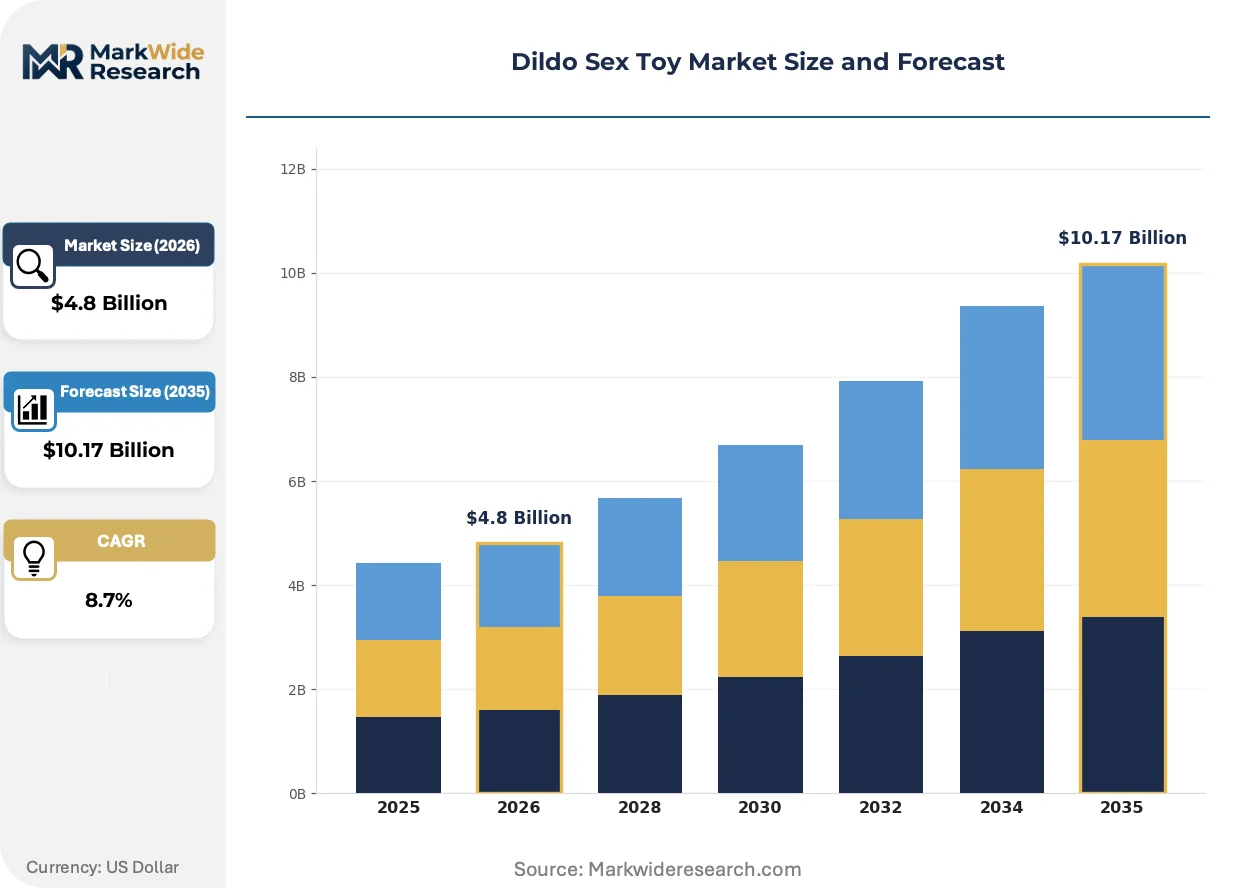
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Realistic, Vibrating, Double Ended, Strap-On Material: Silicone, Glass, Rubber, PVC Color: Red, Black, Flesh, Blue Target Audience: Women, Men, Couples, LGBTQ+ |
| Companies Covered | Lelo, Pipedream, Doc Johnson, Fleshlight, California Exotic, Lovehoney, Tantus, Shenzhen Hejiamei Technology Co., Ltd, Fun Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dildo Sex Toy Market Trends and Innovations
Connected device architectures and material science advances are compressing product lifecycles while regulatory disclosure requirements reshape competitive differentiation around verified safety credentials rather than marketing claims.
App-integrated haptic feedback systems are automating personalized stimulation pattern generation through machine-learning interpretation of biometric response data. Premium buyers in North American and German markets are adopting these connected SKUs at rates outpacing conventional vibrating products by significant margins. This automation of individual preference mapping is compressing brand loyalty cycles as users migrate between platforms based on algorithm sophistication rather than hardware durability.
California Proposition 65 chemical disclosure mandates are forcing reformulation of legacy thermoplastic elastomer compounds to eliminate flagged phthalate plasticizers. Manufacturers serving the United States market are accelerating supply chain audits and supplier qualification processes to preempt litigation exposure. The regulation is most acutely affecting economy-tier product lines that historically relied on cost-optimized material specifications.
Discrete subscription replenishment models for consumable accessories and hygiene products are displacing transactional retail purchasing among urban millennial consumers. Direct-to-consumer platforms in Germany and the United States are bundling device sales with recurring lubricant and cleaning supply deliveries to capture lifetime value. This shift is most visible in metropolitan markets where physical retail access remains stigmatized or geographically constrained.
Dildo Sex Toy Market Segmentation
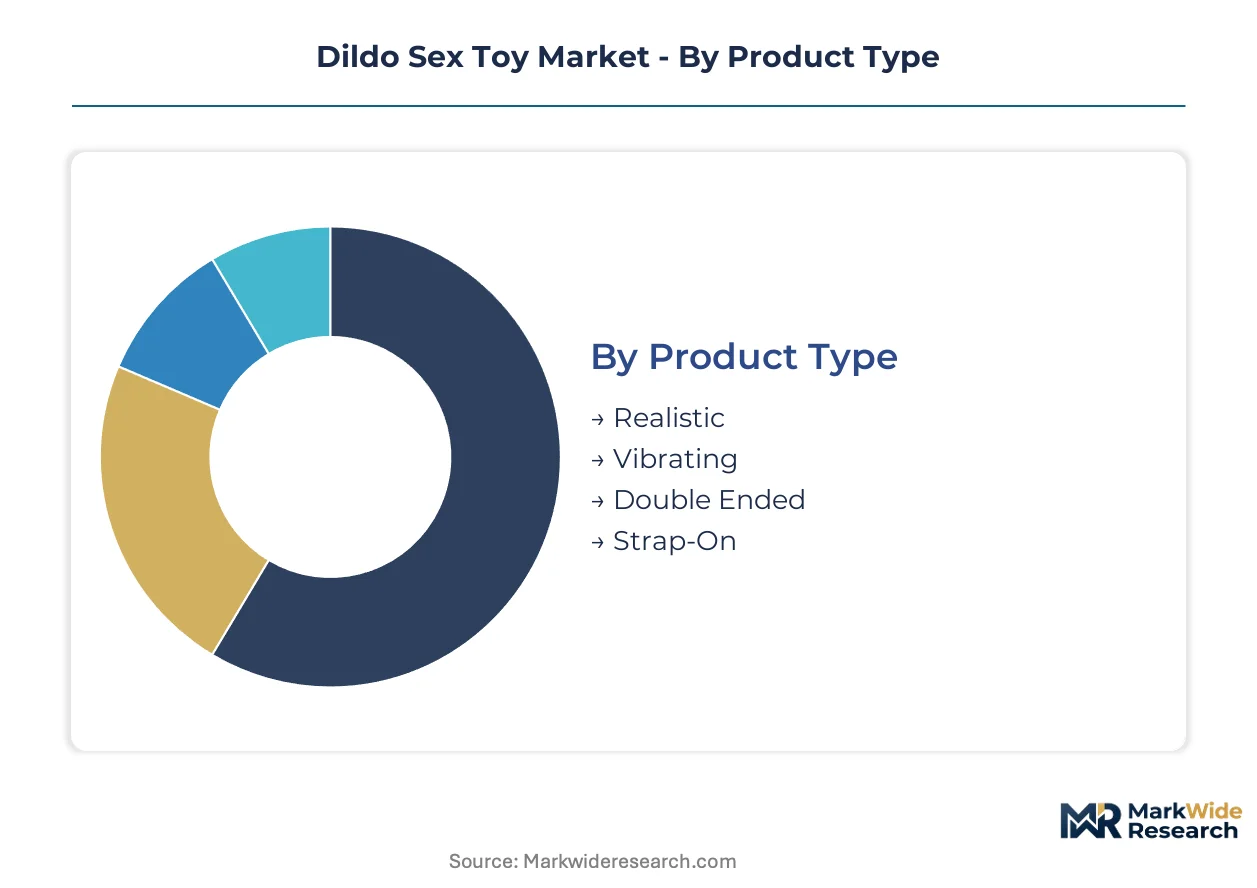
Segmentation in the dildo sex toy market determines material sourcing strategies, regulatory compliance pathways, and channel selection. Manufacturers align production capabilities with specific segment requirements to capture margin pools and minimize certification overhead.
Product Type:
Volume concentrates in conventional non-vibrating formats, while premium positioning clusters around motor-integrated and harness-compatible designs.
- Realistic:Molded from dual-density silicone with anatomically detailed surface texturing, these products dominate mainstream retail channels in Germany and the United States. Demand clusters among first-time buyers seeking familiar form factors, though margin compression intensifies as private-label programs proliferate.
- Vibrating:Integrated motor housings with rechargeable lithium-polymer batteries and app-connectivity modules command the highest price positioning. German and North American consumers adopt these SKUs fastest, driven by algorithmic personalization features that automate stimulation pattern generation.
- Double Ended:Symmetrical or graduated dual-insertion designs target couples-oriented purchasing in Japan and urban United States markets.
- Strap-On:Harness-compatible bases with O-ring standardization serve gender-affirming applications and partnered play, gaining traction fastest in LGBTQ+ targeted marketing channels.
Mature deployment sits with Realistic. Newer deployment is concentrated in Vibrating.
Material:
Medical-grade specifications are displacing legacy compounds as REACH phthalate restrictions and FDA biocompatibility frameworks tighten procurement standards.
- Silicone:Platinum-cured medical-grade formulations dominate premium manufacturing due to hypoallergenic properties, thermal stability, and autoclave sterilization compatibility. German chemical suppliers anchor global feedstock availability, though polymer shortages during supply disruptions expose concentration risk.
- Glass:Borosilicate variants with annealed stress-relief processing capture price-sensitive segments seeking non-porous alternatives without motor failure risk. Japanese craftsmanship traditions support artisanal production clusters in Tokyo and Osaka metropolitan areas.
- Rubber:Thermoplastic elastomer compounds face reformulation pressure under California Proposition 65 disclosure mandates, compressing economy-tier margins.
- PVC:Legacy phthalate-plasticized production is retreating from Western markets as compliance costs escalate, concentrating residual volume in unregulated distribution channels.
Certification-heavy deployment sits with Silicone. Cost-optimized deployment is concentrated in Rubber.
Color:
Aesthetic preferences segment by cultural context and distribution channel, with discrete packaging requirements influencing palette selection for direct-to-consumer fulfillment.
- Red:Bold chromatic signaling targets gift-oriented purchasing and seasonal promotional cycles in German and United States e-commerce.
- Black:Neutral professional aesthetic dominates corporate wellness program procurement and clinical-adjacent positioning in Japan.
- Flesh:Skin-tone matching concentrates in realistic product styling for mainstream United States retail, though inclusive shade expansion is displacing legacy Caucasian-centric defaults.
- Blue:Non-representational colorway adoption is climbing fastest among Gen Z consumers seeking departure from anatomical mimicry.
Conventional deployment sits with Flesh. Expanding most quickly is Blue.
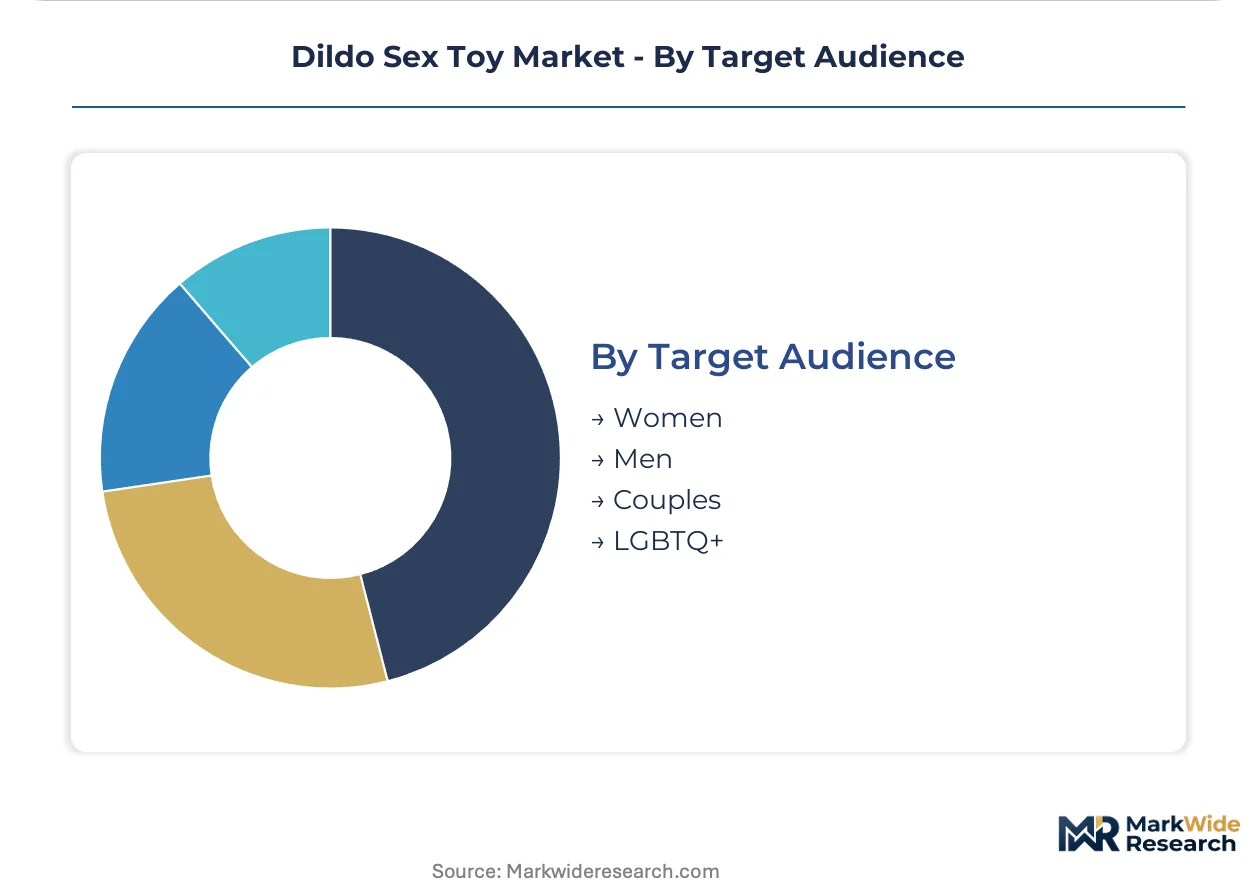
Target Audience:
Demographic targeting is shifting from gender-binary assumptions toward use-case and identity-based segmentation frameworks.
- Women:Historically dominant purchasing segment, now fragmenting across age cohorts with divergent preferences for connectivity features versus simplicity.
- Men:Prostate-focused form factors and perineal stimulation designs are gaining dedicated SKU development beyond repurposed conventional shapes.
- Couples:Synchronized remote-control functionality and dual-user interface design concentrates premium R&D investment in German and North American product pipelines.
- LGBTQ+:Gender-affirming product development and inclusive marketing frameworks are unlocking demand at premium price positioning with lower price elasticity, climbing fastest across all audience segments.
Established deployment sits with Women. Steepest expansion trajectory is LGBTQ+.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, the United States, and Japan where cultural stigma erosion and premium positioning converge. Per-capita purchasing power in these markets outpaces global medians by substantial margins. Regulatory fragmentation between FDA, EU REACH, and Japan's PMDA frameworks complicates unified certification strategies for manufacturers.
United States
Millennial and Gen Z consumers drive direct-to-consumer platform consolidation, displacing legacy adult retail networks. California Proposition 65 chemical disclosure mandates force reformulation of thermoplastic elastomer compounds, compressing economy-tier margins. Los Angeles and San Francisco metropolitan areas anchor domestic distribution logistics for discrete e-commerce fulfillment.
Germany
Erosion of cultural stigma combined with strong BfR safety recommendations establishes the highest per-capita demand concentration in the EU. EU REACH phthalate restrictions and biocompatibility testing protocols filter substandard manufacturers from Western supply chains. Berlin and Hamburg host the densest clusters of premium intimate product retail and direct-to-consumer platform headquarters.
Japan
Underdeveloped direct-to-consumer penetration relative to per-capita purchasing power presents whitespace for localized e-commerce platforms. METI oversight of consumer product safety and PMDA medical device classifications create compliance boundaries for therapeutic-positioned SKUs. Tokyo and Osaka metropolitan areas sustain artisanal production clusters for borosilicate glass variants.
China
Shenzhen-based manufacturers compete aggressively on cost-engineered silicone production, supplying private-label programs for Western distributors. GB standards and SAMR consumer product oversight govern domestic manufacturing quality frameworks. The Pearl River Delta concentration enables rapid prototyping and scale production for export markets.
United Kingdom
Post-Brexit regulatory divergence from EU REACH creates parallel compliance pathways for manufacturers serving British consumers. GDPR and emerging UK data protection frameworks shape app-enabled device development constraints. London anchors European headquarters for direct-to-consumer platforms targeting both domestic and continental markets.
Dildo Sex Toy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connectivity features and gender-affirming product development. The vendor base stratifies across premium Scandinavian design houses, scale-oriented American manufacturers, and cost-engineered Chinese fabricators. Three archetypes dominate: design-led premium positioning, manufacturing-scale coverage across price tiers, and private-label supply for Western distributors. Competitive moves concentrate on M&A for technology acquisition and strategic partnerships for discrete logistics networks.
Within the design-led tier, Lelo leverages Scandinavian aesthetic credentials to command premium positioning in European and North American e-commerce channels. Doc Johnson anchors manufacturing-scale competitive stance through decades of production breadth across multiple price tiers. Shenzhen Hejiamei Technology Co., Ltd exemplifies the cost-engineered archetype, supplying private-label programs for Western distributor networks.
| Leading Market Players |
|---|
| Lelo |
| Pipedream |
| Doc Johnson |
| Fleshlight |
| California Exotic |
| Lovehoney |
| Tantus |
| Shenzhen Hejiamei Technology Co., Ltd |
| Fun Factory |
| Others |
Pricing and Supply Chain Analysis
Medical-grade silicone feedstock from German and Japanese chemical suppliers flows through three distinct pricing tiers before reaching end consumers, with platinum-cured formulations commanding substantial premiums over thermoplastic elastomer alternatives. REACH compliance certification costs and biocompatibility testing timelines create natural segmentation between premium Scandinavian design houses and cost-engineered Chinese fabricators serving private-label distributors.
Pricing Analysis
Volume concentrates in economy-tier realistic products while margins pool in app-integrated vibrating SKUs with algorithmic personalization features. Price differentiation rests on certification grade—EU REACH and FDA biocompatibility tiers separate premium medical-grade silicone from reformulated thermoplastic elastomer compounds facing California Proposition 65 pressure. Cost compression in economy rubber segments is intensifying because legacy phthalate-plasticized formulations require expensive reformulation or market exit. First-time buyers in mainstream United States retail show highest price sensitivity; LGBTQ+ and couples segments demonstrate lowest elasticity for gender-affirming and connectivity-enabled products.
Supply Chain Analysis
EU REACH and California Proposition 65 disclosure mandates are reshaping sourcing patterns by disqualifying legacy compound suppliers from Western market access. Manufacturing concentrates in China, Germany, and Japan—Shenzhen anchors cost-engineered silicone production, German chemical suppliers dominate medical-grade feedstock, and Japanese artisans sustain borosilicate glass craftsmanship. Raw material dependencies center on platinum-cured silicone polymers, lithium-polymer battery cells, and precision motor housings. Single-source vulnerability runs through specialized German polymer suppliers during shortage periods. Distribution runs through direct-to-consumer platforms with discrete logistics partnerships, displacing legacy adult retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained at the premium tier, where medical-grade silicone certification bottlenecks prop pricing power for compliant manufacturers against reformulation-pressured economy competitors.
For Market Incumbents: Acquire edge-computing architecture capabilities to preempt EU AI Act data governance restrictions on app-enabled biometric collection. Incumbents must consolidate certification moats through backward integration into platinum-cured silicone production and deepen channel control via subscription replenishment bundling, defending against private-label erosion from Shenzhen-based cost engineers.
For New Entrants and Emerging Players: App-integrated haptic feedback systems with local biometric processing offer the most penetrable technology wedge for bypassing incumbent algorithm sophistication. Target Japan's underdeveloped direct-to-consumer penetration relative to per-capita purchasing power, and enter through localized e-commerce platforms with discrete metropolitan logistics partnerships rather than competing on manufacturing scale.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with partial REACH compliance investment but stranded by complete reformulation costs in Germany and the United States. Long-term viability hinges on five-to-ten year positioning for therapeutic medical device reclassification rather than wellness product commoditization. Monitor FDA medical device classification clarity as the critical inflection signal for vibrating SKU margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Certification Investment | EU REACH and FDA compliance tiers create defensible pricing separation from reformulation-pressured competitors. |
| Edge-Computing Architecture Development | Local biometric processing preempts EU AI Act restrictions on app-enabled device data transmission. |
| Subscription Replenishment Model Launch | Discrete recurring lubricant and hygiene deliveries capture lifetime value from urban millennial consumers. |
| Gender-Affirming Product Line Expansion | LGBTQ+ segment demand carries lower price elasticity and faster expansion trajectory than legacy demographics. |
| Direct-to-Consumer Platform Localization | Japan's whitespace opportunity requires metropolitan logistics partnerships for culturally discrete fulfillment. |
Research Methodology
Trade databases, regulatory filing repositories, and customs records formed the secondary backbone, cross-referenced with primary interviews across product development executives at premium manufacturers, procurement leads at Western distributor networks, regulatory affairs specialists navigating REACH and FDA frameworks, and channel managers at direct-to-consumer platforms. Bottom-up SKU-level volume estimates and top-down category spend analysis were triangulated against chemical supplier shipment data and e-commerce platform traffic metrics.
Historical trendline analysis identified inflection points at REACH implementation and Proposition 65 enforcement waves, with projection models built across material grade tiers, connectivity feature integration levels, target audience segments, and regional regulatory clusters. CAGRs were derived from segmented growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs incorporated biocompatibility certification timeline compression and direct-to-consumer penetration saturation curves by metropolitan market density.
Several conditions sit outside the modeled scope, including potential FDA medical device reclassification rulings, polymer supply disruption severity, and cultural stigma erosion velocity in underpenetrated markets. Forecasts reflect documented assumptions about regulatory enforcement consistency and substitution elasticity between material grades. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Model Train Market
Toys and Games
US Sex Toys Market
Toys and Games
Pre-School Games and Toys Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Action Figures Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Arcade Games Machine Market
Toys and Games
United States Toys Market
Toys and Games
Fabric Toys Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Wooden Toys Market
Toys and Games
Glow Sticks Market
Toys and Games
Cat Toys Market
Toys and Games
Construction Toys Market
Toys and Games
Blind Box Toys Market