
 Sustainable Toys Market | 2026-2036
Sustainable Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Toys Market Analytics
Buyer concentration among preschool chains and early learning networks is shifting procurement power toward institutional accounts with formal sustainability criteria. LEGO Group anchors its position through captive bioplastic resin development and in-house molding operations. PlanToys differentiates via FSC-certified rubberwood sourcing and zero-waste manufacturing in Thailand. HABA leverages its German craftsmanship heritage to command premium positioning in specialty retail across European markets.
Sustainable toys comprise play products manufactured from renewable, recyclable, or biodegradable materials including FSC-certified wood, bio-based polyethylene, and organic cotton textiles, typically processed without phthalates, heavy metals, or synthetic dyes to meet child safety standards. Wooden toys dominate unit volume in European markets due to durability perceptions and cultural preference for natural materials. Biodegradable plastics represent the fastest-expanding product category as petrochemical price volatility and brand ESG commitments accelerate material substitution. Organic fabric toys concentrate margin pools in the infant segment where parental willingness-to-pay peaks for hypoallergenic, chemical-free products.
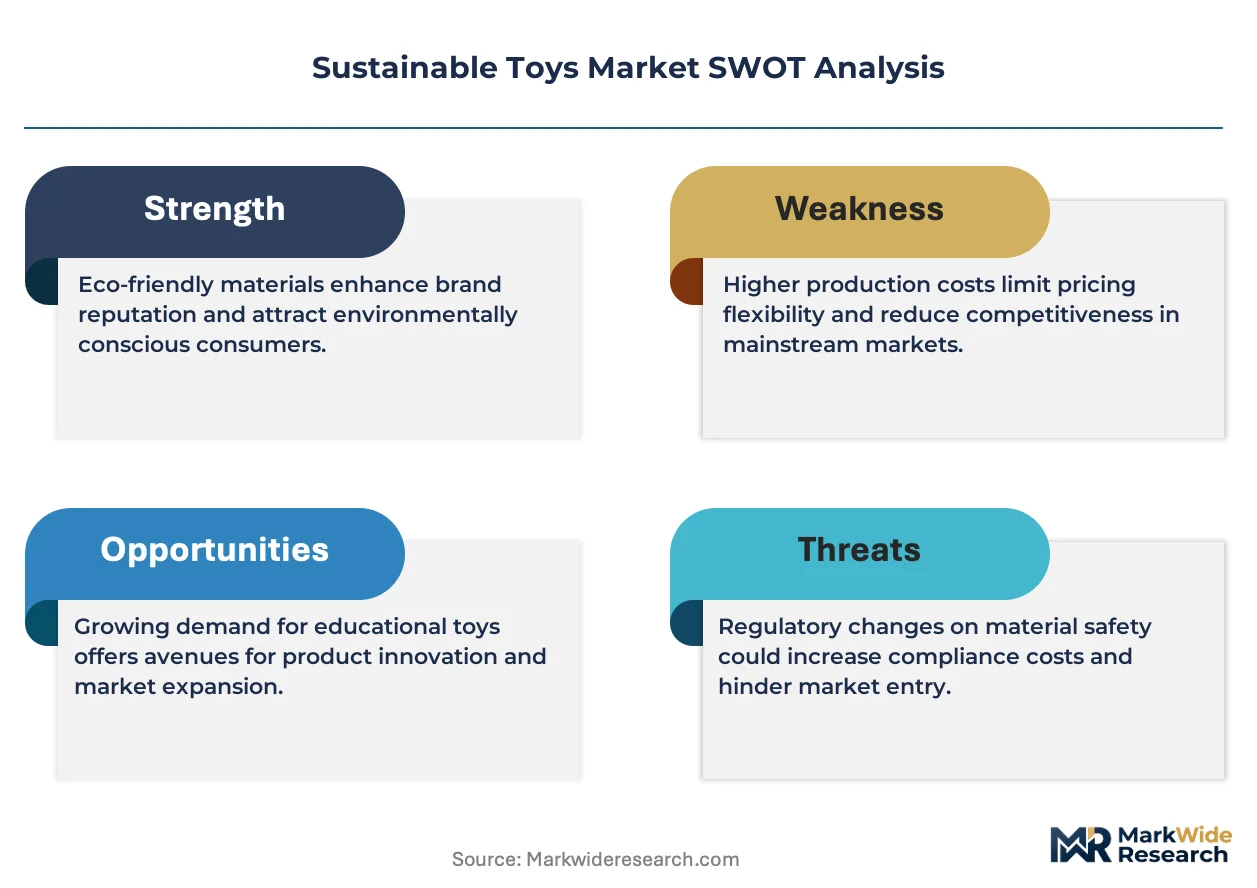
REACH chemical restrictions and the EU Toy Safety Directive mandate rigorous substance testing and traceability documentation, elevating compliance costs for smaller manufacturers while advantaging scaled producers with dedicated regulatory affairs functions. The EU Green Deal's circular economy action plan pressures packaging reduction and end-of-life recyclability, reshaping product design specifications. ISO 8124 safety standards and emerging national eco-label schemes in France and Germany further fragment certification requirements. Stakeholders must monitor evolving chemical threshold limits and invest in preemptive material qualification to maintain market access across diverging regulatory timelines.
Market Dynamics
REACH chemical restrictions and the EU Toy Safety Directive are compressing supplier margins while concentrating procurement power among institutional buyers with dedicated compliance infrastructure.
Growth Catalysts
- EU Green Deal circular economy mandates:Municipal green procurement policies in Nordic countries now require sustainability certifications for publicly funded childcare equipment, redirecting institutional purchasing toward certified suppliers.
- Bioplastic material substitution:Petrochemical price volatility is accelerating brand ESG commitments to bio-based polyethylene and plant-derived resins in molded play products.
- German early childhood networks:Preschool chains are formalizing sustainability criteria in supplier scorecards, creating predictable demand channels for FSC-certified wooden toy manufacturers.
Market Restraints
- Natural rubberwood supply concentration:FSC-certified plantation capacity clusters in Southeast Asia, exposing manufacturers to regional climate disruption and logistics bottlenecks.
- REACH compliance cost escalation:Rigorous substance testing and traceability documentation requirements disproportionately burden smaller manufacturers without dedicated regulatory affairs functions.
- Petrochemical resin price volatility:Conventional plastic input cost swings complicate pricing strategies for bioplastic alternatives competing on total cost of ownership.
Strategic Opportunities
- France and Germany eco-label fragmentation:Emerging national certification schemes create first-mover positioning for suppliers who preemptively qualify materials across diverging regulatory timelines.
- ISO 8124 safety standard harmonization:Convergence of international safety protocols reduces duplicate testing burdens for exporters targeting multiple high-income markets simultaneously.
- Direct-to-institution digital platforms:Procurement digitization in municipal childcare systems enables disintermediation of traditional toy distributors in Nordic markets.
Industry Challenges
- Material qualification timeline compression:Preemptive testing against evolving chemical threshold limits demands R&D coordination with polymer chemists and certification bodies.
- Packaging redesign cycles:End-of-life recyclability mandates under circular economy action plans force rapid retooling of product design specifications and supplier specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Toys Market |
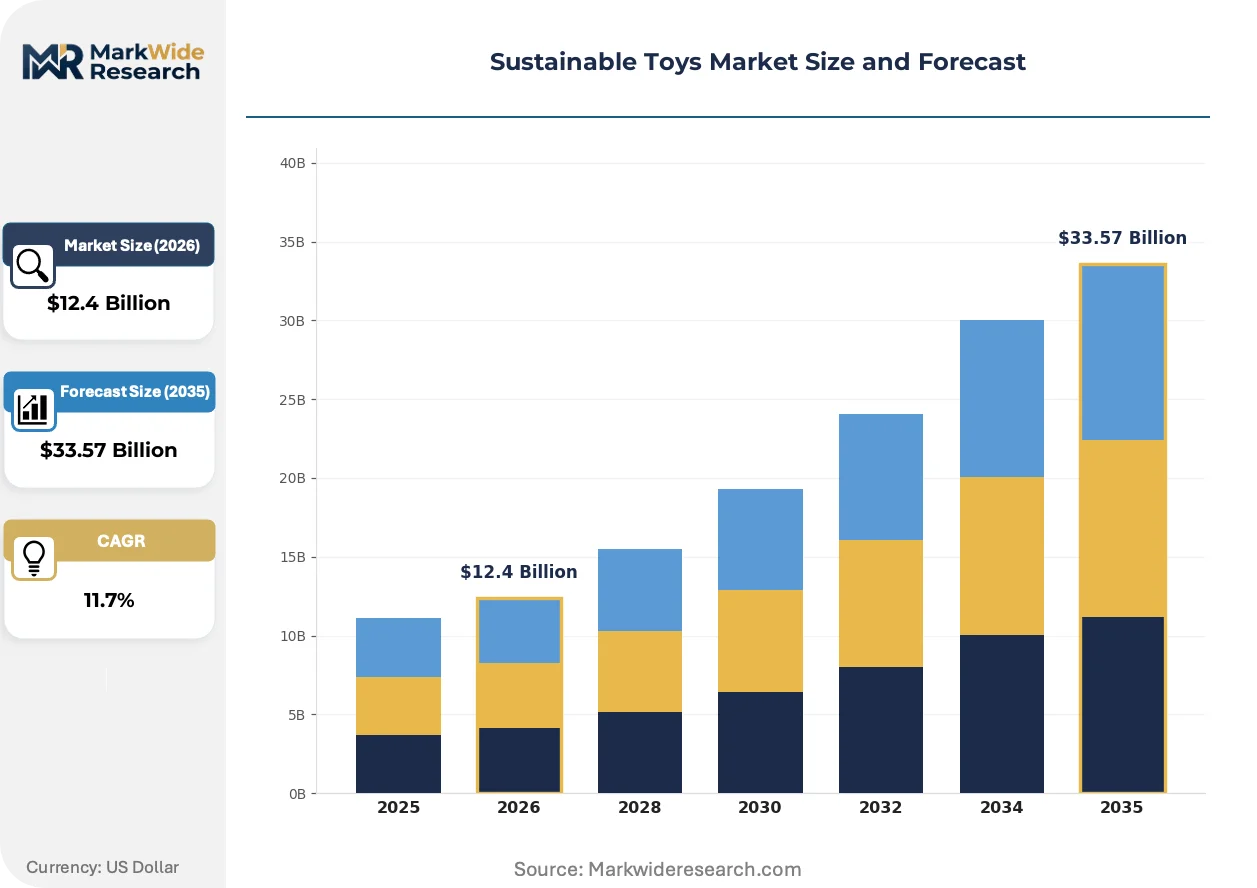
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.57 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Toys, Biodegradable Plastics, Organic Fabric Toys, Eco-friendly Games Age Group: Infants, Toddlers, Preschoolers, School-Age Price Tier: Budget, Mid-range, Premium, Luxury Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Toy Fairs |
| Companies Covered | Green Toys, Tender Leaf Toys, LEGO Group, MGA Entertainment, Playmobil, Mattel, PlanToys, HABA, Hasbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Toys Market Evolving Landscape
Material science advances and procurement digitization are restructuring competitive positioning in sustainable toy supply chains, with regulatory compliance emerging as a capability differentiator rather than a baseline requirement.
Biodegradable plastics are absorbing market share from conventional petroleum-based resins as the dominant material innovation trajectory. German and Scandinavian early learning networks are adopting bio-based polyethylene formulations at accelerating pace for indoor play equipment. This substitution is compressing margins for petrochemical-dependent molders while rewarding captive bioplastic resin development.
REACH chemical restrictions are tightening material compliance requirements across European supply chains with expanded substance testing obligations. The regulation elevates documentation burdens for imported components while advantaging scaled producers with in-house laboratory capabilities. Wooden toy manufacturers sourcing FSC-certified rubberwood face intensified traceability audits but gain preferential access to institutional procurement channels.
Buyer concentration among preschool chains is fragmenting traditional distribution hierarchies in Nordic markets. Municipal green procurement policies now mandate direct sustainability certification verification, displacing reliance on distributor compliance guarantees. This pattern concentrates most visibly in Sweden and Denmark where publicly funded childcare equipment spending follows formal environmental purchasing protocols.
Sustainable Toys Market Segmentation
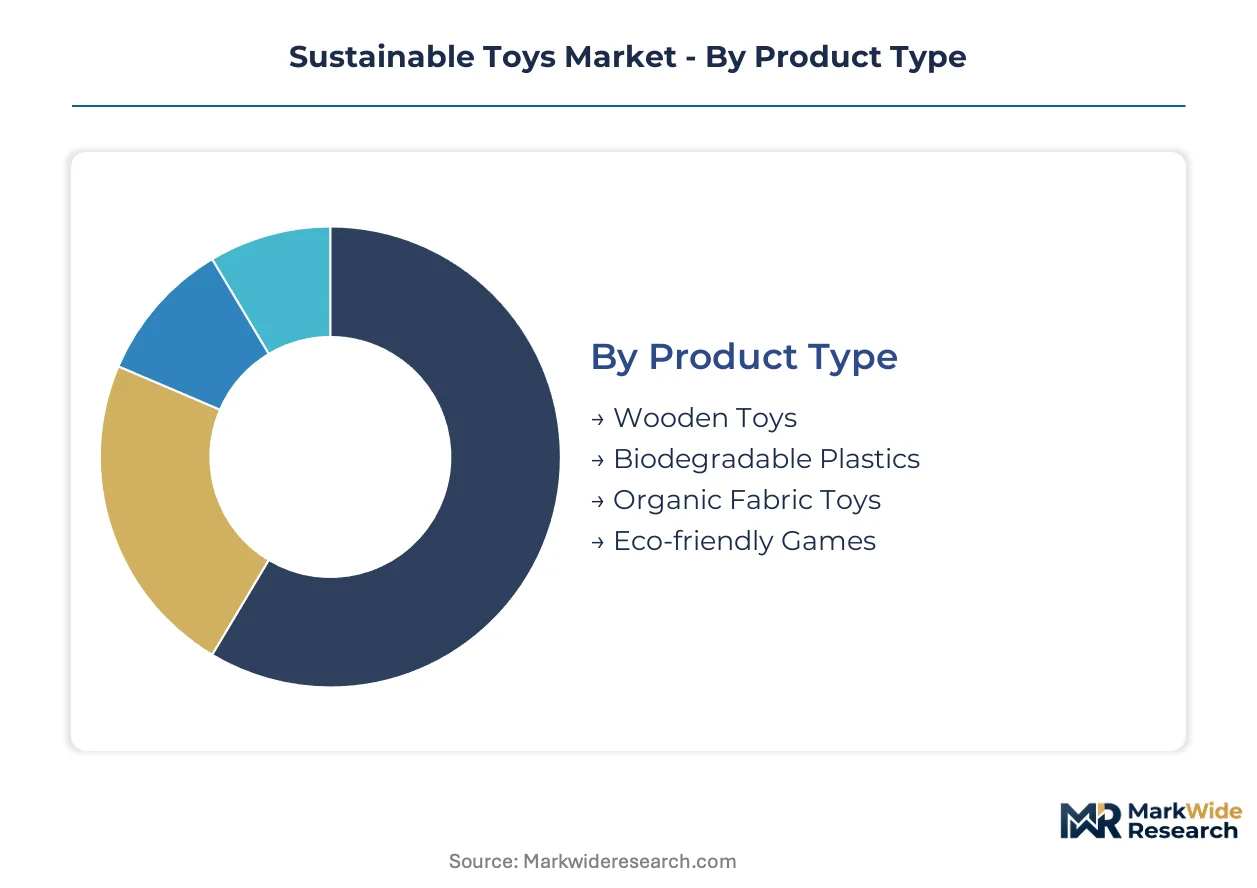
Material composition and age-specific safety requirements create distinct purchasing behaviors across the sustainable toys market. Procurement patterns diverge sharply between institutional buyers with formal certification requirements and individual consumers prioritizing tactile experience and durability perceptions.
Product Type:
Buyers differentiate primarily by material origin and end-of-life disposal pathways, with institutional procurement channels weighting biodegradability and recyclability metrics more heavily than individual consumers.
- Wooden Toys:FSC-certified rubberwood and hardwood constructions processed without synthetic dyes or chemical treatments. German and Scandinavian early childhood education centers dominate institutional demand, driven by municipal green procurement mandates and cultural preference for natural material durability.
- Biodegradable Plastics:Bio-based polyethylene and plant-derived resins formulated for molded play equipment with compostable end-of-life characteristics. Nordic preschool chains are accelerating adoption as petrochemical price volatility compresses total cost of ownership differentials against conventional plastics.
- Organic Fabric Toys:Certified organic cotton and natural fiber textiles with hypoallergenic processing for infant-safe applications.
- Eco-friendly Games:Board games and educational playsets utilizing recycled cardboard, soy-based inks, and plastic-free component packaging.
Wooden toys lead volumes today; biodegradable plastics are gaining share fastest.
Age Group:
Developmental safety standards and parental willingness-to-pay create tiered demand intensity, with infant and toddler segments commanding premium positioning due to heightened chemical exposure concerns.
- Infants:Sensory and motor development products with strictest material purity requirements. Organic fabric toys concentrate margin pools here as parental expenditure peaks for hypoallergenic, chemical-free certification.
- Toddlers:Exploratory play materials emphasizing durability and mouthing safety. Wooden toys capture disproportionate share in German-speaking markets where craftsmanship heritage influences purchasing decisions.
- Preschoolers:Structured learning and social play equipment with institutional procurement concentration.
- School-Age:Complex construction sets and educational games with independent purchasing influence emerging.
Toddler-focused products generate the highest unit volumes; infant-directed segments sustain the steepest margin premiums.
Price Tier:
Certification depth and material traceability create stratified pricing architecture, with REACH compliance documentation and FSC chain-of-custody verification separating premium positioning from economy alternatives.
- Budget:Entry-level sustainable materials with basic safety certification and limited traceability documentation. REACH compliance cost escalation disproportionately pressures this tier as testing obligations accumulate.
- Mid-range:Balanced sustainability credentials with recognizable eco-labels and regional certification acceptance. This tier absorbs the largest share of bioplastic substitution demand as price-performance ratios improve.
- Premium:Comprehensive certification portfolios including FSC, organic textiles, and carbon footprint verification.
- Luxury:Artisan-crafted heirloom-quality pieces with provenance documentation and limited production runs.
Mid-range positioning captures the broadest demand base; premium tier expansion is accelerating fastest among institutional buyers.
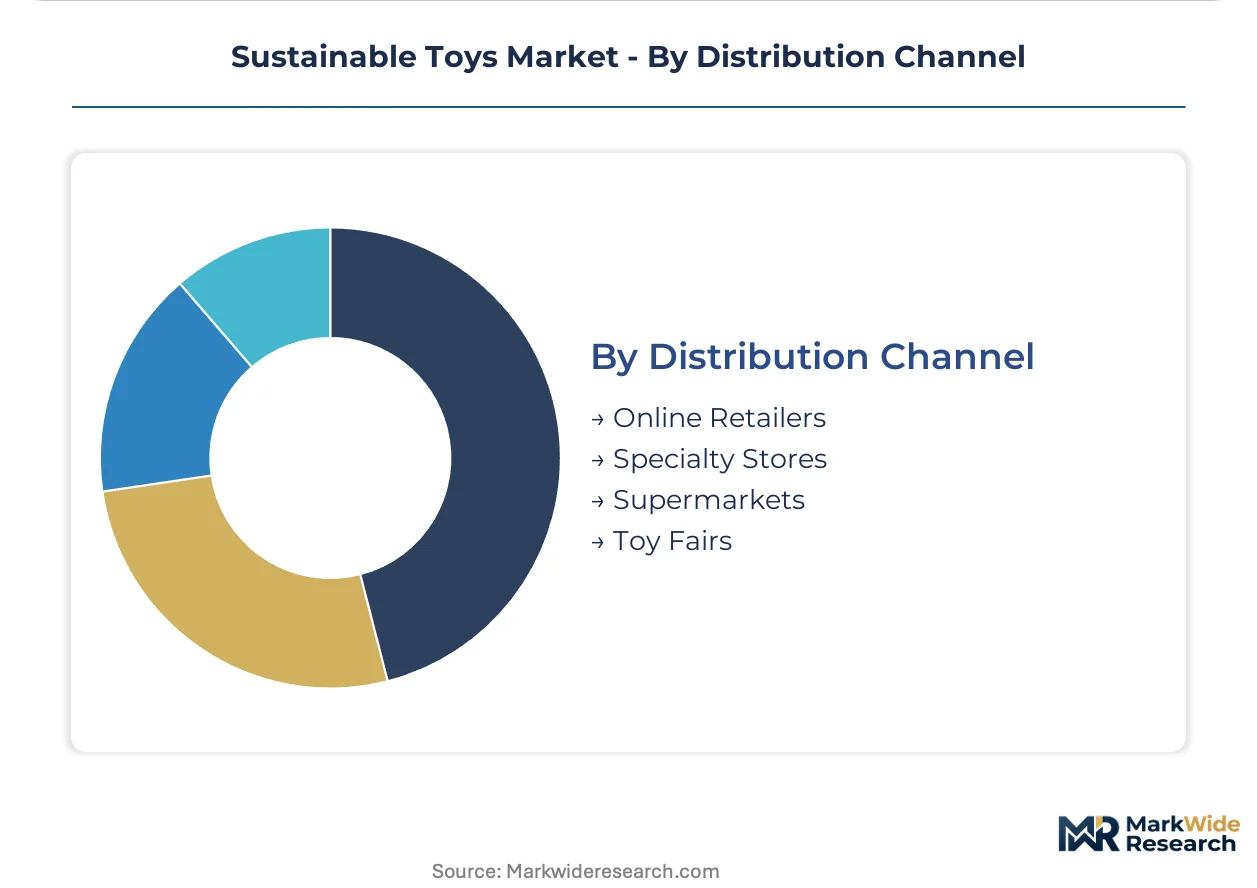
Distribution Channel:
Procurement digitization and direct certification verification requirements are fragmenting traditional distributor hierarchies, particularly in Nordic municipal childcare systems.
- Online Retailers:E-commerce platforms with sustainability filter functionality and direct-to-consumer certification transparency. German consumers demonstrate highest digital adoption for wooden toy purchases, bypassing traditional specialty retail intermediaries.
- Specialty Stores:Curated brick-and-mortar experiences with tactile product demonstration and expert guidance. HABA and PlanToys maintain flagship positioning here through craftsmanship storytelling and material education.
- Supermarkets:Mass-market accessibility with limited sustainability credential depth and price-driven assortment.
- Toy Fairs:B2B procurement events with institutional buyer concentration and direct manufacturer negotiation.
Online retailers lead volume growth today; specialty stores retain the highest margin capture per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized toy manufacturing clusters in Germany, Thailand, and Denmark concentrate the skilled labor and certification infrastructure driving sustainable material innovation.
Germany
Early childhood education networks in Bavaria and North Rhine-Westphalia are formalizing sustainability scorecards for supplier selection. The EU Toy Safety Directive and REACH chemical restrictions administered by ECHA mandate rigorous substance testing documentation. Nuremberg hosts the annual Spielwarenmesse toy fair, where municipal procurement officials from across Europe negotiate direct manufacturer contracts.
Sweden
Municipal green procurement policies in Stockholm and Malmö redirect publicly funded childcare equipment spending toward certified sustainable suppliers. The Swedish Environmental Protection Agency enforces national eco-label criteria that exceed baseline EU requirements. Småland's traditional woodworking region has pivoted toward FSC-certified rubberwood processing for institutional toy contracts.
Denmark
Public childcare systems in Copenhagen and Aarhus operate under mandatory environmental purchasing protocols for play materials. The Danish Environmental Protection Agency coordinates with EU Green Deal circular economy implementation timelines. Billund anchors concentrated bioplastic resin development and captive molding operations for construction toy manufacturing.
Thailand
FSC-certified rubberwood plantation capacity clusters in Trang and Surat Thani provinces, supplying raw material for zero-waste manufacturing operations. The Thailand Board of Investment promotes sustainable manufacturing through tax incentives for green process certification. Bangkok serves as the regional logistics hub for wooden toy exports to European institutional buyers.
United States
California's early learning quality rating systems incorporate material safety documentation requirements for subsidized childcare providers. The Consumer Product Safety Commission enforces ASTM F963 toy safety standards with expanding chemical disclosure obligations. Los Angeles and New York metropolitan areas concentrate specialty retail distribution for premium sustainable toy brands.
Sustainable Toys Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base fragments between mass-market plastic toy manufacturers pivoting toward bioplastic portfolios and heritage wooden toy craftsmen scaling institutional channels. Three archetypes dominate: scale-driven polymer innovators with captive resin development, craft heritage brands commanding premium specialty retail positioning, and sustainability-native pure-plays built on zero-waste manufacturing from inception. Competitive intensity centers on preemptive material qualification against diverging regulatory timelines and direct-to-institution procurement digitization.
Among Denmark-based construction toy manufacturers, LEGO Group exemplifies scale-driven bioplastic innovation through in-house resin chemistry capabilities. PlanToys and HABA occupy differentiated positions within the craft heritage tier, with the former representing Southeast Asian zero-waste manufacturing integration and the latter anchoring German specialty retail channel dominance. These three companies illustrate how material science investment and regional certification depth separate sustainable toy market positions.
| Leading Market Players |
|---|
| Green Toys |
| Tender Leaf Toys |
| LEGO Group |
| MGA Entertainment |
| Playmobil |
| Mattel |
| PlanToys |
| HABA |
| Hasbro |
| Others |
Value Network & Pricing Analysis
Bioplastic resin formulation advances are compressing production cost differentials against petroleum-based alternatives while simultaneously concentrating supply leverage among manufacturers with captive chemistry capabilities and FSC-certified plantation networks. REACH compliance documentation burdens and municipal green procurement mandates reshape how buyers evaluate total cost of ownership beyond unit price.
Pricing Analysis
Certification-bundled versus unbundled procurement splits the market. Three-tier pricing structure across premium, standard, and economy levels reflects FSC chain-of-custody depth and REACH documentation completeness. Price differentiation hinges on certification grade and volume scale. Cost compression in the budget tier intensifies because testing obligation accumulation outpaces margin recovery. Institutional buyers with formal sustainability scorecards demonstrate lowest price sensitivity; mass-market supermarket channels exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with FSC-certified rubberwood plantation networks concentrated in Thailand's Trang and Surat Thani provinces. Geographic supply concentration clusters in Thailand, Germany, and Denmark. Raw material dependencies rest on bio-based polyethylene feedstocks, organic cotton textiles, and FSC-certified hardwoods. Supply chain risk centers on regional climate disruption to Southeast Asian plantation yields. Distribution runs through direct-to-institution digital platforms in Nordic municipal childcare systems and specialty retail channels in German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sustainable toys market functions as a stable compounder anchored by regulatory ratchet effects in European childcare procurement that perpetually tighten material compliance thresholds and certification requirements.
For Market Incumbents: Anticipate REACH chemical threshold revisions by preemptively qualifying alternative bioplastic formulations with polymer chemists and certification bodies. Deepen backward integration into FSC-certified plantation operations to secure raw material preferential access as climate volatility intensifies. Control channel position through direct digital procurement platform partnerships with Nordic municipal childcare systems.
For New Entrants and Emerging Players: Capture white-space in France and Germany's emerging national eco-label schemes where first-mover qualification creates positioning ahead of regulatory divergence. Target mid-range biodegradable plastic segments where price-performance ratios are improving fastest against conventional alternatives. Pursue white-label manufacturing partnerships with established Southeast Asian zero-waste facilities to bypass capital-intensive facility buildout.
For Investors and Strategic Acquirers: Valuations sit cheapest among craft heritage wooden toy manufacturers lacking institutional procurement channel scale but possessing FSC certification depth and regional brand equity. Long-term viability favors vertically integrated specialists with captive bioplastic resin development and direct municipal buyer relationships. Watch REACH substance restriction expansion timelines as the signal for accelerated consolidation among compliance-burdened smaller manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| FSC-Certified Plantation Acquisition | Secures raw material preferential access for German and Scandinavian institutional contracts. |
| Bioplastic Resin Development Partnership | Captures cost compression benefits as petrochemical price volatility accelerates material substitution. |
| Direct-to-Institution Digital Platform Launch | Disintermediates traditional toy distributors in Nordic municipal childcare procurement systems. |
| REACH Preemptive Qualification Program | Maintains market access across diverging EU national eco-label timelines and chemical threshold revisions. |
| Zero-Waste Manufacturing Certification | Aligns production with EU Green Deal circular economy mandates and packaging reduction requirements. |
Research Methodology
Coverage spans Germany, Scandinavia, Thailand, and the United States, with primary inputs from each combining interviews with sustainability procurement officers at preschool chains, regulatory affairs directors at toy manufacturers, FSC certification auditors, and bioplastic polymer chemists with secondary validation against EU Toy Safety Directive documentation, REACH substance restriction databases, municipal green procurement policy filings, and customs trade records for certified wooden toy exports. Bottom-up segment sizing triangulates against top-down market reconstruction.
Rate-of-change decomposition separates volume growth from value expansion across material type, age group, price tier, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis of historical procurement data against regulatory implementation timelines and petrochemical price elasticity coefficients. Industry-specific inputs include FSC certification penetration rates by country and bioplastic resin cost curves.
REACH chemical threshold revisions, Southeast Asian plantation climate disruption, and Nordic municipal budget allocation shifts are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about regulatory implementation pacing and material substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Animation Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Model Train Market
Toys and Games
Toy Collectibles Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Cat Toys Market
Toys and Games
Inflatable Toys Market
Toys and Games
Construction Toys Market
Toys and Games
Plastic Toy Storage Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
China Toys Market
Toys and Games
Kids Toys Market
Toys and Games
China Playing Cards & Board Games Market