
 Connected Toys Market | 2026-2036
Connected Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Toys Market Intelligence
Multi-source component procurement is restructuring supply dynamics across the Connected Toys Market. Mattel leverages its established manufacturing partnerships to maintain cost discipline across plastic-electronic hybrid product lines. Hasbro competes through broad entertainment licensing that extends toy connectivity into transmedia storytelling ecosystems.
Connected toys embed microprocessors, wireless transceivers, and sensor arrays within traditional play objects to enable responsive, data-generating interactions between children and digital environments. Bluetooth-enabled products dominate volume shipments due to lower power requirements and simplified pairing protocols for young users. Interactive robots command premium positioning among early school age segments, while smart dolls sustain higher margin pools through subscription-linked content services. Learning games anchored in augmented reality represent the fastest-growing technology-application intersection.
The Federal Trade Commission enforces COPPA-mandated parental consent frameworks that govern data collection from connected toys marketed to children under thirteen. The EU AI Act classifies emotion-recognition features in children's products as high-risk, compelling redesigns of voice-interactive systems. Stakeholders must monitor evolving interoperability standards and jurisdiction-specific age-verification mandates to sustain market access across fragmented regulatory territories.
Market Dynamics
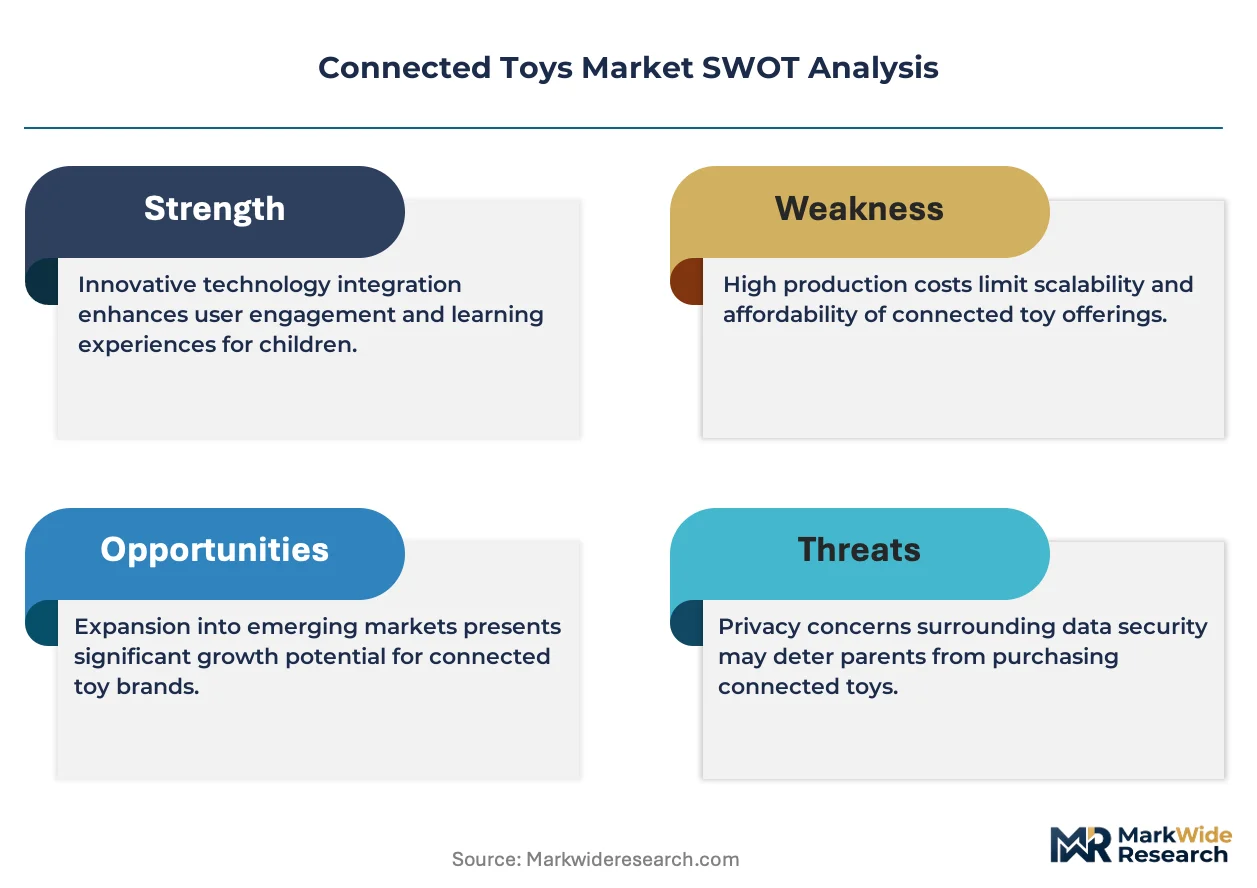
Regulatory fragmentation across children's data protection is forcing manufacturers to maintain parallel compliance architectures, raising fixed costs while compressing time-to-market for voice-enabled and biometric-sensing products.
Growth Catalysts
- GDPR Article 8 age-verification mandates:European preschool programs now require COPPA-equivalent consent frameworks, expanding procurement pools for compliant STEM-integrated toy systems.
- Bluetooth Low Energy 5.3 adoption:Extended range and reduced power draw enable outdoor-responsive play patterns in suburban United States households with larger property footprints.
- Subscription content services:Recurring revenue models anchored in augmented reality learning modules are restructuring unit economics away from one-time hardware sales.
Market Restraints
- Lithium polymer cell volatility:Battery raw material concentration in Chinese processing facilities exposes margin structures to export quota fluctuations and freight cost spikes.
- EU AI Act high-risk classification:Emotion-recognition features trigger mandatory third-party conformity assessment, extending certification timelines by 8-14 months.
- Silicon wafer fabrication bottlenecks:Mature-node microcontroller shortages constrain output scaling for sensor-embedded product lines below 28nm process nodes.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component assembly incentives reduce landed costs for Bluetooth module integration serving price-sensitive emerging middle-class segments.
- Voice-interactive eldercare crossover:Companion robot architectures developed for pediatric markets are adapting to aging-in-place applications with minimal hardware redesign.
- Direct-to-educator distribution:Bypassing traditional retail through institutional procurement portals captures bulk pricing power and multi-year curriculum adoption contracts.
Industry Challenges
- Embedded systems security engineering:Firmware vulnerability patching cycles lag hardware replacement timelines, creating persistent exposure windows for connected play devices.
- Interoperability standard fragmentation:Competing proprietary protocols between major platform ecosystems force redundant development tracks and dilute R&D concentration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Toys Market |
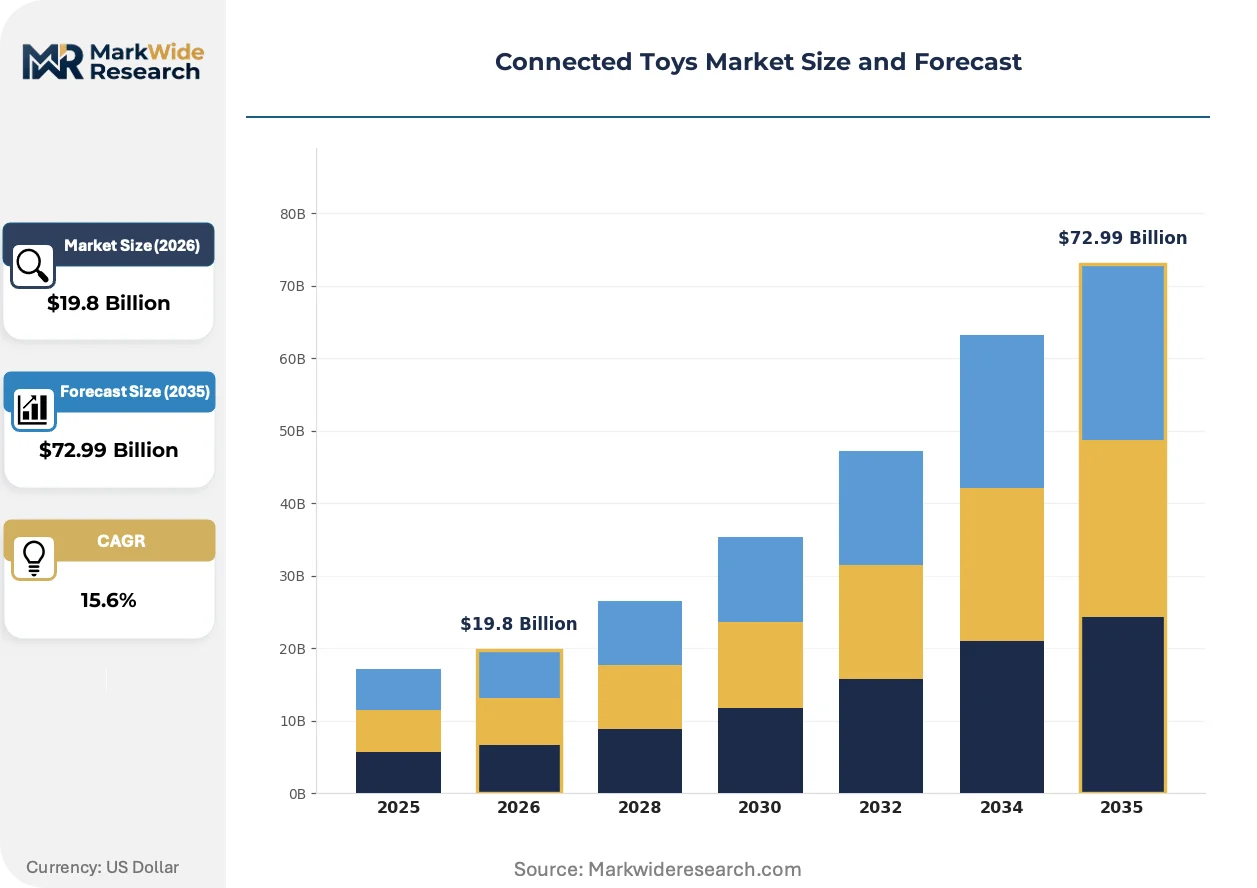
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $72.99 Billion |
| CAGR (2026 – 2036) | 15.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Dolls, Interactive Robots, Learning Games, Action Figures Technology: Bluetooth, Wi-Fi, RFID, Augmented Reality Age Group: Toddlers, Preschoolers, Early School Age, Tweens Material: Plastic, Fabric, Wood, Electronic Components |
| Companies Covered | Mattel, Hasbro, LEGO Group, VTech, Sphero, Sony Corporation, WowWee Group, Wonder Workshop, Spin Master, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Toys Market Strategic Shifts & Innovations
Edge computing architectures are migrating processing loads away from cloud dependency, reshaping data governance obligations and hardware cost structures simultaneously. Three developments are compressing competitive differentiation timelines.
On-device neural inference is decentralizing voice command interpretation from remote servers to local microcontrollers. Preschool-focused manufacturers in the United States are adopting TensorFlow Lite Micro runtimes to eliminate round-trip latency and reduce COPPA-triggered data transmission events. This shift compresses cloud infrastructure spend while complicating firmware update distribution logistics.
The EU AI Act's high-risk classification for biometric inference in children's products is compelling architecture redesigns ahead of August 2027 enforcement deadlines. Voice-interactive systems must now implement deterministic processing boundaries that prevent emotion-state extraction. German and French distributors are demanding pre-certified component modules to accelerate their own conformity assessment timelines.
Parental purchasing committees in United States suburban districts are unbundling hardware procurement from content subscription decisions. School technology coordinators now source Bluetooth-enabled base units through competitive bidding while evaluating AR learning content through separate pilot programs. This bifurcation is fragmenting vendor relationships and extending sales cycle complexity for integrated platform providers.
Connected Toys Market Segmentation
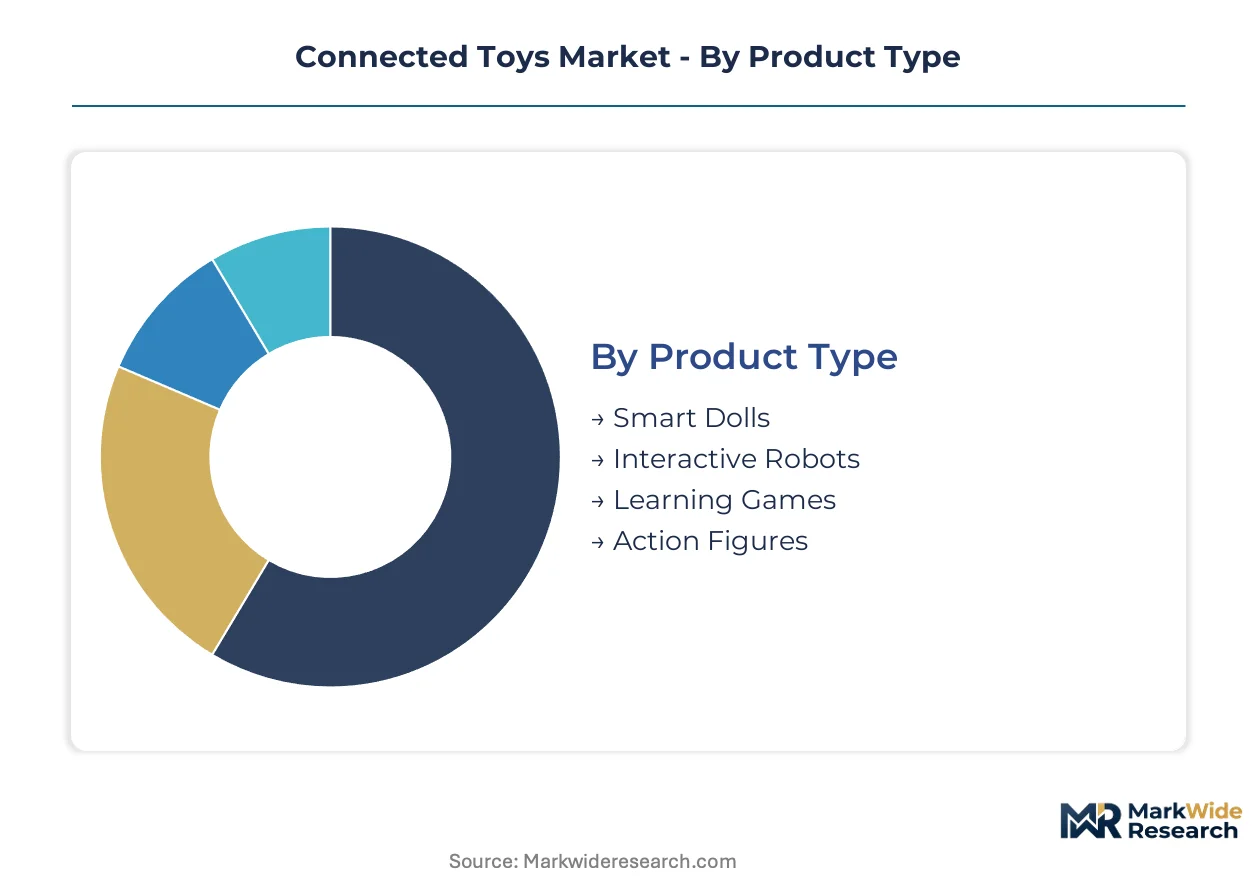
Connected toys demand granular segmentation because hardware specifications, connectivity protocols, and content maturity ratings determine regulatory compliance pathways and distribution channel eligibility. Manufacturers must align product architectures with distinct age-verification mandates and data governance frameworks that vary by segment.
Product Type:
Customization versus standardization tension runs deepest here, with subscription-linked content services demanding flexible hardware platforms while mass retail SKUs prioritize cost-locked configurations.
- Smart Dolls:These products integrate voice-recognition microprocessors and cloud-linked content libraries within traditional doll form factors. Parental purchasing committees in United States suburban districts concentrate procurement through institutional pilot programs that evaluate AR learning content separately from hardware acquisition, fragmenting vendor relationships.
- Interactive Robots:Sensor-embedded locomotion platforms with deterministic processing boundaries for EU AI Act compliance. Early school age segments in Germany and France drive demand for pre-certified component modules that accelerate distributor conformity assessments.
- Learning Games:Tablet-based and physical-digital hybrid educational systems.
- Action Figures:NFC-enabled collectibles with limited connectivity for inventory authentication.
Most installed capacity flows through Smart Dolls. Expansion is steepest in Interactive Robots.
Technology:
Cost tier stratification separates premium positioning from volume penetration, with licensing fees and certification burdens concentrating margin pressure at the low end.
- Bluetooth:Bluetooth Low Energy 5.3 modules dominate volume shipments through reduced power draw and simplified pairing protocols. United States households with larger suburban property footprints are adopting outdoor-responsive play patterns that exploit extended range specifications.
- Wi-Fi:Higher-bandwidth connectivity enabling real-time video streaming and cloud-dependent AI inference. COPPA-mandated parental consent frameworks from the FTC constrain data collection architectures for under-thirteen users.
- RFID:Passive and active tagging for proximity-based interaction triggers.
- Augmented Reality:Camera-mediated overlay systems anchoring the fastest-expanding content subscription models.
Bluetooth captures the largest shipment volumes. Augmented Reality is climbing the fastest.
Age Group:
Application context determines hardware durability requirements and content governance intensity, with institutional procurement creating divergent specifications from consumer retail.
- Preschoolers:STEM-integrated toy systems with TensorFlow Lite Micro runtimes for on-device neural inference. GDPR Article 8 age-verification mandates in European preschool programs now require COPPA-equivalent consent frameworks, expanding compliant procurement pools.
- Early School Age:Voice-interactive systems with deterministic processing boundaries preventing emotion-state extraction under EU AI Act high-risk classifications. German and French distributors demand pre-certified modules to compress certification timelines.
- Toddlers:Simplified tactile interfaces with minimal connectivity exposure.
- Tweens:Social-featured platforms with peer connectivity and content creation tools.
Preschoolers absorb the most institutional procurement volume. Early School Age is gaining share fastest.
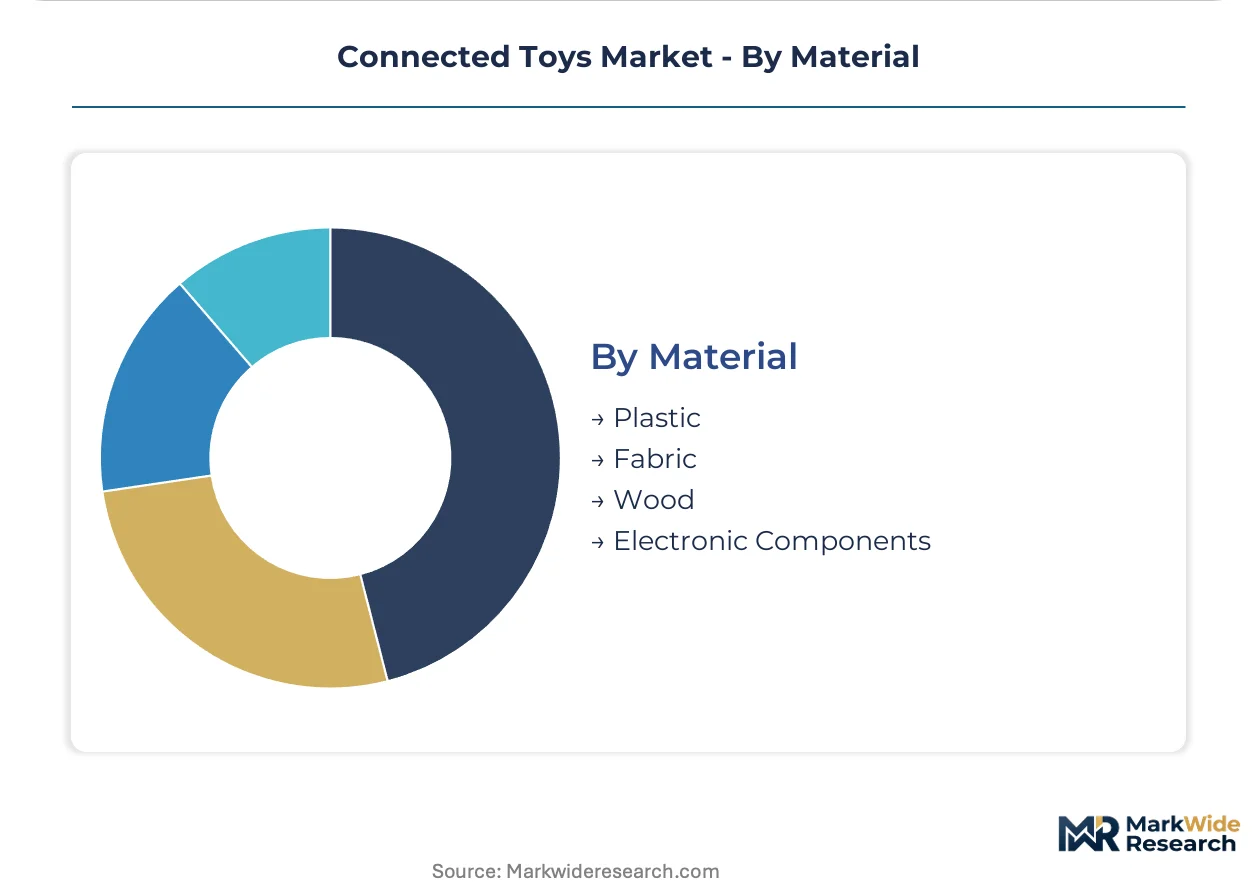
Material:
Supply concentration in Chinese processing facilities for electronic subcomponents creates margin volatility that plastic and fabric sourcing cannot hedge.
- Electronic Components:Microcontrollers, wireless transceivers, and sensor arrays embedded within hybrid products. Silicon wafer fabrication bottlenecks for mature-node chips below 28nm constrain output scaling.
- Plastic:ABS and polycarbonate shells housing electronic assemblies. Mattel leverages established manufacturing partnerships to maintain cost discipline across plastic-electronic hybrid lines.
- Fabric:Soft-bodied doll exteriors with embedded conductive threading.
- Wood:Premium positioning materials for sustainability-positioned SKUs.
Electronic Components represent the dominant cost stack. Plastic maintains the broadest manufacturing footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the densest electronics manufacturing corridor for connected toy components, with the Pearl River Delta supplying Bluetooth modules and microcontroller assemblies to brands worldwide. Demand concentrates in the United States, Germany, China, India, and Japan.
United States
Parental spending on technology-enriched educational play drives procurement through suburban school districts and institutional pilot programs. The FTC enforces COPPA-mandated parental consent frameworks that govern data collection from products marketed to children under thirteen. Silicon Valley hardware startups and Los Angeles entertainment licensors cluster around transmedia content integration for interactive dolls.
Germany
German distributors demand pre-certified component modules to accelerate conformity assessments for voice-interactive systems. The EU AI Act classifies emotion-recognition features in children's products as high-risk, compelling deterministic processing boundaries that prevent emotion-state extraction. Bavarian industrial automation suppliers and Berlin-based edtech procurement platforms are compressing certification timelines through modular compliance architectures.
China
Domestic consumption of STEM-integrated preschool systems is expanding alongside export manufacturing dominance. MIIT oversees national standards for wireless device certification that align with international Bluetooth Low Energy specifications. Shenzhen and Dongguan host the world's densest concentration of plastic-electronic hybrid assembly lines, though lithium polymer cell volatility exposes margin structures to raw material quota fluctuations.
India
The PLI scheme for electronics manufacturing is attracting component assembly investment that reduces landed costs for Bluetooth module integration. BIS certification requirements for wireless children's products are tightening alongside state-level preschool curriculum digitization initiatives. Karnataka and Maharashtra host emerging distributor networks serving price-sensitive emerging middle-class segments in Bangalore and Mumbai metropolitan corridors.
Japan
METI promotes domestic production of educational robotics through regional innovation clusters targeting early school age segments. JIS standards for electronic toy safety intersect with GDPR-equivalent data governance expectations from European export customers. Tokyo and Osaka anchor premium positioning for companion robot architectures that cross over into aging-in-place applications with minimal hardware redesign.
Connected Toys Market Key Industry Players
Global majors compete with regional champions across content licensing and manufacturing scale dimensions. The vendor base stratifies into three tiers: entertainment conglomerates with transmedia ecosystems, dedicated toy manufacturers with electronics integration capabilities, and hardware-originated startups with software-native architectures. Consolidation pressure concentrates in the middle tier as subscription revenue models favor platform scale. Dominant competitive moves include direct-to-educator distribution bypasses and pre-certified component module sourcing for EU AI Act compliance acceleration.
Within the entertainment-licensing tier, Mattel and Hasbro occupy positions that exemplify divergent supply chain strategies. Mattel leverages established manufacturing partnerships to maintain cost discipline across plastic-electronic hybrid product lines. Hasbro competes through broad entertainment licensing that extends toy connectivity into transmedia storytelling ecosystems. Sphero represents the hardware-native archetype, sitting within the specialist tier where sensor-embedded locomotion platforms command premium positioning among early school age segments.
| Leading Market Players |
|---|
| Mattel |
| Hasbro |
| LEGO Group |
| VTech |
| Sphero |
| Sony Corporation |
| WowWee Group |
| Wonder Workshop |
| Spin Master |
| Others |
Cost & Logistics Intelligence
Institutional procurement committees in United States suburban school districts concentrate hardware purchasing power, driving subscription-unbundled pricing models that separate Bluetooth-enabled base units from AR content licensing fees.
Pricing Analysis
Input-cost pass-through from lithium polymer cell volatility and silicon wafer fabrication bottlenecks compresses margins for sensor-embedded product lines below 28nm process nodes. Three-tier pricing structure across premium interactive robots, standard Bluetooth-enabled dolls, and economy RFID action figures reflects certification grade differentiation and volume scale. Pricing pressure stems from raw material concentration in Chinese processing facilities exposing margin structures to export quota fluctuations. Mass retail SKUs face the highest price sensitivity, while institutional pilot programs absorb premium positioning for EU AI Act pre-certified modules.
Supply Chain Analysis
Reverse-logistics flows for firmware-upgraded voice-interactive systems create refurbishment channels extending product lifecycles while complicating COPPA-mandated data deletion protocols. Component assembly concentrates in China, Vietnam, and India under the PLI scheme, drawing from lithium polymer cells, mature-node microcontrollers, and ABS polycarbonate shells. Single-source vulnerability in Shenzhen Bluetooth module suppliers exposes brands to MIIT certification delays. Distribution runs through direct-to-educator portals and traditional retail with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected toys constitute a late-cycle quality story as parental purchasing committees shift procurement toward GDPR Article 8 and COPPA-compliant STEM-integrated systems with deterministic processing boundaries.
For Market Incumbents: To counter subscription revenue fragmentation by hardware-content unbundling, Mattel and Hasbro should deepen backward integration into microcontroller firmware development while securing multi-year institutional procurement contracts through pre-certified EU AI Act component modules. For New Entrants and Emerging Players: Direct-to-educator distribution portals represent the most penetrable channel for voice-interactive eldercare crossover applications, targeting aging-in-place segments in Japan and Germany with minimal hardware redesign from pediatric companion robot architectures. For Investors and Strategic Acquirers: Entertainment conglomerates with transmedia ecosystems are the most active acquirers in this space, consolidating hardware-native startups to capture subscription recurring revenue models. Long-term viability hinges on edge computing architecture differentiation and AR content library depth. Practitioners should monitor EU AI Act third-party conformity assessment timelines as inflection indicators for voice-enabled product launches.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Accelerates conformity assessment timelines for German and French distributors by 8-14 months. |
| Direct-to-Educator Distribution Launch | Bypasses retail margin compression while capturing bulk pricing power through institutional procurement portals. |
| Edge Computing Architecture Migration | Eliminates COPPA-triggered data transmission events via TensorFlow Lite Micro runtime adoption. |
| Voice-Interactive Eldercare Crossover | Extends companion robot platforms into Japan's aging-in-place applications with minimal hardware redesign. |
| India PLI Scheme Manufacturing Footprint | Reduces landed costs for Bluetooth module integration serving price-sensitive emerging middle-class segments. |
Research Approach
Bottom-up preschool and early school age demand modeling reconciled against top-down electronics manufacturing capacity tracking forms the analytical core. Primary interviews with toy product development executives, institutional procurement coordinators, regulatory compliance officers, and edtech curriculum specialists were validated against secondary sources including FTC COPPA enforcement actions, EU AI Act implementation guidance, MIIT wireless device certification databases, and India PLI scheme beneficiary disclosures. Triangulation between supply-side component procurement patterns and demand-side subscription revenue recognition ensures segmentation integrity.
Input-output matrix framing connects Bluetooth Low Energy 5.3 module shipments, lithium polymer cell procurement volumes, and AR content licensing transactions across product type, technology protocol, age group, and material composition dimensions. CAGRs were derived from slope-intercept modeling of hardware replacement cycles and content renewal rates. Forecast inputs include EU AI Act enforcement timeline assumptions and India BIS certification throughput capacity.
Regulatory enforcement delays, raw material export quota fluctuations, and firmware vulnerability disclosure patterns are the dominant revision risks. Forecasts reflect documented assumptions regarding interoperability standard convergence and institutional procurement budget continuity. Practitioners should monitor FTC COPPA consent framework updates and EU AI Act high-risk classification guidance amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Bounce House Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Drone for Kids Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Global Fidget Toys Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Pre-School Games and Toys Market
Toys and Games
Glow Sticks Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Toy Cars Market
Toys and Games
Plush Toy Market
Toys and Games
Male Sex Toys Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Toy Collectibles Market
Toys and Games
Australia Toys and Games Market