
 Australia Toys and Games Market | 2026-2036
Australia Toys and Games Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Toys and Games Market Outlook
China's manufacturing expansion is reshaping supply availability for Australian importers. Moose Toys leverages its Melbourne headquarters to sustain design-led product development for domestic and export markets. The LEGO Group anchors premium construction toy demand through controlled retail partnerships and direct-to-consumer channels. Mattel Inc. competes across multiple price tiers with established doll and vehicle franchises.
Toys and games encompass physical play products manufactured from plastics, textiles, wood, and electronic components, designed for entertainment, education, and developmental stimulation across childhood stages. Injection molding and automated assembly dominate plastic toy production, while hand-finished elements persist in premium collectible segments. Board games and puzzles retain structural importance as screen-time moderation drives family-oriented purchasing among Australian households. Action figures and dolls capture concentrated margin pools through licensed entertainment properties and seasonal release cycles. Online retail channels extend fastest among sales channels, though specialty toy retailers maintain experiential differentiation.
The Australian Competition and Consumer Commission administers mandatory toy safety standards including AS/NZS ISO 8124, while the Therapeutic Goods Administration oversees products with therapeutic claims. These frameworks elevate compliance costs for entrants but reinforce quality positioning for established suppliers. Stakeholders must monitor evolving digital privacy regulations affecting connected toys and app-integrated play experiences.
Market Dynamics
Screen-time moderation mandates from Australian health authorities are redirecting household expenditure toward tactile play products, compressing traditional seasonality and elevating year-round educational toy procurement.
Growth Catalysts
- AS/NZS ISO 8124 enforcement:Mandatory safety testing protocols elevate entry barriers for low-quality imports, protecting margin pools for compliant domestic distributors.
- Preschool learning toy demand:Australian parents prioritize developmental stimulation products, expanding addressable market beyond entertainment-only purchases.
- New South Wales retail corridor concentration:Sydney's specialty toy precincts generate experiential differentiation that sustains premium pricing power.
Market Restraints
- China supply concentration:Australian importers face concentrated manufacturing dependency across injection-molding and electronics assembly capabilities.
- Polymer resin cost volatility:Petroleum-derived plastic feedstock fluctuations compress margin predictability for mid-tier producers.
- AS/NZS compliance timeline:Mandatory safety certification cycles extend product launch windows by four to eight months versus unregulated markets.
Strategic Opportunities
- Tasmania underpenetration:Hobart and Launceston retail networks carry limited specialty toy depth, creating whitespace for curated distribution partnerships.
- App-integrated play convergence:Bluetooth-enabled construction sets bridge physical-digital engagement, commanding price premiums from tech-forward households.
- Direct-to-consumer channel expansion:Subscription-box models bypass traditional retail markups while capturing recurring revenue streams.
Industry Challenges
- Licensed IP negotiation complexity:Entertainment property agreements require multi-year commitments with minimum volume guarantees that strain working capital.
- Connected toy cybersecurity certification:ACMA radio communications compliance and emerging privacy frameworks demand specialized technical talent scarce in Australian manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Toys and Games Market |
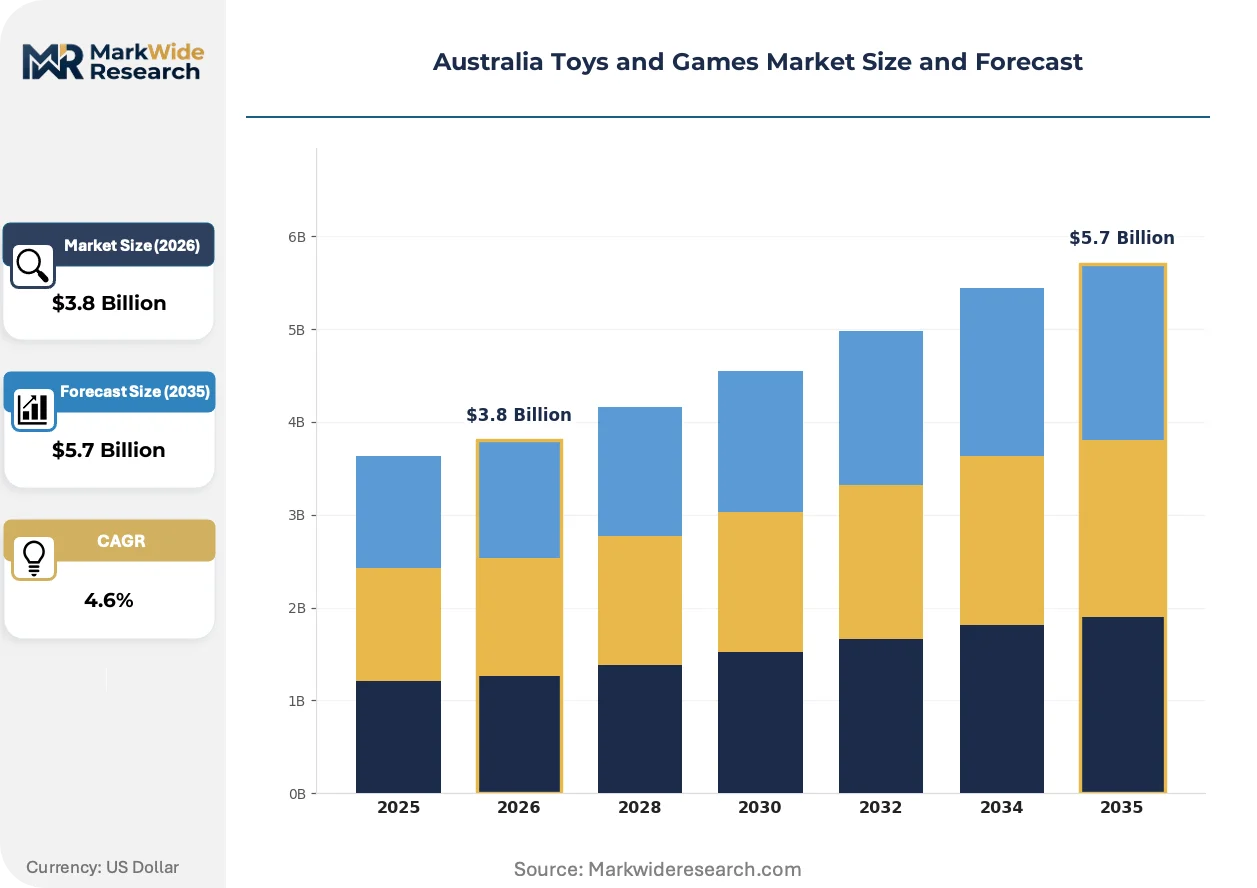
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Board Games, Dolls, Puzzles Age Group: Infants, Toddlers, Pre-Teens, Teens Sales Channel: Online Retail, Department Stores, Specialty Stores, Toy Retailers Theme: Educational, Fantasy, Adventure, Sports |
| Companies Covered | Moose Toys, Bandai Namco Holdings, The LEGO Group, MGA Entertainment, VTech Holdings Ltd, Mattel Inc., Spin Master Corp., Nintendo Co., Ltd., Hasbro Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Toys and Games Market Strategic Shifts
Physical-digital hybrid play systems are compressing traditional category boundaries, forcing suppliers to reconfigure product architectures and retail partnerships simultaneously.
Biodegradable bioplastic formulations derived from cornstarch and sugarcane waste are rendering obsolete petroleum-dependent ABS and PVC in premium construction sets. Melbourne-based design studios specify these materials for export-bound product lines. The shift is compressing conventional polymer supply contracts and elevating raw material qualification timelines.
TGA therapeutic claims oversight is expanding beyond medical devices into sensory and developmental toys marketed with specific cognitive benefits. Suppliers must now substantiate efficacy claims through clinical evidence or reclassify products as general merchandise. Victoria-based distributors are restructuring marketing collateral to pre-empt enforcement action.
Australian household purchasing has pivoted toward experiential retail environments where product demonstration and child engagement replace transactional efficiency. Specialty toy retailers in Melbourne and Sydney are expanding floor space for interactive play zones while shrinking inventory depth. Regional Queensland and Western Australia markets lag this transition, sustaining conventional big-box purchasing patterns.
Australia Toys and Games Market Segmentation
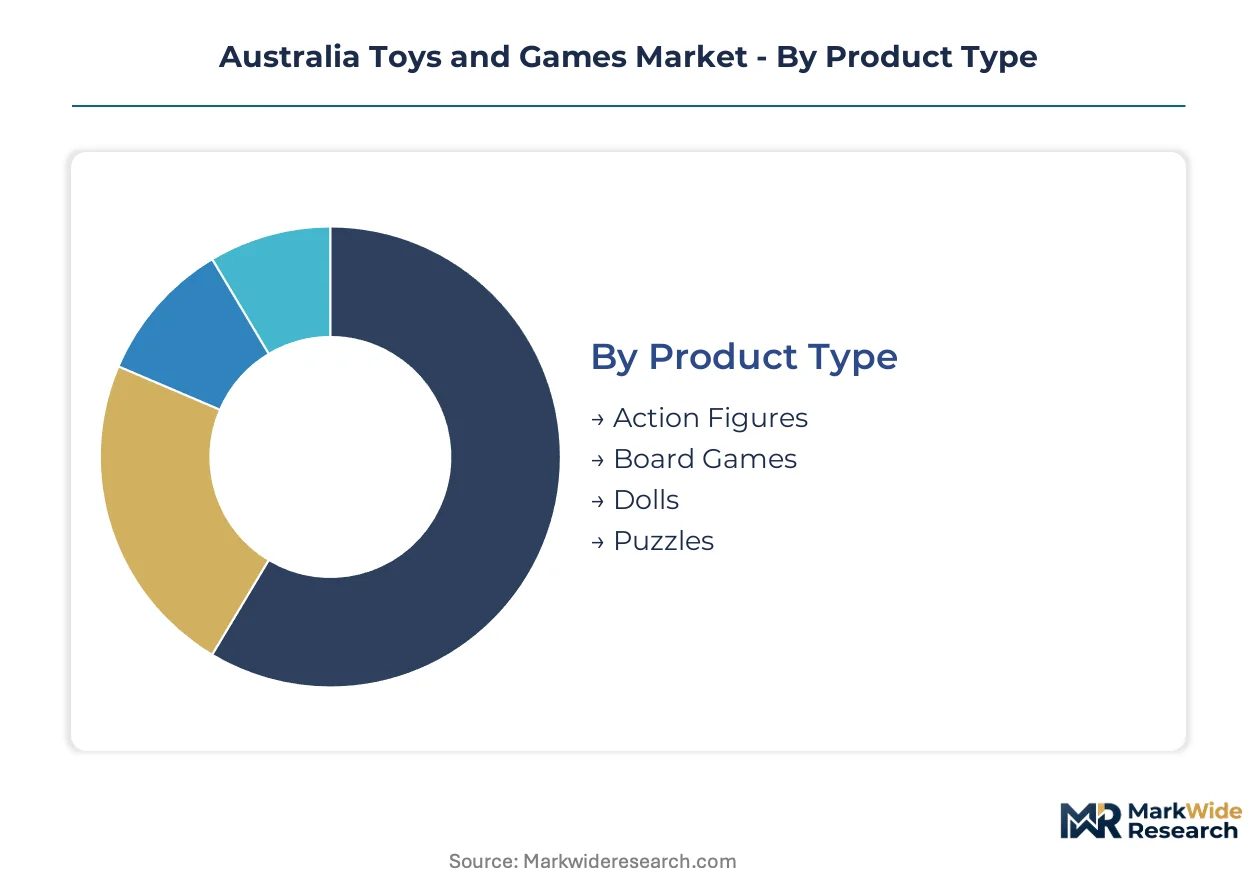
Segmentation in the Australian toys and games market reveals divergent inventory velocities and margin architectures across product categories. Distinct replenishment cycles, age-based safety compliance tiers, and channel-specific experiential requirements shape supplier resource allocation and retail partnership priorities.
Product Type:
Board Games and Puzzles turn inventory slowest due to extended play lifecycles and gift-giving seasonality, while Action Figures and Dolls rotate fastest through licensed entertainment release windows.
- Action Figures:Injection-molded articulated figures with licensed entertainment IP drive concentrated margin pools through theatrical and streaming release synchronization. Melbourne and Sydney specialty retailers pre-order six months ahead of film launches to secure allocation.
- Board Games:Cardboard, wood, and plastic component sets with rulebook-driven mechanics exhibit 18-24 month sales tails. Family screen-time moderation policies in New South Wales and Victoria sustain demand beyond traditional holiday peaks.
- Dolls:Fashion dolls and collectibles with textile accessories and hair-rooting features target developmental role-play stages. AS/NZS ISO 8124 small parts testing extends certification timelines for infant-directed variants.
- Puzzles:Die-cut cardboard interlocking piece sets range from 24-piece toddler formats to 3000-piece adult collector editions. Hobart and Launceston retail networks carry limited puzzle depth relative to mainland state capitals.
Board Games dominate installed base through multi-year household retention. Action Figures is where expansion concentrates.
Age Group:
Cost tier stratification separates premium developmental products for Infants from mass-market entertainment purchases for Teens, with compliance burden escalating at younger age brackets.
- Infants:Sensory and motor skill stimulation products featuring food-grade silicones and untreated hardwoods command price premiums. TGA therapeutic claims oversight now captures products marketed with specific cognitive benefit language.
- Toddlers:Preschool learning toys with shape-sorting, stacking, and early numeracy features exhibit fastest inventory turnover among age brackets. Australian parent prioritization of developmental stimulation expands addressable market beyond pure entertainment.
- Pre-Teens:Construction sets, craft kits, and collectibles bridge physical and digital engagement through app integration. Regional Queensland and Western Australia markets sustain conventional big-box purchasing patterns for this bracket.
- Teens:Strategy board games, advanced construction systems, and hobby collectibles target discretionary spending from part-time employment income. Specialty retailers in Sydney's retail corridors generate experiential differentiation that sustains premium pricing power.
Toddlers segment dominates installed base through repeat purchase frequency. Pre-Teens is where expansion concentrates.
Sales Channel:
Volume concentration favors Online Retail for replenishment purchases, while margin protection concentrates in Specialty Stores where demonstration and engagement justify price premiums.
- Online Retail:Direct-to-consumer platforms and marketplace listings capture recurring revenue through subscription-box models. Melbourne-based design studios leverage domestic fulfillment to compress delivery windows versus China-direct alternatives.
- Department Stores:Mid-tier toy assortments with seasonal promotional calendars target gift-giving occasions. New South Wales and Victoria department store networks carry deeper inventory than Tasmania equivalents.
- Specialty Stores:Curated assortments with interactive play zones and staff expertise sustain premium pricing. Sydney and Melbourne specialty toy precincts are expanding floor space for experiential differentiation.
- Toy Retailers:Dedicated toy chains with controlled retail partnerships anchor volume for major franchise properties. The LEGO Group utilizes this channel for premium construction set distribution alongside direct-to-consumer capture.
Department Stores dominate installed base through broad geographic reach. Online Retail is climbing the fastest.
Theme:
Application focus separates Educational products with TGA-adjacent therapeutic positioning from Fantasy and Adventure entertainment properties requiring licensed IP negotiation.
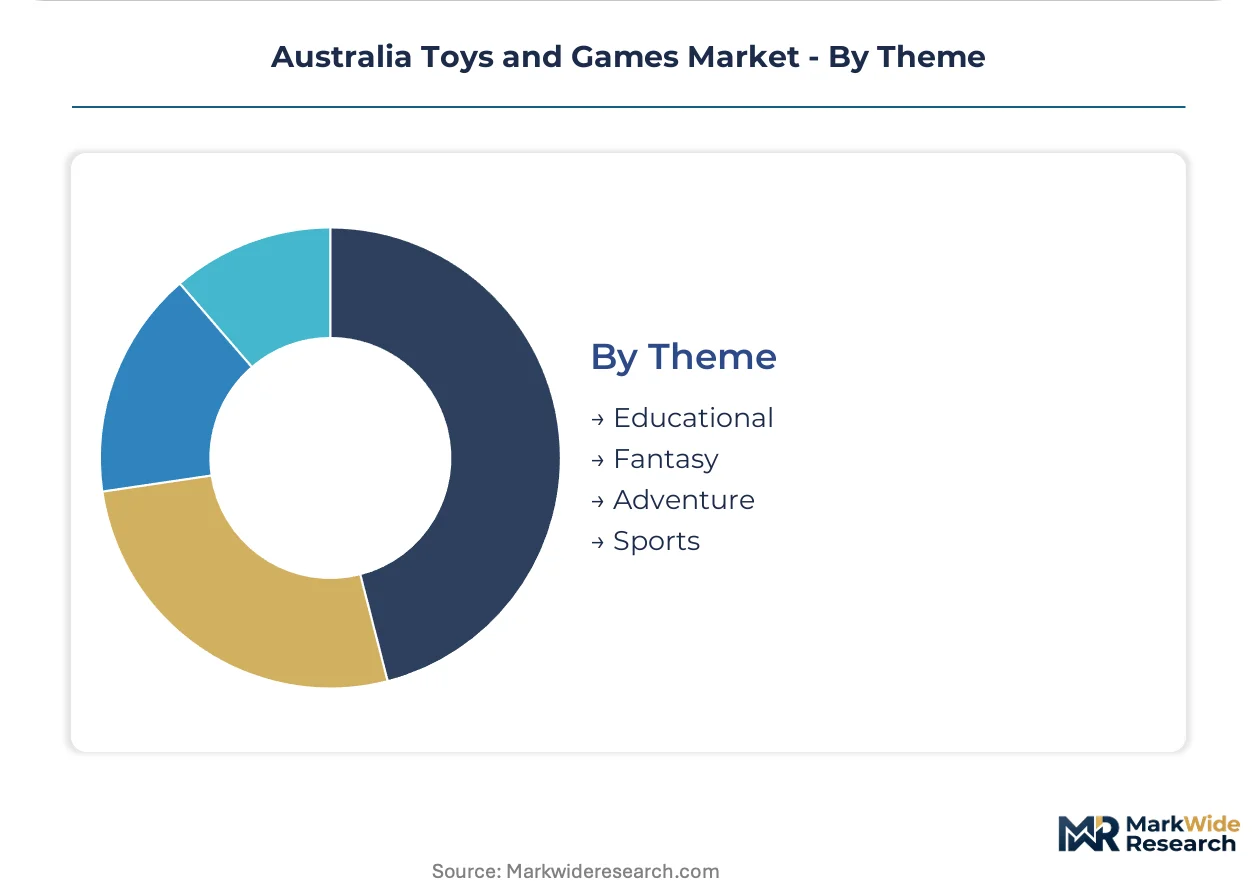
- Educational:STEM-focused construction systems, coding toys, and language development products carry explicit learning outcome marketing. Victoria-based distributors are restructuring collateral to pre-empt TGA enforcement on unsubstantiated cognitive claims.
- Fantasy:Licensed and proprietary IP spanning wizards, dragons, and magical realms drives collectible purchasing and expansion pack attachment. Multi-year licensing agreements with minimum volume guarantees strain working capital for mid-tier suppliers.
- Adventure:Exploration, rescue, and outdoor simulation themes bridge physical play with narrative engagement. Biodegradable bioplastic formulations from cornstarch and sugarcane waste render obsolete petroleum-dependent materials in premium Adventure construction sets.
- Sports:Athletic simulation products, equipment miniatures, and active play systems target physical development outcomes. Australian health authority screen-time moderation mandates redirect expenditure toward tactile Sports products.
Adventure dominates installed base through evergreen entertainment property renewal. Educational is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australian Competition and Consumer Commission enforces AS/NZS ISO 8124 safety standards that govern toy distribution across all states and territories. State-level retail concentration and regional income disparities create divergent market access conditions for suppliers.
New South Wales
Sydney's specialty toy precincts generate experiential differentiation through interactive play zones that sustain premium pricing. The ACCC's mandatory safety testing protocols elevate compliance costs for NSW-based distributors. Parramatta and Chatswood retail corridors anchor volume concentration for construction toy franchises.
Victoria
Melbourne headquarters for design-led manufacturers compress product development cycles for domestic and export markets. The Therapeutic Goods Administration oversees therapeutic claims on sensory toys marketed from Victoria-based distributors. Southbank and Chadstone retail networks carry deeper specialty toy inventory than regional equivalents.
Queensland
Brisbane and Gold Coast markets sustain conventional big-box purchasing patterns for pre-teen entertainment products. Queensland health authority screen-time moderation mandates redirect household expenditure toward tactile play systems. Cairns and Townsville retail networks carry limited specialty toy depth relative to southeast corridors.
Western Australia
Perth's geographic isolation elevates freight costs for China-direct toy imports serving Western Australian households. The state's consumer protection framework mirrors federal ACCC standards without additional state-level overlay. Fremantle and Joondalup retail precincts concentrate mid-tier toy assortment distribution.
Tasmania
Hobart and Launceston retail networks carry limited specialty toy depth, creating whitespace for curated distribution partnerships. Tasmanian household income levels compress addressable market for premium construction sets relative to mainland states. Burnie and Devonport logistics infrastructure constrains direct-to-consumer delivery windows.
Australia Toys and Games Market Competitive Environment
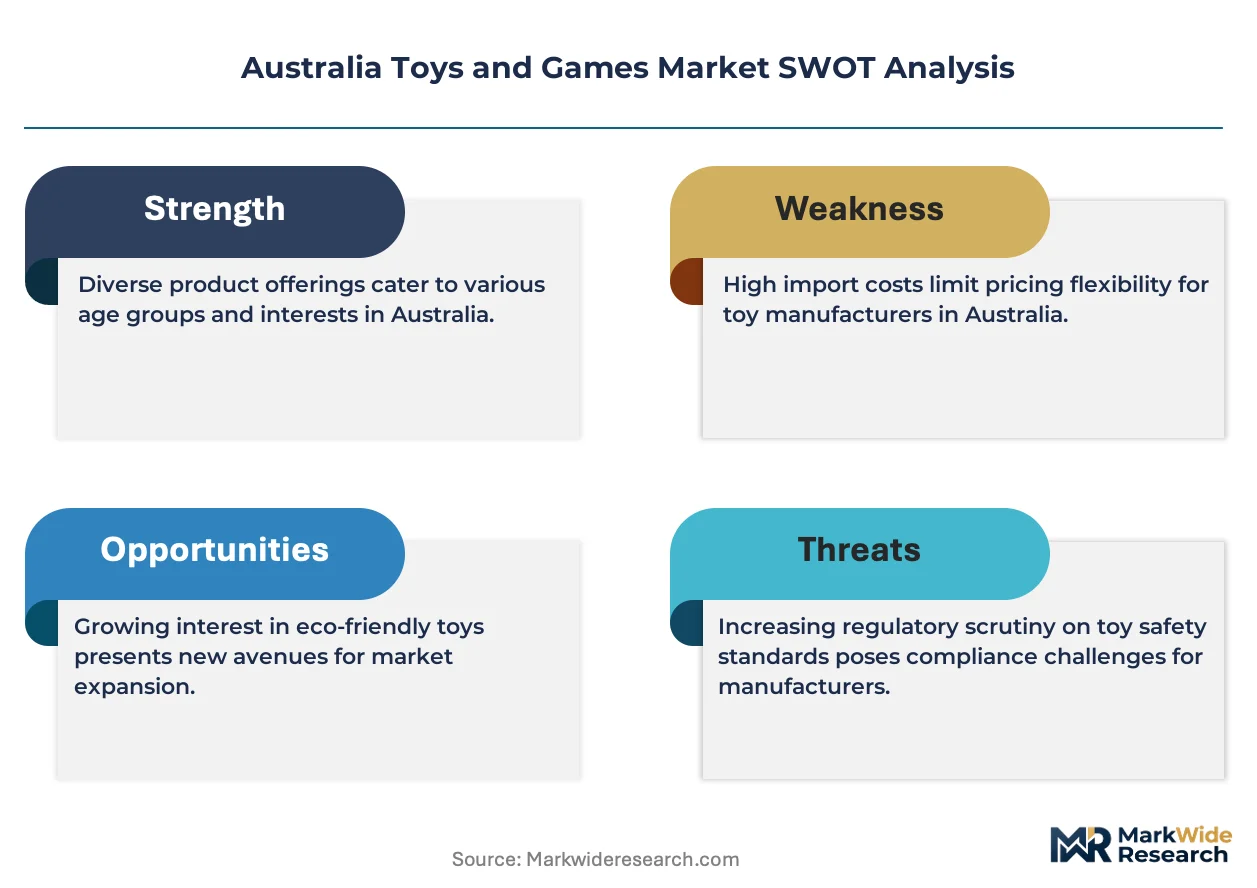
Design-led domestic developers and multinational franchise holders split the market between localized innovation and global IP leverage. The vendor base concentrates around three strategic archetypes: Melbourne-based studios with export capabilities, Asia-Pacific headquarters operations serving Australian distribution, and direct-to-consumer platforms bypassing traditional retail markups. Competitive moves center on bioplastic material qualification and experiential retail partnership expansion.
Within the domestic design-led tier, Moose Toys exemplifies Melbourne-headquartered product development for international markets. The LEGO Group anchors premium construction toy positioning through controlled channel management. Mattel Inc. occupies a position spanning multiple price tiers with established entertainment property franchises. These three represent distinct strategic postures: localized innovation, premium brand control, and diversified portfolio scale.
| Leading Market Players |
|---|
| Moose Toys |
| Bandai Namco Holdings |
| The LEGO Group |
| MGA Entertainment |
| VTech Holdings Ltd |
| Mattel Inc. |
| Spin Master Corp. |
| Nintendo Co., Ltd. |
| Hasbro Inc. |
| Others |
Value Chain & Pricing Dynamics
China supply concentration determines both tiered pricing spreads across premium construction sets and economy plastic toys and supply chain configuration for Australian importers. AS/NZS ISO 8124 compliance timelines compress margin predictability while elevating entry barriers that protect compliant domestic distributors.
Pricing Analysis
Perth's geographic isolation from Sydney and Melbourne retail corridors generates freight-adjusted price premiums of 15-25% for identical toy assortments. Three-tier pricing structure across premium, standard, and economy levels separates LEGO-controlled construction sets from mid-tier doll franchises and unbranded imports. Cost compression in economy tiers stems from polymer resin volatility and China-direct shipping rate fluctuations. Mass-market big-box buyers exhibit highest price sensitivity, while specialty store patrons accept experiential premiums for staff expertise and interactive demonstration.
Supply Chain Analysis
Contract manufacturing concentration sits with Dongguan and Shenzhen injection-molding specialists serving Moose Toys and Mattel procurement teams. Australian importers draw 80-85% of plastic toy volume from China, with residual electronics assembly anchored in Vietnam and Malaysia. Raw material dependencies span petroleum-derived ABS and PVC resins, food-grade silicones for infant products, and cornstarch-based bioplastics for premium sustainable lines. Single-source vulnerability concentrates in AS/NZS certification laboratories with four-to-eight-month testing queues. Distribution runs through Melbourne and Sydney bonded warehouses before state-level retail corridor allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preschool learning toy penetration sits below comparable developed markets, positioning the sector for early-cycle expansion as Australian health authorities elevate developmental stimulation priorities.
For Market Incumbents: Harden margin protection through backward integration into bioplastic raw material qualification and captive AS/NZS testing capacity. Secure six-month pre-order commitments from Sydney specialty retailers ahead of theatrical release windows for licensed action figure properties. Threat vectors include direct-to-consumer subscription models and TGA therapeutic claims enforcement on sensory toy marketing. For New Entrants and Emerging Players: Build out curated distribution partnerships in Hobart and Launceston where specialty toy depth remains underdeveloped. Tasmania's compressed premium pricing tolerance favors mid-tier educational assortments over construction set franchises. App-integrated play convergence offers the most penetrable wedge, commanding price premiums through Bluetooth-enabled STEM products absent from incumbent catalogs. For Investors and Strategic Acquirers: The market sits at a penetration acceleration phase that favors design-led domestic studios with export-ready bioplastic product lines. Long-term viability hinges on regulatory compliance infrastructure rather than pure IP licensing scale. Acquisition targets should demonstrate AS/NZS certification expertise and Melbourne-based R&D proximity. Monitor quarterly AS/NZS enforcement action filings and China shipping rate indices as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastic Material Qualification | Melbourne design studios specify cornstarch-derived formulations to preempt petroleum cost volatility. |
| Direct-to-Consumer Channel Expansion | Subscription-box models bypass traditional retail markups while capturing recurring revenue from Australian households. |
| AS/NZS Certification Investment | Domestic testing capacity compresses four-to-eight-month launch windows versus offshore laboratory queues. |
| Tasmania Distribution Partnership | Hobart and Launceston whitespace offers first-mover positioning before mainland specialty retailers expand south. |
| App-Integrated Product Development | Bluetooth-enabled construction sets bridge physical-digital engagement for tech-forward New South Wales and Victoria parents. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs import records, ACCC enforcement filings, and specialty retailer inventory audits. Primary interviews engaged product development directors at Melbourne-headquartered design studios, category buyers at Sydney department store networks, and compliance officers navigating AS/NZS ISO 8124 certification protocols. Secondary validation drew from Therapeutic Goods Administration guidance documents, Australian Bureau of Statistics household expenditure surveys, and China customs export data. Bottom-up SKU-level demand modeling triangulates against top-down state-level retail corridor concentration analysis.
Forecast inputs span product type segmentation across action figures, board games, dolls, and puzzles; age group stratification from infants through teens; and sales channel differentiation between online retail, department stores, specialty stores, and dedicated toy chains. CAGRs derive from regression analysis of historical import volume trajectories and projected household formation patterns across the analysis window. Industry-specific inputs include AS/NZS compliance timeline elasticity and bioplastic raw material adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive direct-to-consumer investment by multinational franchise holders would shift outcomes beyond modeled ranges. Quarterly review of ACCC enforcement action velocity and China polymer resin futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
United States Toys Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Model Train Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Construction Toys Market
Toys and Games
Action Figures Market
Toys and Games
Global Toys Market
Toys and Games
Bubble Blower Market
Toys and Games
Air Hockey Table Market
Toys and Games
Animation Toys Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
US Sex Toys Market
Toys and Games
Remote Control Toys Market