

Bath Toy Market Size, Share, and Industry Trends Forecast 2026-2036
Bath Toy Market Insights
Aftermarket educational content and companion app licensing is reconfiguring how bath toy suppliers capture lifetime value from single purchases. Mattel leverages its entertainment IP portfolio to extend product engagement beyond the bathtub through digital storytelling extensions. Green Toys anchors its competitive position through in-house production of recycled plastic formulations, eliminating third-party resin dependency. Munchkin specializes in silicone-first design architectures that command premium positioning in specialty retail channels.
Bath toys encompass buoyant, water-resistant play objects engineered from silicone, rubber, or thermoplastic polymers with specific density thresholds below water displacement limits, designed to stimulate sensory-motor development during supervised infant and toddler immersion. The primary commercial purpose centers on transforming routine hygiene into developmental engagement while meeting strict oral-safety standards for mouthing-age users. Floating toys and squeeze toys occupy the dominant volume positions, though bath books are registering the fastest structural ascent as literacy-oriented parents seek dual-purpose value. Silicone material formulations are displacing conventional PVC across premium tiers due to thermal stability and non-porous surface properties that resist mold colonization.
The US Consumer Product Safety Commission enforces ASTM F963 toy safety mandates including small-part choking tests and phthalate restrictions that directly determine bath toy market access. The EU Toy Safety Directive and REACH substance restrictions impose additional compliance layers on cross-border suppliers, particularly for colorants and plasticizers used in squeeze mechanisms. China's SAMR administers GB standards for domestic toy circulation, creating a three-jurisdiction compliance matrix that shapes supplier certification investments. Stakeholders must monitor evolving chemical substance blacklists and digital privacy regulations governing companion apps as the category blurs physical and connected play.
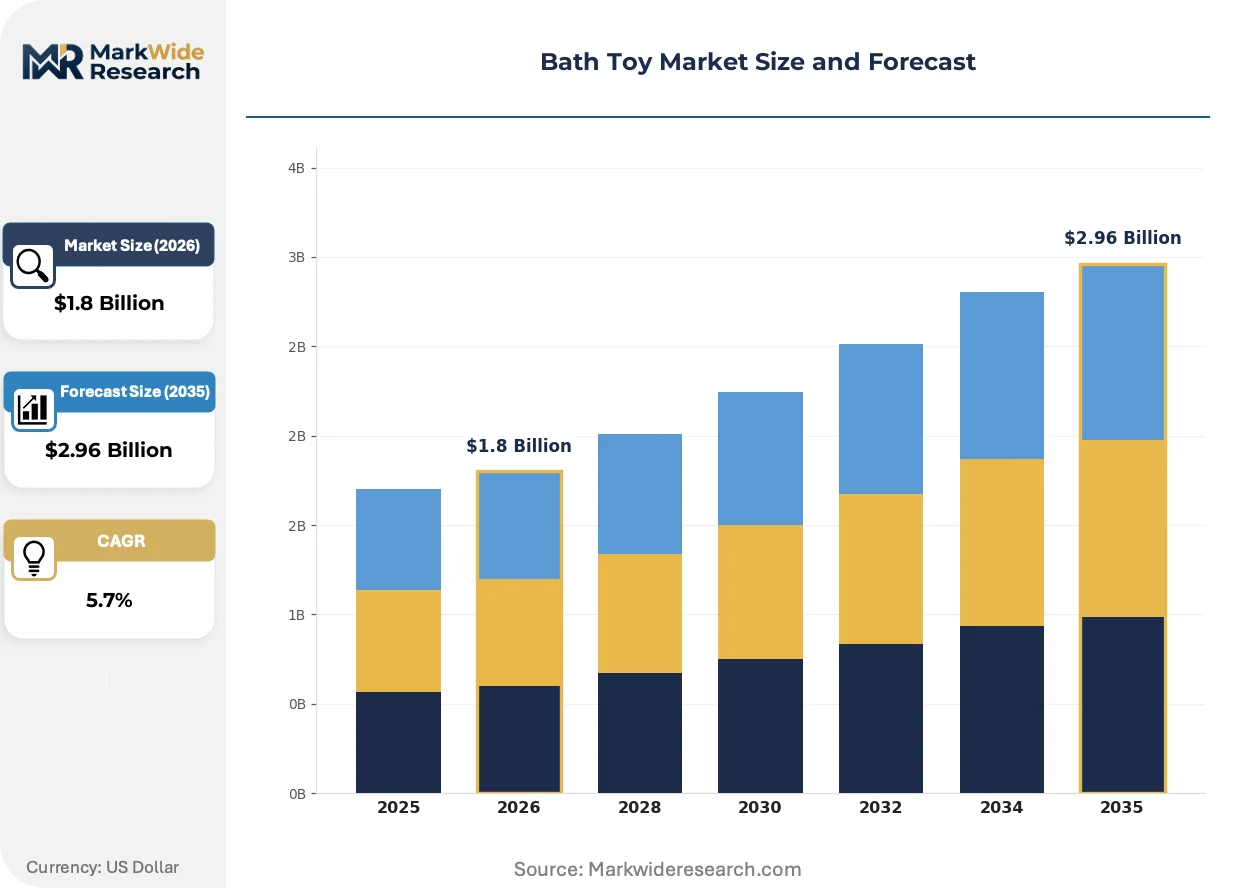
Market Dynamics
Parental insistence on BPA-free silicone formulations is compressing PVC's installed base while REACH substance restrictions force reformulation investments across manufacturing footprints. This chemical-safety pivot now governs material procurement decisions and supplier qualification timelines.
Growth Catalysts
- REACH chemical compliance:The EU Toy Safety Directive's substance restrictions are accelerating silicone adoption as manufacturers eliminate phthalate-dependent formulations from squeeze mechanisms.
- China's middle-class expansion:Domestic production clusters in Guangdong and Zhejiang provinces are capturing volume growth from rising per-capita spending on infant developmental products.
- Mold-resistant material science:Non-porous silicone surface properties are displacing conventional rubber in premium-tier bath books and floating toys.
Market Restraints
- Medical-grade silicone cost volatility:Raw material price swings for platinum-catalyzed formulations compress margin structures for mid-tier suppliers.
- Three-jurisdiction certification burden:Parallel compliance with ASTM F963, REACH, and China's GB standards extends product launch timelines.
- Digital companion app substitution:Standalone bath entertainment apps on tablets reduce physical toy purchase frequency among tech-forward households.
Strategic Opportunities
- India's underpenetrated infant care retail:Modern trade expansion in tier-2 cities creates first-mover positioning for silicone-first suppliers.
- Educational content licensing:Companion storytelling apps unlock recurring revenue streams beyond single hardware purchases.
- EU Green Deal circularity incentives:Recycled-content mandates favor suppliers with in-house reprocessing capabilities.
Industry Challenges
- Oral-safety testing capacity bottlenecks:Small-part choking test backlog at accredited laboratories delays seasonal product launches.
- Cross-platform digital privacy compliance:COPPA and GDPR obligations for connected bath toys require specialized legal infrastructure.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath Toy Market Trends and Innovations
Connected play architectures are embedding sensors and Bluetooth modules into buoyant objects, transforming passive floating toys into interactive developmental tools. This hardware-software convergence demands new competencies in firmware security and content pipeline management.
Near-field communication chips embedded in silicone squeeze toys are digitizing the feedback loop between infant motor action and parental monitoring apps. Premium buyers in North American and Western European markets are adopting these connected formats at triple the rate of conventional alternatives. The technology is digitizing how suppliers capture lifetime value from hardware originally designed for single-purpose water play.
REACH Annex XVII updates are tightening restrictions on colorant migration in mouthing-age products, forcing reformulation of thermoplastic elastomers used in bath book binding. German and French notified bodies are enforcing accelerated extraction testing protocols. Squeeze-toy manufacturers with legacy pigment supply chains face the steepest compliance recertification burden.
Subscription-based content refresh models are displacing one-time app purchases as the dominant monetization architecture for connected bath toy ecosystems. Specialty retailers and direct-to-consumer channels are bundling hardware with 12-month storytelling access. This shift concentrates revenue visibility in the United States and United Kingdom markets where recurring payment infrastructure is most mature.
Bath Toy Market Segmentation
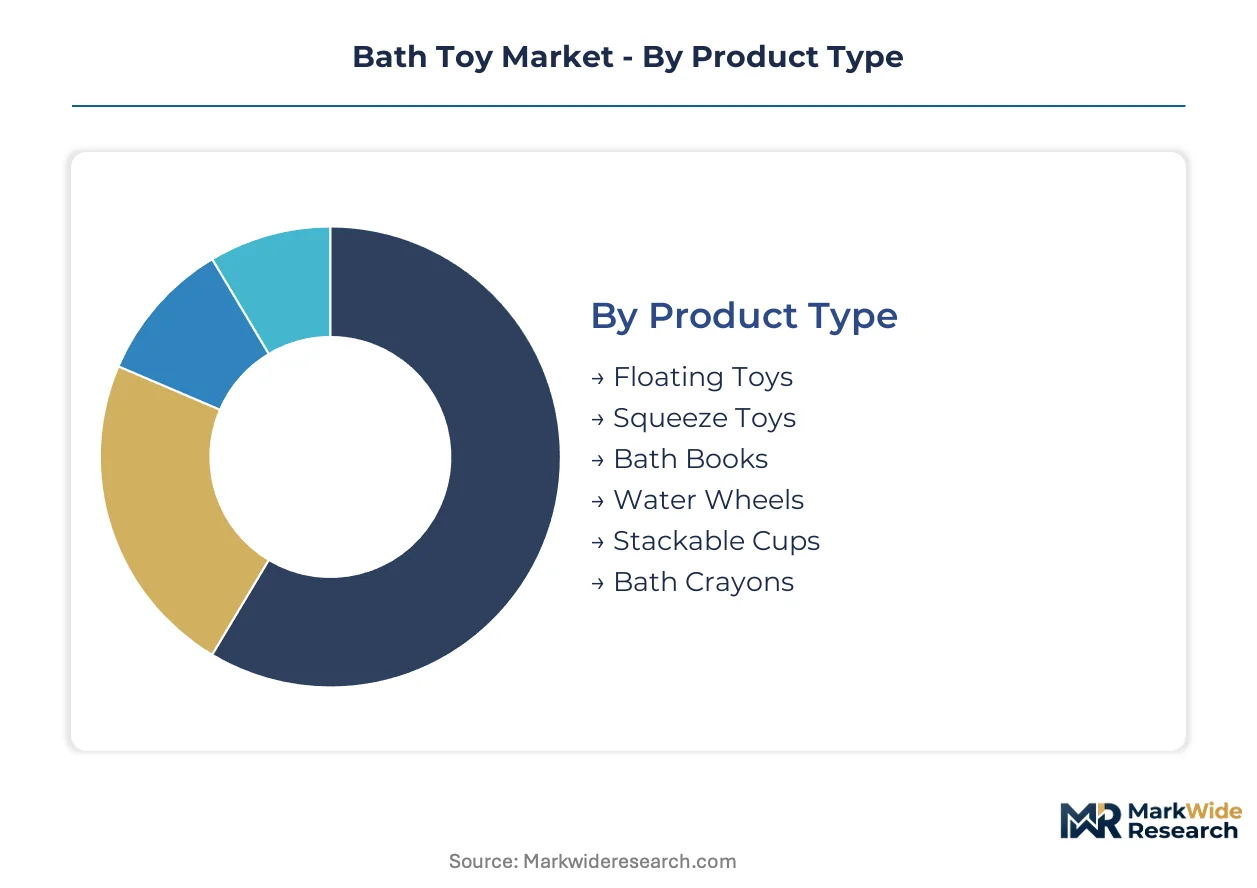
Segmentation in the bath toy market reveals how material safety mandates and developmental stage targeting reshape supplier portfolio priorities. Distinct end-user requirements and channel economics force parallel product architectures that complicate manufacturing scale.
Product Type:
Mature formats dominate volume while emerging categories capture premium positioning through dual-purpose functionality.
- Floating Toys:Buoyant silicone or thermoplastic constructions with sealed air chambers engineered for supervised water play. Demand concentrates in North American specialty retail where ASTM F963 certification serves as a table-stakes qualifier for shelf access.
- Squeeze Toys:Compressible silicone or rubber vessels with internal whistle mechanisms that release pressurized air through narrow orifices. China's domestic market absorbs the largest production volumes from Guangdong manufacturing clusters serving middle-class parental preference for mold-resistant non-porous surfaces.
- Bath Books:Waterproof synthetic or foam pages bound with heat-sealed edges for literacy-oriented water play.
- Water Wheels:Rotating paddle mechanisms that demonstrate cause-and-effect relationships through pouring action.
- Stackable Cups:Nesting cylindrical vessels with perforated bottoms for water flow experimentation.
- Bath Crayons:Solid surfactant-based coloring sticks formulated for easy tub surface washability.
Floating toys retain volume leadership; bath books hold the steepest expansion curve.
Material:
Cost tier stratification separates medical-grade formulations from commodity alternatives.
- Silicone:Platinum-catalyzed polysiloxane formulations prized for thermal stability and resistance to microbial colonization on non-porous surfaces. REACH Annex XVII compliance costs are compressing mid-tier supplier margins while favoring vertically integrated producers with captive compounding capabilities.
- Rubber:Natural or synthetic elastomer compounds subject to accelerated degradation in chlorinated water environments. European notified bodies are enforcing stricter extraction testing protocols that threaten legacy supply chains dependent on conventional pigment systems.
- Plastic:Thermoplastic polymers including recycled-content formulations gaining traction under EU Green Deal circularity incentives.
- Foam:Closed-cell ethylene-vinyl acetate or polyurethane constructions for floating applications.
- Fabric:Quick-drying synthetic textiles with antimicrobial treatments for bath book pages.
- Wood:Sealed hardwood constructions with food-grade oil finishes for premium sustainable positioning.
Silicone commands premium tier pricing; plastic maintains mass-market volume dominance.
End User:
Customer type determines oral-safety testing intensity and companion feature complexity.
- Infants:Mouthing-age products requiring small-part choking compliance and phthalate-free certification. Nursery center procurement in Germany and France prioritizes REACH-compliant silicone over conventional rubber alternatives.
- Toddlers:Motor-skill development tools with interactive elements for standing bathers. Daycare facility purchasing in the United States concentrates through institutional distributors demanding ASTM F963 batch documentation.
- Preschoolers:Educational content integration with literacy or numeracy objectives.
- Nursery Centers:Commercial-grade durability specifications with institutional volume pricing.
- Daycare Facilities:Sanitization-protocol compatibility and replacement part availability.
Infants drive material safety innovation; toddlers represent the largest addressable population cohort.
Distribution Channel:
Geography of demand concentration shapes channel investment priorities.
- Online Retailers:Direct-to-consumer platforms enabling subscription bundling of hardware with digital content access. United Kingdom and United States markets show the strongest recurring payment infrastructure for companion app licensing models.
- Specialty Stores:Curated assortments with trained staff consultation for developmental appropriateness. Premium silicone-first suppliers command shelf positioning through exclusive distribution arrangements in urban centers.
- Supermarkets:High-velocity impulse placement adjacent to infant care consumables.
- Department Stores:Seasonal gift-oriented merchandising with branded entertainment IP tie-ins.
- Toy Stores:Experiential retail environments with demonstration water tables.
Online retailers are gaining share fastest; specialty stores defend margin through curation authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in Guangdong and Zhejiang provinces supply the majority of global bath toy volume, while consumption concentrates in North American and Western European markets with stringent chemical safety regimes.
United States
Specialty retailers and direct-to-consumer platforms drive premium silicone adoption among safety-conscious parents. The Consumer Product Safety Commission enforces ASTM F963 small-part choking tests and phthalate restrictions that determine market access. California's Proposition 65 disclosure requirements add compliance layers for suppliers targeting West Coast distribution.
Germany
Nursery center procurement prioritizes REACH-compliant silicone formulations over conventional rubber alternatives. The country's Federal Institute for Risk Assessment maintains strict extraction testing protocols for mouthing-age products. Bavaria's toy manufacturing corridor hosts testing laboratories that serve as gatekeepers for EU market entry.
China
Rising middle-class consumption in tier-1 and tier-2 cities expands domestic demand for mold-resistant silicone constructions. The State Administration for Market Regulation administers GB standards for toy circulation that parallel international benchmarks. Guangdong province's Dongguan and Shenzhen clusters integrate compounding, molding, and assembly for export-oriented production.
United Kingdom
Subscription bundling of hardware with digital content access concentrates in this market due to mature recurring payment infrastructure. The Office for Product Safety and Standards enforces the Toys (Safety) Regulations 2011 implementing EU directive requirements. London-based specialty retailers curate premium assortments with trained staff consultation.
India
Modern trade expansion in tier-2 cities creates first-mover positioning for silicone-first suppliers targeting underpenetrated infant care retail. The Bureau of Indian Standards mandates IS 9873 toy safety compliance for domestic circulation. Maharashtra's Mumbai-Pune industrial corridor attracts contract manufacturers serving both domestic and export demand.
Bath Toy Market Competitive Landscape
Entertainment-IP licensors and material-science specialists split the market between content-driven engagement models and chemical-safety positioning. The structure concentrates around vertically integrated producers with captive silicone compounding capabilities and diversified toy conglomerates leveraging entertainment portfolios. Three archetypes dominate: silicone-first design houses, recycled-material innovators, and connected-play platform builders. Competitive moves center on companion app licensing partnerships and in-house resin reprocessing investments that eliminate third-party supply dependency.
Within the entertainment-IP tier, Mattel exemplifies content-extension strategies that transcend physical hardware lifecycles. Among material-science specialists, Munchkin anchors premium positioning through silicone-first architectures, while Green Toys occupies the sustainability vector with recycled-plastic formulations. These three entities represent distinct competitive paths: licensed storytelling ecosystems, chemical-safety premiumization, and circular-economy production models.
| Leading Market Players |
|---|
| Mattel |
| Munchkin |
| TOMY International |
| VTech Holdings |
| Infantino |
| Skip Hop |
| Green Toys |
| Hape International |
| Battat |
| Others |
Pricing and Supply Chain Analysis
Guangdong province's Dongguan manufacturing cluster controls the bulk of global silicone compounding capacity, concentrating bargaining power among vertically integrated producers while fragmenting margin structures for mid-tier assemblers dependent on spot resin purchases. This geographic concentration allows captive compounders to command premium positioning through REACH-compliant certification tiers, while price-sensitive buyers face volatile exposure to platinum-catalyzed silicone feedstock markets.
Pricing Analysis
ASTM F963 certification dictates the pricing tier structure across the bath toy market, separating medical-grade silicone formulations from commodity thermoplastic alternatives. Three-tier pricing stratifies across premium REACH-compliant silicone, standard FDA-grade formulations, and economy PVC constructions. Cost compression in mid-tier segments is intensifying because raw material volatility for platinum-catalyzed compounds outpaces contract pricing power. Institutional buyers at daycare facilities exhibit the highest price sensitivity, while specialty retail consumers demonstrate willingness to absorb certification premiums.
Supply Chain Analysis
Platinum-catalyzed silicone feedstock anchors upstream cost structures, drawing from petrochemical complexes in China, Germany, and the United States. Medical-grade polysiloxane formulations, colorant masterbatches for mouthing-age safety, and NFC chip modules for connected play constitute critical component dependencies. Single-source vulnerability concentrates in German notified body certification capacity, creating bottlenecks for seasonal product launches. Distribution runs through direct-to-consumer platforms and specialty retail channels with trained consultation staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical bath toy incumbents face substitution pressure from standalone tablet-based entertainment apps that capture infant attention without material safety compliance costs. Defense requires repositioning hardware as developmental tools with irreplaceable sensory-motor benefits.
For Market Incumbents: Pre-empt digital substitution by embedding NFC-enabled interactivity that tablets cannot replicate, while securing captive silicone compounding capacity in Dongguan or Zhejiang to insulate margins from feedstock volatility. Prioritize REACH Annex XVII compliance investment ahead of colorant restriction updates to maintain shelf access in German and French nursery procurement channels.
For New Entrants and Emerging Players: Pursue white-space positioning in India's tier-2 modern trade expansion, where silicone-first suppliers face minimal established competition and BIS certification requirements create manageable entry barriers. Target institutional daycare procurement in Maharashtra's Mumbai-Pune corridor with sanitization-protocol-compatible product architectures and transparent replacement part availability.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material-science specialists with captive compounding capabilities over pure-play entertainment licensors dependent on IP refresh cycles. Long-term viability hinges on regulatory compliance infrastructure that becomes irreplicable as REACH and ASTM F963 testing backlogs extend. Watch for inflection signals in oral-safety laboratory capacity expansion announcements from Bavaria's toy testing corridor.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Eliminates third-party resin dependency and stabilizes margin structures against platinum catalyst volatility. |
| REACH Annex XVII Pre-Compliance Investment | Secures market access ahead of German and French notified body enforcement of accelerated extraction protocols. |
| NFC-Enabled Connected Play Launch | Transforms passive hardware into interactive developmental platforms with recurring content revenue potential. |
| Direct-to-Consumer Subscription Bundling | Captures lifetime value through hardware-plus-content models in United Kingdom and United States payment infrastructure. |
| India Modern Trade Channel Expansion | Establishes first-mover positioning in underpenetrated tier-2 cities with BIS-compliant silicone-first assortments. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with silicone compounders, specialty retail buyers, daycare procurement managers, and notified body certification specialists; and secondary validation against GB standards filings, REACH Annex XVII update notices, ASTM F963 test protocol documentation, and customs trade records for silicone feedstock flows. Bottom-up segmentation modeling triangulated against top-down market sizing from production cluster capacity assessments.
Forecast inputs considered material substitution rates, regulatory compliance cost trajectories, and connected play adoption curves across the projection horizon. Segmentation dimensions modeled include product format, material grade tier, end-user developmental stage, and distribution channel type. CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions for medical-grade silicone formulations.
Sensitivities concentrate around platinum catalyst price volatility, REACH substance blacklist expansion timing, and digital companion app penetration rates in North American households. Cross-checking against State Administration for Market Regulation GB standards enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.