
 K-12 Instructive Toy Market | 2026-2036
K-12 Instructive Toy Market Size, Share, and Industry Trends Forecast 2026-2036
K-12 Instructive Toy Market Insights
ASTM F963 certification is rotating as the primary gate for North American market access, forcing smaller manufacturers toward third-party testing investments. LEGO Group leverages its captive manufacturing network across Denmark and Mexico to sustain margin control on complex Technic sets. VTech Holdings anchors its position through vertical integration into electronic component sourcing for its KidiZoom and InnoTab lines. Melissa & Doug competes on wooden toy specialization, navigating California's Proposition 65 labeling requirements as a de facto national standard.
K-12 instructive toys comprise purpose-designed play materials engineered to developmental milestones, typically incorporating ABS plastics, sustainably harvested wood, or food-grade silicone with dimensional tolerances under 0.5 millimeters for interlocking components. Their commercial purpose centers on scaffolding cognitive, motor, or socio-emotional skills within structured curriculum alignment. STEM Kits now lead product-type revenue as district-level science budgets recover post-pandemic, while Art Supplies occupy the most fragmented margin pool with heavy private-label pressure. The Preschool age bracket generates the highest per-unit spending through parent gifting behavior, though Middle School represents the fastest-growing educational focus as coding and robotics curricula expand.
The U.S. Consumer Product Safety Commission enforces ASTM F963 with mandatory third-party testing, effectively raising capital barriers for new entrants. The European Chemicals Agency administers REACH restrictions on phthalates and heavy metals, redirecting Asian export capacity toward compliant material formulations. China's State Administration for Market Regulation operates under GB 6675 toy safety standards with escalating surveillance inspections ahead of peak seasonal production. Stakeholders must monitor how diverging chemical disclosure regimes between Brussels and Beijing reshape supplier qualification timelines and inventory positioning.
Market Dynamics
STEAM curriculum mandates across U.S. public school districts are forcing institutional procurement toward robotics and coding kits, while China's GB 6675 safety standards and the EU's REACH chemical restrictions simultaneously reshape supplier qualification timelines and material formulation requirements.
Growth Catalysts
- Curriculum Mandates:U.S. public school districts now require hands-on STEAM instruction, institutionalizing bulk purchases of programmable robotics kits for elementary and middle school classrooms.
- REACH Compliance:The European Chemicals Agency's phthalate and heavy metal restrictions redirect Asian export capacity toward compliant material formulations, filtering out substandard competitors.
- After-School Enrichment:East Asian metropolitan clusters in Japan, South Korea, and China sustain premium segment demand through competitive tutoring center procurement of advanced construction sets.
Market Restraints
- ABS Resin Volatility:Petrochemical feedstock fluctuations squeeze margins on injection-molded interlocking components, forcing manufacturers to absorb cost spikes or sacrifice volume.
- Testing Concentration:ASTM F963 third-party certification requirements concentrate compliance capability among a handful of accredited laboratories, extending new entrant lead times by 4-6 months.
- Digital Substitution:Tablet-based educational applications capture discretionary parent spending previously allocated to physical manipulatives, particularly in middle-income households.
Strategic Opportunities
- India Expansion:BIS certification alignment and PLI scheme incentives for domestic manufacturing create entry pathways for compliant foreign suppliers in underpenetrated tier-2 cities.
- Bio-Based Polymers:Convergence of food-grade silicone formulations with 3D printing tolerances enables premium positioning for sustainability-focused preschool segments.
- Direct Institutional Contracting:District-level science budget recovery permits manufacturers to bypass retail markup through direct RFP participation for multi-year kit supply agreements.
Industry Challenges
- Embedded Systems Talent:Shortage of firmware engineers capable of integrating age-appropriate coding interfaces into durable hardware platforms extends product development cycles.
- Multi-Jurisdiction Labeling:Simultaneous compliance with California Proposition 65, EU CE marking, and China CCC certification creates packaging complexity and inventory segmentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | K-12 Instructive Toy Market |
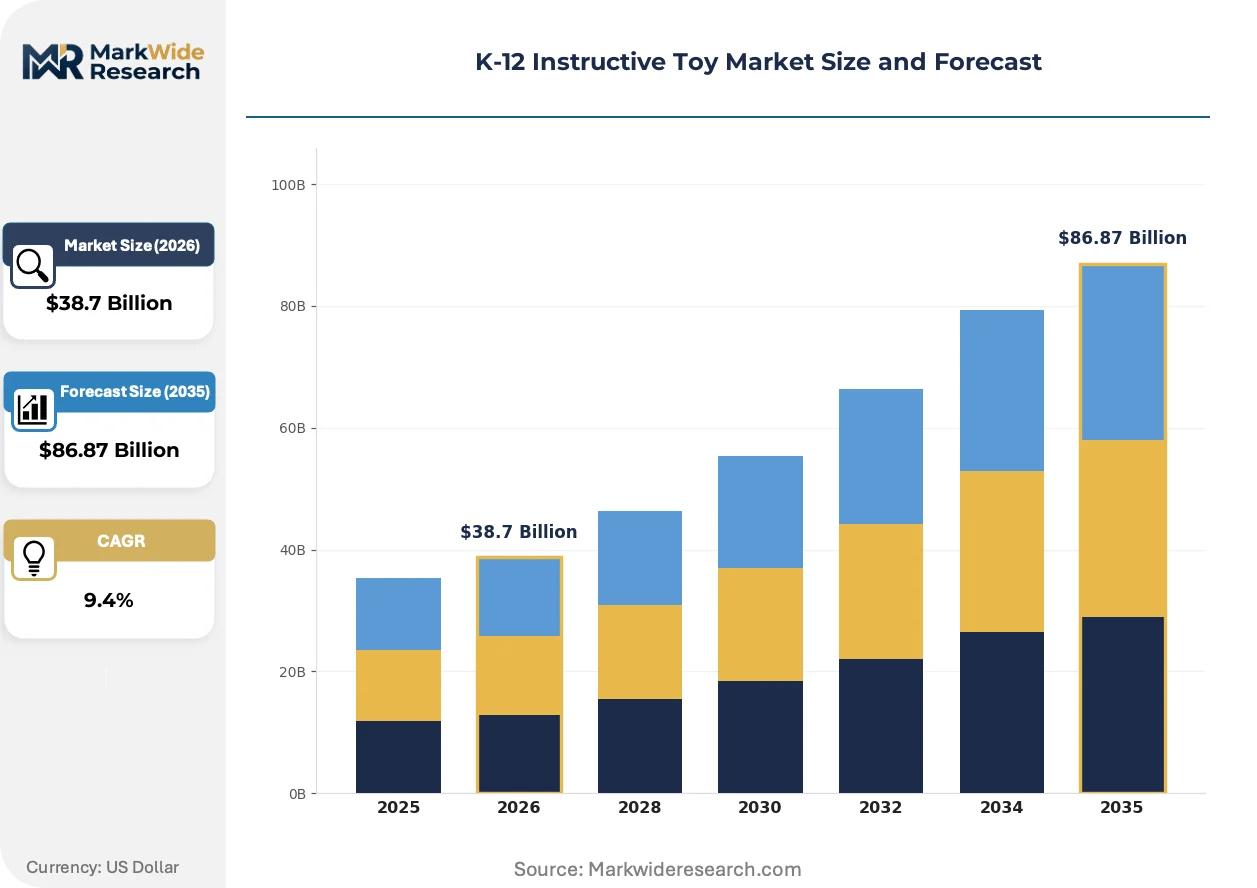
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Sets, Art Supplies, STEM Kits, Puzzles Educational Focus: Mathematics, Science, Creativity, Language Development Age Group: Preschool, Early Elementary, Late Elementary, Middle School Distribution Channel: Online Stores, Brick-and-Mortar, Educational Institutions, Specialty Retailers |
| Companies Covered | LEGO Group, Mattel, Hasbro, VTech Holdings, Spin Master, LeapFrog Enterprises, Melissa & Doug, Learning Resources, Thames & Kosmos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
K-12 Instructive Toy Market Trends and Innovations
Physical-digital hybrid play patterns are redefining product architecture, with sensor-enabled manipulatives and app-integrated construction systems capturing development budgets previously siloed between hardware and software teams.
Programmable microcontrollers with drag-and-drop coding interfaces are displacing static mechanical sets in district procurement specifications. Elementary STEM coordinators in Texas and California now prioritize Bluetooth-enabled hubs over purely structural components. This compression of the hardware-software boundary forces traditional manufacturers to acquire or partner for firmware competency.
ECHA's 2023 expansion of SVHC candidate list to include additional flame retardants is accelerating reformulation of electronic housing plastics. Manufacturers serving EU member states must now validate supply chains back to polymer resin sources. Preschool electronic toy lines face the steepest retooling costs given mouth-contact proximity and existing safety margin constraints.
Parent purchasing committees in South Korean hagwons and Japanese juku now specify open-source compatibility as a procurement criterion. These after-school academies reject proprietary coding languages that lock students into single-vendor progression paths. The shift pressures incumbents to publish API documentation and support third-party sensor integration, eroding traditional ecosystem control.
K-12 Instructive Toy Market Segmentation
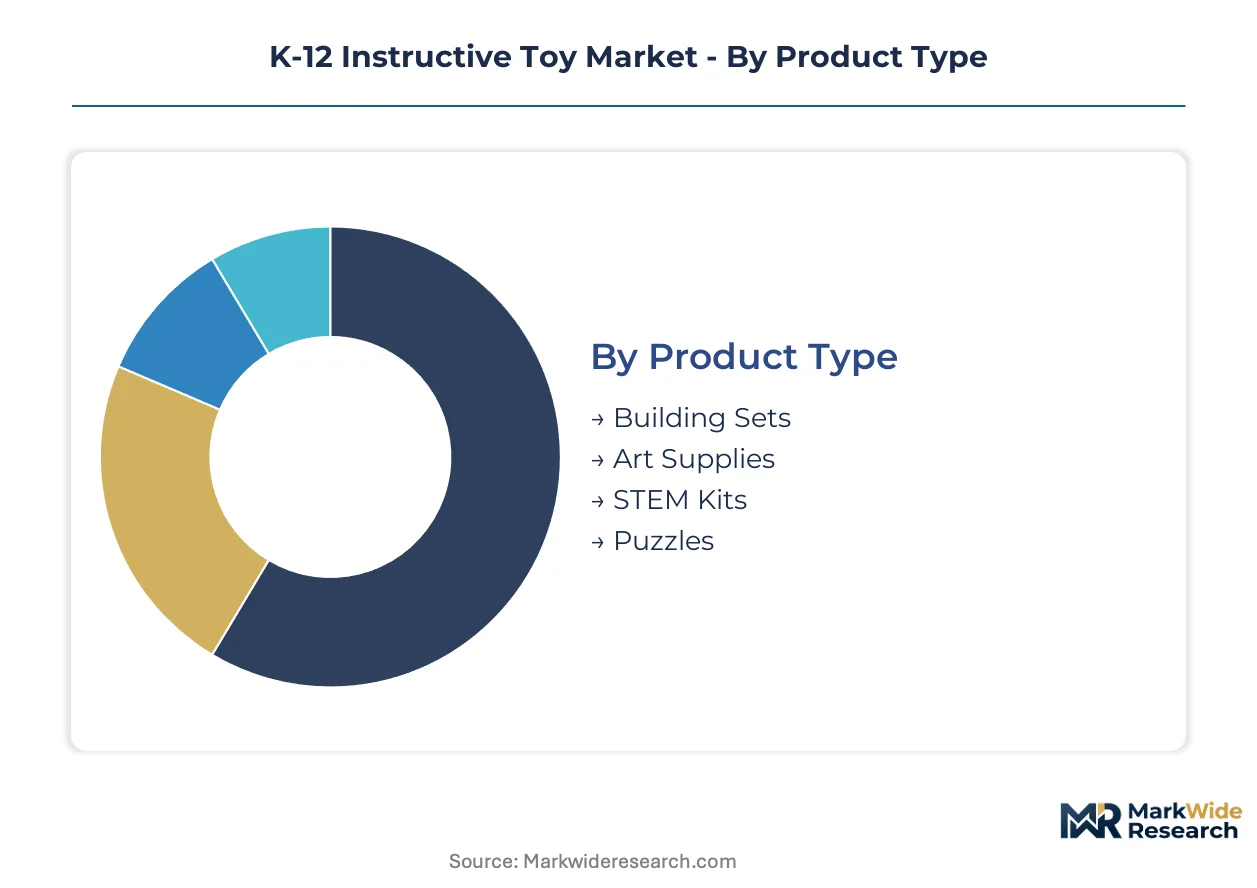
Segmentation in the K-12 instructive toy market reveals how procurement authority splits between parent-driven retail purchases and institutional buying cycles. Understanding these divides exposes where margin pools concentrate and which compliance burdens fall on which suppliers.
Product Type:
Export-led demand concentrates in STEM Kits and Building Sets, while Art Supplies and Puzzles serve more fragmented domestic retail channels.
- STEM Kits:Programmable robotics and coding hardware incorporating Bluetooth-enabled microcontrollers and drag-and-drop interfaces. District-level science budget recovery in Texas and California is institutionalizing bulk procurement of these programmable systems for elementary and middle school classrooms.
- Building Sets:Interlocking plastic or wooden components with dimensional tolerances under 0.5 millimeters, often integrating sensor-enabled hubs for hybrid physical-digital play. East Asian metropolitan clusters in Japan, South Korea, and China sustain premium demand through competitive after-school academy procurement.
- Art Supplies:Crayons, markers, and sculpting materials facing heavy private-label pressure and margin compression.
- Puzzles:Cognitive development tools spanning jigsaw, logic, and spatial reasoning formats with stable but slower growth trajectories.
STEM Kits hold the largest share; momentum sits with Building Sets as hybrid play architectures expand.
Educational Focus:
Cost tier separation runs deepest here, with Science and Mathematics commanding premium pricing against Creativity and Language Development's volume-driven economics.
- Science:Laboratory equipment, chemistry sets, and biology models requiring REACH-compliant material formulations for EU export. ECHA's SVHC candidate list expansion is forcing reformulation of electronic housing plastics and flame-retardant compounds.
- Mathematics:Manipulatives, abacuses, and geometric construction tools with strong institutional adoption in Singapore and South Korean tutoring centers.
- Creativity:Open-ended design materials with lower per-unit pricing and higher purchase frequency in parent-driven retail.
- Language Development:Phonics cards, storytelling kits, and bilingual learning tools concentrated in early childhood segments.
Science commands premium positioning; Mathematics is climbing the fastest as coding curricula integrate computational thinking requirements.
Age Group:
Volume concentration peaks in Preschool, while application complexity and per-student spending rise sharply through Middle School.
- Preschool:Products engineered to developmental milestones using food-grade silicone and sustainably harvested wood with mouth-contact safety margins. Parent gifting behavior drives the highest per-unit spending in this bracket.
- Early Elementary:Foundational literacy and numeracy tools aligned with kindergarten through second-grade curricula.
- Late Elementary:Intermediate construction sets and introductory coding platforms bridging concrete and abstract learning stages.
- Middle School:Advanced robotics, 3D printing peripherals, and microcontroller-based systems with open-source compatibility requirements specified by South Korean hagwons and Japanese juku.
Preschool dominates transaction volume; Middle School shows the steepest expansion trajectory as robotics and coding mandates spread.
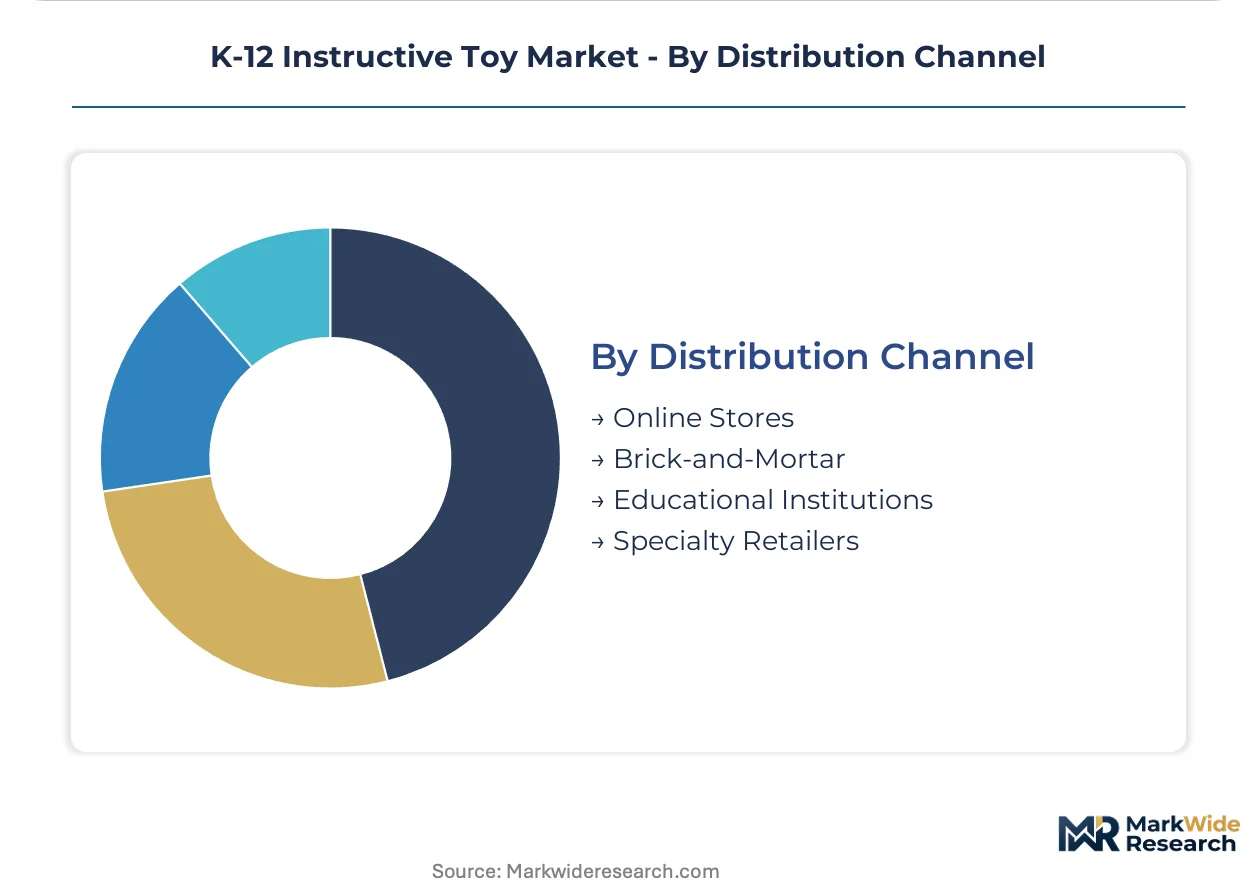
Distribution Channel:
Supply concentration varies sharply, with Educational Institutions and Specialty Retailers demanding compliant supply chains against Online Stores' price-transparent competition.
- Online Stores:E-commerce platforms capturing parent discretionary spending through subscription box models and direct-to-consumer fulfillment.
- Brick-and-Mortar:Big-box retailers and toy chains with seasonal inventory cycles and California Proposition 65 labeling exposure as a de facto national standard.
- Educational Institutions:District-level RFP participation requiring ASTM F963 third-party certification and multi-year kit supply agreements bypassing retail markup.
- Specialty Retailers:Curated independent stores and learning resource centers with higher service intensity and STEAM-curriculum-aligned merchandising.
Educational Institutions anchor institutional revenue; Online Stores are gaining share fastest through convenience and subscription retention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
STEAM curriculum mandates and after-school enrichment subsidies are redistributing procurement authority across distinct national regulatory environments, with each major market imposing unique compliance burdens on material formulations and safety testing protocols.
United States
District-level science budget recovery in Texas and California institutionalizes bulk procurement of programmable robotics kits for elementary classrooms. The Consumer Product Safety Commission enforces ASTM F963 with mandatory third-party testing, extending supplier qualification timelines. Greater Boston anchors ed-tech startup density for sensor-enabled manipulatives targeting institutional RFP channels.
China
East Asian metropolitan clusters sustain premium segment demand through competitive tutoring center procurement of advanced construction sets. The State Administration for Market Regulation operates escalating surveillance inspections under GB 6675 standards ahead of peak seasonal production. Yangtze River Delta manufacturing hubs retool electronic housing plastics to meet diverging EU and domestic chemical disclosure regimes.
Germany
Parent purchasing committees in after-school academies prioritize open-source compatibility for coding progression paths. ECHA administers REACH restrictions on phthalates and heavy metals, redirecting Asian export capacity toward compliant formulations. Bavaria's precision engineering clusters supply high-tolerance injection molds for interlocking components serving EU-wide distribution.
Japan
Juku after-school networks specify microcontroller-based systems with published API documentation for third-party sensor integration. METI oversees industrial standards alignment for educational hardware imports. Kanto region distributors manage multi-jurisdiction labeling complexity for products simultaneously serving domestic and export markets.
India
BIS certification alignment and PLI scheme incentives create entry pathways for compliant foreign suppliers in underpenetrated tier-2 cities. State education boards pilot coding curriculum integration in Maharashtra and Karnataka. Delhi-NCR procurement offices aggregate demand for bulk kit supply agreements bypassing retail markup structures.
K-12 Instructive Toy Market Competitive Landscape
Player mix skews toward vertically integrated conglomerates with captive manufacturing networks and specialized mid-cap developers focused on single educational domains. Market structure concentrates around three tiers: global brand houses with multi-category portfolios, regional specialists with deep curriculum alignment, and contract manufacturers serving private-label retail channels. Dominant competitive moves include direct institutional contracting to bypass retail margins and backward integration into electronic component sourcing for margin control on programmable systems.
Within the premium-tier vector, LEGO Group exemplifies the conglomerate archetype through its Denmark and Mexico-based manufacturing footprint. VTech Holdings occupies a position representing vertical integration into electronic component supply chains. Melissa & Doug sits within the material specialization tier, navigating California Proposition 65 labeling requirements as a de facto compliance benchmark for wooden toy categories.
| Leading Market Players |
|---|
| LEGO Group |
| Mattel |
| Hasbro |
| VTech Holdings |
| Spin Master |
| LeapFrog Enterprises |
| Melissa & Doug |
| Learning Resources |
| Thames & Kosmos |
| Others |
Pricing and Supply Chain Analysis
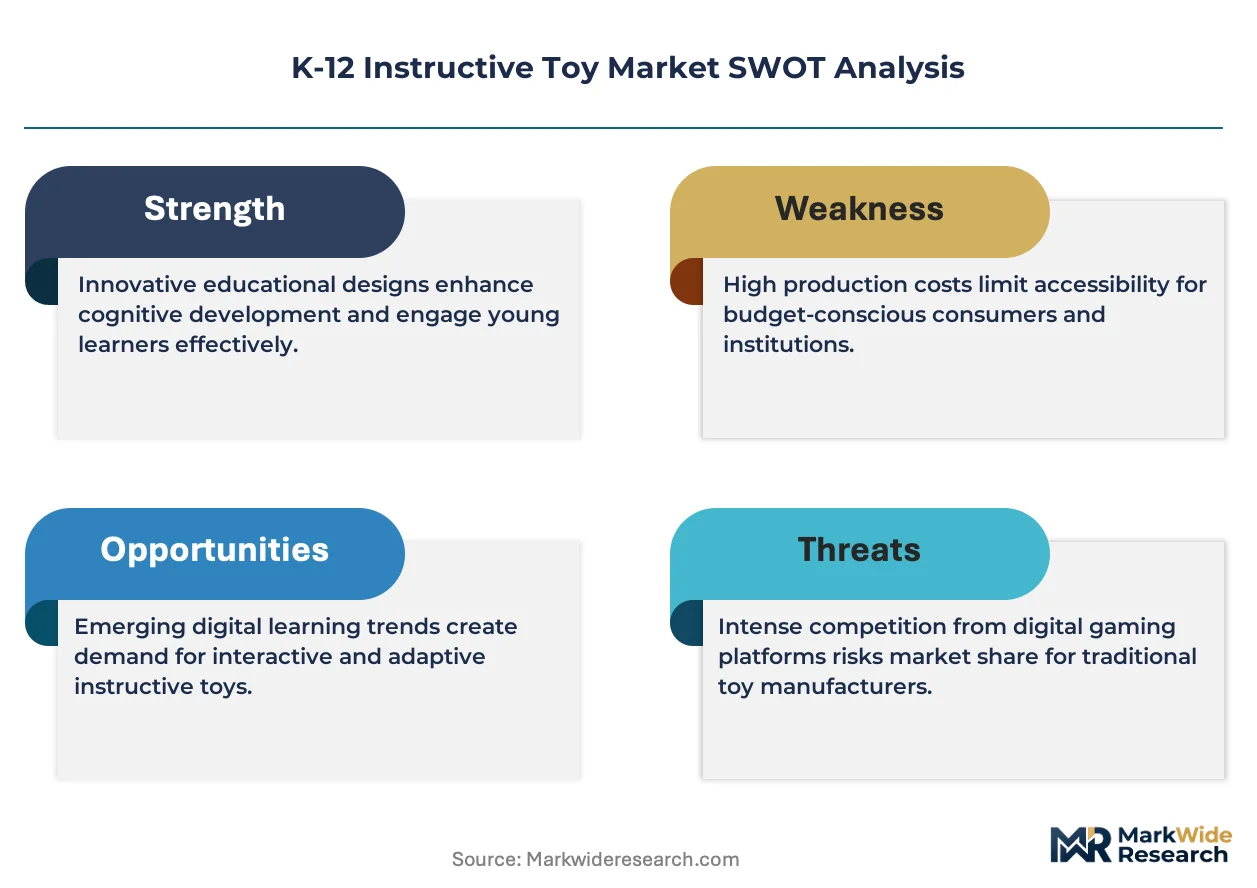
Four-to-six-month ASTM F963 certification lead times concentrate compliance capability among accredited laboratories, anchoring pricing power with incumbents who have pre-qualified testing relationships while squeezing margin flexibility for new entrants navigating third-party validation queues.
Pricing Analysis
Certification grade creates the primary spread between premium and standard tiers, with ASTM F963 third-party validation and REACH SVHC-compliant material formulations commanding substantial markups over basic CE-marked alternatives. Pricing stratifies across premium certified, standard compliant, and economy private-label tiers, with volume scale and after-sales curriculum support bundling as secondary differentiation drivers. Cost compression in the economy tier is intensifying because private-label retailers are consolidating supplier panels. Parent-driven retail segments show highest price sensitivity, while district-level institutional procurement demonstrates lowest sensitivity due to budget recovery dynamics and multi-year kit depreciation accounting.
Supply Chain Analysis
Yangtze River Delta injection molding capacity serves as the dominant chokepoint for ABS interlocking components, with Denmark and Mexico providing secondary captive supply for premium-tier manufacturers. Raw material dependencies center on petrochemical-derived ABS resin, food-grade silicone formulations, and sustainably harvested hardwood lumber. Single-source vulnerability concentrates in third-party testing laboratory accreditation, where CPSC-recognized facilities face capacity constraints during peak seasonal production. Distribution runs through educational institution RFP channels, specialty retail merchandising, and direct-to-consumer subscription fulfillment with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as district-level science budget recovery institutionalizes bulk procurement of programmable robotics kits for elementary and middle school classrooms.
For Market Incumbents: Compound firmware engineering capabilities through targeted hiring in Greater Boston's ed-tech talent cluster, defending against digital substitution threats from tablet-based educational applications. Deepen backward integration into electronic component sourcing to maintain margin control on Bluetooth-enabled microcontroller systems. Prioritize ASTM F963 pre-certification investments to extend lead-time advantages over emerging competitors. For New Entrants and Emerging Players: Differentiate on open-source compatibility specifications demanded by South Korean hagwons and Japanese juku purchasing committees, avoiding proprietary coding language lock-in. Target India's tier-2 cities through BIS certification alignment and PLI scheme incentive navigation, where coding curriculum pilots in Maharashtra and Karnataka create institutional demand aggregation. Pursue direct institutional contracting models that bypass retail markup structures and establish multi-year supply relationships. For Investors and Strategic Acquirers: Long-term, this sits as a curriculum-embedded hardware play because STEAM mandates are institutionalizing recurring procurement cycles with district-level budget authority. Acquisition target archetype: mid-cap developers with demonstrated REACH-compliant supply chains and established firmware integration capabilities. Signal to watch: district RFP specification shifts toward physical-digital hybrid architectures as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Institutional Contracting | Bypasses retail markup through multi-year district RFP participation for kit supply agreements. |
| Firmware Capability Acquisition | Addresses embedded systems talent scarcity compressing product development cycles for programmable platforms. |
| REACH-Compliant Material Reformulation | Validates supply chains back to polymer resin sources under ECHA's expanded SVHC candidate list. |
| Open-Source API Publication | Meets South Korean and Japanese after-school academy procurement criteria for coding progression flexibility. |
| Bio-Based Polymer Integration | Enables premium positioning in sustainability-focused preschool segments through food-grade silicone convergence. |
Research Methodology
A standing panel of district STEM coordinators, toy safety compliance officers, after-school academy procurement managers, and electronic component sourcing directors provided ongoing calibration across primary interview rounds. Secondary validation drew from CPSC enforcement bulletins, ECHA SVHC candidate list updates, GB 6675 surveillance inspection reports, and customs trade data on ABS resin and electronic component flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with analytical framework disaggregation across product type, educational focus, age group, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression-based trajectory modeling incorporating curriculum mandate adoption curves, petrochemical feedstock price indices, and district science budget recovery patterns as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained district budget recovery trajectories or accelerated digital substitution rates would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement intensity and material formulation cost pass-through elasticity. Practitioners should keep alternative scenarios live as REACH SVHC expansion timelines and China GB standard surveillance protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Global Toys Market
Toys and Games
Ride-Ons Market
Toys and Games
Robot Toys for Children Market
Toys and Games
United States Toys Market
Toys and Games
Global Stem Toys Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Games and Puzzles Market
Toys and Games
Cat Toys Market
Toys and Games
Male Sex Toys Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
Sustainable Toys Market
Toys and Games
Toys and Games Market
Toys and Games
Dildo Sex Toy Market