
 Bubble Tubes Market | 2026-2036
Bubble Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Bubble Tubes Market Outlook
The capital-intensity gap between integrated paperboard converters and specialty packaging pure-plays is collapsing as raw material volatility compresses margins across tiers. Mondi Group leverages captive pulp supply and extrusion coating capacity to sustain cost discipline in protective packaging derivatives. Smurfit Kappa competes through European corrugated integration and recycled fiber dominance, while DS Smith anchors its position via e-commerce-optimized design capabilities and retail-ready formats.
Bubble tubes are sealed cylindrical enclosures, typically fabricated from extruded polycarbonate or acrylic, containing a water column aerated by a regulated compressor to generate continuous rising bubble streams; internal LED arrays provide chromatic control for sensory stimulation applications. The product serves primarily as therapeutic equipment in multisensory environments, where controlled visual and auditory feedback supports neurological engagement protocols. Standard and customizable product types occupy the mature volume tier, while inflatable and portable variants capture the fastest-expanding segment as mobile therapy units gain traction in community-based care. PVC and plastic materials dominate current fabrication, though foam and nylon alternatives are carving margin pools in lightweight, transport-focused designs.
FDA Class I medical device oversight governs bubble tubes deployed in clinical rehabilitation settings, while REACH and RoHS frameworks in Europe restrict phthalate content and hazardous substance thresholds in polymer formulations. CE marking under the EU Medical Device Regulation further conditions market access for therapeutic-grade installations. Stakeholders must monitor evolving sensory equipment standards from ISO and national health technology assessment bodies to anticipate procurement specification shifts.
Market Dynamics
REACH compliance in Europe is tightening material safety requirements for PVC and plastic components, forcing manufacturers to reformulate polymer bases and revalidate supply chains. Pediatric healthcare facilities are expanding sensory room installations, creating institutional procurement pull that favors certified therapeutic-grade equipment over consumer alternatives.
Growth Catalysts
- REACH Phase-Out Mandates:Restrictions on phthalate-laden PVC formulations in the EU are accelerating demand for compliant polycarbonate and acrylic alternatives in clinical-grade bubble tubes.
- German Institutional Funding:Therapeutic sensory infrastructure receives strong public health investment, concentrating procurement volume in rehabilitation centers and pediatric hospitals.
- Mobile Therapy Expansion:Community-based care models are driving uptake of inflatable and portable bubble tube variants for non-clinical deployment.
Market Restraints
- Raw Material Volatility:Polycarbonate resin prices fluctuate with benzene and bisphenol-A feedstock costs, compressing converter margins.
- Supply Concentration Risk:LED array and compressor component sourcing clusters in East Asian manufacturing hubs, exposing buyers to logistics disruption.
- Substitution Threat:Projection-based sensory systems and virtual reality environments compete for capital allocation in multisensory room budgets.
Strategic Opportunities
- Underpenetrated Home Care:Residential autism and dementia care markets in the United States lack standardized bubble tube distribution, creating channel development potential.
- EU Green Deal Alignment:Circular economy incentives favor recyclable acrylic formulations and energy-efficient compressor designs in public tenders.
- Telehealth Integration:Remote-controlled chromatic programming enables therapist oversight of home-based sensory sessions, converging hardware with digital health platforms.
Industry Challenges
- CE Marking Timelines:EU Medical Device Regulation certification for therapeutic-grade installations extends product launch cycles by 12-18 months.
- Skill Shortage in Sensory Design:Qualified occupational therapists who can specify appropriate bubble tube configurations remain scarce relative to facility expansion plans.
- Legacy System Interoperability:New LED control protocols must integrate with existing room management systems in renovated healthcare infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bubble Tubes Market |
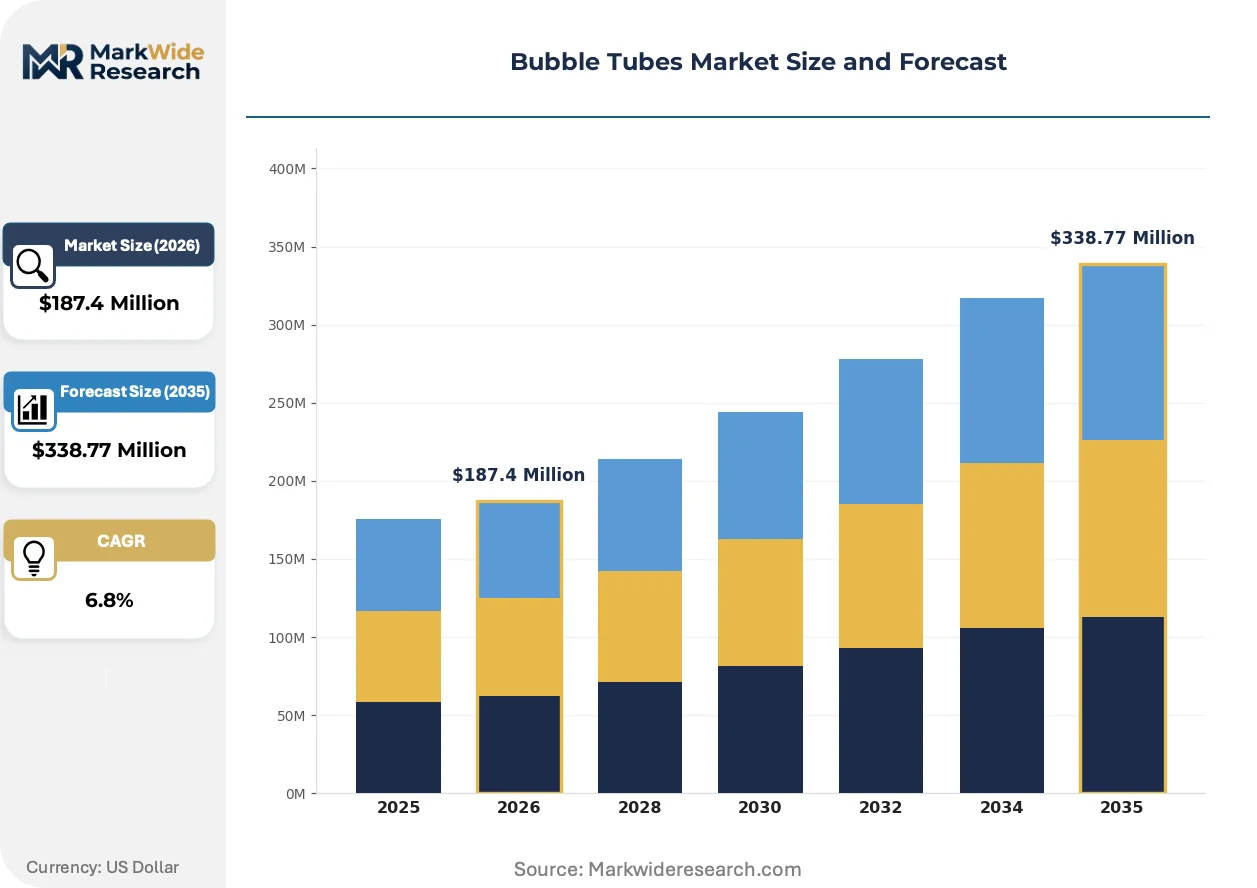
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Inflatable, Portable, Customizable Application: Aquatic Therapy, Recreational Parks, Home Use, Rehabilitation Centers Material: Plastic, PVC, Foam, Nylon Customer Type: Retailers, Distributors, Manufacturers, End Users |
| Companies Covered | Mondi Group, Pratt Industries, Smurfit Kappa, Stora Enso, UFP Technologies, WestRock, International Paper, Packaging Corporation of America, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bubble Tubes Market Strategic Shifts
LED control architectures and material formulations are converging to redefine therapeutic sensory equipment specifications. Manufacturers are responding to institutional procurement pressure with modular designs that accommodate both permanent installation and mobile deployment.
Addressable RGB-LED arrays with DMX512 protocol compatibility are supplanting basic color-wheel systems in premium bubble tube configurations. Pediatric hospitals in Germany and the Netherlands are specifying these units for synchronized multisensory room programming. The shift is compressing demand for entry-level static-color products while expanding the addressable market for programmable therapeutic hardware.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC compound reformulation across European supply chains. Manufacturers serving clinical rehabilitation settings must now validate alternative polymer bases or migrate entirely to polycarbonate extrusion. Therapeutic-grade bubble tubes with CE marking under the EU Medical Device Regulation face the steepest compliance burden, with smaller fabricators exiting the segment rather than absorbing retesting costs.
Facility managers in pediatric healthcare are consolidating vendor relationships and demanding extended warranty and maintenance contracts alongside hardware procurement. Traditional equipment-only sales models are losing share to bundled service agreements in the United Kingdom and Scandinavian markets. Autism treatment centers and dementia care facilities represent the verticals where this behavioral shift is most pronounced, with procurement committees prioritizing total cost of ownership over upfront capital expenditure.
Bubble Tubes Market Segmentation
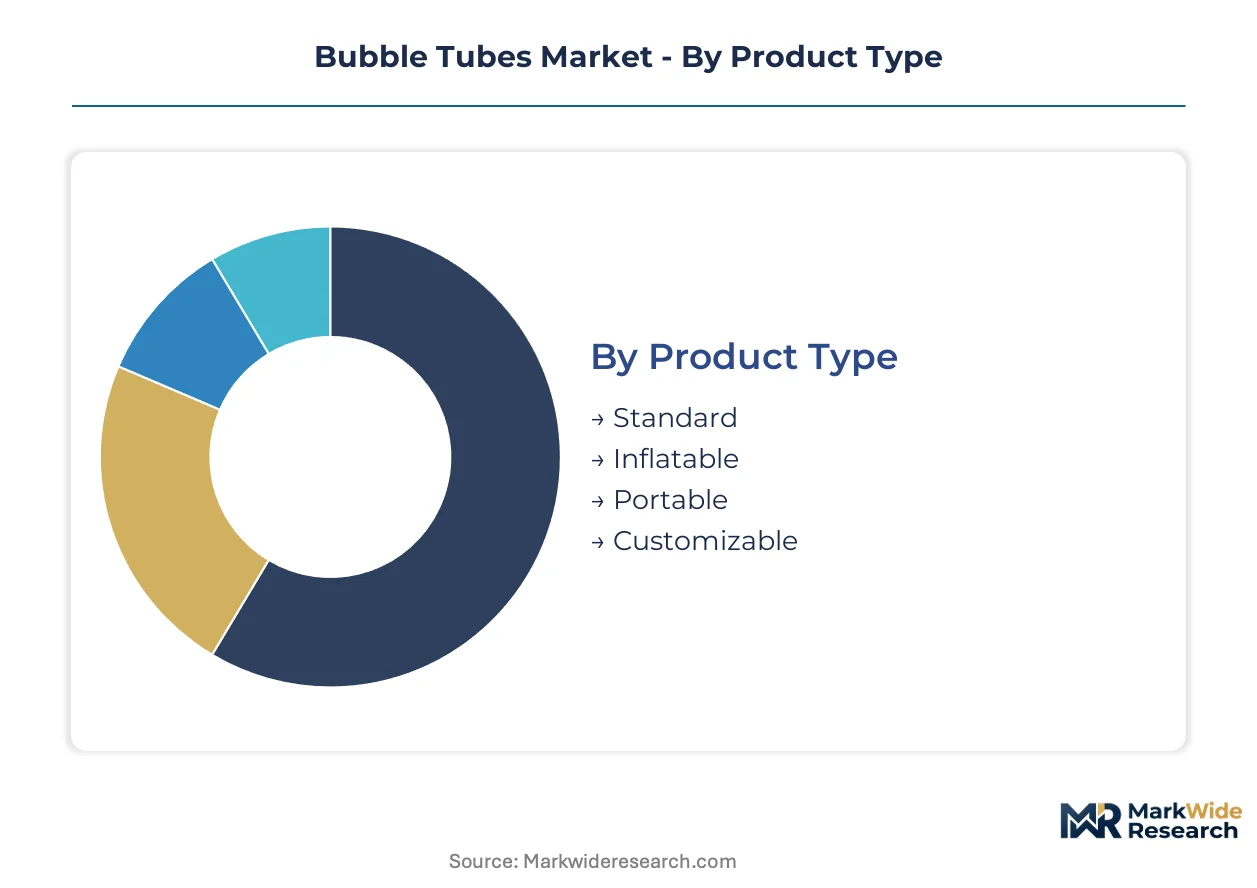
Bubble tube procurement patterns diverge sharply across therapeutic versus recreational deployment contexts. Material compliance requirements and mobility specifications create distinct margin profiles that reshape vendor prioritization.
Product Type:
Substitution pressure from projection-based sensory systems weighs most heavily on static installations lacking programmable features.
- Standard:Fixed-height cylindrical enclosures with integrated LED arrays dominate institutional procurement in German pediatric hospitals. Rehabilitation centers specify these units for permanent multisensory room infrastructure where durability outweighs portability concerns.
- Inflatable:Collapsible polymer chambers with external compressor coupling enable rapid deployment in community-based autism treatment programs. Dutch mobile therapy providers are consolidating procurement around these variants to serve dispersed patient populations.
- Portable:Lightweight assemblies with battery-powered compressors support home-based dementia care in underpenetrated United States residential markets.
- Customizable:Modular height and diameter configurations accommodate facility-specific architectural constraints in renovated healthcare infrastructure.
Standard retains volume leadership; Inflatable holds the steepest expansion curve.
Application:
Cost tier stratification separates reimbursed clinical equipment from discretionary consumer purchases.
- Rehabilitation Centers:CE-marked therapeutic-grade installations with DMX512 protocol compatibility command premium positioning in Scandinavian bundled service contracts. Extended warranty requirements from facility managers compress margins for equipment-only vendors.
- Aquatic Therapy:Waterproof-rated compressor housings and sealed LED drivers serve hydrotherapy suites in Netherlands pediatric facilities. REACH-compliant polycarbonate formulations are mandatory for pool-adjacent deployment.
- Home Use:Simplified control interfaces and reduced decibel compressors address residential noise constraints in United States autism care households.
- Recreational Parks:High-capacity bubble generation systems with vandal-resistant enclosures target entertainment venues with minimal therapeutic oversight requirements.
Rehabilitation Centers anchor revenue concentration; Home Use is climbing the fastest as telehealth integration enables remote therapist oversight.
Material:
Supply concentration in East Asian polymer feedstocks creates divergent compliance burdens across regulatory jurisdictions.
- Plastic:Generic polymer formulations face displacement in European clinical procurement as REACH Annex XVII restrictions tighten. Recyclable acrylic variants aligned with EU Green Deal circular economy incentives are gaining tender preference.
- PVC:Phthalate-laden compounds are exiting therapeutic-grade segments entirely due to ECHA authorization requirements. Reformulated plasticizer alternatives remain cost-disadvantaged against polycarbonate migration.
- Foam:Lightweight cushioning materials enable transport-focused inflatable designs with reduced shipping dimensional weight.
- Nylon:High-tensile fabric substrates support collapsible chamber integrity in portable variant compressive stress testing.
Plastic maintains installed base dominance; Foam is gaining share fastest in logistics-optimized product lines.
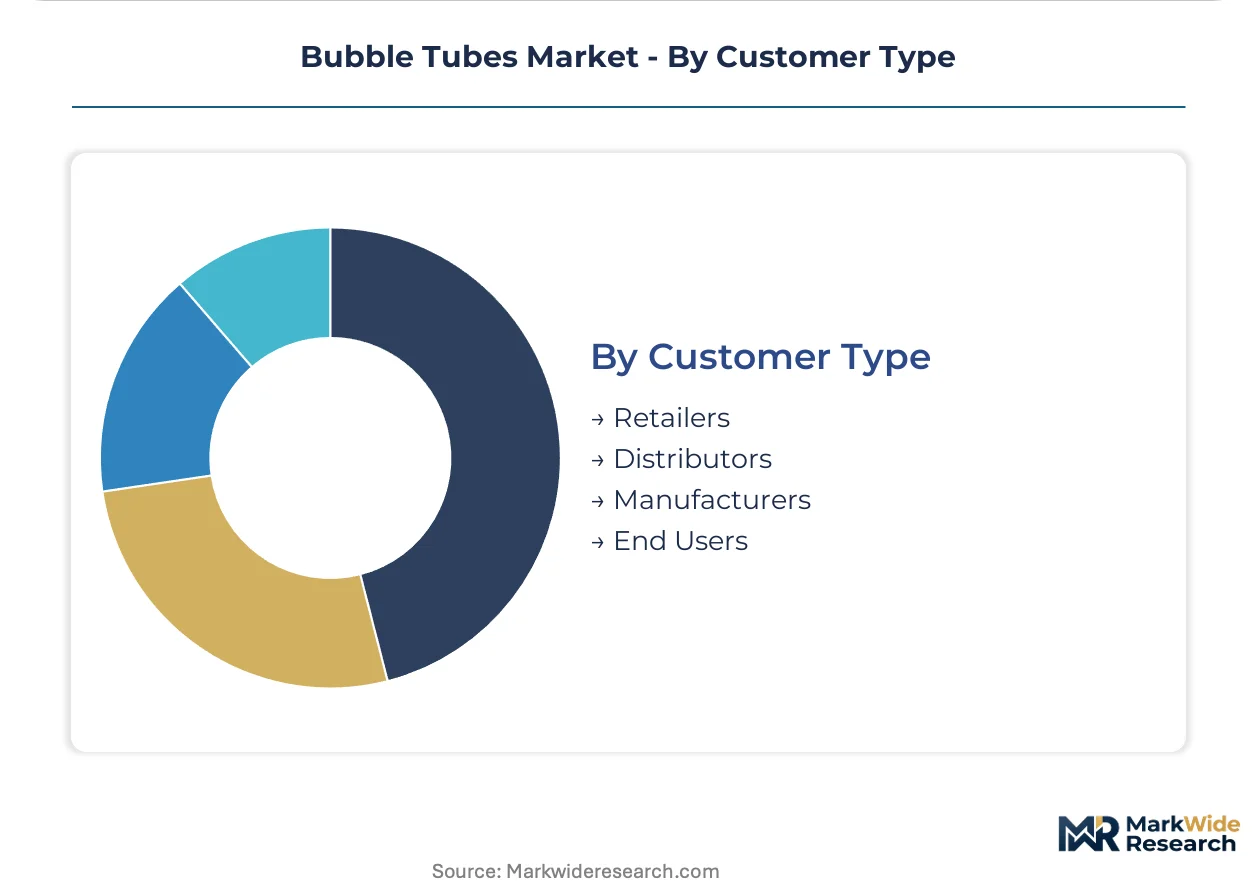
Customer Type:
Maturity gradients separate established institutional procurement committees from emerging direct-to-consumer channels.
- Distributors:Specialized sensory equipment intermediaries consolidate vendor relationships for United Kingdom autism treatment centers. Inventory carrying costs for CE-marked therapeutic-grade stock create working capital barriers for smaller resellers.
- End Users:Pediatric hospitals and dementia care facilities in Germany are shifting toward total-cost-of-ownership evaluation frameworks. Procurement committees now weight ten-year maintenance contracts above upfront capital expenditure.
- Retailers:General medical equipment suppliers lack occupational therapy specification expertise, creating channel conflict with specialized distributors.
- Manufacturers:Vertically integrated producers with captive extrusion capacity capture margin pools in polycarbonate-based standard configurations.
Distributors retain channel volume leadership; End Users are expanding most quickly as direct procurement authority consolidates in facility management departments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement committees command pricing premiums through bundled long-term service contracts, while United States residential channels absorb margin compression from fragmented distributor networks and minimal insurance reimbursement.
Germany
Bavarian pediatric hospitals and North Rhine-Westphalian rehabilitation centers drive institutional procurement volume through public health infrastructure budgets. ECHA REACH Annex XVII enforcement mandates phthalate-free polymer formulations for all clinical-grade installations. The Stuttgart industrial corridor hosts polycarbonate extrusion specialists serving CE-marked therapeutic equipment supply chains.
United States
Autism treatment centers in California and dementia care facilities in Florida generate demand for home-use portable variants with simplified control interfaces. FDA Class I medical device oversight applies to clinical rehabilitation deployments, though residential segments face minimal regulatory burden. The Greater Boston healthcare cluster concentrates occupational therapy specification expertise for sensory room design.
United Kingdom
NHS-funded autism treatment centers and private dementia care chains are consolidating vendor relationships toward total-cost-of-ownership frameworks. MHRA alignment with EU MDR transitional provisions conditions market access for therapeutic-grade equipment. The Midlands manufacturing belt accommodates specialized sensory equipment distributors carrying CE-marked inventory.
Netherlands
Mobile therapy providers serving dispersed pediatric populations across Randstad and Brabant favor inflatable bubble tube variants for community-based deployment. Dutch environmental regulations incentivize recyclable acrylic formulations in public tenders. The Eindhoven region hosts LED array component suppliers integrated into programmable chromatic control systems.
China
Domestic compressor and LED array manufacturing concentrates supply-side cost advantages for export-oriented fabricators. NMPA medical device registration requirements are tightening for therapeutic equipment imports, though recreational segments face lighter oversight. The Yangtze River Delta industrial corridor dominates polycarbonate resin processing and extrusion capacity for acrylic enclosure fabrication.
Bubble Tubes Market Competitive Environment
Concentration sits with diversified packaging conglomerates that have backward integrated into captive pulp supply and extrusion coating capacity. The vendor base spans three tiers: integrated paperboard converters with protective packaging derivatives, specialty packaging pure-plays focused on corrugated integration, and regional fabricators serving localized sensory equipment demand. Strategic moves center on M&A-driven corrugated consolidation in Europe and capacity expansion into e-commerce-optimized design formats.
Among packaging-integrated conglomerates, Mondi Group and Smurfit Kappa exemplify archetypes leveraging upstream fiber control and European corrugated networks respectively. DS Smith occupies a position emphasizing retail-ready formats and design-led differentiation. These entities represent competitive pressure on dedicated bubble tube fabricators, who must defend therapeutic-grade positioning through CE marking and occupational therapy channel relationships rather than scale economics.
| Leading Market Players |
|---|
| Mondi Group |
| Pratt Industries |
| Smurfit Kappa |
| Stora Enso |
| UFP Technologies |
| WestRock |
| International Paper |
| Packaging Corporation of America |
| DS Smith |
| Others |
Value Chain & Pricing Dynamics
Polycarbonate migration away from phthalate-laden PVC compounds is simultaneously redrawing supplier geography toward German extrusion specialists and compressing margin structures across European clinical-grade tiers. This material transition forces fabricators to absorb retesting costs for REACH Annex XVII compliance while repositioning procurement relationships around captive polymer supply.
Pricing Analysis
The customization-premium spread separates DMX512-programmable therapeutic installations from static-color consumer alternatives by a factor reflecting certification burden and after-sales bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking status, LED protocol sophistication, and compressor decibel rating. Cost compression in entry-tier static products is intensifying because projection-based sensory systems capture multisensory room capital allocation. Pediatric hospitals in Germany exhibit lowest price sensitivity due to public health infrastructure budgets, while United States residential autism care households face highest sensitivity from minimal insurance reimbursement.
Supply Chain Analysis
Inventory carrying costs for CE-marked therapeutic-grade stock create 12-18 month lead-time extensions that favor vertically integrated producers with captive extrusion capacity. Polycarbonate resin supply concentrates in China, Germany, and the Netherlands, with LED array and compressor component sourcing anchored in East Asian manufacturing hubs. Raw material dependencies rest on benzene and bisphenol-A feedstock costs, biaxially oriented polycarbonate film, and addressable RGB semiconductor dies. Single-source vulnerability in compressor motor windings exposes buyers to logistics disruption from Taiwan Strait shipping routes. Distribution runs through specialized sensory equipment intermediaries in the United Kingdom and direct procurement committees in German pediatric hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend installed base positions against projection-based sensory systems and virtual reality environments that compete for institutional capital allocation. Substitution threats from digital therapeutic platforms require hardware vendors to demonstrate irreplaceable tactile-auditory feedback value.
For Market Incumbents: Compound CE marking expertise into extended warranty and maintenance contracts that lock out smaller fabricators exiting under retesting cost burdens. Backward integration into polycarbonate extrusion capacity secures margin pools as REACH Annex XVII enforcement tightens. Prioritize DMX512 protocol compatibility investments that synchronize with existing room management systems in renovated healthcare infrastructure.
For New Entrants and Emerging Players: Lead with inflatable and portable variants targeting underpenetrated United States residential autism and dementia care markets where distributor fragmentation creates channel entry gaps. Deploy telehealth-integrated chromatic programming as the go-to-market angle that converges hardware with remote therapist oversight platforms. Avoid German institutional procurement where bundled long-term service contracts favor established vendor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed packaging conglomerates that have diversified into protective equipment derivatives without therapeutic-grade certification depth. Long-term viability over a 5-10 year window hinges on regulatory moat sustainability rather than scale economics. Watch ECHA authorization timelines for alternative plasticizer formulations as the inflection signal determining whether PVC reformulation or polycarbonate migration dominates material strategy.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR certification extends product launch cycles but locks out uncertified competitors from German procurement. |
| Backward Integration | Captive polycarbonate extrusion capacity insulates margins from benzene feedstock volatility and REACH reformulation costs. |
| Telehealth Platform Integration | Remote-controlled chromatic programming enables therapist oversight of home-based sessions in United States residential markets. |
| Hospital System Partnership | Bundled service agreements with NHS-funded autism centers in the United Kingdom shift procurement toward total cost of ownership. |
| Green Manufacturing Transition | Recyclable acrylic formulations aligned with EU Green Deal circular economy incentives gain tender preference in Dutch public procurement. |
Study Parameters
The analysis maps standard, inflatable, portable, and customizable product configurations, each validated through occupational therapists, pediatric hospital procurement committees, biomedical engineers, and specialized sensory equipment distributors. Primary interviews with these stakeholders combined with secondary validation from FDA Class I device filings, ECHA REACH Annex XVII substance restrictions, EU MDR technical documentation, and hospital procurement database records. Bottom-up unit economics triangulate against top-down public health infrastructure spending patterns.
Consistency checks validated volume and value outputs against external benchmarks including trade flow data for polycarbonate resin, compressor component import records, and institutional capital expenditure disclosures from German rehabilitation centers. The analytical framework models product type, application context, material formulation, and customer channel across the projection horizon. CAGRs derive from segmented demand elasticity coefficients and substitution threat penetration curves. Forecast inputs incorporate REACH authorization timelines for alternative plasticizers and LED protocol adoption rates in multisensory room specifications.
Forecasts assume regulatory continuity in EU MDR transitional provisions and FDA Class I oversight frameworks; material policy shifts would require re-modeling certification burden and procurement specification timelines. Outputs reflect assumptions about telehealth reimbursement expansion in United States residential markets and occupational therapy workforce availability for sensory room design. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Animation Toys Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Bath Toy Market
Toys and Games
Kids Toys Market
Toys and Games
Dartboard Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Ferret Toys Market
Toys and Games
Remote Control Toys Market
Toys and Games
Global Stem Toys Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Toy Collectibles Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Drone for Kids Market
Toys and Games
Glow Sticks Market