
 Games and Puzzles Market | 2026-2036
Games and Puzzles Market Size, Share, and Industry Trends Forecast 2026-2036
Games and Puzzles Market Intelligence
Digital printing and AI-assisted design tools are reshaping how publishers prototype and customize game components, collapsing development cycles from months to weeks. Hasbro, Inc. leverages its captive manufacturing network across Massachusetts and East Asia to sustain rapid SKU turnover for licensed properties. Ravensburger AG anchors its premium positioning through precision die-cutting technology and archival-grade cardboard formulations that command shelf space in German and Austrian specialty retailers. Buffalo Games competes aggressively on jigsaw puzzle piece-count variety, occupying the mass-market tier through Walmart and Target distribution dominance.
Games and puzzles encompass rule-based recreational products—board games with modular boards and tokens, card games with standardized decks, jigsaw puzzles with interlocking die-cut pieces, and dice games with polyhedral randomizers—typically manufactured from laminated cardboard, ABS plastic, or sustainably sourced wood, designed to deliver structured social interaction and cognitive engagement. Board games and jigsaw puzzles represent the largest product type segments, with board games capturing the highest margin pools through expansion packs and collectible miniatures, while jigsaw puzzles are registering the fastest growth among adults seeking mindfulness-oriented offline activities. Cardboard and wood materials lead volume production, though plastic maintains entrenched share in dice and token components where durability standards exceed paper-based alternatives.
FDA oversees material safety for toys and games intended for children under twelve through the Consumer Product Safety Improvement Act, while REACH in Europe mandates disclosure of phthalates and heavy metals in colored inks and plastic coatings. The EU Green Deal is accelerating pressure on publishers to eliminate petroleum-based laminates and shift toward FSC-certified substrates, reshaping supplier qualification criteria for export-oriented manufacturers. Stakeholders must monitor how extended producer responsibility frameworks evolve across North American and European jurisdictions, as compliance costs will increasingly determine which material formats and distribution channels remain economically viable.
Market Dynamics
REACH compliance in Europe is tightening chemical safety standards for printed cardboard and plastic components, forcing publishers to reformulate inks and coatings while recalibrating supplier networks across multiple jurisdictions.
Growth Catalysts
- Digital Detox Movement:Millennial and Gen Z parents are redirecting family entertainment budgets toward offline tabletop experiences, expanding the addressable household base for board games and jigsaw puzzles.
- REACH Chemical Disclosure Mandates:European manufacturers investing in phthalate-free formulations and heavy-metal testing are capturing shelf space in German and Austrian specialty retailers.
- AI-Assisted Prototyping:Publishers deploying machine learning for component design are collapsing development cycles from months to weeks, accelerating SKU turnover for licensed properties.
Market Restraints
- Petroleum-Based Laminate Dependency:Petroleum-derived coatings remain entrenched in mass-market production, exposing margins to crude oil volatility and complicating EU Green Deal alignment.
- East Asian Manufacturing Concentration:Die-cutting and injection molding capacity clusters in specific coastal provinces, creating vulnerability to shipping rate spikes and customs processing delays.
- Plastic Durability Standards:ABS and polypropylene tokens face technical limitations in biodegradability, constraining brand positioning for sustainability-focused buyers.
Strategic Opportunities
- FSC-Certified Substrate Adoption:Publishers eliminating petroleum-based laminates in favor of forest-certified cardboard can access preferential placement in EU Green Deal-compliant retail channels.
- Subscription Box Services:Curated monthly game deliveries are penetrating underexploited metropolitan markets, building recurring revenue streams distinct from traditional retail.
- Board Game Café Expansion:Licensed social venues in United States cities are creating experiential marketing platforms that convert trial into purchase.
Industry Challenges
- Extended Producer Responsibility Compliance:Evolving packaging waste frameworks across North American and European jurisdictions demand new reverse logistics capabilities and material tracking systems.
- Precision Die-Cutting Talent Scarcity:Archival-grade cardboard formulations require specialized tooling expertise that outpaces vocational training pipeline output in traditional manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Games and Puzzles Market |
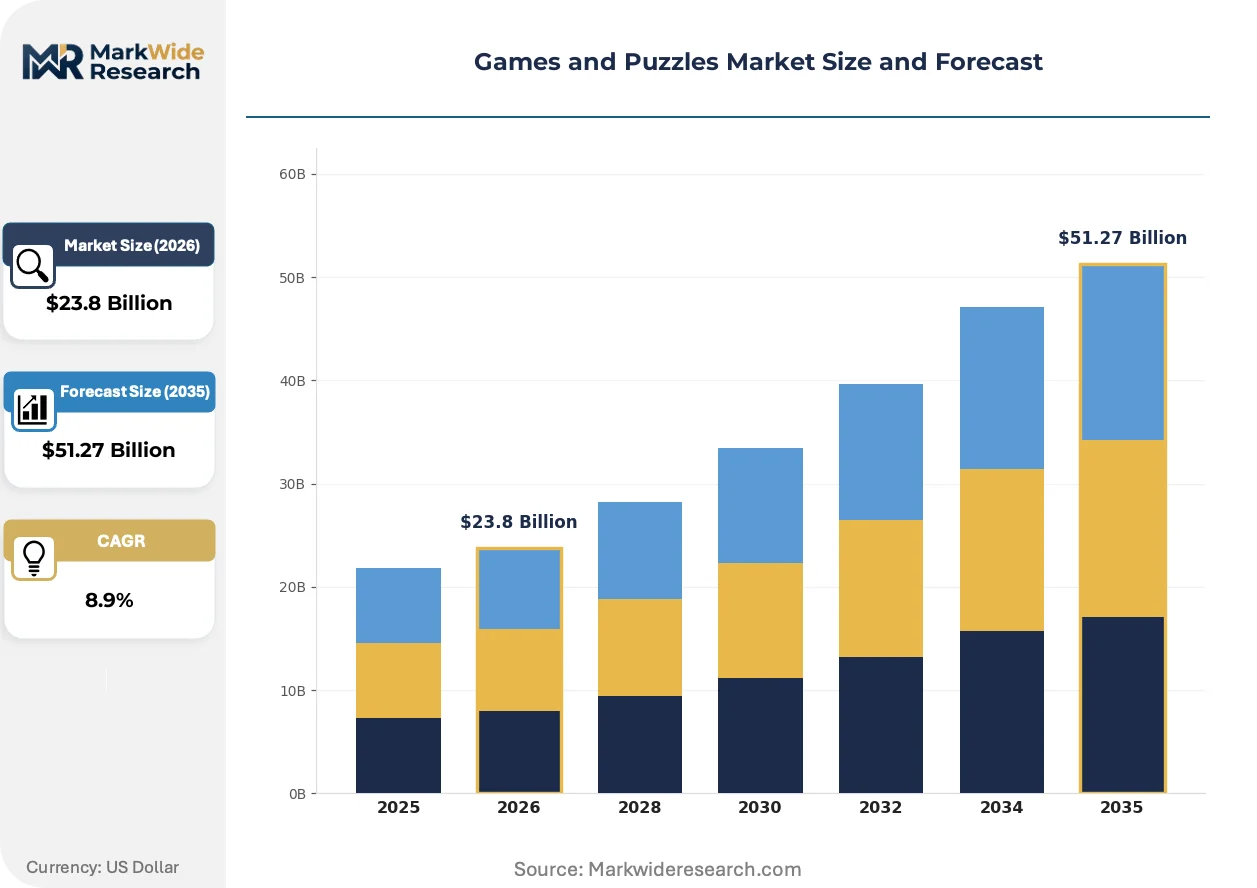
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $51.27 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board Games, Card Games, Jigsaw Puzzles, Dice Games Material: Wood, Plastic, Cardboard, Metal Age Group: Kids, Teens, Adults, Family Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Toy Stores |
| Companies Covered | Buffalo Games, Asmodee, Hasbro, Inc., Educa Borras, Ceaco, Inc., Mattel, Inc., LEGO, Schmidt Spiele, Ravensburger AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Games and Puzzles Market Strategic Shifts & Innovations
Three intersecting forces are restructuring how games and puzzles reach end users: manufacturing technology is compressing production timelines, regulatory frameworks are rewriting material specifications, and distribution channels are fragmenting across physical and digital touchpoints.
Digital printing systems are enabling variable data runs and personalized component customization at unit economics previously reserved for mass production. Boutique publishers in the United States and Germany are adopting these systems for limited-edition releases and Kickstarter fulfillment. This capability is digitizing how publishers test market response before committing to large-scale offset runs.
REACH enforcement through ECHA is mandating substance-by-substance disclosure for colored inks and plastic coatings used in children's products. Manufacturers serving European export markets are reformulating supply chains to eliminate SVHC candidates ahead of sunset dates. Small and mid-tier publishers without captive laboratories are outsourcing compliance verification to certified testing houses in the Netherlands and Switzerland.
Specialty board game cafés and direct-to-consumer subscription services are displacing traditional toy store and big-box retail as the primary discovery channel for adult hobbyists. United States metropolitan clusters including Austin, Seattle, and Chicago host dense networks of licensed venues where customers trial games before purchase. This behavioral shift is concentrating marketing spend toward experiential and community-based activation rather than shelf placement fees.
Games and Puzzles Market Segmentation
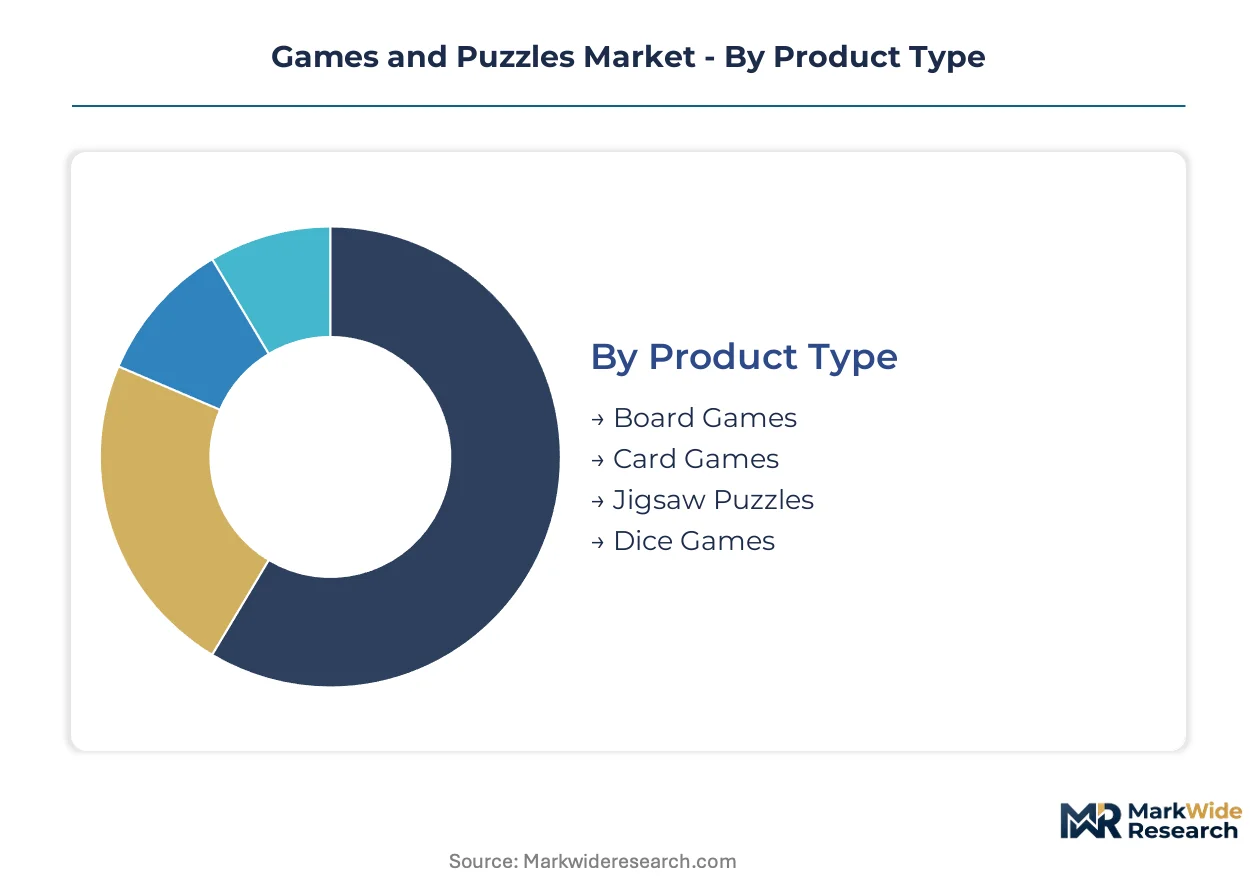
Product, material, and channel configurations in games and puzzles determine margin capture, regulatory exposure, and customer acquisition economics. Publishers align SKU portfolios against distinct usage occasions and durability expectations across household types.
Product Type:
Use cases span competitive strategy sessions, collaborative family entertainment, solitary mindfulness practice, and probabilistic gambling-style recreation.
- Board Games:Modular boards with tokens, cards, and dice deliver structured competitive or cooperative play. Demand concentrates in United States metropolitan markets where board game cafés convert trial into purchase, driven by millennial parents seeking screen-free family rituals.
- Jigsaw Puzzles:Interlocking die-cut pieces assembled into pictorial images provide meditative solo engagement. Adults in Germany and Austria specialty retail channels are expanding addressable volume fastest, drawn by mindfulness-oriented offline activities and premium archival-grade formulations.
- Card Games:Standardized decks enable portable, rules-light social interaction across travel and casual settings.
- Dice Games:Polyhedral randomizers support role-playing and quick-decision mechanics where tactile rolling enhances immersion.
Established volume favors board games; emerging adoption favors jigsaw puzzles.
Material:
Cost tiers separate premium heirloom-grade substrates from mass-market disposables, with regulatory compliance costs widening the gap.
- Cardboard:Laminated paperboard dominates volume production through offset printing compatibility and FSC certification accessibility. REACH-compliant European publishers are reformulating coatings to eliminate petroleum-based laminates, capturing preferential placement in Green Deal-aligned retail.
- Plastic:ABS and polypropylene deliver durability for dice, tokens, and interlocking mechanisms where repeated handling exceeds paper lifespan. United States mass-market distribution through Walmart and Target sustains entrenched share despite biodegradability constraints.
- Wood:Sustainably sourced hardwoods command artisan positioning in German and Austrian specialty channels.
- Metal:Zinc alloy and steel components serve premium collectible miniatures and precision-weighted dice subsets.
Plastic sustains volume leadership; cardboard is climbing the fastest on sustainability credentials.
Age Group:
Customer type determines safety testing intensity, complexity calibration, and price elasticity across household decision-making units.
- Adults:Hobbyist-grade titles with 90-180 minute playtimes and narrative depth command premium pricing. United States subscription box services and Seattle-Austin-Chicago café networks are concentrating demand among college-educated professionals seeking community-based leisure.
- Family:Cross-generational titles bridge competitive depth with accessible rulesets for mixed-age play. German and Austrian retailers prioritize this segment for holiday gifting occasions, driving seasonal volume spikes.
- Kids:CPSIA-mandated testing for under-twelve products shapes material selection and ink formulation.
- Teens:Social deduction and party games align with peer-group entertainment contexts and shorter attention windows.
Family segment anchors revenue concentration; adult segment shows steepest expansion trajectory.
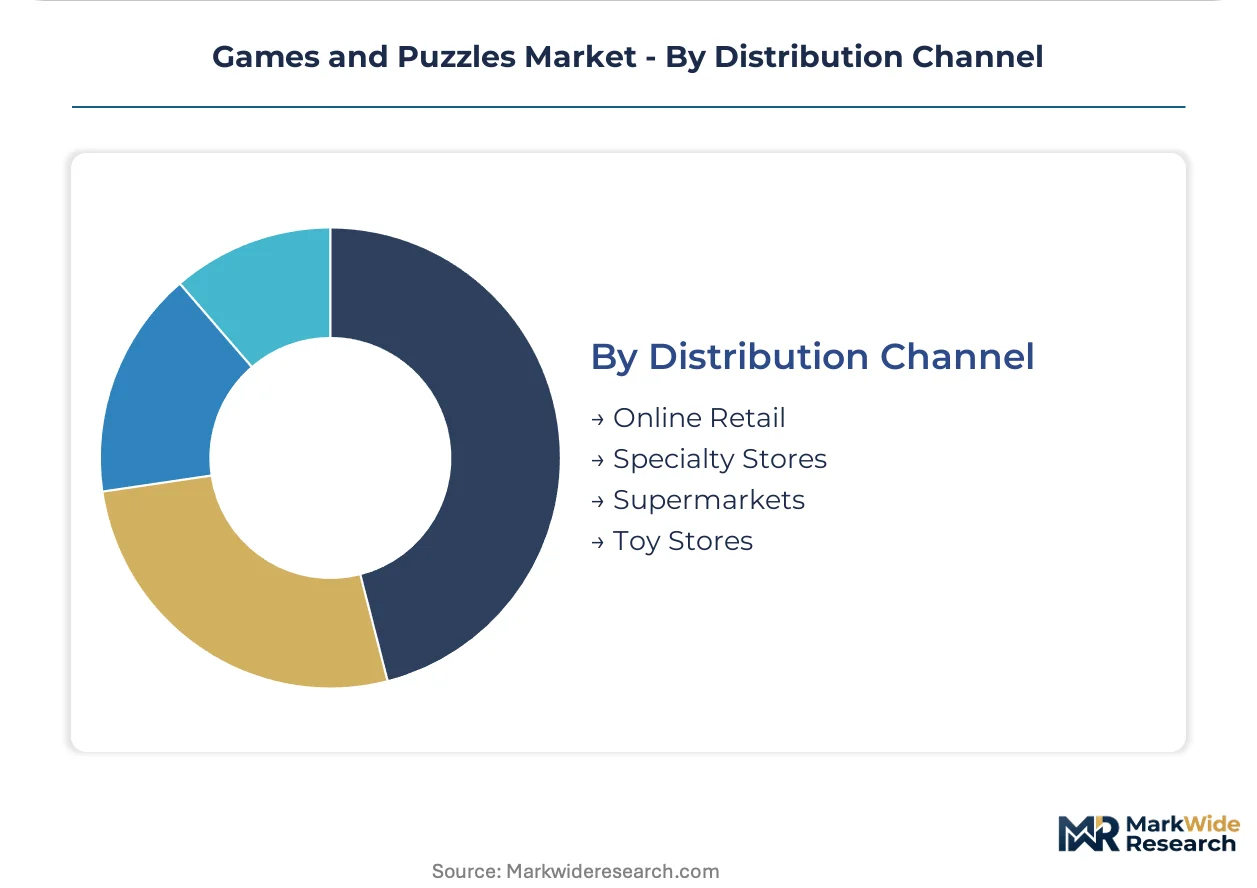
Distribution Channel:
Geography and fulfillment economics fragment across experiential discovery, convenience purchasing, and curated selection.
- Specialty Stores:Staff-curated inventories with demonstration tables enable tactile evaluation before purchase. German and Austrian independent retailers leverage precision die-cutting expertise and archival-grade cardboard sourcing to justify premium positioning.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators collapse geographic constraints for niche titles. United States Kickstarter fulfillment and subscription box services are displacing traditional discovery functions for hobbyist audiences.
- Supermarkets:Mass-market placements prioritize impulse visibility and sub-$20 price points for family segments.
- Toy Stores:Seasonal merchandising and licensed property tie-ins concentrate volume in fourth-quarter windows.
Specialty stores defend margin position; online retail gains share fastest on fulfillment convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
College-educated millennial parents in the United States, Germany, and Japan are redirecting household entertainment budgets toward screen-free tabletop experiences, creating concentrated demand pockets that reshape regional supply chains and retail formats.
United States
Board game cafés in Austin, Seattle, and Chicago convert trial into purchase through experiential marketing platforms. FDA oversees material safety for children's products under CPSIA, mandating third-party testing for phthalates and lead content. Subscription box services in metropolitan coastal corridors are displacing traditional toy store discovery for hobbyist audiences.
Germany
Specialty retailers in Bavaria and Baden-Württemberg leverage precision die-cutting expertise to justify premium positioning for archival-grade cardboard formulations. ECHA enforces REACH substance-by-substance disclosure for colored inks and plastic coatings, accelerating reformulation timelines. Stuttgart and Nuremberg manufacturing clusters supply FSC-certified substrates to EU Green Deal-aligned retail channels.
Japan
METI guidelines on sustainable packaging are pressuring publishers to eliminate petroleum-based laminates in favor of biodegradable alternatives. Tokyo and Osaka metropolitan areas host dense networks of hobby shops where adult collectors drive demand for limited-edition releases. JIS standards for toy safety shape material selection for family-oriented titles.
United Kingdom
London and Southeast England concentrate direct-to-consumer fulfillment infrastructure for Kickstarter campaigns and boutique publisher launches. UK REACH retains EU chemical disclosure mandates post-Brexit, requiring SVHC documentation for export-oriented manufacturers. Midlands-based printing houses are adopting digital systems for variable data runs and personalized component customization.
Canada
Health Canada regulates toy safety through the Canada Consumer Product Safety Act, aligning testing protocols with US CPSIA requirements. Toronto and Vancouver metropolitan clusters support board game café expansion and specialty retail growth. Prairie provinces are emerging as distribution hubs for US-market fulfillment, leveraging customs processing efficiencies.
Games and Puzzles Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. Mass-market distributors leverage Walmart and Target shelf placement dominance to sustain volume leadership in jigsaw puzzles and family board games. Premium-tier specialists anchor positioning through archival-grade materials and precision manufacturing. Strategic moves concentrate on SKU turnover acceleration for licensed properties and FSC-certified substrate adoption for EU market access.
Within the diversified entertainment conglomerate tier, Hasbro, Inc. and Mattel, Inc. represent scale-driven archetypes with captive manufacturing networks across multiple jurisdictions. Ravensburger AG exemplifies the precision-specialist position, anchoring premium market segments through die-cutting technology and German specialty retail relationships. Buffalo Games occupies the mass-market puzzle tier, competing on piece-count variety and big-box distribution density.
| Leading Market Players |
|---|
| Buffalo Games |
| Asmodee |
| Hasbro, Inc. |
| Educa Borras |
| Ceaco, Inc. |
| Mattel, Inc. |
| LEGO |
| Schmidt Spiele |
| Ravensburger AG |
| Others |
Cost & Logistics Intelligence
East Asian die-cutting and injection molding capacity clusters in Zhejiang and Guangdong provinces anchor cost structures for mass-market cardboard and plastic components, concentrating bargaining power with contract manufacturers who index raw material pass-throughs to petroleum and pulp futures. This upstream consolidation shapes how margin pools distribute between publishers with captive tooling networks versus those dependent on spot-market sourcing.
Pricing Analysis
Cost-plus contracts with petroleum-linked indexation dominate mass-market production agreements, locking publishers into margin volatility when crude oil spikes disrupt laminate coating costs. Three-tier pricing structure across premium, standard, and economy levels separates archival-grade FSC-certified formulations in German specialty retail from petroleum-laminated mass-market SKUs in Walmart and Target. Pricing pressure stems from REACH compliance investments in phthalate-free ink reformulation, which compresses margins for mid-tier publishers without testing house scale. Family segment buyers exhibit highest price sensitivity, while adult hobbyists tolerate premium positioning for limited-edition releases and Kickstarter exclusives.
Supply Chain Analysis
Petroleum-derived laminates and FSC-certified pulp feedstock from Scandinavian and Baltic suppliers constitute upstream dependencies for cardboard substrate production. Manufacturing concentrates in China for injection-molded plastic tokens and dice, Germany for precision die-cutting equipment, and Vietnam for emerging offset printing capacity. Single-source vulnerability runs through Zhejiang province tooling clusters, where die-cutting mold fabrication expertise outpaces training pipeline output. Distribution runs through board game café networks in Austin, Seattle, and Chicago for adult hobbyist discovery, alongside Walmart and Target mass-market dominance for family impulse purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as millennial and Gen Z parents redirect entertainment budgets toward screen-free family rituals following pandemic-era digital saturation.
For Market Incumbents: Insulate margin position by deepening captive control over FSC-certified substrate supply chains in Baltic and Scandinavian sourcing regions, while accelerating SKU turnover through AI-assisted prototyping to offset REACH compliance cost inflation. Precision die-cutting talent scarcity in traditional manufacturing regions demands proactive vocational pipeline investment or acquisition of specialized tooling houses. For New Entrants and Emerging Players: Subscription box services in underexploited United States metropolitan corridors represent the most penetrable entry point, with curated monthly deliveries bypassing shelf placement fee barriers that entrench mass-market incumbents. Direct-to-consumer Kickstarter fulfillment for limited-edition adult hobbyist titles offers a second white-space avenue, leveraging digital printing for variable data runs without large-scale offset commitment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU Green Deal-compliant manufacturing footprints as petroleum-based laminate elimination requires retooling investment. Acquisition targets should emphasize publishers with established FSC-certified supplier relationships and archival-grade cardboard formulation expertise. The signal to watch is ECHA sunset date acceleration for SVHC candidates, which will force compliance-driven consolidation among mid-tier players lacking testing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| FSC-Certified Substrate Adoption | Eliminates petroleum-based laminates to access EU Green Deal-compliant retail placement in Germany and Austria. |
| AI-Assisted Prototyping Deployment | Collapses development cycles from months to weeks, accelerating licensed property SKU turnover for seasonal windows. |
| Subscription Box Service Launch | Builds recurring revenue streams in United States metropolitan markets while bypassing traditional retail discovery costs. |
| Board Game Café Licensing Expansion | Creates experiential marketing platforms in Austin, Seattle, and Chicago that convert trial into direct purchase. |
| REACH Compliance Infrastructure Investment | Captures shelf space in German and Austrian specialty retail through phthalate-free formulation certification. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from publicly traded entertainment conglomerates, and ECHA substance registration databases. Primary interviews engaged game publisher product development executives, specialty retail category buyers in Bavaria and Baden-Württemberg, board game café operators in Austin and Chicago, and die-cutting equipment procurement managers. Bottom-up SKU-level volume modeling triangulates against top-down macroeconomic consumption indicators for household entertainment expenditure.
Forecast inputs incorporate product type segmentation across board games, jigsaw puzzles, card games, and dice games; material tiering across cardboard, plastic, wood, and metal substrates; and distribution channel dynamics spanning specialty stores, online retail, supermarkets, and toy stores. CAGRs derive from regression analysis against historical household entertainment budget allocation shifts and digital detox trend penetration rates across the analysis window. Industry-specific inputs include REACH compliance timeline acceleration and FSC certification adoption curves in EU export markets.
Practitioners should monitor ECHA SVHC candidate list expansion and crude oil futures volatility for early signals requiring forecast revision. Cross-checking against Nielsen retail audit data for United States hobby game sales is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
China Toys Market
Toys and Games
Snooker Tables Market
Toys and Games
Plush Toy Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Plastic Toy Storage Market
Toys and Games
Kid's Microphone Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Connected Toys Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Kids Toys Market
Toys and Games
Baby Toys Market
Toys and Games
Global Stem Toys Market