
 Animation Toys Market | 2026-2036
Animation Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Animation Toys Market Outlook
Digital sculpting and AI-assisted character modeling is tilting production pipelines toward shorter design cycles and rapid prototyping. Hasbro leverages its entertainment studio partnerships to synchronize toy releases with streaming content launches. Bandai Namco Holdings anchors its competitive position through deep integration with anime intellectual property ecosystems. Spin Master differentiates via robotics-infused animatronics that merge physical play with programmable behaviors.
Animation toys are three-dimensional consumer products derived from licensed or original animated intellectual property, typically fabricated through injection molding of ABS or PVC resins, rotational casting of soft vinyl, or textile assembly with embroidered digital-printed graphics, designed primarily for narrative play, display collecting, or character emulation. Action figures and collectibles command the dominant margin pools due to adult collector willingness to pay premium prices for limited editions and chase variants. Plush toys sustain volume leadership in the preschool channel where fabric construction meets stringent mouthability and seam-strength standards. Playsets face structural pressure as space-constrained urban households favor compact single-figure purchases over large footprint diorama sets.
The US Consumer Product Safety Commission enforces ASTM F963 mechanical and chemical safety standards that govern small-part choking hazards and heavy-metal content limits, directly shaping material selection and testing costs for export-bound manufacturers. The EU Toy Safety Directive and REACH chemical registration framework impose parallel compliance burdens that segment the supplier base between certified premium-tier producers and uncertified value players. China's SAMR administers mandatory CCC certification for domestic toy sales while its GB 6675 standards increasingly align with international protocols. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation becomes a decisive factor in supplier qualification and margin structure.
Market Dynamics
Streaming platform release calendars now dictate animation toy production cycles, compressing traditional 18-month development windows into synchronized drops that demand agile manufacturing responses from Southeast Asian suppliers.
Growth Catalysts
- GB 6675 Alignment:China's SAMR is harmonizing domestic toy safety standards with international ASTM F963 protocols, reducing dual-certification costs for export-oriented manufacturers.
- AI-Assisted Sculpting:Digital character modeling tools are slashing prototype development timelines from weeks to days across design studios.
- Preschool Channel Expansion:Fabric-based plush construction meeting mouthability standards is capturing shelf space in early childhood retail formats.
Market Restraints
- ABS Resin Volatility:Petrochemical feedstock price swings inject margin unpredictability into injection-molded figure production.
- Dongguan-Shenzhen Concentration:Over 60% of rotational vinyl casting capacity sits within a 100-kilometer corridor, creating single-point vulnerability.
- REACH Chemical Friction:ECHA's expanding SVHC candidate list forces continuous reformulation of PVC plasticizers and textile dyes.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for toy manufacturing are attracting greenfield molding facility investments in Maharashtra and Tamil Nadu.
- Programmable Animatronics:Robotics-infused toys merging physical play with coding education represent unpenetrated price tiers above traditional action figures.
- Direct-to-Collector Platforms:Crowdfunding and subscription models bypass wholesale markups for limited-edition chase variants.
Industry Challenges
- Phthalate Substitution Chemistry:Reformulating soft vinyl compounds to meet tightening GB and REACH restrictions demands specialized polymer science talent in short supply.
- CCC Certification Timelines:China's mandatory domestic market approval processes create 4-6 month launch delays versus parallel export tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animation Toys Market |
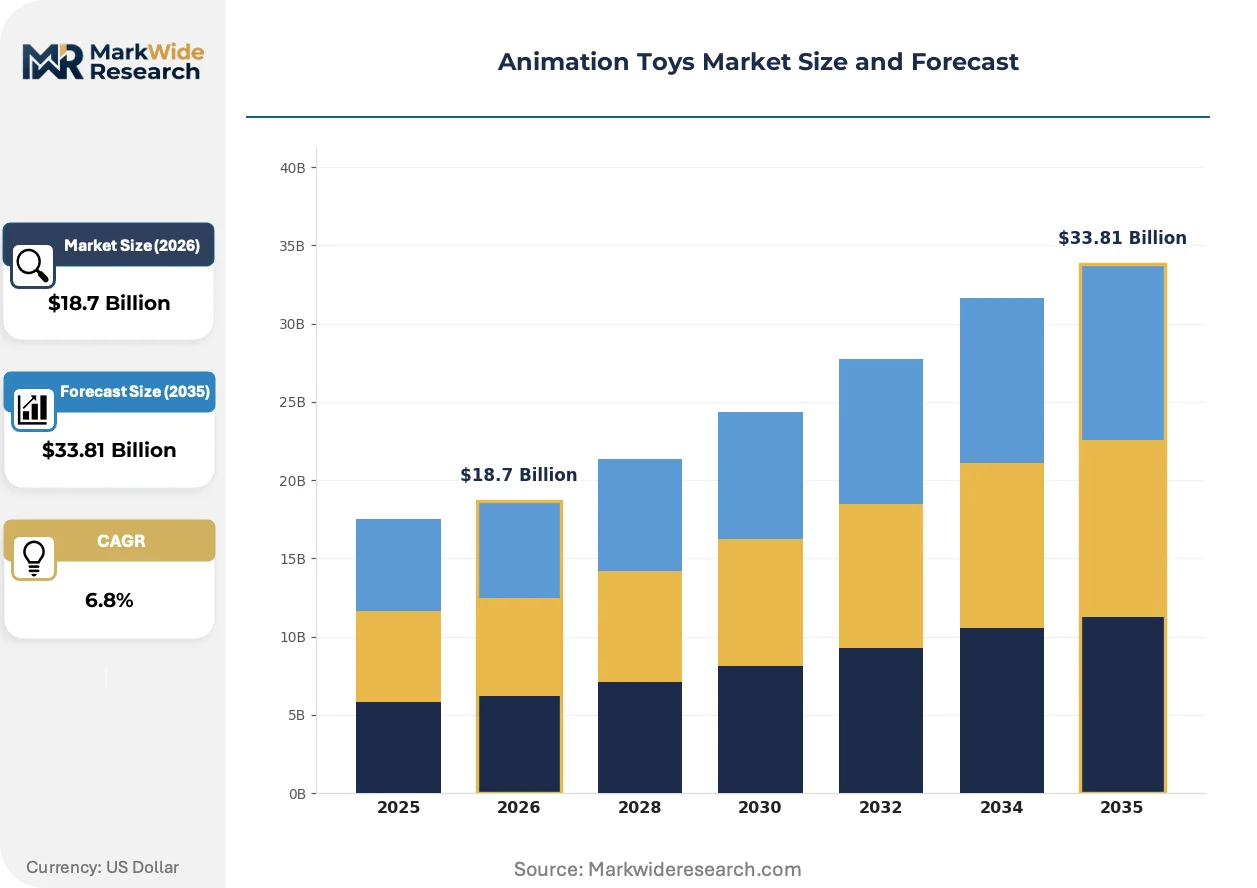
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Plush Toys, Playsets, Collectibles Age Group: Toddlers, Preschoolers, Kids, Pre-Teens Material: Plastic, Fabric, Wood, Metal Distribution Channel: Online Retailers, Toy Stores, Department Stores, Specialty Shops |
| Companies Covered | Hasbro, Mattel, The LEGO Group, Bandai Namco Holdings, Spin Master, Good Smile Company, MGA Entertainment, Funko, McFarlane Toys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animation Toys Market Strategic Shifts
Production pipelines are rewiring around real-time audience analytics from streaming platforms, enabling demand-responsive manufacturing that reduces inventory risk for seasonal character properties.
Photogrammetry and 3D scanning is digitizing legacy hand-sculpting workflows in collectible figure design. Premium adult collector segments are adopting these tools fastest, expecting 90-day turnarounds from screen debut to physical prototype. This compression is digitizing traditional seasonal buying cycles into year-round drop culture.
REACH's expanded SCIP database obligations are forcing component-level chemical traceability across EU-bound supply chains. Manufacturers must now document safe-use instructions for every ABS pellet and textile dye lot. Small-batch artisan producers face disproportionate compliance burdens versus certified mid-tier competitors.
Collector purchasing is fragmenting across specialized subscription boxes, convention exclusives, and platform-direct preorders. Mass retail big-box placement is losing share to curated unboxing experiences and influencer-curated drops. This channel rotation is most pronounced in North American and Western European urban markets where hobby shop networks have digitized their fulfillment infrastructure.
Animation Toys Market Segmentation
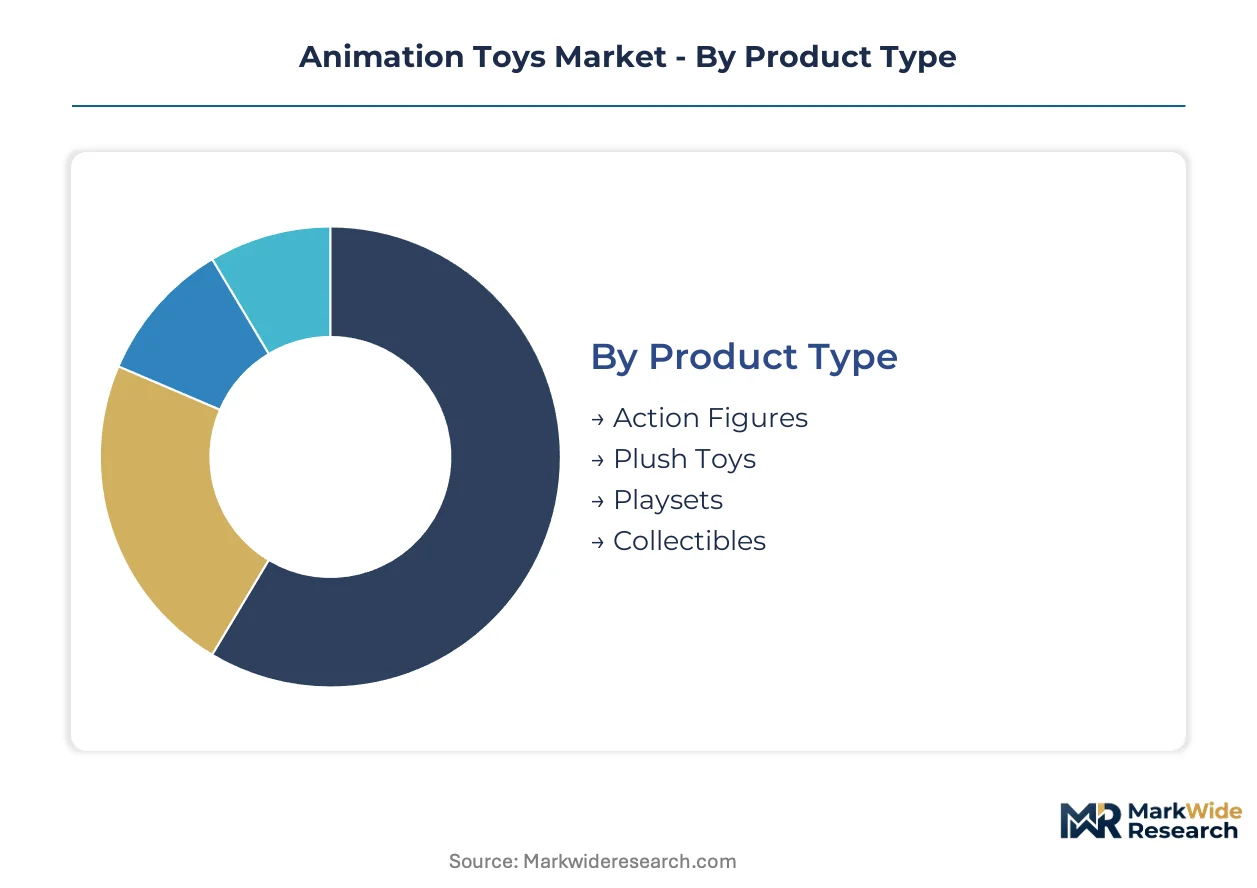
Animation toys fragment across four intersecting dimensions that determine margin structure, compliance burden, and channel strategy. Product type and age group dominate portfolio allocation decisions, while material selection and distribution channel shape working capital intensity and geographic reach.
Product Type:
Mature injection-molded categories coexist with emerging robotics-infused formats that command premium positioning.
- Action Figures:Articulated ABS or PVC constructs with multiple points of movement and interchangeable accessories. Demand clusters in adult collector segments across the United States and Japan, where limited-edition drops and chase variants sustain 40-60% gross margins despite volatile petrochemical feedstock costs.
- Plush Toys:Fabric-based constructions employing polyester fill and embroidered or digital-printed surface graphics. Southeast Asian manufacturing clusters in Vietnam and Indonesia dominate output for this segment, serving preschool retail channels where mouthability standards under ASTM F963 and GB 6675 dictate seam-strength specifications and fiber composition.
- Playsets:Diorama-scale environments with multiple figures and interactive components, typically occupying larger retail footprints.
- Collectibles:Static display pieces emphasizing sculptural fidelity over articulation, often produced in numbered limited runs.
Action Figures handles the majority of throughput; Collectibles is expanding most quickly on share.
Age Group:
Developmental stage determines safety certification tier, material restrictions, and permissible small-part geometries.
- Toddlers:Products engineered for children under three years, subject to the most stringent choking hazard prohibitions and mouthability testing under CPSC and EU Toy Safety Directive protocols.
- Preschoolers:Children aged three to five represent the fastest-expanding demand pool as parental purchasing prioritizes developmental play outcomes. Fabric-based plush construction captures disproportionate shelf space in early childhood retail formats across Germany and the United Kingdom.
- Kids:The five-to-eight demographic drives volume for action figure and playset categories tied to streaming content synchronization.
- Pre-Teens:Older children transition toward collectible-grade products with higher per-unit price points and hobbyist community engagement.
Preschoolers commands the steepest volume trajectory; Toddlers operates under the tightest regulatory constraints.
Material:
Supply concentration and chemical compliance burden vary dramatically across substrate categories.
- Plastic:ABS and PVC resins processed through injection molding or rotational casting dominate figure production. REACH SVHC candidate list expansion and China's phthalate restrictions under GB standards force continuous reformulation of plasticizers and colorants.
- Fabric:Polyester, cotton, and blended textiles with embroidered or heat-transfer graphics. This material anchors plush construction for preschool channels, with compliance focused on seam strength, fiber migration, and flammability standards.
- Wood:Sustainable timber substrates gaining traction in premium European markets under CSRD-aligned sourcing requirements.
- Metal:Die-cast zinc alloys and stamped steel components for high-durability articulated joints and display bases.
Plastic absorbs the largest share of raw material procurement; Fabric is climbing fastest on regulatory preference.
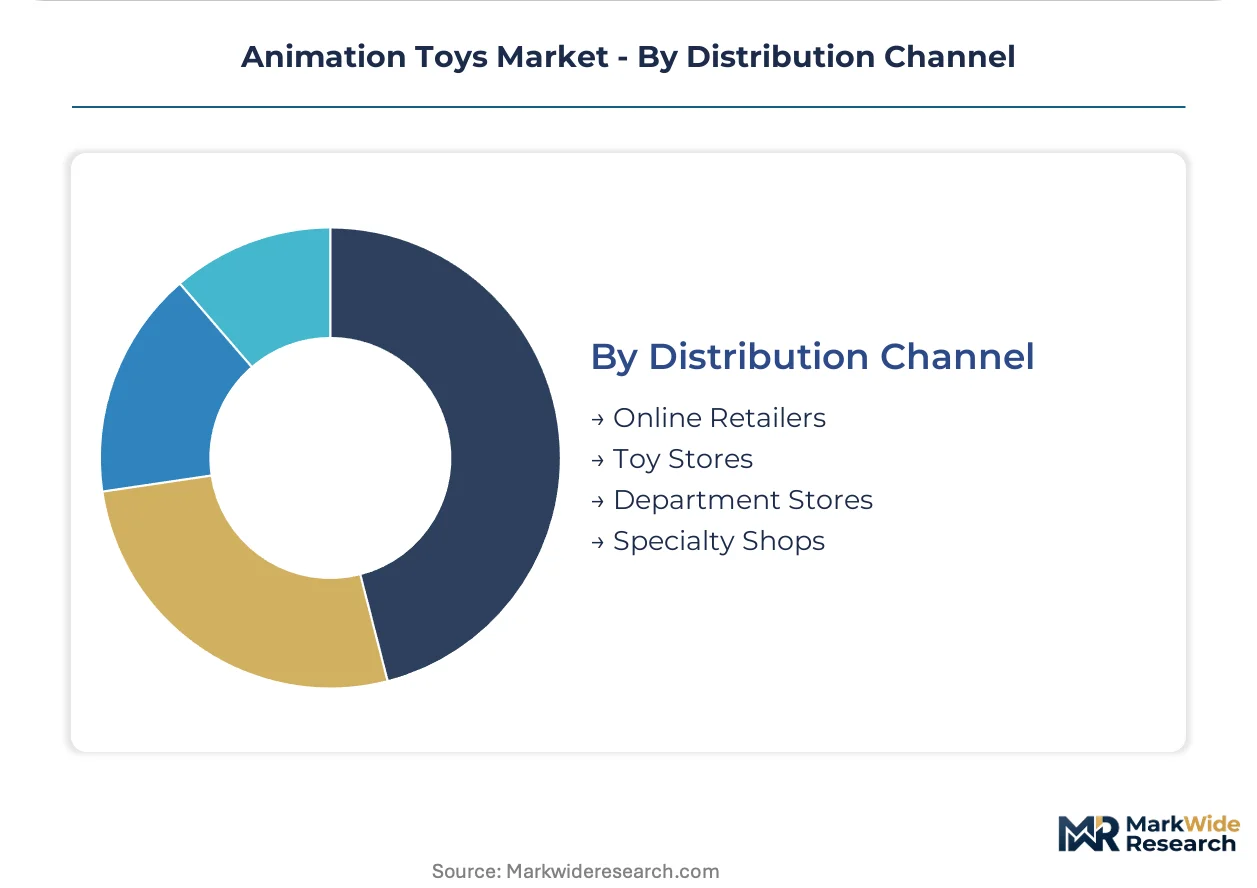
Distribution Channel:
Channel selection determines margin capture, inventory risk allocation, and collector community access.
- Online Retailers:Platform-direct sales including Amazon, dedicated hobby sites, and brand-owned storefronts. This channel is displacing mass retail fastest in North American and Western European urban markets where influencer-curated drops and subscription box models concentrate collector demand.
- Toy Stores:Specialized retail chains and independent hobby shops with digitized fulfillment infrastructure.
- Department Stores:Legacy big-box placement facing structural pressure from space-constrained urban households favoring compact single-figure purchases.
- Specialty Shops:Convention exclusives, curated unboxing experiences, and platform-direct preorders serving premium collector segments.
Online Retailers captures the dominant share of growth; Department Stores is losing ground to specialized formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished animation toys through Shenzhen and Hong Kong ports to United States and German retail channels, while Vietnam and Indonesia serve as secondary fabrication hubs for fabric-based plush construction bound for European preschool markets.
United States
Adult collector demand for limited-edition action figures and chase variants sustains premium pricing tiers in urban hobby shop networks and platform-direct channels. The Consumer Product Safety Commission enforces ASTM F963 standards governing small-part choking hazards and heavy-metal content limits. Los Angeles and New York City concentrate entertainment studio licensing offices that synchronize toy releases with streaming content calendars.
China
Domestic preschool demand for developmental plush toys accelerates alongside parental purchasing power in tier-one cities. The State Administration for Market Regulation administers mandatory CCC certification for domestic sales while GB 6675 standards harmonize with international protocols. The Dongguan-Shenzhen corridor hosts over sixty percent of global rotational vinyl casting capacity for collectible figure production.
Germany
CSRD-aligned sourcing requirements drive preference for sustainable timber substrates in premium European markets. The EU Toy Safety Directive and ECHA's REACH framework impose chemical registration obligations on PVC plasticizers and textile dyes. Bavaria and North Rhine-Westphalia concentrate distribution infrastructure serving centralized European retail networks.
Japan
Anime intellectual property ecosystems anchor collector-grade figure demand across adult hobbyist segments with exceptional margin retention. METI oversees product safety standards while industry associations coordinate JIS alignment with export market requirements. Tokyo and Osaka house design studios leveraging photogrammetry and 3D scanning to compress prototype development timelines.
India
Production-linked incentive schemes attract greenfield injection molding investments targeting export markets and domestic preschool channel expansion. The Bureau of Indian Standards administers toy safety certifications while state industrial policies compete for manufacturing relocation from Southeast Asian clusters. Maharashtra and Tamil Nadu emerge as primary investment destinations for multinational fabrication facilities.
Animation Toys Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base clusters around three strategic archetypes: entertainment-integrated conglomerates with studio partnerships, robotics-infused animatronics specialists, and collectible-grade figure artisans serving adult hobbyist segments. Competitive moves concentrate on M&A for intellectual property portfolios and strategic partnerships for streaming content synchronization.
Within the entertainment-integrated tier, Hasbro and Bandai Namco Holdings exemplify archetypes leveraging studio relationships to align physical product releases with streaming content calendars. Mattel occupies a position representing scale-driven fabrication capacity serving mass retail channels across multiple age demographics. These three entities anchor distinct competitive vectors: content synchronization, manufacturing scale, and intellectual property depth.
| Leading Market Players |
|---|
| Hasbro |
| Mattel |
| The LEGO Group |
| Bandai Namco Holdings |
| Spin Master |
| Good Smile Company |
| MGA Entertainment |
| Funko |
| McFarlane Toys |
| Others |
Value Chain & Pricing Dynamics
Shenzhen-Hong Kong freight corridors transmit ABS resin cost volatility directly into Southeast Asian factory gate pricing, amplifying margin compression for injection-molded figure producers while enabling certified premium-tier manufacturers to capture widening price spreads over uncertified competitors.
Pricing Analysis
Current-generation programmable animatronics command 3-4x per-unit premiums over prior-generation static figures, while next-generation AI-integrated prototypes remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates adult collector limited editions from mass retail preschool plush and value-channel unbranded imports. Pricing pressure stems from petrochemical feedstock instability and REACH compliance reformulation costs. Adult collectors exhibit lowest price sensitivity; mass retail preschool channels face acute margin compression.
Supply Chain Analysis
Export-control friction around advanced robotics components and AI chipsets constrains programmable animatronics scaling for smaller manufacturers. Manufacturing gravity centers on China's Dongguan-Shenzhen corridor, Vietnam's Ho Chi Minh City industrial zones, and Indonesia's Jakarta-Bandung textile belt. Production draws from ABS/PVC petrochemical feedstocks, polyester textile fibers, and servo motor assemblies. Single-source vulnerability concentrates in rotational vinyl casting capacity within the 100-kilometer Dongguan-Shenzhen corridor. Distribution runs through platform-direct channels, specialized hobby networks, and mass retail big-box placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment moat where CCC certification timelines and REACH compliance burdens create asymmetric barriers favoring incumbents with dedicated polymer science teams and pre-qualified supplier networks.
For Market Incumbents: Harden defensive positioning through backward integration into ABS compound formulation capabilities and captive rotational casting capacity in Maharashtra under India's PLI scheme. Counter emerging robotics-infused specialists by accelerating photogrammetry-to-prototype pipelines. Certification investment in GB 6675-ASTM F963 dual compliance anchors supplier qualification advantages. For New Entrants and Emerging Players: India's underpenetrated domestic preschool channel offers white-space expansion as production-linked incentives attract greenfield molding investments. Target fabric-based plush construction for tier-one Chinese cities where developmental play purchasing accelerates. Platform-direct crowdfunding models bypass wholesale markups for limited-edition collector segments. For Investors and Strategic Acquirers: Carve-out targets emerge from entertainment conglomerates divesting non-core toy divisions amid streaming studio consolidation. Long-term viability rests on intellectual property depth and manufacturing certification portfolios rather than transient content licensing. Watch for phthalate substitution chemistry breakthroughs as inflection signals enabling margin recovery in soft vinyl segments.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-Infused Product Line Launch | Programmable animatronics capture premium tiers above traditional action figures in education-adjacent positioning. |
| Direct-to-Collector Platform Buildout | Subscription and crowdfunding models bypass wholesale markups for limited-edition chase variants in urban markets. |
| GB 6675-ASTM F963 Dual Certification Investment | Harmonized compliance reduces dual-certification costs for export-oriented manufacturers serving US and Chinese retail channels. |
| Photogrammetry Pipeline Acceleration | 3D scanning compresses prototype timelines from weeks to days for streaming-synchronized character releases. |
| India PLI Scheme Manufacturing Relocation | Greenfield injection molding investments in Maharashtra and Tamil Nadu diversify supply concentration risk from Dongguan-Shenzhen corridor. |
Study Parameters
Operator-level perspectives from toy design studio leads, Southeast Asian factory operations managers, retail category buyers, and polymer compliance specialists anchored the qualitative base. Secondary validation drew from customs export records, CPSC recall databases, ECHA SVHC candidate list updates, and streaming platform content calendars. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Scenario-bracketing framed demand projections across conservative, baseline, and aggressive streaming content release assumptions over the projection horizon. Segmentation modeling incorporated product type, age group developmental stage, material substrate, and distribution channel intensity. CAGRs derived from fitted growth curves against historical toy category lifecycles and content property decay patterns. Inputs included petrochemical price indices, certification timeline distributions, and channel shift velocity metrics.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by entertainment conglomerates or sudden phthalate regulatory bans would shift outcomes. Material shifts in REACH SVHC list expansion velocity or India's PLI scheme uptake rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Plastic Toy Storage Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Snooker Tables Market
Toys and Games
Die-Cast Toys Market
Toys and Games
Kid's Microphone Market
Toys and Games
Fabric Toys Market
Toys and Games
Drone for Kids Market
Toys and Games
United States Toys Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Kids Toys Market
Toys and Games
Toy Collectibles Market
Toys and Games
Dartboard Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Inflatable Toys Market