
 Global Smart Ring Market | 2026-2036
Global Smart Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Ring Market Outlook
Modular sensor packaging is realigning how buyers evaluate smart rings against wrist-worn alternatives. Oura Health leverages its vertical integration into sleep-scoring algorithms to sustain premium positioning across direct-to-consumer channels. Samsung Electronics anchors its ecosystem strategy by embedding ring data into Galaxy Health dashboards, while Ultrahuman Healthcare competes through glucose-monitoring integration that extends its addressable base beyond fitness into metabolic health.
A smart ring is a finger-worn computing device incorporating photoplethysmography sensors, accelerometers, and temperature monitors within a titanium or ceramic housing typically weighing under four grams, designed to capture cardiovascular, sleep, and activity metrics with minimal user friction. Health monitoring rings dominate current revenue pools due to recurring subscription models for longitudinal data, while payment rings represent the fastest-growing technology segment as NFC-enabled transit and retail authentication expands in Asia-Pacific urban centers. Bluetooth connectivity remains the mature baseline across all price tiers, though biometric sensor density now separates premium hardware from economy alternatives.
FDA clearance pathways for pulse oximetry and ECG functions shape product development timelines for vendors targeting clinical credibility in the United States, while EMA's MDR classification in Europe demands notified-body involvement for any ring claiming diagnostic output. China's NMPA maintains separate standards for wearable medical devices that delay market entry without local testing partnerships. Stakeholders must monitor whether regulatory divergence between FDA's software-as-medical-device framework and EMA's stricter hardware-plus-algorithm bundling forces parallel certification investments or geographic product segmentation.
Market Dynamics
Modular photoplethysmography sensor packaging is compressing development cycles and forcing hardware vendors to choose between algorithmic differentiation and component commoditization. This structural pressure separates premium clinical-grade offerings from consumer fitness accessories.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Healthcare providers in Germany and France now require explainable biometric scoring for continuous patient monitoring, creating procurement preference for vendors with certified machine-learning documentation.
- Recurring subscription revenue models:Sleep clinics and corporate wellness programs in the United States prioritize longitudinal data access over hardware margins, locking in multi-year contracts for population health analytics.
- Photoplethysmography miniaturization:Taiwan-based semiconductor foundries have reduced PPG die sizes below 2mm², enabling three-sensor arrays within sub-four-gram titanium housings previously limited to single-channel designs.
Market Restraints
- Lithium-polymer cell volatility:Battery chemistry costs fluctuate with cobalt and lithium carbonate spot markets, compressing gross margins on economy-tier rings priced below manufacturing cost recovery thresholds.
- Notified-body capacity constraints:EMA's MDR classification for diagnostic-output rings faces eighteen-month certification queues at TÜV SÜD and BSI, freezing product launches for European clinical claims.
- Wrist-worn smartwatch substitution:Apple Watch and Garmin devices with FDA-cleared ECG functions capture overlapping health-conscious consumers, particularly in United States direct-to-consumer channels.
Strategic Opportunities
- India's PLI scheme for wearable electronics:Manufacturing incentives covering 4-6% of incremental sales value attract assembly relocation from China, with BIS certification streamlining domestic market entry.
- Glucose-monitoring ring convergence:Non-invasive optical glucose sensing is converging with metabolic health platforms, opening addressable base beyond fitness into Type 2 diabetes management.
- NFC payment ring expansion:Transit authority mandates in Singapore, Japan, and South Korea are accelerating contactless authentication adoption across Asia-Pacific urban centers.
Industry Challenges
- FDA 510(k) clearance timelines:Pulse oximetry and ECG algorithm submissions face fourteen-month review cycles for software-as-medical-device classification, delaying revenue recognition.
- Biometric data science talent scarcity:Signal processing engineers with photoplethysmography artifact rejection expertise command premium compensation, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Ring Market |
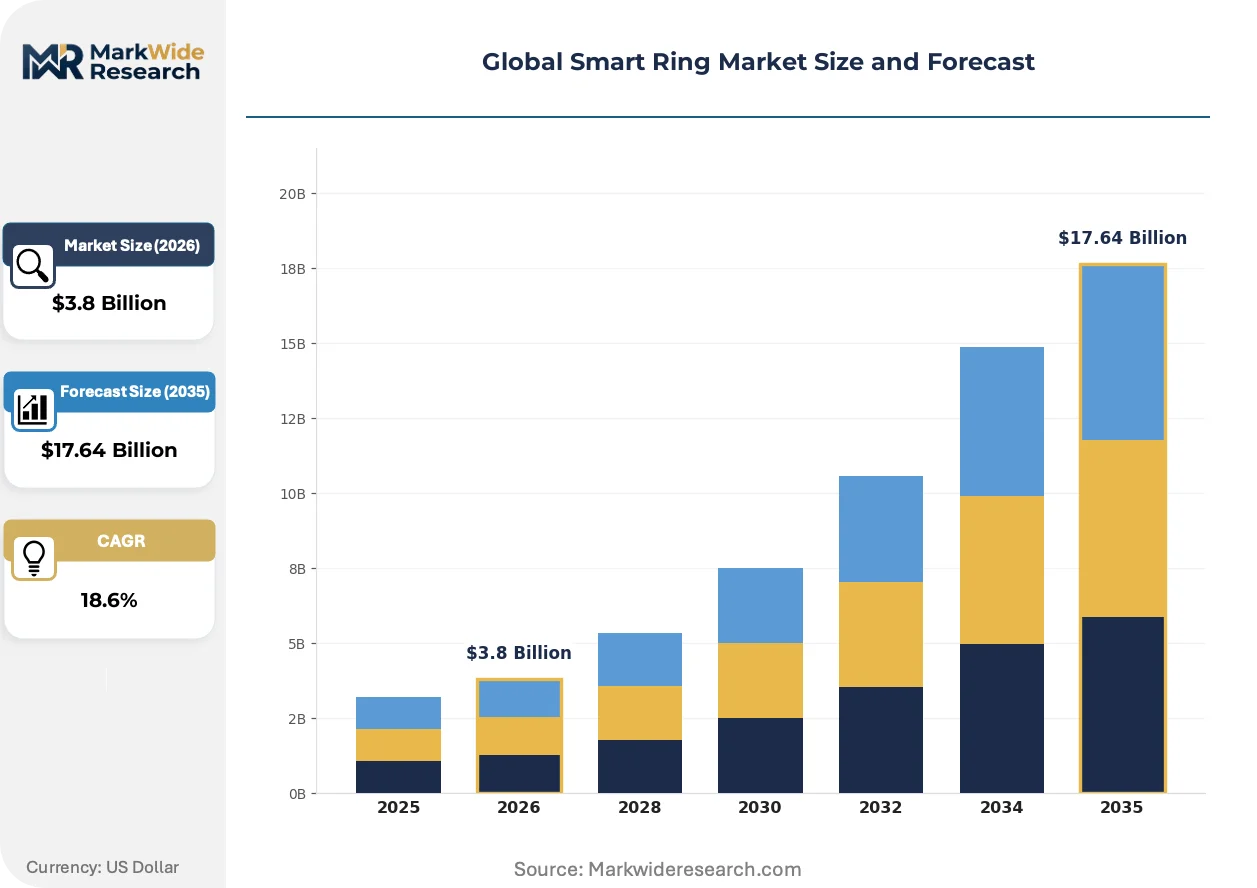
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Rings, Payment Rings, Health Monitoring Rings, Communication Rings Technology: NFC, Bluetooth, Biometric Sensors, Gesture Control End User: Consumers, Healthcare Providers, Sports Enthusiasts, Tech Professionals Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Oura Health, Ultrahuman Healthcare Pvt Ltd, Samsung Electronics Co., Ltd., RingConn LLC, Movano Health, Inc., Zepp Health Corporation, Circular SAS, Noise, boAt Lifestyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Ring Market Strategic Shifts
Sensor fusion architectures are collapsing discrete measurement categories into unified cardiovascular-metabolic profiles. This integration is redrawing competitive boundaries between fitness accessory vendors and clinical diagnostic suppliers.
Multi-wavelength photoplethysmography is converging with accelerometer-derived motion compensation to enable continuous blood pressure estimation without cuff calibration. Samsung Electronics and Oura Health have deployed six-LED PPG arrays in 2024 hardware refreshes. Clinical validation partnerships with Cleveland Clinic and Stanford Sleep Medicine are compressing the credibility gap between consumer wearables and ambulatory monitoring devices.
EMA's MDR Article 10 post-market surveillance requirements now mandate algorithmic performance tracking across diverse skin tone populations. This regulatory pressure forces biometric vendors to expand training datasets beyond Fitzpatrick Type I-III representation. Rings claiming SpO2 accuracy must submit clinical equivalence studies to notified bodies, with Germany's BfArM scrutinizing melanin-dependent signal attenuation claims.
Enterprise procurement teams at self-insured employers are unbundling hardware from analytics subscriptions, negotiating per-employee-per-month fees for aggregated sleep and stress metrics. This purchasing model shift displaces upfront device subsidies with outcome-contingent pricing. United States Fortune 500 wellness programs in financial services and technology verticals have adopted this structure earliest.
Global Smart Ring Market Segmentation
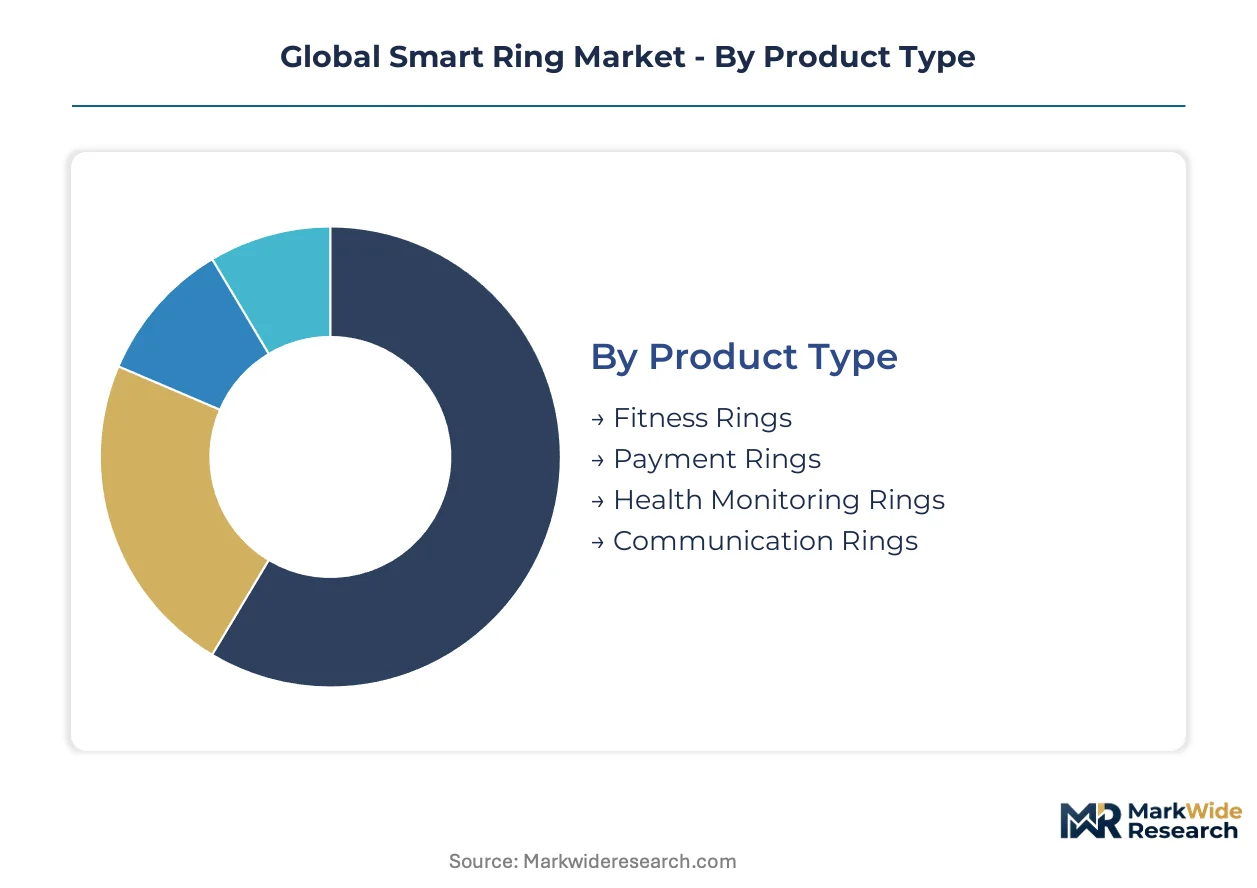
Smart ring segmentation reveals divergent paths to profitability across hardware commoditization and algorithmic premium capture. Understanding where volume concentrates versus where margins accrue determines portfolio allocation for component suppliers and platform vendors alike.
Product Type:
Volume concentrates in health monitoring variants while payment-enabled rings command premium unit economics through financial services partnerships.
- Health Monitoring Rings:Photoplethysmography, accelerometer, and temperature sensors packaged in titanium housings under four grams capture cardiovascular, sleep, and metabolic metrics. Demand concentrates in United States direct-to-consumer channels where recurring subscription models for longitudinal data sustain hardware margins. FDA 510(k) clearance pathways for pulse oximetry and ECG functions separate clinical-grade offerings from fitness accessories.
- Payment Rings:NFC-enabled titanium or ceramic housings facilitate transit and retail authentication without battery dependence. Singapore, Japan, and South Korea transit authority mandates are accelerating adoption across Asia-Pacific urban centers where contactless infrastructure penetration exceeds wrist-worn alternatives.
- Fitness Rings:Accelerometer and basic heart rate monitoring target gym-centric users seeking minimal friction alternatives to smartwatches.
- Communication Rings:Gesture control and haptic feedback enable discrete notification management for tech professionals in meeting-intensive environments.
Today's leader: Health Monitoring Rings. Tomorrow's challenger: Payment Rings.
Technology:
Connectivity maturity separates baseline functionality from premium differentiation as biometric sensor density becomes the new margin lever.
- Biometric Sensors:Multi-wavelength photoplethysmography arrays with six-LED configurations enable continuous blood pressure estimation and glucose monitoring convergence. Taiwan-based semiconductor foundries have reduced PPG die sizes below 2mm², enabling three-sensor arrays within sub-four-gram housings previously limited to single-channel designs.
- NFC:Passive 13.56MHz communication enables payment and access authentication without battery dependence, extending operational lifespan indefinitely.
- Bluetooth:Low-energy 5.3 protocols remain the mature baseline across all price tiers, with firmware updates extending hardware utility cycles.
- Gesture Control:Inertial measurement unit arrays interpret finger motions for device-agnostic input commands.
Current margin anchor: Biometric Sensors. Steepest expansion trajectory: NFC.
End User:
Procurement authority distinguishes consumer impulse purchases from enterprise contract negotiations with outcome-contingent pricing.
- Healthcare Providers:German and French hospital systems now require EU AI Act-compliant explainable biometric scoring for continuous patient monitoring, creating procurement preference for vendors with certified machine-learning documentation and EMA MDR classification.
- Consumers:United States willingness to pay for premium health tracking devices remains strongest globally, with direct-to-consumer channels absorbing hardware-plus-subscription bundles.
- Sports Enthusiasts:Marathon runners and triathletes prioritize minimal-weight form factors that preserve biomechanical efficiency during extended exertion.
- Tech Professionals:Software engineers and product managers in San Francisco and Seattle metro areas adopt gesture-enabled variants for discrete notification management.
Contract volume leader: Healthcare Providers. Fastest-growing addressable base: Consumers.
Distribution Channel:
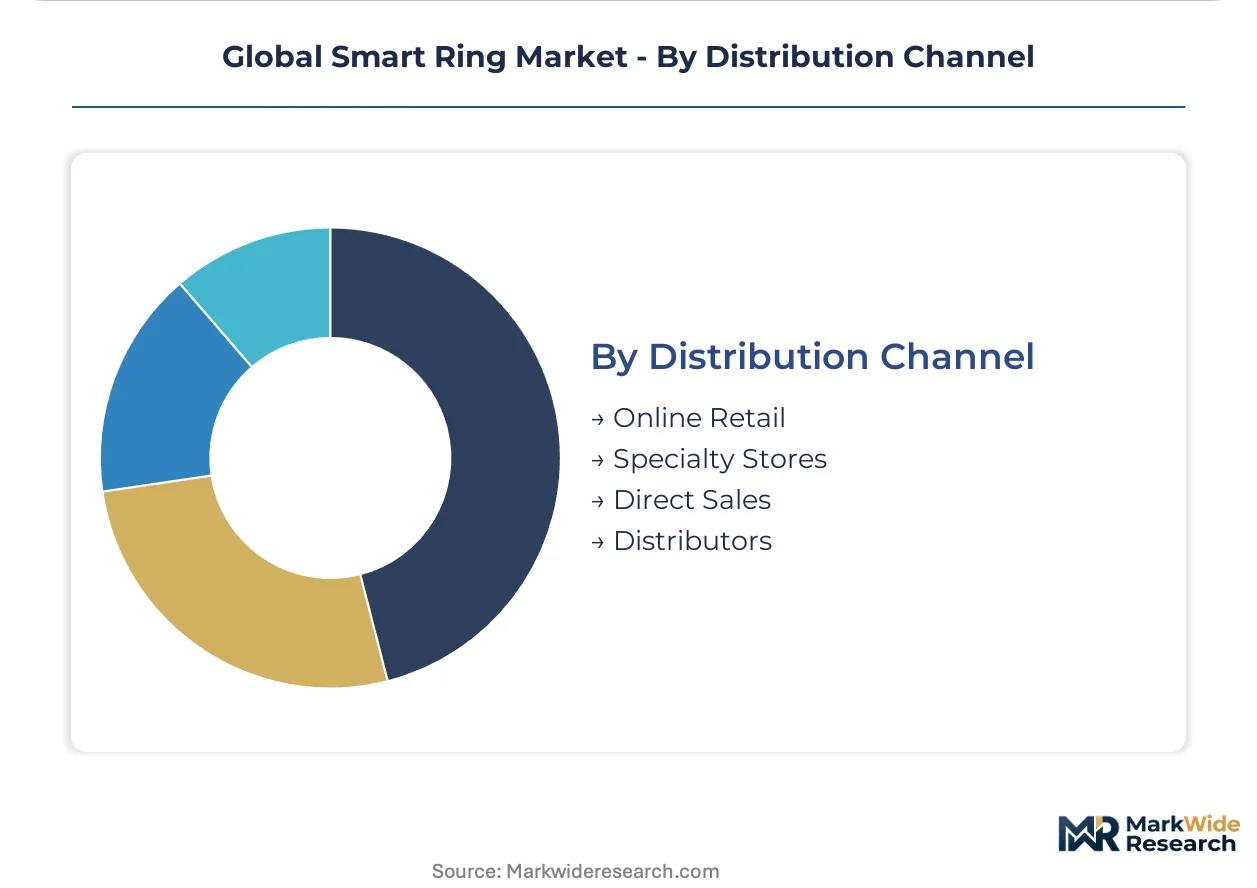
Channel selection determines customer acquisition cost structures and subscription attach rates for recurring revenue models.
- Direct Sales:Oura Health and Ultrahuman Healthcare leverage owned digital storefronts to capture full hardware margins and enforce subscription bundling, with sleep clinics and corporate wellness programs in the United States negotiating per-employee-per-month fees for aggregated analytics.
- Online Retail:Amazon and dedicated electronics marketplaces enable discovery among fitness-curious consumers with lower intent thresholds than clinical buyers.
- Specialty Stores:Electronics retailers and running shops provide tactile evaluation for premium titanium and ceramic housings where fit precision affects sensor accuracy.
- Distributors:Healthcare-focused intermediaries navigate EMA notified-body documentation and FDA 510(k) clearance requirements for institutional procurement.
Margin preservation leader: Direct Sales. Scale expansion priority: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart ring manufacturing originated in Finnish and American sleep technology clusters during the mid-2010s, with subsequent scaling across East Asian semiconductor corridors and European clinical validation networks.
United States
Corporate wellness programs at Fortune 500 technology and financial services firms drive institutional procurement of health monitoring rings with per-employee-per-month subscription pricing. FDA 510(k) clearance pathways for pulse oximetry and ECG functions create regulatory moats for clinical-grade vendors. Sleep medicine research partnerships in the San Francisco Bay Area and Greater Boston compress validation timelines for biometric algorithm credibility.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia now mandate EU AI Act-compliant explainable biometric scoring for continuous patient monitoring contracts. EMA MDR classification through notified bodies like TÜV SÜD demands eighteen-month certification queues for diagnostic-output rings. Berlin-Brandenburg hosts emerging digital health clusters where machine-learning documentation standards for algorithmic transparency are being stress-tested.
China
NMPA maintains separate certification standards for wearable medical devices that delay market entry without local testing partnerships in Shanghai or Shenzhen. Manufacturing gravity concentrates in the Pearl River Delta where Taiwan-based semiconductor foundries supply miniaturized photoplethysmography die components. Domestic brands leverage cost-optimized assembly for economy-tier fitness rings targeting price-sensitive consumers.
Singapore
Transit authority mandates for contactless authentication accelerate NFC-enabled payment ring deployment across Asia-Pacific urban centers. The Land Transport Authority's interoperability standards create procurement specifications that favor battery-independent passive designs. Financial services partnerships with regional banks embed ring-based retail authentication into everyday commerce infrastructure.
India
PLI scheme incentives covering 4-6% of incremental sales value attract assembly relocation from China with BIS certification streamlining domestic market entry. Maharashtra and Karnataka host emerging electronics manufacturing clusters where wearable device assembly is scaling. Local brands compete on hardware margins while subscription-based health analytics remain underpenetrated relative to Western markets.
Global Smart Ring Market Competitive Environment
Premium-margin players sit above commodity-margin players across algorithmic differentiation and clinical certification dimensions. The vendor base stratifies into three tiers: vertically integrated platform owners with captive sensor supply, algorithm specialists licensing biometric scoring engines, and hardware assemblers competing on component cost. Consolidation pressure favors players with FDA or EMA clearance documentation. Dominant competitive moves include clinical validation partnerships with academic medical centers and backward integration into photoplethysmography semiconductor sourcing.
Among Finnish-origin platform developers, Oura Health exemplifies vertical integration into sleep-scoring algorithms and direct-to-consumer subscription models. Samsung Electronics anchors the ecosystem-tier position through Galaxy Health dashboard integration that locks ring data into broader device portfolios. Ultrahuman Healthcare Pvt Ltd occupies the metabolic health specialization vector with glucose-monitoring convergence that extends addressable base beyond fitness into chronic disease management. These three represent distinct strategic archetypes: algorithm-native vertical integration, ecosystem platform leverage, and biomarker specialization.
| Leading Market Players |
|---|
| Oura Health |
| Ultrahuman Healthcare Pvt Ltd |
| Samsung Electronics Co., Ltd. |
| RingConn LLC |
| Movano Health, Inc. |
| Zepp Health Corporation |
| Circular SAS |
| Noise |
| boAt Lifestyle |
| Others |
Value Chain & Pricing Dynamics
Titanium and lithium-polymer cell costs cascade from Taiwanese semiconductor foundries through three distinct pricing tiers, with FDA-cleared clinical-grade rings commanding hardware-plus-subscription premiums while economy-tier assemblers in India absorb margin compression from raw material volatility.
Pricing Analysis
Hardware-plus-recurring-subscription models dominate the United States direct-to-consumer channel, separating clinical-grade vendors with FDA 510(k) documentation from fitness accessory competitors. Price differentiation hinges on algorithmic certification tier and biometric sensor density, with six-LED photoplethysmography arrays sustaining premium positioning. Cost compression in economy-tier rings priced below manufacturing recovery thresholds is intensifying because cobalt and lithium carbonate spot market volatility erodes already-thin hardware margins. Corporate wellness programs at Fortune 500 firms exhibit lowest price sensitivity through per-employee-per-month outcome-contingent contracts, while Asia-Pacific mass-market consumers drive volume at minimal unit economics.
Supply Chain Analysis
Freight cost fluctuations between Taiwan, China, and India are reshaping assembly location decisions as manufacturers seek BIS certification efficiency under India's PLI scheme. Photoplethysmography die production concentrates in Taiwan, titanium housing fabrication centers on China, and final assembly is gravitating toward Maharashtra and Karnataka electronics clusters. Supply chain risk rests on single-source vulnerability for sub-2mm² semiconductor components from foundries with limited alternative qualified suppliers. Distribution runs through direct-to-consumer digital storefronts for premium vendors, healthcare-focused intermediaries for institutional procurement, and Amazon marketplace channels for fitness-curious discovery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Smart Ring Market has entered a late-cycle quality phase where procurement committees at German hospital systems and United States corporate wellness programs now mandate EMA MDR classification and FDA clearance documentation as table stakes, compressing margins for undifferentiated hardware assemblers.
For Market Incumbents: Cement algorithmic differentiation through backward integration into photoplethysmography semiconductor sourcing and captive sleep-scoring engine development. Prioritize EMA notified-body capacity reservations at TÜV SÜD and BSI to preempt eighteen-month certification queues freezing European clinical claims. Defend against wrist-worn smartwatch substitution by embedding ring data into broader health platform dashboards that raise switching costs.
For New Entrants and Emerging Players: Capture white-space in glucose-monitoring ring convergence for Type 2 diabetes management, where metabolic health platforms remain underdeveloped relative to fitness tracking saturation. India's PLI scheme incentives offer the most penetrable manufacturing entry point with 4-6% incremental sales value coverage and streamlined BIS domestic market access. Lead with NFC payment ring deployment in Singapore, Japan, and South Korea transit authority procurement specifications.
For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated algorithm specialists because FDA and EMA clearance documentation scarcity creates durable competitive moats that commodity hardware assemblers cannot replicate. Long-term viability favors platform owners with recurring subscription revenue locked into multi-year corporate wellness contracts. Watch EU AI Act algorithmic transparency enforcement breadth as the signal indicating whether European procurement preference for explainable machine-learning documentation accelerates consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Fourteen-month review cycles for pulse oximetry algorithms create regulatory moats against fitness-accessory competitors. |
| EMA MDR Classification | Eighteen-month notified-body queues at TÜV SÜD and BSI freeze product launches without early documentation investment. |
| Photoplethysmography Semiconductor Sourcing | Taiwan-based foundry partnerships for sub-2mm² die components compress development cycles and enable three-sensor arrays. |
| Corporate Wellness Contract Negotiation | Per-employee-per-month outcome-contingent pricing at Fortune 500 firms displaces upfront hardware subsidies. |
| Glucose-Monitoring Clinical Validation | Non-invasive optical sensing partnerships with Stanford Sleep Medicine and Cleveland Clinic extend addressable base into diabetes management. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sleep medicine clinicians, hospital purchasing committees, biomedical engineers at device manufacturers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up sensor shipment modeling and top-down healthcare IT expenditure analysis were cross-referenced for triangulation.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning health monitoring versus payment-enabled product types, biometric sensor versus NFC connectivity technologies, and healthcare provider versus consumer end-user archetypes. CAGRs were derived from fitted growth curves applied to disclosed foundry capacity expansions and regulatory approval timelines, incorporating EU AI Act compliance cost assumptions and PLI scheme incentive trajectories as industry-specific forecast inputs.
Regulatory divergence between FDA software-as-medical-device frameworks and EMA hardware-plus-algorithm bundling, notified-body capacity constraints extending certification queues, and photoplethysmography signal processing engineer talent scarcity are the dominant revision risks that could compress or extend projected adoption curves. Stakeholders should weight assumptions against their own operating context and certification investment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
US Pet Wearable Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Smart Bra Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Smart Band Market
Wearable Technology
Battery for Children Smart Watch Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Women's Watch Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Children Digital Watch Market