
 Europe Wearable Technology Market | 2026-2036
Europe Wearable Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wearable Technology Market Foresight
Finland is fragmenting as Oura Health Oy anchors its ring-form-factor manufacturing and Garmin Ltd. competes through multisport GPS specialization. Samsung Electronics Co., Ltd. leverages semiconductor integration across its Galaxy Watch portfolio, while Apple Inc. sustains premium positioning through proprietary health sensor arrays and closed-loop ecosystem control.
Wearable technology encompasses body-borne electronic devices integrating microelectromechanical sensors, low-power Bluetooth chipsets, and biocompatible housing materials to capture physiological or environmental data for real-time feedback. These systems serve clinical diagnostics, athletic optimization, and occupational safety through continuous biometric streaming. Smartwatches dominate value capture due to higher average selling prices and recurring software subscription revenue, while medical devices represent the fastest-expanding margin pool as CE marking under MDR unlocks prescription reimbursement channels. Fitness trackers occupy a mature volume tier where Xiaomi Corporation and others compete on component cost minimization.
EMA guidelines on software-as-medical-device classification interact with GDPR data portability mandates and REACH substance restrictions to shape product architecture decisions across European development teams. The EU AI Act's risk-tiering framework for health-critical algorithms is forcing pre-market conformity assessments that extend time-to-revenue for new entrants. Stakeholders must monitor whether notified bodies expand capacity fast enough to prevent MDR certification backlogs from constraining launch timelines.
Market Dynamics
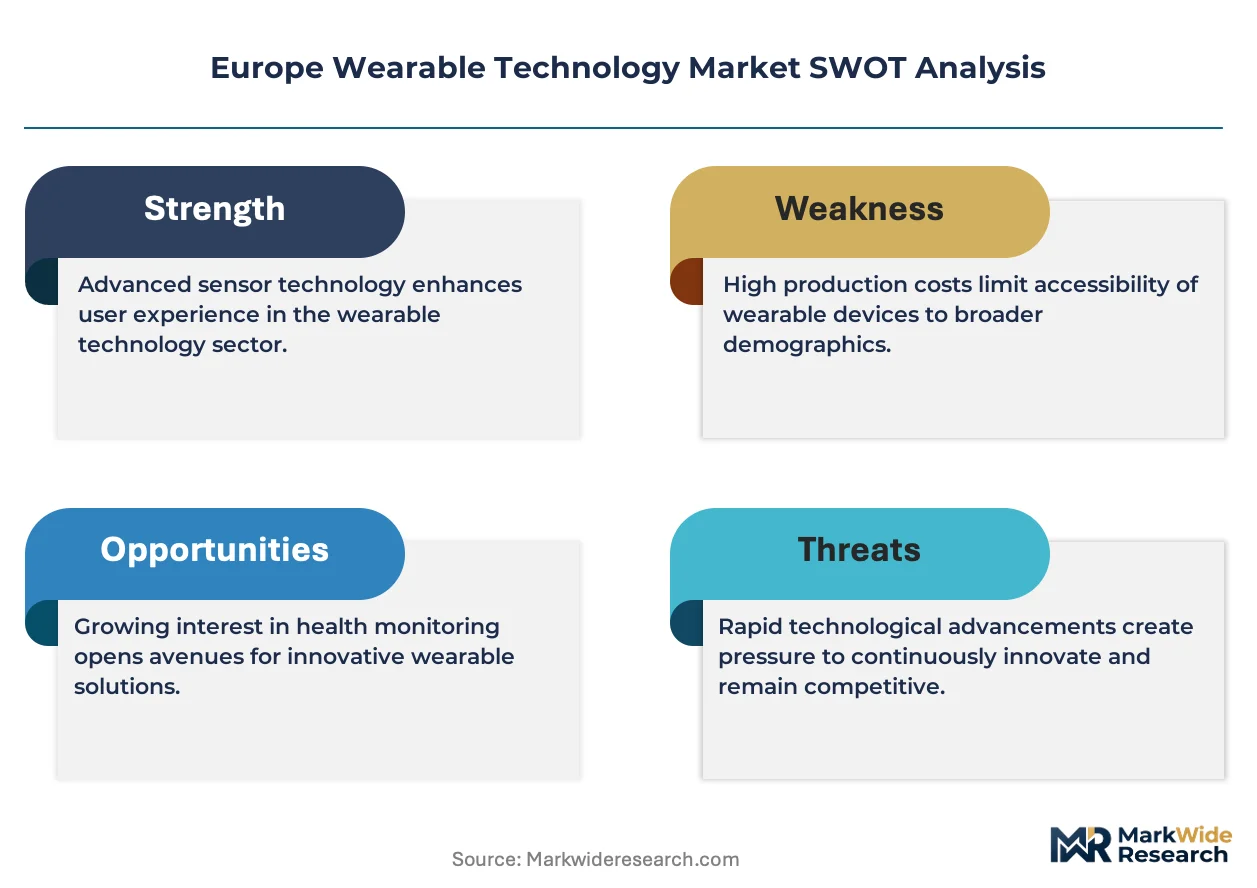
The EU Medical Device Regulation (MDR) is compressing time-to-revenue timelines for Class IIa and above devices, forcing manufacturers to pre-fund extended clinical evidence generation before CE marking unlocks prescription reimbursement channels.
Growth Catalysts
- Continuous glucose monitoring:German healthcare providers are accelerating deployment of prescription-grade diabetes wearables as statutory health insurance reimbursement pathways mature.
- GDPR data portability:Mandates for patient-controlled health data are stimulating demand for interoperable wearable platforms that stream biometrics directly to electronic health records.
- Cardiac arrhythmia detection:Dutch hospital systems are integrating consumer smartwatch ECG outputs into telecardiology workflows, expanding the addressable patient population.
Market Restraints
- Notified body capacity:EU MDR certification backlogs are extending conformity assessment timelines for novel sensor technologies awaiting CE marking.
- Biocompatible polymer supply:REACH substance restrictions on certain phthalates are constraining housing material sourcing for skin-contact wearables.
- Optical sensor accuracy:Melanin interference with photoplethysmography readings limits addressable demographics across Southern European populations.
Strategic Opportunities
- Occupational safety mandates:French industrial regulators are drafting requirements for fatigue-monitoring wearables in transportation and logistics sectors.
- Nordic remote patient monitoring:Finland's decentralized healthcare infrastructure creates white space for ring-form-factor devices in sleep disorder management.
- AI Act health-critical tiering:Pre-market conformity assessments for diagnostic algorithms are creating first-mover advantages for compliant software architectures.
Industry Challenges
- Embedded firmware engineering:Scarce talent pools for ultra-low-power Bluetooth chipset optimization are inflating R&D compensation costs.
- Legacy hospital IT integration:HL7 FHIR connectivity requirements demand specialized middleware development for wearable data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wearable Technology Market |
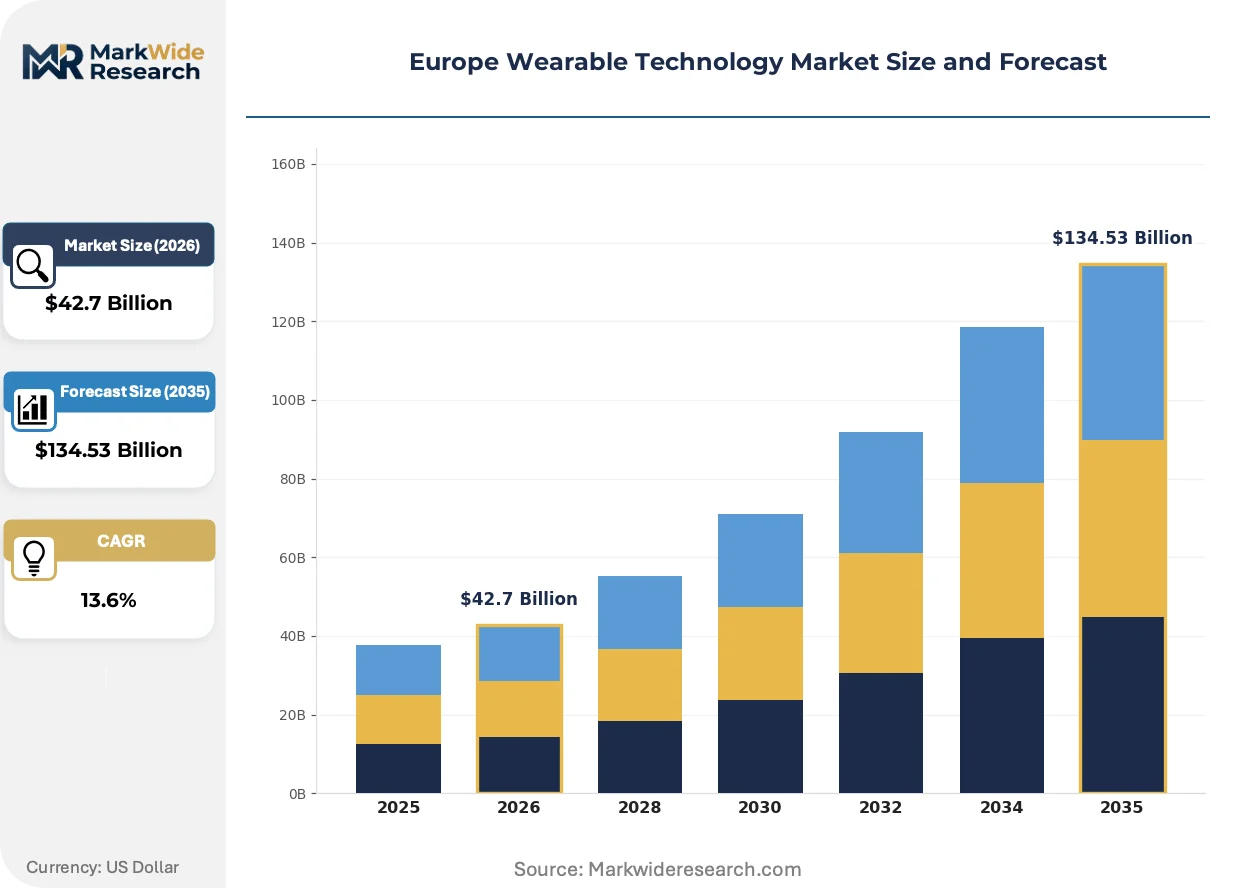
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $134.53 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Medical Devices Technology: Bluetooth, Wi-Fi, NFC, GPS End User: Healthcare Providers, Fitness Enthusiasts, Retail Consumers, Corporate Users Application: Health Monitoring, Sports Performance, Fitness Tracking, Industrial Use |
| Companies Covered | Garmin Ltd., Sony Semiconductor Solutions Corporation, Apple Inc., Xiaomi Corporation, LG Electronics, Samsung Electronics Co., Ltd., Huawei Technologies Co., Ltd., Oura Health Oy, Alphabet Inc. (Google), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wearable Technology Market Shifts & Advancements
Sensor fusion architectures and edge AI inference are compressing latency between biometric capture and clinical decision support, reshaping product development priorities across European engineering centers.
Photoplethysmography arrays with multi-wavelength LED configurations are virtualizing traditional pulse oximetry hardware into software-defined hemoglobin saturation estimation. Dutch cardiology departments are piloting these systems for overnight oxygen monitoring. The technology is virtualizing standalone medical device categories into generalized wearable platforms.
EMA guidelines on software-as-medical-device classification are tightening quality management system requirements for algorithm-driven diagnostics. Manufacturers must now maintain post-market surveillance infrastructures comparable to pharmaceutical vigilance systems. Cardiac monitoring applications face the steepest compliance cost escalation.
Hospital procurement departments are consolidating wearable vendor relationships around platforms offering native electronic health record integration. Germany's university hospital networks are displacing standalone fitness trackers with enterprise-contracted prescription-grade ecosystems. France's regional health agencies are following this consolidation pattern most aggressively.
Europe Wearable Technology Market Segmentation
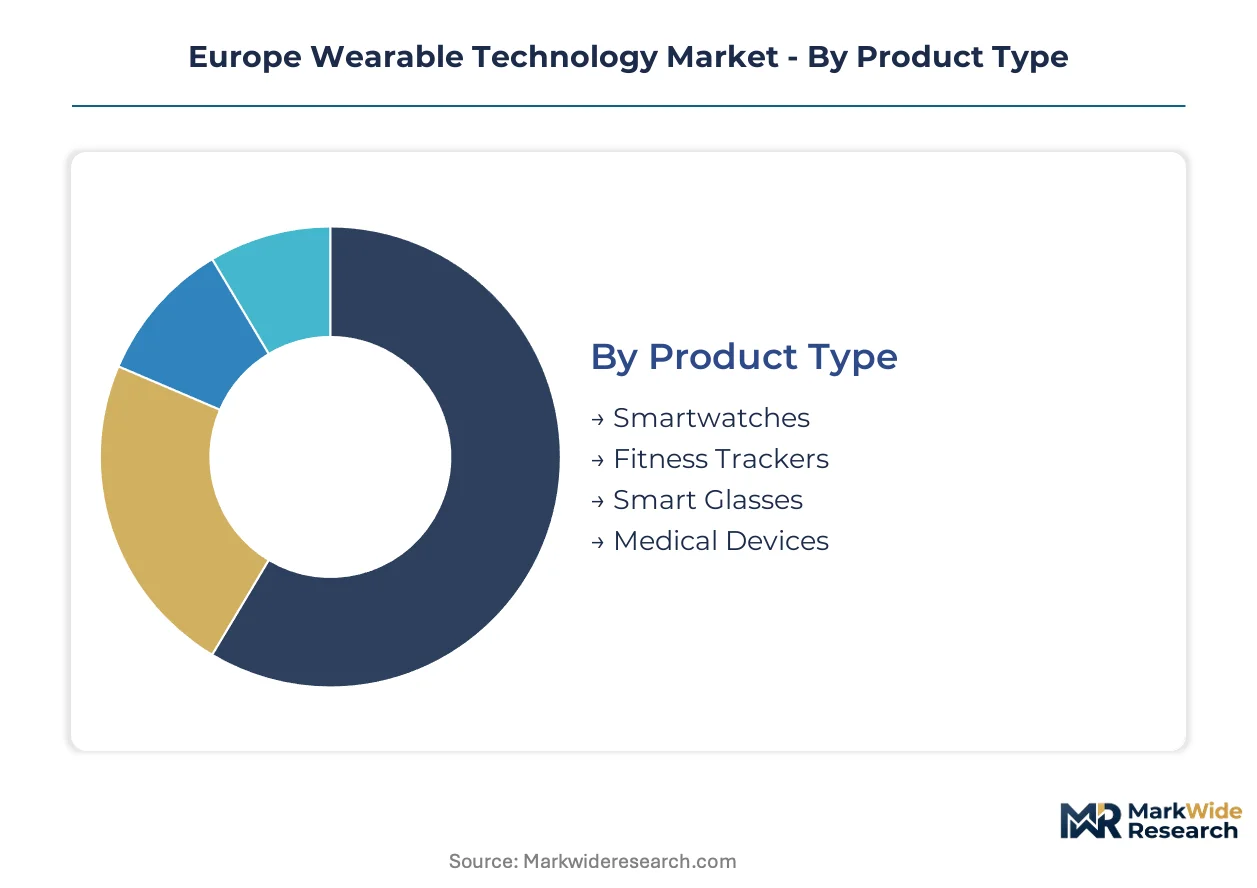
Product architecture decisions in European wearable technology hinge on reimbursement eligibility under MDR classification tiers and the interoperability mandates embedded in GDPR data portability rules. Segmentation reveals where prescription-grade devices command premium positioning against consumer wellness products facing commoditization pressure.
Product Type:
Mature smartwatch platforms coexist with emerging medical device categories as CE marking pathways diverge sharply on clinical evidence requirements.
- Smartwatches:Multisensor platforms integrating photoplethysmography, accelerometry, and ECG electrodes into wrist-worn form factors. German statutory health insurance funds are piloting selective reimbursement for arrhythmia detection capabilities, expanding addressable patient populations beyond fitness-oriented consumers.
- Medical Devices:Continuous glucose monitors and cardiac event recorders requiring Class IIa or above CE marking under MDR. Dutch hospital procurement departments are consolidating vendor relationships around platforms with native HL7 FHIR connectivity, displacing standalone consumer alternatives in clinical workflows.
- Fitness Trackers:Cost-optimized step counters and sleep monitors competing on component minimization.
- Smart Glasses:Optical see-through displays for industrial maintenance and surgical assistance applications.
Smartwatches handle the majority of throughput; medical devices are climbing the fastest on revenue share as prescription channels mature.
Technology:
Connectivity specifications map directly to power budgets and use case latency requirements across the European installed base.
- Bluetooth:Ultra-low-power chipsets enabling week-long battery life in compact ring and wrist form factors. Finland's Oura Health Oy anchors manufacturing around Nordic Semiconductor components optimized for overnight sleep staging data transmission.
- GPS:Multiband GNSS receivers supporting meter-level positioning accuracy for outdoor athletic applications. French multisport specialists leverage dual-frequency configurations for trail running and cycling segments where route fidelity determines product selection.
- Wi-Fi:High-throughput streaming for clinical-grade video and bulk data offload.
- NFC:Contactless payment and access control integration in enterprise deployment scenarios.
Bluetooth dominates unit shipments; GPS commands the steepest expansion trajectory in average selling price contribution.
End User:
Customer archetypes split on procurement authority, with institutional buyers prioritizing EMA software-as-medical-device compliance and individual consumers emphasizing ecosystem continuity.
- Healthcare Providers:Hospital systems and primary care networks prescribing continuous monitoring for chronic disease management. Germany's university hospital networks are displacing consumer-grade devices with enterprise-contracted prescription-grade ecosystems featuring integrated electronic health record streaming.
- Corporate Users:Industrial safety managers deploying fatigue-monitoring and lone-worker protection systems. French transportation regulators are drafting mandatory requirements for logistics operator biometric oversight, creating procurement pull for occupational wearable platforms.
- Fitness Enthusiasts:Amateur athletes prioritizing training load metrics and recovery recommendations.
- Retail Consumers:General wellness purchasers selecting on brand ecosystem lock-in and aesthetic preferences.
Healthcare providers concentrate the highest-margin demand; corporate users are gaining share fastest as occupational mandates proliferate.
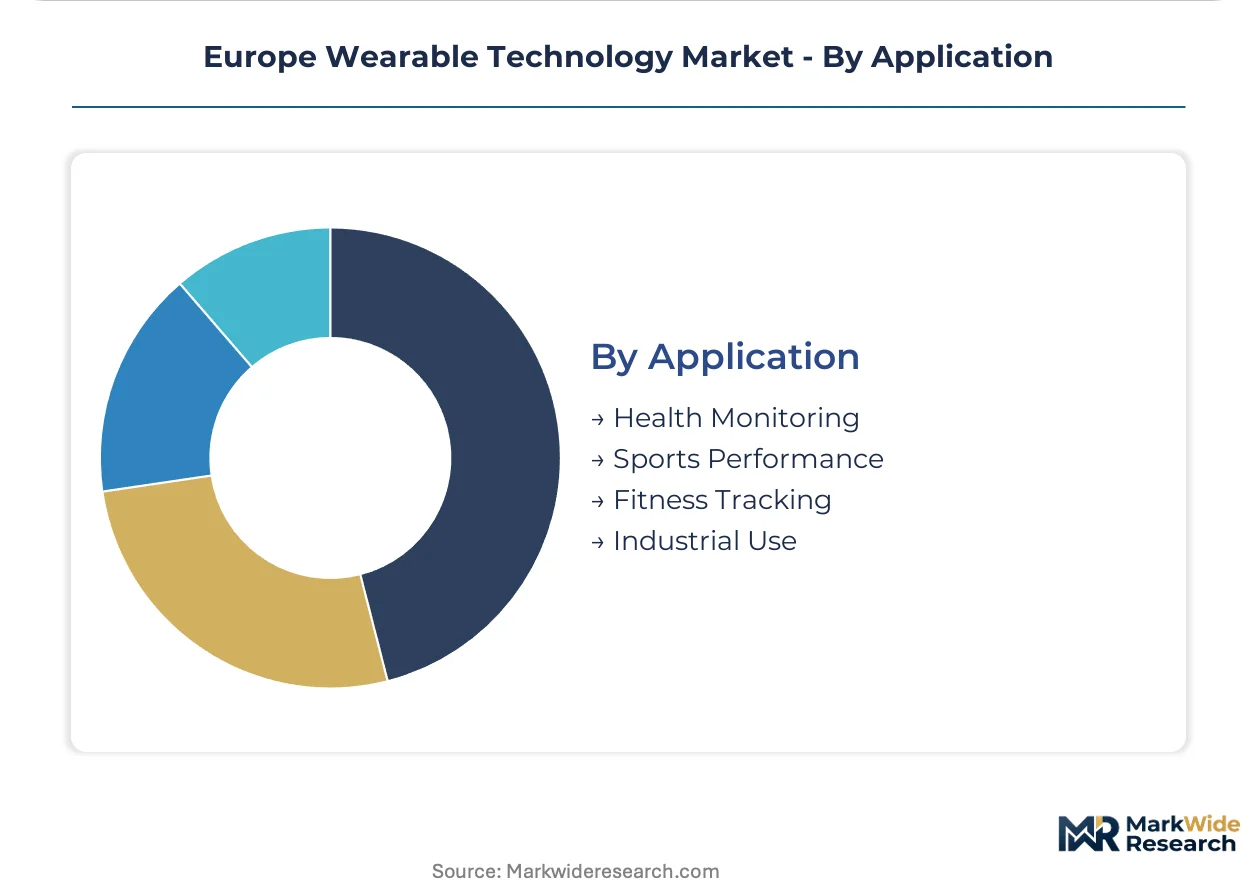
Application:
Use case segmentation tracks the migration from recreational wellness toward clinical diagnostic utility under tightening regulatory frameworks.
- Health Monitoring:Continuous vital sign capture for chronic disease surveillance and acute event detection. Dutch telecardiology workflows now integrate consumer smartwatch ECG outputs, blurring historical boundaries between consumer and clinical device categories.
- Industrial Use:Occupational safety applications including heat stress monitoring, fall detection, and hazardous atmosphere alerts. French industrial regulators are advancing fatigue-monitoring mandates for transportation and logistics sectors.
- Sports Performance:Training optimization through biomechanical load quantification and recovery metric tracking.
- Fitness Tracking:Basic activity quantification facing margin compression from component cost minimization.
Health monitoring commands the dominant revenue position; industrial use is expanding most quickly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MDR certification timelines anchor competitive positioning across the continent. Germany's statutory health insurance funds and Dutch hospital procurement departments concentrate institutional demand. REACH substance restrictions and GDPR data portability mandates reshape product architecture decisions from Finland to France.
Germany
Statutory health insurance funds pilot selective reimbursement for arrhythmia detection capabilities in smartwatch platforms. The EU Medical Device Regulation compresses time-to-revenue for Class IIa devices awaiting CE marking. Bavaria's university hospital networks displace consumer-grade devices with enterprise-contracted prescription-grade ecosystems.
Netherlands
Hospital procurement departments consolidate vendor relationships around HL7 FHIR connectivity for seamless electronic health record integration. EMA software-as-medical-device guidelines tighten quality management requirements for algorithm-driven diagnostics. Dutch telecardiology workflows in Amsterdam and Rotterdam integrate consumer smartwatch ECG outputs, expanding addressable patient populations.
France
Industrial regulators draft mandatory fatigue-monitoring requirements for transportation and logistics operators. ANSM and CNIL oversight intersects with EU AI Act risk-tiering for health-critical algorithms. Auvergne-Rhône-Alpes hosts multisport specialists leveraging dual-frequency GPS configurations for trail running segments.
Finland
Decentralized healthcare infrastructure creates white space for ring-form-factor devices in sleep disorder management. GDPR mandates for patient-controlled health data stimulate demand for interoperable platforms streaming biometrics to electronic health records. Oura Health Oy anchors manufacturing in the Helsinki region around Nordic Semiconductor components optimized for overnight data transmission.
United Kingdom
Post-Brexit regulatory divergence creates parallel conformity assessment pathways alongside retained EU MDR provisions. London's hospital networks evaluate prescription-grade wearable procurement through NHS England technology appraisal frameworks. The Southeast concentrates health-tech venture activity targeting remote patient monitoring integration.
Europe Wearable Technology Market Competitive Landscape
Capability concentration sits with semiconductor-integrated specialists; scale advantage sits with multisensor platform operators. The vendor base splits between premium-tier ecosystem controllers and component-cost-minimized volume players. Two archetypes dominate: closed-loop health platform architects and open-standard interoperability specialists. Competitive moves center on MDR certification pre-funding and strategic partnerships for HL7 FHIR middleware development.
Among Nordic-origin specialists, Oura Health Oy exemplifies ring-form-factor medical device positioning. Samsung Electronics Co., Ltd. and Apple Inc. occupy the premium-tier ecosystem control vector, representing contrasting approaches to proprietary sensor array integration versus semiconductor verticalization. Garmin Ltd. anchors the multisport GPS specialization segment. These three company patterns illustrate how geographic origin and corporate structure map to divergent regulatory compliance strategies across the European notified body landscape.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Sony Semiconductor Solutions Corporation |
| Apple Inc. |
| Xiaomi Corporation |
| LG Electronics |
| Samsung Electronics Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| Oura Health Oy |
| Alphabet Inc. (Google) |
| Others |
Supply & Pricing Matrix
Nordic Semiconductor's concentration in Bluetooth chipset fabrication anchors margin capture for ring-form-factor manufacturers while compressing pricing power for downstream assemblers competing on sensor integration rather than silicon design. CE marking tiers under MDR create discrete price bands that stratify prescription-grade devices from consumer wellness products.
Pricing Analysis
German statutory health insurance funds reimburse prescription-grade cardiac wearables at premiums exceeding consumer smartwatch retail by substantial multiples, while Dutch hospital procurement drives volume discounts through enterprise contracting. Pricing stratifies across premium, standard, and economy tiers based on MDR classification grade and HL7 FHIR interoperability certification. Cost compression in fitness trackers intensifies as Xiaomi Corporation and component-cost minimizers flood volume tiers with undifferentiated hardware. Healthcare providers exhibit lowest price sensitivity due to reimbursement pass-through mechanics, while retail consumers demonstrate highest elasticity to ecosystem switching costs.
Supply Chain Analysis
Biocompatible polymer feedstocks draw from German specialty chemical manufacturers and Dutch coating specialists constrained by REACH phthalate restrictions. Photoplethysmography LED arrays and MEMS accelerometers source from Taiwanese optoelectronics foundries and South Korean packaging houses. Single-source vulnerability concentrates in Nordic Semiconductor's Bluetooth Low Energy chipset architecture, where alternative qualified suppliers remain limited. Distribution runs through enterprise procurement departments at German university hospital networks and French regional health agencies, with direct-to-consumer channels capturing residual fitness-oriented demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where MDR certification backlogs and clinical evidence requirements create regulatory entrenchment that protects incumbent positions against fast-follower erosion.
For Market Incumbents: Pre-empt notified body capacity constraints by pre-funding extended clinical trials for Class IIa glucose monitoring algorithms before competitors secure CE marking slots. Accelerate backward integration into biocompatible polymer compounding to neutralize REACH supply restrictions threatening housing material sourcing. Samsung Electronics Co., Ltd. and Apple Inc. already anchor semiconductor verticalization that emerging players cannot replicate without capital intensity exceeding viable returns.
For New Entrants and Emerging Players: Pursue occupational safety mandates in French transportation and logistics sectors where regulatory drafting creates procurement pull without incumbent lock-in. Target Finland's decentralized sleep disorder management infrastructure for ring-form-factor deployment before Oura Health Oy consolidates institutional relationships. Lead with HL7 FHIR-native architectures that bypass legacy hospital IT integration barriers incumbents face with closed-loop ecosystems.
For Investors and Strategic Acquirers: Capital is best deployed toward software-as-medical-device specialists with EMA-compliant quality management systems and post-market surveillance infrastructure comparable to pharmaceutical vigilance. Long-term viability hinges on whether AI Act pre-market conformity assessments for diagnostic algorithms create sustainable first-mover advantages or merely delay revenue recognition without differentiation. Watch notified body capacity expansion rates as the inflection signal determining whether MDR certification backlogs constrain launch timelines or normalize competitive entry.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class IIa certification unlocks German statutory health insurance reimbursement channels. |
| Hospital System Partnership | Dutch procurement consolidation favors vendors with native HL7 FHIR EHR connectivity. |
| Software Companion Development | EMA software-as-medical-device guidelines demand post-market surveillance infrastructure investment. |
| Reimbursement Strategy | Prescription-grade positioning in Germany requires evidence generation before notified body submission. |
| Strategic Partnership | French occupational safety mandates create procurement pull for fatigue-monitoring platform alliances. |
Research Methodology
A spread of perspectives from biomedical engineers at Dutch telecardiology departments, procurement managers at German university hospital networks, regulatory affairs specialists navigating EMA software-as-medical-device guidelines, and semiconductor sourcing executives at Nordic component distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EMA submission databases, EU MDR notified body capacity reports, and statutory health insurance reimbursement pathway documentation. Bottom-up demand modeling from device shipment data triangulated against top-down healthcare expenditure flows across the analysis window.
Demand-supply balance framing anchored the forecast architecture across product type, technology connectivity specification, end-user procurement authority, and application clinical utility dimensions. CAGRs derived from segment-level growth rate reconciliation with macro healthcare digitization trends and regulatory implementation timelines. Optical sensor accuracy limitations across melanin-variant populations and AI Act risk-tiering enforcement patterns served as industry-specific forecast sensitivity inputs throughout the projection horizon.
Sensitivities concentrate around notified body capacity expansion rates, REACH substance restriction scope creep, and GDPR data portability mandate enforcement intensity. Cross-checking against NHS England technology appraisal frameworks and Health Canada parallel regulatory pathways is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Smart Band Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Women's Watch Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Europe Watch Market