
 Children Digital Watch Market | 2026-2036
Children Digital Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Children Digital Watch Market Analysis
Multi-source component procurement is consolidating as brands reduce dependency on single semiconductor foundries. VTech Holdings Ltd anchors its supply base across Taiwanese and mainland Chinese chip vendors. Garmin Ltd differentiates through in-house GPS module design and proprietary antenna engineering. Xiaomi Corporation competes on manufacturing scale, leveraging its consumer electronics ecosystem to absorb component cost volatility.
A children digital watch is a wrist-worn electronic device combining time display with programmable functions such as location tracking, two-way voice communication, and activity monitoring, typically operating through Bluetooth or cellular radio modules with rechargeable lithium-polymer cells. Its primary purpose is to provide guardians with real-time child safety oversight while offering age-appropriate digital engagement. Smartwatches command the dominant value share as parents prioritize two-way calling and geofencing capabilities over simpler fitness trackers. GPS tracking features attract premium positioning, while silicone materials dominate volume production due to hypoallergenic properties and moldability for colorful, durable housings.
The US Consumer Product Safety Commission enforces battery ingestion and strangulation hazard standards, while the FCC regulates radio frequency emissions from cellular-enabled models. Europe's ECHA REACH framework restricts phthalates in silicone and plastic watchbands, and the EU AI Act imposes transparency requirements on algorithmic location prediction features. Stakeholders must monitor evolving cybersecurity certification mandates as connected child wearables face heightened data sovereignty scrutiny across multiple jurisdictions.
Market Dynamics
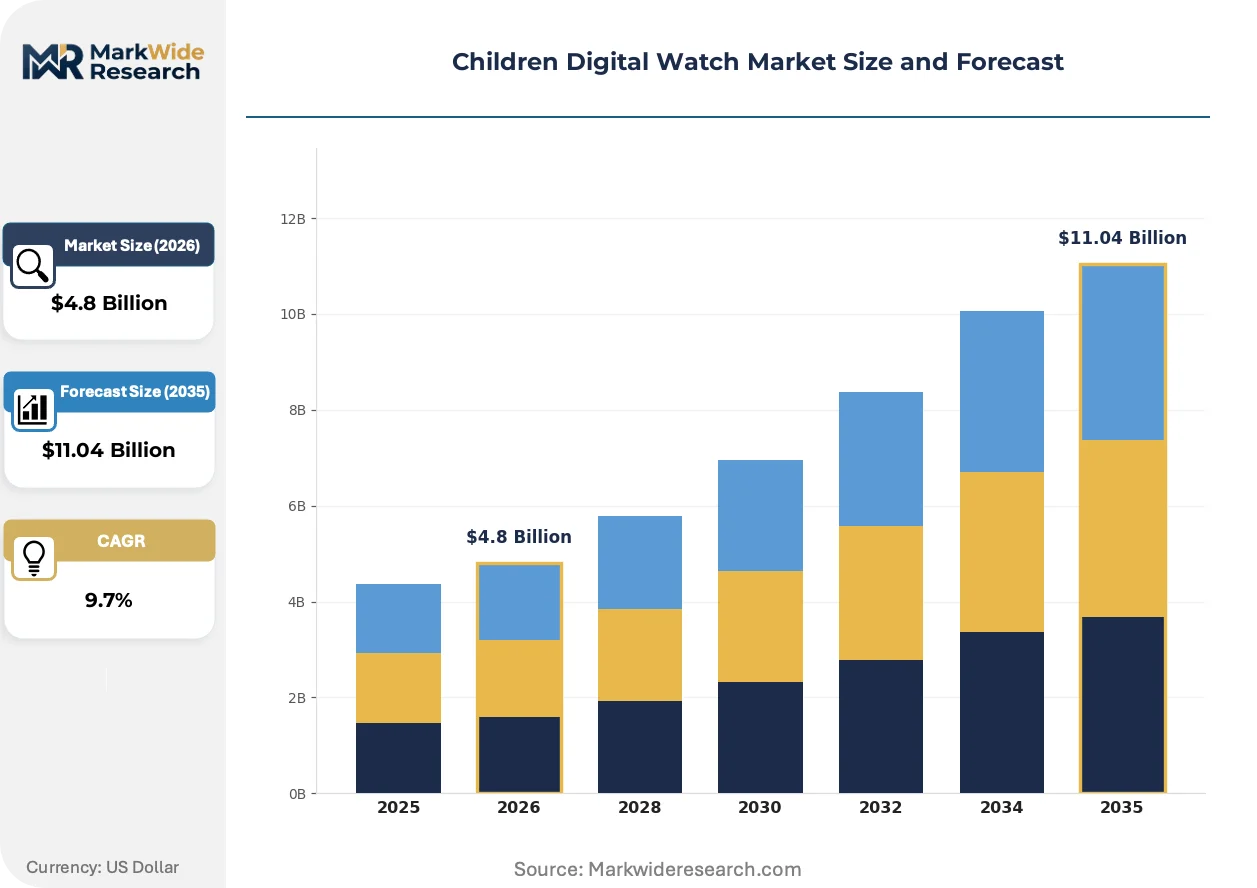
Parental demand for real-time child location monitoring is compressing product development cycles, forcing manufacturers to integrate cellular and GPS modules into sub-$100 price points while navigating tightening electromagnetic exposure standards across multiple jurisdictions.
Growth Catalysts
- GPS-enabled safety mandates:School districts and childcare facilities in China are adopting location-tracking policies that normalize wearable oversight. This institutional acceptance accelerates household penetration.
- REACH phthalate restrictions:Europe's ECHA framework is banning hazardous plasticizers in watchbands, creating certified silicone supply advantages for compliant manufacturers.
- Dual-earner household time scarcity:Working parents in urban India and Brazil are prioritizing devices that reduce coordination friction between school pickup and extracurricular schedules.
Market Restraints
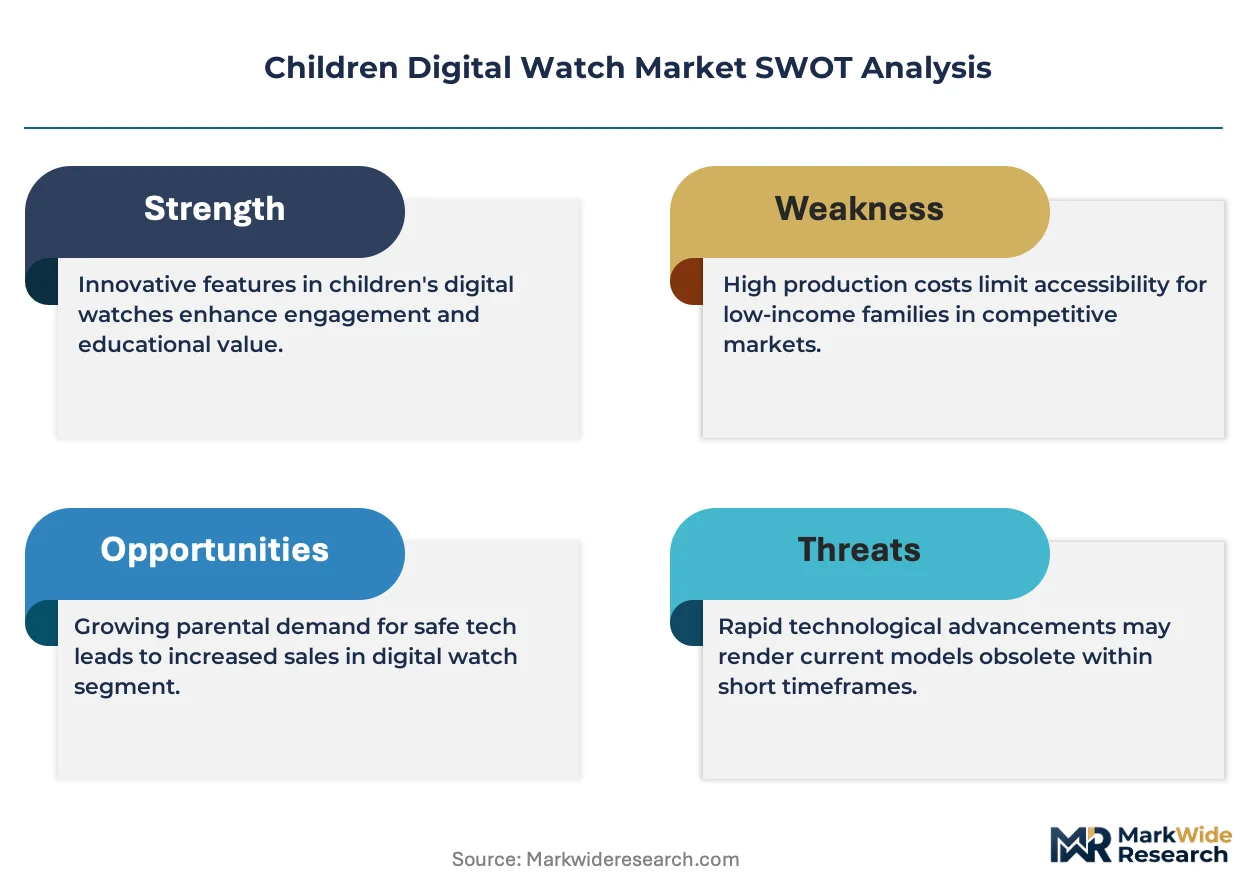
- Lithium-polymer cell volatility:Battery raw material costs fluctuate with cobalt and lithium carbonate spot markets, squeezing margin structures at the economy tier.
- Taiwanese semiconductor concentration:Cellular modem and GPS chipset supply clusters in Hsinchu Science Park create single-point vulnerability for brands without multi-source qualification.
- EU AI Act algorithmic transparency:Predictive geofencing and anomaly detection features face documentation burdens that extend certification timelines by 8-14 months.
Strategic Opportunities
- Rural India connectivity gaps:Low-bandwidth messaging protocols and offline map caching address regions with intermittent 4G coverage, opening distribution through regional telecom partnerships.
- Health-monitoring convergence:Integration of photoplethysmography sensors for sleep and activity tracking is expanding addressable demand beyond pure safety applications.
- China dual carbon manufacturing incentives:SAMR subsidies for renewable-powered production facilities reduce operational costs for domestic assembly operations.
Industry Challenges
- RF engineering talent scarcity:Compact antenna design for children's form factors requires specialized electromagnetic simulation expertise concentrated in Shenzhen and Taipei hiring pools.
- Multi-jurisdiction certification parallelism:Simultaneous FCC, CE, and SRRC (China) testing protocols demand dedicated compliance teams and extended pre-launch capital commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Digital Watch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Traditional Digital Watches, Hybrid Watches Feature: GPS Tracking, Waterproofing, Camera, Voice Calling Age Group: Toddlers, Preschoolers, Early School Age, Tweens Material: Silicone, Plastic, Stainless Steel, Rubber |
| Companies Covered | Apple Inc., VTech Holdings Ltd, Garmin Ltd, Fitbit, Casio Computer Co. Ltd, Seiko Holdings Corp., Ltd., Xiaomi Corporation, Xplora Technologies, Huawei Technologies Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Digital Watch Market Emerging Trajectories
Component miniaturization and cloud-native location platforms are compressing the functional gap between children's wearables and adult smartwatches, while regulatory fragmentation is forcing modular hardware architectures.
Low-power wide-area network (LPWAN) chipsets are expanding into children's digital watches as manufacturers replace traditional cellular modems with NB-IoT and LTE-M alternatives. Preschool-focused brands in Germany and South Korea are adopting these modules to extend battery life beyond 72 hours. This migration is expanding into cost-sensitive segments previously served by Bluetooth-tethered devices, compressing the premium-economy feature divide.
Europe's EU AI Act transparency requirements are reshaping algorithmic location prediction features, forcing vendors to document decision logic for geofence breach alerts and routine pattern analysis. Industrial consequence includes mandatory human-in-the-loop review for automated emergency escalations. GPS-enabled models with machine learning capabilities face the stiffest compliance burdens, with several manufacturers stripping predictive functions to accelerate CE marking.
Direct-to-parent subscription models are displacing traditional retail channel dependency in North America and Western Europe. Monthly service fees covering cellular data and cloud storage generate recurring revenue that offsets hardware margin compression. This shift is most visible among urban professional households in the US and UK, where bundled insurance and emergency response services justify premium pricing.
Children Digital Watch Market Segmentation
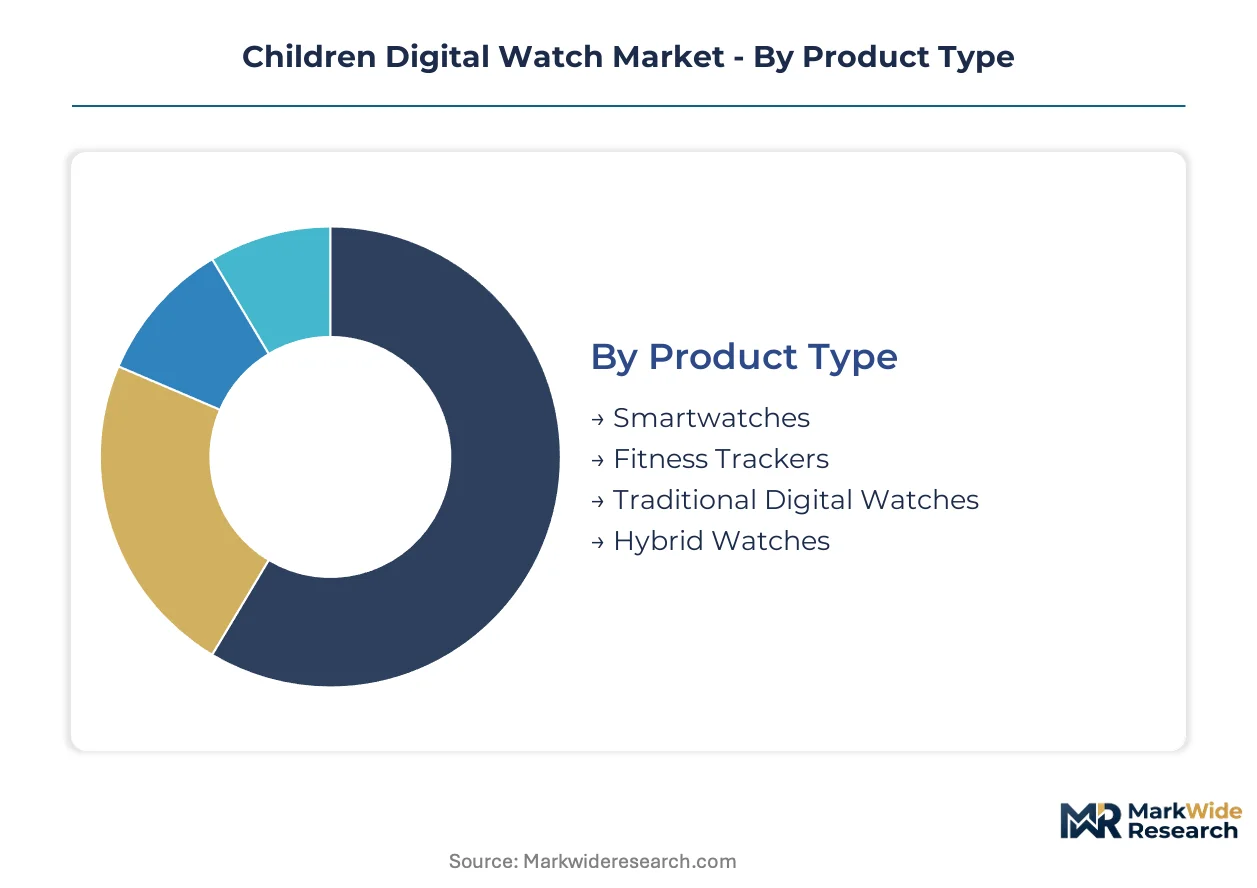
Children's digital watch buyers segment sharply by safety priority versus digital engagement preference. Product architecture, material certification, and age-appropriate feature depth determine margin capture across household income tiers.
Product Type:
Buyer willingness to pay for cellular connectivity and cloud platforms separates the four product architectures.
- Smartwatches:Full-stack devices integrate GPS modems, two-way voice, and parental control apps through proprietary cloud platforms. Demand concentrates in urban Chinese households where Xiaomi and Huawei ecosystem lock-in drives replacement cycles. SAMR cybersecurity certifications for child data handling extend development timelines by four to six months for non-domestic entrants.
- Fitness Trackers:Bluetooth-tethered units omit cellular modules, relying on smartphone proximity for data sync. Preschool facilities in Germany favor these for activity-monitoring programs without location-tracking privacy concerns. ECHA REACH silicone band compliance adds EUR 0.80-1.20 per unit versus Asian-sourced alternatives.
- Traditional Digital Watches:Basic time-display units with alarm and stopwatch functions serve price-sensitive rural markets in India and Indonesia. TRAI's recent mandate on electronic product labeling has compressed informal import channels.
- Hybrid Watches:Analog faces conceal Bluetooth beacons for limited connectivity without screen exposure. South Korean parents prefer these for tween age groups managing school device restrictions.
Volume sits with Traditional Digital Watches; growth tilts toward Smartwatches.
Feature:
Regulatory exposure and component cost structure differentiate the four capability bundles.
- GPS Tracking:Multi-constellation receivers (GPS, GLONASS, BeiDou) enable 3-5 meter accuracy for geofencing alerts. Shenzhen-based manufacturers dominate module sourcing, though FCC Part 15 and CE RED certification parallelism adds 90 days to launch schedules.
- Waterproofing:IP67 and IP68 ingress protection ratings determine school swim program eligibility. Japanese METI quality benchmarks for child product durability exceed baseline ISO standards, favoring domestic brands in that market.
- Camera:Low-resolution imaging modules (2-5MP) enable photo sharing with parent-approved contacts. India's BIS compulsory registration scheme for electronic components has blocked several Chinese OEMs lacking factory audit documentation.
- Voice Calling:Cellular-enabled two-way audio requires carrier partnerships and eSIM provisioning infrastructure. Brazilian ANATEL homologation for voice-capable wearables demands in-country RF testing that excludes parallel certification tracks.
Certification burden is heaviest for Voice Calling; GPS Tracking commands the steepest expansion trajectory.
Age Group:
Developmental stage dictates acceptable device weight, strap circumference range, and parental control interface complexity.
- Toddlers:Devices under 30 grams with tamper-proof clasps target 18-36 month demographics. Demand clusters in Shanghai and Beijing where dual-income households purchase through Tmall flagship stores.
- Preschoolers:3-5 year old segments drive highest GPS penetration as kindergarten pickup coordination becomes critical. EU AI Act transparency requirements for location prediction algorithms impose documentation burdens that several vendors address by stripping machine learning features.
- Early School Age:6-10 year old users gain device autonomy, expanding addressable demand for camera and messaging features. US CPSC battery compartment standards mandate tool-required access panels for this cohort.
- Tweens:10-12 year old segments resist overt parental monitoring, favoring hybrid designs with concealed tracking. South Korea's MFDS electromagnetic exposure guidelines for adolescent wearables are tightening beyond general population limits.
Preschoolers generate current volume peaks; Tweens represent the fastest-climbing cohort as feature sophistication requirements escalate.
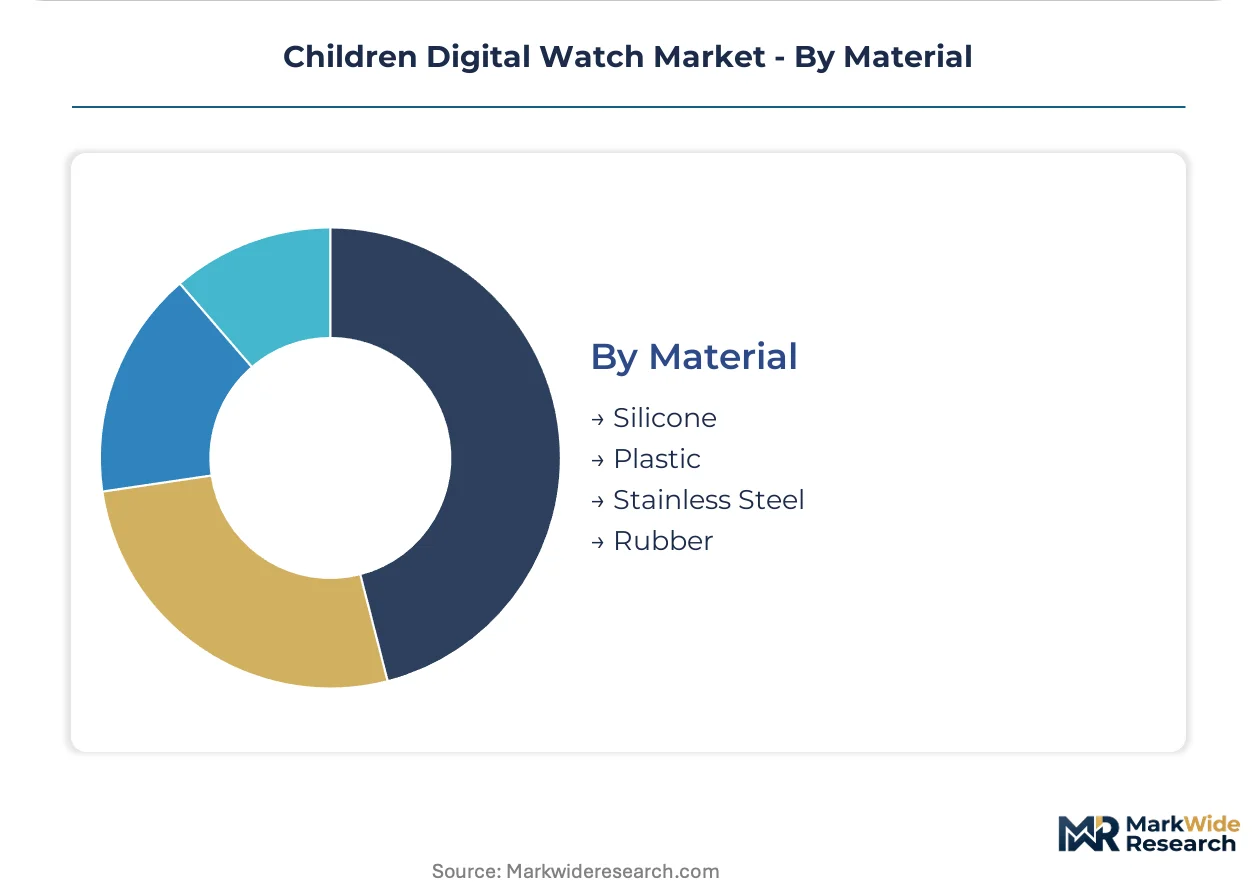
Material:
Skin contact duration and regional chemical regulation stringency shape procurement decisions.
- Silicone:Medical-grade platinum-cured compounds dominate hypoallergenic positioning. ECHA REACH phthalate restrictions have eliminated PVC alternatives in European distribution, consolidating certified silicone supply advantages for compliant manufacturers.
- Plastic:ABS and polycarbonate housings serve sub-$30 economy tiers in Southeast Asian markets. China's GB standards for plasticizer content in child products are converging toward REACH-equivalent limits.
- Stainless Steel:316L surgical grade cases target premium tween segments with adult-watch aesthetics. India's import duties on non-essential electronics constrain pricing flexibility for metal-bodied models.
- Rubber:TPU and natural rubber compounds offer mid-tier durability at silicone-adjacent price points. Brazilian environmental regulator IBAMA documentation requirements for rubber sourcing have complicated supply chain qualification.
Silicone holds manufacturing volume; Stainless Steel is gaining share fastest in premium tier repositioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household demand concentrates in China, where urban dual-income families normalize wearable child safety oversight through domestic e-commerce channels and subsidized manufacturing clusters.
China
Preschool enrollment policies in Shanghai and Beijing accelerate GPS-enabled watch adoption as institutional pickup coordination becomes standard. SAMR cybersecurity certifications for child data handling extend development timelines for hardware vendors. Shenzhen's Huaqiangbei electronics corridor anchors module sourcing, with domestic foundries capturing cellular modem assembly from Taiwanese competitors.
United States
Working parents in metropolitan corridors prioritize two-way voice calling and geofencing capabilities over simpler activity trackers. The FCC enforces Part 15 radio frequency emission limits on cellular-enabled models, while the CPSC mandates tool-required battery compartment access for early school-age demographics. Austin and Boston host RF engineering talent pools specializing in compact antenna design for children's form factors.
Germany
Preschool facilities in Bavaria and North Rhine-Westphalia favor Bluetooth-tethered fitness trackers for activity programs without location-tracking privacy concerns. ECHA REACH phthalate restrictions in watchbands eliminate PVC alternatives, consolidating certified silicone supply advantages for compliant manufacturers. Berlin's consumer electronics testing laboratories handle parallel CE marking and BSI cybersecurity certification.
India
Urban dual-earner households in Mumbai and Delhi-NCR reduce school pickup coordination friction through low-cost GPS wearables. TRAI's electronic product labeling mandate compresses informal import channels, while BIS compulsory registration blocks OEMs lacking factory audit documentation. Tamil Nadu's Sriperumbudur electronics cluster hosts domestic assembly operations for economy-tier brands.
South Korea
Tween demographics in Seoul and Busan resist overt parental monitoring, driving demand for hybrid designs with concealed Bluetooth beacons. MFDS electromagnetic exposure guidelines for adolescent wearables tighten beyond general population limits, forcing RF power reductions. Suwon's Gwanggyo district concentrates wearable R&D facilities serving both domestic and export markets.
Children Digital Watch Market Vendor Landscape
Multi-source component qualification dominates the current landscape as brands reduce dependency on single semiconductor foundries. The vendor base stratifies across three tiers: ecosystem-locked consumer electronics giants, specialized child-safety wearable pure-plays, and contract-manufacturing-dependent regional brands. Strategic archetypes include in-house GPS module designers, silicone supply chain integrators, and cloud-native parental control platform operators. Competitive moves center on RF engineering talent acquisition and parallel multi-jurisdiction certification tracks.
Within the ecosystem-locked tier, Apple Inc. and Xiaomi Corporation exemplify scale-driven positioning through consumer electronics platform leverage. Garmin Ltd occupies a distinct position among specialized wearable architects with proprietary antenna engineering capabilities. VTech Holdings Ltd anchors the child-focused pure-play segment, representing multi-source procurement strategies across Taiwanese and mainland Chinese chip vendors. These three archetypes capture divergent margin structures: premium hardware-software integration, manufacturing scale absorption, and supply base diversification respectively.
| Leading Market Players |
|---|
| Apple Inc. |
| VTech Holdings Ltd |
| Garmin Ltd |
| Fitbit |
| Casio Computer Co. Ltd |
| Seiko Holdings Corp., Ltd. |
| Xiaomi Corporation |
| Xplora Technologies |
| Huawei Technologies Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Cellular-enabled smartwatch premiumization against Bluetooth-tethered economy tiers creates a sharp bifurcation in both margin capture and component sourcing strategies. SAMR cybersecurity certification requirements for child data handling extend development timelines and concentrate premium pricing power among domestic Chinese vendors, while economy-tier brands absorb volatility through Shenzhen spot-market procurement of uncertified silicone and lithium-polymer cells.
Pricing Analysis
Volume concentrates in sub-$30 traditional digital watches sold through informal channels in rural India and Indonesia, while margin capture concentrates in $80-$150 cellular-enabled smartwatches bundled with subscription services. Three-tier pricing structure across premium, standard, and economy levels separates GPS-plus-voice models from Bluetooth-only trackers from basic time-display units. Cost compression in the economy tier is intensifying because cobalt and lithium carbonate spot market volatility squeezes cell suppliers. Preschool facilities in Germany exhibit lowest price sensitivity due to REACH compliance mandates, while Southeast Asian distributors serving price-sensitive rural households face highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Hsinchu Science Park concentration for cellular modem and GPS chipset supply. Module assembly draws from Taiwan, mainland China, and South Korea, with Shenzhen's Huaqiangbei corridor anchoring final device integration. Raw material dependencies center on lithium-polymer cells, platinum-cured silicone compounds, and multi-constellation GPS receivers. Tariff exposure runs through escalating US-China technology trade restrictions on semiconductor components. Distribution runs through Tmall and JD.com flagship stores in China, regional telecom partnerships in India, and direct-to-parent subscription platforms in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The children digital watch market sits in a technology-transition phase as LPWAN chipsets displace traditional cellular modems for battery-life extension. NB-IoT and LTE-M module adoption is reshaping competitive positioning across preschool-focused brands in Germany and South Korea.
For Market Incumbents: Anticipate margin compression from LPWAN-enabled new entrants by accelerating proprietary antenna engineering differentiation and securing multi-source qualification for cellular modem supply beyond Hsinchu Science Park. Ecosystem-locked players should deepen cloud-native parental control platform stickiness to defend against hardware commoditization. Certification investment in parallel FCC, CE, and SRRC tracks preserves launch velocity against regulatory fragmentation. For New Entrants and Emerging Players: EU AI Act transparency requirements in Europe open a window for stripped-down GPS models without machine learning features to accelerate CE marking and undercut compliance-burdened incumbents. Rural India connectivity gaps represent the most penetrable geography, with low-bandwidth messaging protocols and offline map caching enabling distribution through regional telecom partnerships. Go-to-market angle should emphasize battery-life superiority through LPWAN architecture against cellular-dependent legacy models. For Investors and Strategic Acquirers: Re-rating potential sits with specialized child-safety wearable pure-plays given institutional adoption tailwinds from school district location-tracking policies in China. Long-term viability favors vendors with in-house RF engineering capabilities and certified silicone supply chain integration rather than contract-manufacturing-dependent regional brands. Watch for LPWAN module cost curves crossing cellular modem parity as the inflection indicator for technology-transition completion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Parallelism | Simultaneous FCC, CE, and SRRC testing compresses time-to-revenue for cellular-enabled launches. |
| LPWAN Module Migration | NB-IoT and LTE-M adoption extends battery life beyond 72 hours for preschool-focused positioning. |
| Direct-to-Parent Subscription Launch | Recurring revenue from cellular data and cloud storage offsets hardware margin compression in North America. |
| Certified Silicone Supply Integration | ECHA REACH phthalate restrictions eliminate PVC alternatives and consolidate compliant manufacturer advantages. |
| Regional Telecom Partnership Expansion | Distribution through Reliance Jio and Airtel channels addresses rural India connectivity gaps with offline-capable devices. |
Methodological Framework
SEC filings from VTech Holdings Ltd and Garmin Ltd, SAMR cybersecurity certification databases, and ECHA REACH compliance registries formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with RF engineering directors at Shenzhen wearable OEMs, procurement leads at Taiwanese semiconductor foundries, and category buyers at Tmall Electronics validated component cost structures and channel dynamics. Bottom-up triangulation across device bill-of-materials analysis and top-down reconciliation against customs trade data ensured volume estimates anchored in physical flow verification.
Historical trendline analysis of cellular module cost curves, silicone raw material indices, and lithium-polymer cell pricing informed the projection framework. Segmentation dimensions modeled include product architecture, age-appropriate feature depth, material certification grade, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration curves across household income tiers. Industry-specific forecast inputs incorporated ETSI standards evolution for LPWAN interoperability and MFDS electromagnetic exposure guideline tightening for adolescent wearables.
The model assumes a particular technology adoption path; alternative pathways for satellite-direct-to-device integration would alter the outlook for GPS module demand. Forecasts reflect assumptions about institutional adoption velocity for school district location-tracking policies and carrier eSIM provisioning infrastructure buildout. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Women's Watch Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Wearable Computing Devices Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Electronic Underwear Market