
 Battery for Children Smart Watch Market | 2026-2036
Battery for Children Smart Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Battery for Children Smart Watch Market Insights
Aftermarket battery replacement revenue is tilting toward OEM-authorized channels as safety-conscious parents prioritize certified cells over third-party alternatives. ATL leverages its vertical integration in cobalt-free cathode development to command premium positioning in the children's segment. VARTA sustains its European manufacturing footprint to satisfy CE marking and REACH compliance requirements for EU-bound smart watch brands. Sunwoda competes through high-volume production of ultra-thin lithium polymer packs tailored to sub-40mm watch case dimensions.
A battery for children smart watch constitutes a compact electrochemical energy storage device, typically lithium polymer or lithium-ion in chemistry, engineered to deliver stable voltage output across temperature ranges of 0°C to 45°C while meeting IEC 62133 safety standards for portable cells in consumer products. Its primary commercial purpose centers on powering GPS tracking, two-way communication, and biometric monitoring functions in wearable devices designed for juvenile users. Lithium polymer configurations occupy the dominant share of value given their form-factor flexibility and superior energy density for slim industrial designs. Wireless charging infrastructure is expanding fastest among charging methods as magnetic alignment systems reduce port vulnerability and liquid ingress risks for active children. The 1000 mAh capacity tier remains the volume anchor, though 2000 mAh variants are gaining traction in premium models targeting multi-day GPS tracking without parental intervention.
FCC Part 15 governs radio-frequency emissions from cellular-enabled children's watches in the United States, while the EU AI Act and GDPR impose parallel constraints on voice data collection and geolocation processing that indirectly shape battery architecture through processing load specifications. China's GB standards and NMPA device classifications further define cell testing protocols for products manufactured in Shenzhen and Dongguan clusters. Stakeholders must monitor how evolving UN 38.3 lithium transport regulations and emerging state-level right-to-repair mandates in jurisdictions like California and New York reshape aftermarket battery accessibility and OEM service revenue models.
Market Dynamics
Shenzhen's electronics cluster concentrates contract manufacturing for children's smart watch batteries, creating supply-side leverage that shapes pricing power and certification requirements across the value chain.
Growth Catalysts
- EU Green Deal battery sustainability rules:Stricter material sourcing mandates are accelerating cobalt-free cathode development and circular economy investments among cell manufacturers supplying European brands.
- GPS tracking functionality expansion:Parents of children aged four to twelve are prioritizing multi-day location monitoring, pulling demand toward higher-capacity lithium polymer configurations.
- Wireless charging infrastructure:Magnetic alignment systems are eliminating port vulnerability concerns for active juvenile users, expanding addressable market among safety-conscious buyer segments.
Market Restraints
- Cobalt price volatility:Raw material input costs for traditional lithium-ion cathodes create margin compression for manufacturers without captive mining arrangements or alternative chemistry pathways.
- Shenzhen supply concentration:Battery pack assembly clustering in a single Chinese metropolitan region exposes brands to geopolitical friction and logistics disruption risks.
- IEC 62133 certification timelines:Extended safety testing protocols for portable cells delay product launches and tie up working capital in pre-market compliance phases.
Strategic Opportunities
- Right-to-repair mandates:Emerging state-level legislation in California and New York is creating aftermarket battery accessibility frameworks that favor OEM-authorized service channels.
- Ultra-thin form factor convergence:Sub-40mm watch case dimensions are opening white space for high-volume production of tailored lithium polymer packs with customized thermal management.
- GDPR-aligned voice data processing:EU AI Act constraints on biometric monitoring are driving demand for localized edge computing architectures that reduce transmission loads and extend battery runtime.
Industry Challenges
- UN 38.3 lithium transport compliance:Evolving air freight regulations for cells above specified watt-hour thresholds complicate inventory positioning and increase working capital requirements.
- Cross-functional talent scarcity:Battery electrochemistry expertise combined with pediatric wearable safety engineering represents a narrow labor pool that constrains R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery for Children Smart Watch Market |
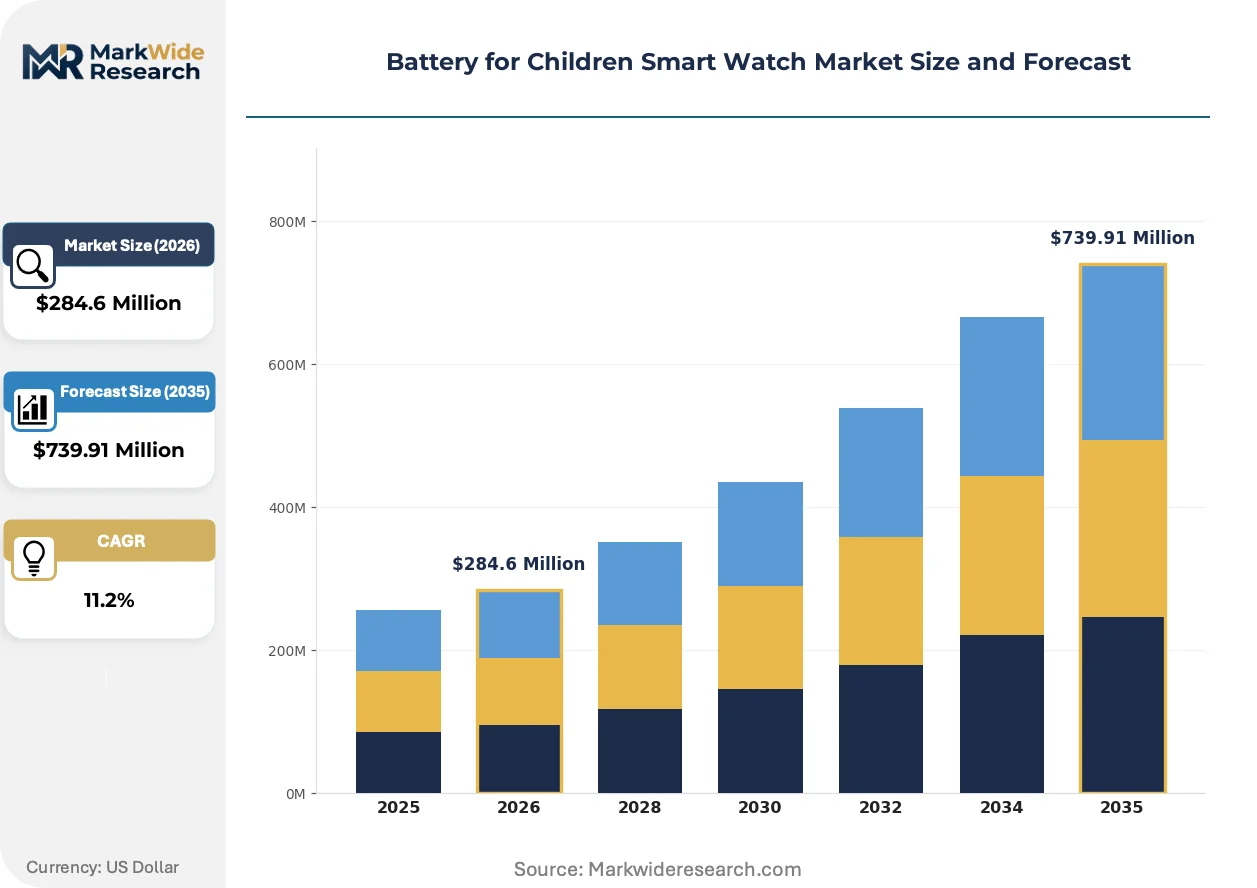
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $739.91 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel Metal Hydride, Lithium Polymer, Alkaline Charging Method: Wireless Charging, USB-C, Solar Charging, Direct Charge Capacity: 1000 mAh, 1500 mAh, 2000 mAh, 2500 mAh Usage Duration: 1 Day, 2 Days, 3 Days, 4 Days |
| Companies Covered | ATL, VARTA, EVE Energy, Sunwoda, Great Power, Ganfeng Lithium, AEC Battery, PATL Cell, VDL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery for Children Smart Watch Market Trends and Innovations
Solid-state electrolyte architectures and cobalt-free cathode formulations are actively disrupting incumbent lithium-ion supply chains, while regulatory pressure on material provenance is compressing traditional manufacturing timelines.
Solid-state battery technology replaces flammable liquid electrolytes with ceramic or polymer solid conductors, eliminating thermal runaway risks critical for juvenile wearable applications. Premium children's watch brands in the European Union are piloting these cells for 2026 product lines despite current cost premiums. This chemistry transition is rendering obsolete conventional lithium-ion pouch designs that rely on cobalt-heavy cathodes and organic solvent electrolytes.
The EU AI Act imposes strict constraints on voice data collection and geolocation processing from children's devices, indirectly mandating lower-power edge computing architectures. Battery manufacturers must now design cells capable of sustaining localized AI inference without continuous cloud transmission. European-bound smart watch brands are responding by specifying reduced standby current draw and enhanced deep-sleep efficiency in procurement tenders.
Certification-driven procurement preferences are consolidating buyer decision-making around OEM-authorized battery replacement channels. Safety-conscious parents are rejecting third-party alternatives despite price advantages, compressing aftermarket revenue toward certified cell distributors. This behavioral shift is most pronounced in Germany and France, where CE marking awareness and product liability consciousness shape purchasing patterns for juvenile electronics.
Battery for Children Smart Watch Market Segmentation
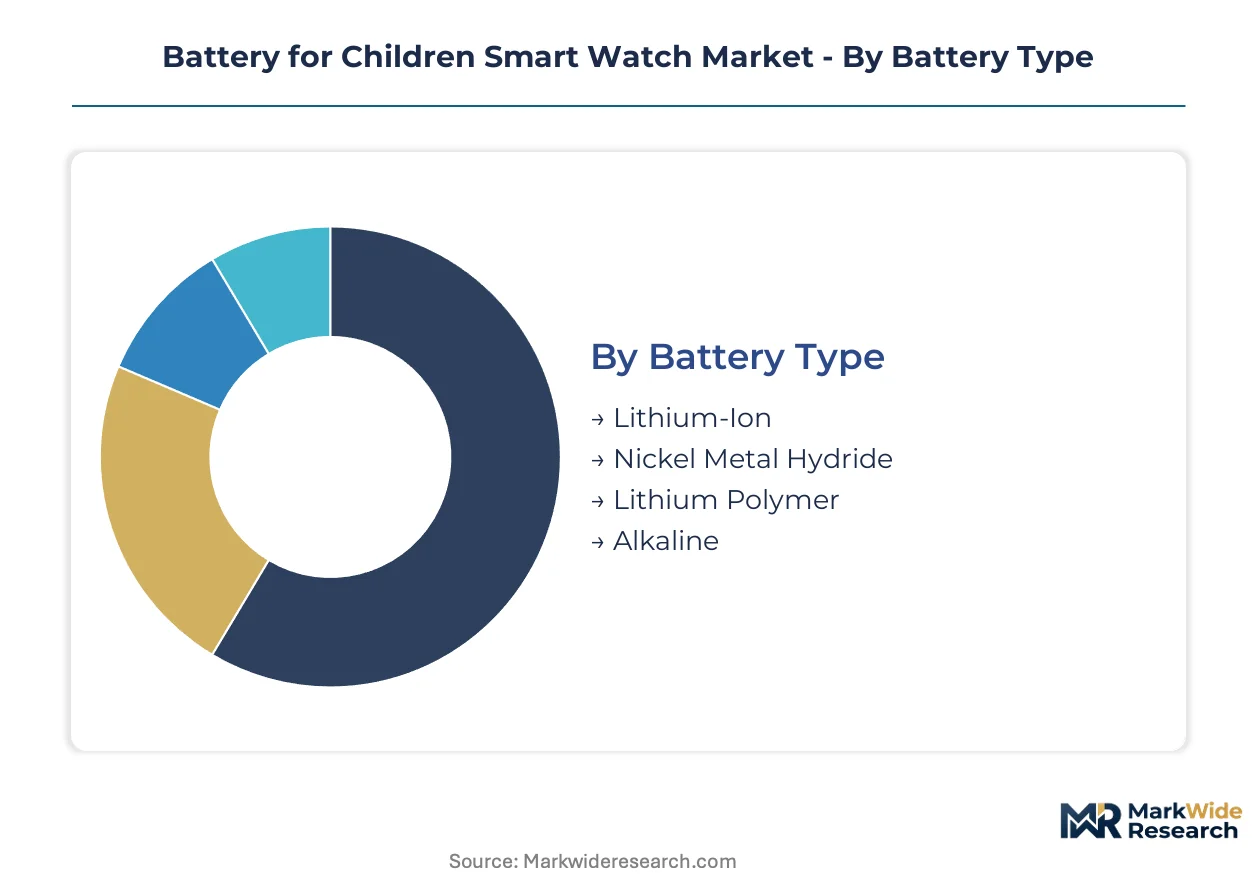
Segmentation in the children's smart watch battery market reveals how safety engineering and parental purchasing behavior fragment demand across chemistry types, charging interfaces, and runtime specifications. Each dimension carries distinct certification burdens and replacement cycle implications that shape manufacturer R&D allocation and channel strategy.
Battery Type:
Lithium polymer configurations turn over fastest as slim industrial designs and thermal safety requirements drive annual refresh cycles, while nickel metal hydride persists longest in legacy device maintenance.
- Lithium Polymer:Flexible pouch construction enables sub-40mm case integration with cobalt-free cathode formulations accelerating under EU Green Deal material mandates. Shenzhen contract manufacturers concentrate high-volume output here for GPS-enabled watches targeting four-to-twelve age segments where parental safety consciousness peaks.
- Lithium-Ion:Cylindrical and prismatic hard-case cells deliver higher discharge rates for cellular-enabled watches with continuous two-way communication. Demand clusters in China for domestic brands prioritizing cost efficiency over form-factor minimalism.
- Nickel Metal Hydride:Lower energy density restricts application to budget-tier legacy devices with minimal processing loads.
- Alkaline:Disposable primary cells survive only in novelty watch segments with no rechargeable infrastructure.
Lithium polymer dominates installed base. Lithium-ion is where expansion concentrates.
Charging Method:
Cost tier stratification separates premium magnetic alignment systems from economy direct-charge alternatives, with mid-tier USB-C capturing volume scale.
- Wireless Charging:Magnetic alignment eliminates liquid ingress risks for active juvenile users while reducing mechanical port failure. German and French parents prioritize this interface despite 15-20% price premiums, pulling procurement specifications from Shenzhen OEMs toward coil-integrated battery pack designs.
- USB-C:Universal connector standard enables cross-device cable reuse and accelerates replacement battery turnover through standardized port wear. Volume production concentrates in Dongguan assembly plants serving mid-market brands.
- Solar Charging:Amorphous silicon integration extends runtime in outdoor-oriented watch models with intermittent grid access.
- Direct Charge:Pogo-pin and proprietary dock systems persist in ultra-budget segments with minimal regulatory compliance overhead.
USB-C dominates installed base. Wireless charging is where expansion concentrates.
Capacity:
Application-driven segmentation maps runtime requirements to GPS tracking intensity and parental intervention tolerance.
- 1000 mAh:Baseline configuration supports single-day GPS polling with voice calling for school commute monitoring. Shenzhen manufacturers optimize cell thickness to 3.2mm for sub-40mm case compatibility.
- 2000 mAh:Dual-cell stacked architectures enable 48-72 hour autonomous tracking without parental charging intervention. European brands specify this tier for rural vacation use cases under GDPR-constrained edge computing loads.
- 1500 mAh:Mid-tier balancing of thickness and runtime for urban daily-use scenarios.
- 2500 mAh:Premium tier targeting multi-day camping and adventure watch formats with continuous biometric monitoring.
1000 mAh dominates installed base. 2000 mAh is where expansion concentrates.
Usage Duration:
Customer type segmentation separates anxiety-driven parental segments demanding maximum autonomy from convenience-oriented urban buyers accepting daily charging rituals.
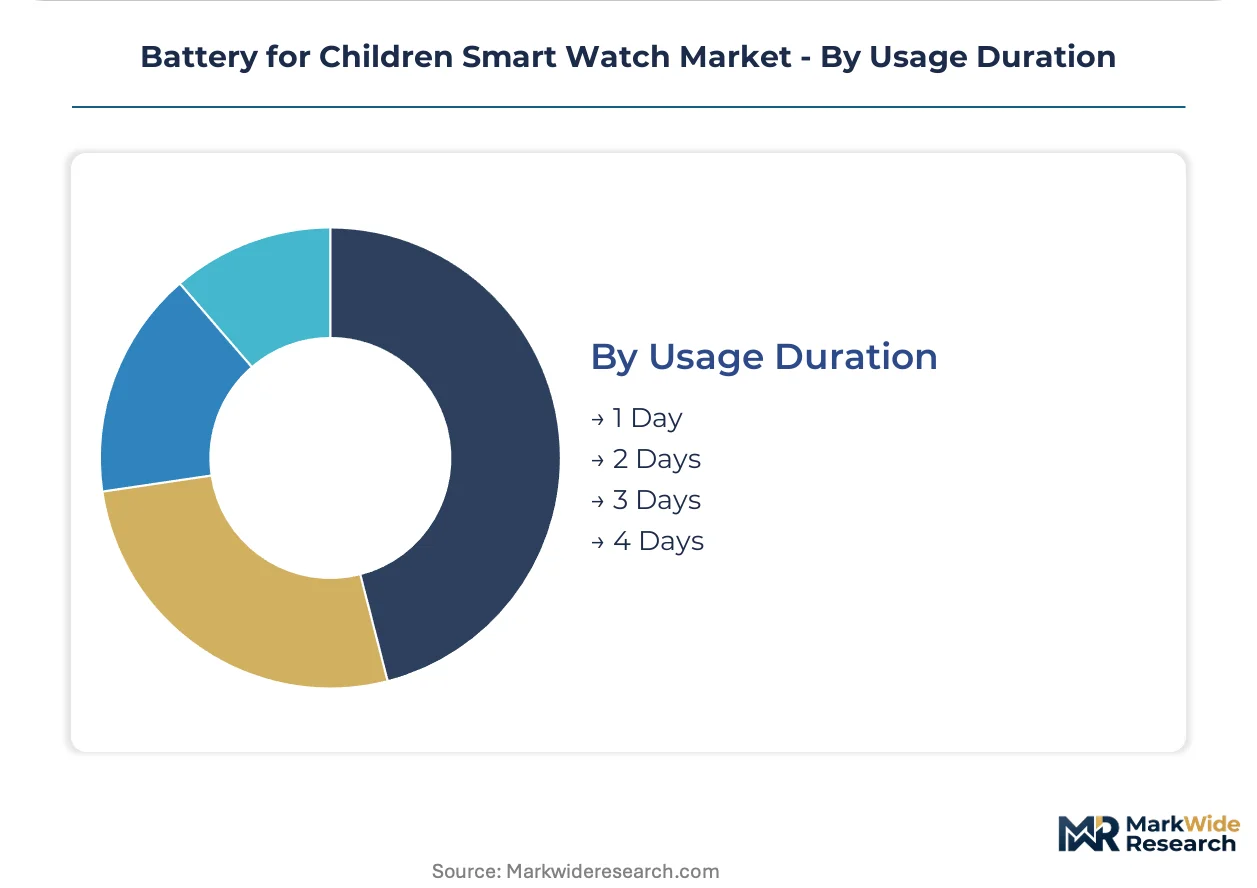
- 2 Days:48-hour runtime matches weekend custody transfer schedules and short school trips, emerging as the psychological threshold for "reliable" parental peace of mind. Battery procurement tenders from European distributors increasingly specify this minimum.
- 3 Days:72-hour specification supports rural family vacation scenarios with intermittent charger access. Chinese domestic brands pilot solid-state electrolyte architectures here to differentiate premium positioning.
- 1 Day:Nightly charging acceptance limits this tier to budget-conscious urban segments with predictable daily routines.
- 4 Days:Extended autonomy targets special needs monitoring and adventure watch applications with minimal market penetration.
1 Day dominates installed base. 2 Days is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes children's smart watch batteries at manufacturing scale for export production, while European and North American markets prioritize certified replacement channels and extended runtime specifications for end-user safety.
China
Shenzhen's electronics cluster drives contract manufacturing for GPS-enabled watches targeting four-to-twelve age segments, with Dongguan assembly plants serving mid-market brands. GB standards and NMPA device classifications define cell testing protocols for products manufactured in these clusters. The Pearl River Delta concentrates high-volume lithium polymer output for both domestic brands and export-bound OEMs.
Germany
Safety-conscious parents in Germany prioritize CE-marked batteries and OEM-authorized replacement channels over third-party alternatives. REACH compliance and EU Green Deal material mandates accelerate cobalt-free cathode procurement specifications from cell suppliers. Bavaria and Baden-Württemberg host distribution hubs serving Central European brands with certified battery logistics.
United States
FCC Part 15 governs radio-frequency emissions from cellular-enabled children's watches, while emerging state-level right-to-repair mandates in California and New York reshape aftermarket battery accessibility. Parents prioritize multi-day GPS tracking autonomy for school commute monitoring. The Southeast and Texas corridors concentrate e-commerce fulfillment infrastructure for replacement battery distribution.
France
CNIL oversight of voice data collection combines with GDPR geolocation constraints to drive demand for edge-computing architectures that reduce transmission loads and extend battery runtime. French buyers exhibit strong CE marking awareness and product liability consciousness. The Île-de-France region anchors procurement specifications for EU-bound smart watch brands.
Japan
METI efficiency standards and JIS certification requirements shape battery procurement for premium children's watch brands emphasizing thermal safety. Domestic manufacturers prioritize solid-state electrolyte pilot programs for 2026 product lines. The Kanto and Kansai regions concentrate R&D partnerships between cell suppliers and wearable electronics firms.
Battery for Children Smart Watch Market Competitive Landscape
Capability concentration sits with chemistry specialists commanding premium positioning through cobalt-free formulations; scale advantage sits with high-volume producers serving mid-market brands with standardized lithium polymer packs. The vendor base separates into three tiers: integrated cell manufacturers with captive cathode development, contract pack assemblers serving Shenzhen OEMs, and regional distributors managing certified replacement channels. Dominant competitive moves include backward integration into raw material sourcing and strategic partnerships with wearable brands for co-development of form-factor-specific designs.
Among Asia-Pacific-based cell producers, ATL, Sunwoda, and EVE Energy exemplify contrasting strategic archetypes. ATL occupies a position emphasizing chemistry innovation and vertical control over cathode formulations. Sunwoda anchors the high-volume contract manufacturing tier with specialization in ultra-thin pouch configurations. EVE Energy represents the diversified energy storage player leveraging scale economies across consumer electronics applications. European manufacturers including VARTA sit within the compliance-driven premium tier, sustaining continental manufacturing footprints to satisfy CE marking and REACH requirements for brands serving Germany, France, and adjacent markets.
| Leading Market Players |
|---|
| ATL |
| VARTA |
| EVE Energy |
| Sunwoda |
| Great Power |
| Ganfeng Lithium |
| AEC Battery |
| PATL Cell |
| VDL |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European cobalt-free cathode production is tightening supplier discipline and amplifying pricing power for certified cell manufacturers serving EU-bound children's watch brands. Shenzhen contract manufacturers respond with volume-driven cost structures that compress margins on standard lithium polymer configurations while premium tiers capture markup from REACH compliance and CE marking investments.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between Shenzhen pack assemblers and mid-market wearable brands, insulating against cobalt price volatility while spot purchases persist for prototype and premium solid-state pilot programs. Price differentiation hinges on IEC 62133 certification tier and after-sales service bundling, with OEM-authorized replacement channels commanding 25-40% premiums over third-party alternatives. Cost compression in the 1000 mAh standard tier is intensifying as Dongguan producers scale ultra-thin pouch output, though safety-conscious parents in Germany and France exhibit lowest price sensitivity among buyer segments.
Supply Chain Analysis
Extended payment terms from Shenzhen OEMs to cathode material suppliers are compressing working capital cycles and favoring vertically integrated cell producers with captive financing facilities. Raw material sourcing draws from lithium carbonate processed in Chile and Argentina, cobalt hydroxide from the DRC, and separator membranes manufactured in Japan and South Korea. Single-source vulnerability concentrates in Shenzhen-Dongguan battery pack assembly, where tariff exposure on Chinese-manufactured cells creates contingency planning costs for brands serving North American markets. Distribution runs through OEM-authorized service networks for certified replacement channels and electronics component distributors for original equipment supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Children's smart watch battery adoption sits in early-cycle expansion as GPS tracking functionality penetrates the four-to-twelve age segment and EU Green Deal material mandates accelerate chemistry transitions.
For Market Incumbents: Build certification moats around IEC 62133 and UN 38.3 compliance expertise to defend against emerging solid-state entrants and cobalt-free chemistry specialists. Backward integration into cathode material sourcing secures supply continuity amid raw material volatility, while capacity addition in Vietnam or Mexico hedges tariff exposure on Chinese-assembled packs. Channel control through OEM-authorized replacement networks locks in aftermarket revenue as right-to-repair mandates expand. For New Entrants and Emerging Players: Establish a beachhead in the 2000 mAh premium tier where multi-day GPS runtime specifications remain undersupplied by incumbent volume producers. The 48-72 hour autonomy segment targeting rural European vacation use cases offers lowest competitive density and highest margin capture potential. A go-to-market angle through co-development partnerships with niche adventure watch brands bypasses Shenzhen OEM procurement gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward chemistry specialists with demonstrated cobalt-free cathode pathways and existing REACH compliance infrastructure for European brand supply. The five-to-ten year viability window favors acquisition targets with solid-state electrolyte pilot programs and pediatric wearable safety engineering talent pools. The signal to watch is solid-state cost parity achievement in sub-500 mWh cells, which would trigger rapid displacement of incumbent lithium polymer architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Cobalt-Free Cathode Development | EU Green Deal material mandates are accelerating chemistry transitions among cell suppliers serving REACH-bound brands. |
| Solid-State Electrolyte Pilot Programs | Japanese METI efficiency standards and thermal safety requirements are driving premium tier differentiation for 2026 product lines. |
| OEM-Authorized Service Network Expansion | Right-to-repair mandates in California and New York are consolidating aftermarket revenue toward certified replacement channels. |
| Ultra-Thin Pouch Configuration Scale-Up | Sub-40mm watch case convergence in Shenzhen is creating volume opportunities for tailored thermal management designs. |
| Edge Computing Architecture Partnerships | GDPR and EU AI Act constraints on voice data processing are pulling demand toward localized inference with reduced transmission loads. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with battery cell engineering directors, Shenzhen contract manufacturing procurement leads, European wearable brand supply chain managers, and pediatric device safety compliance officers. Secondary validation drew from NMPA device classification filings, EU Battery Regulation implementation guidance, UN 38.3 transport certification databases, and IEC 62133 test report archives. Bottom-up cell shipment estimates by capacity tier and chemistry type were triangulated against top-down wearable brand production forecasts across the analysis window.
Calibration against historical lithium polymer adoption curves in consumer electronics and pediatric wearable penetration patterns anchored the analytical framework. Segmentation dimensions modeled included battery chemistry type, charging interface standard, capacity tier, usage duration specification, and regional regulatory cluster. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint anchoring, with inputs from GPS tracking functionality attach rates and wireless charging infrastructure deployment curves in target markets.
Stress conditions across cobalt price volatility bands, Shenzhen logistics disruption scenarios, and EU material sourcing mandate acceleration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding solid-state cost reduction curves and right-to-repair legislative diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Smart Bra Market
Wearable Technology
Asia Pacific Smartwatch Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Women's Watch Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
UK Wearable Technology Market