
 Global Intelligent Platform Management Interface (IPMI) Market | 2026-2036
Global Intelligent Platform Management Interface (IPMI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Platform Management Interface (IPMI) Market Intelligence
Demand from hyperscale cloud providers is collapsing the distinction between traditional OEM and white-box server procurement. Super Micro Computer specializes in optimized server solutions that integrate IPMI functionalities for this customer base. Intel Corporation provides foundational Baseboard Management Controller (BMC) firmware and silicon, influencing standards across the ecosystem. Hewlett Packard Enterprise differentiates through its integrated Lights-Out (iLO) management platform, which extends beyond base IPMI capabilities for enterprise clients.
Intelligent Platform Management Interface is a set of standardized specifications for out-of-band computer system management. It operates independently of the host system's CPU, firmware, and operating system, enabling administrators to manage a server even if it is powered off or unresponsive. While Data Centers constitute the largest application segment, Edge Computing represents the fastest-growing area for new deployments. Embedded Solutions are gaining share over Standalone Systems, as IPMI functionality becomes a standard feature integrated directly onto server motherboards by OEMs.
Security standards from bodies like the US National Institute of Standards and Technology (NIST) influence firmware security requirements for IPMI implementations. In Europe, GDPR compliance considerations affect how remote access and data monitoring are handled through management interfaces. Vendor success now depends on navigating the transition from the legacy IPMI 2.0 protocol to the more secure and scalable Redfish API standard, which is displacing the older technology.
Market Dynamics
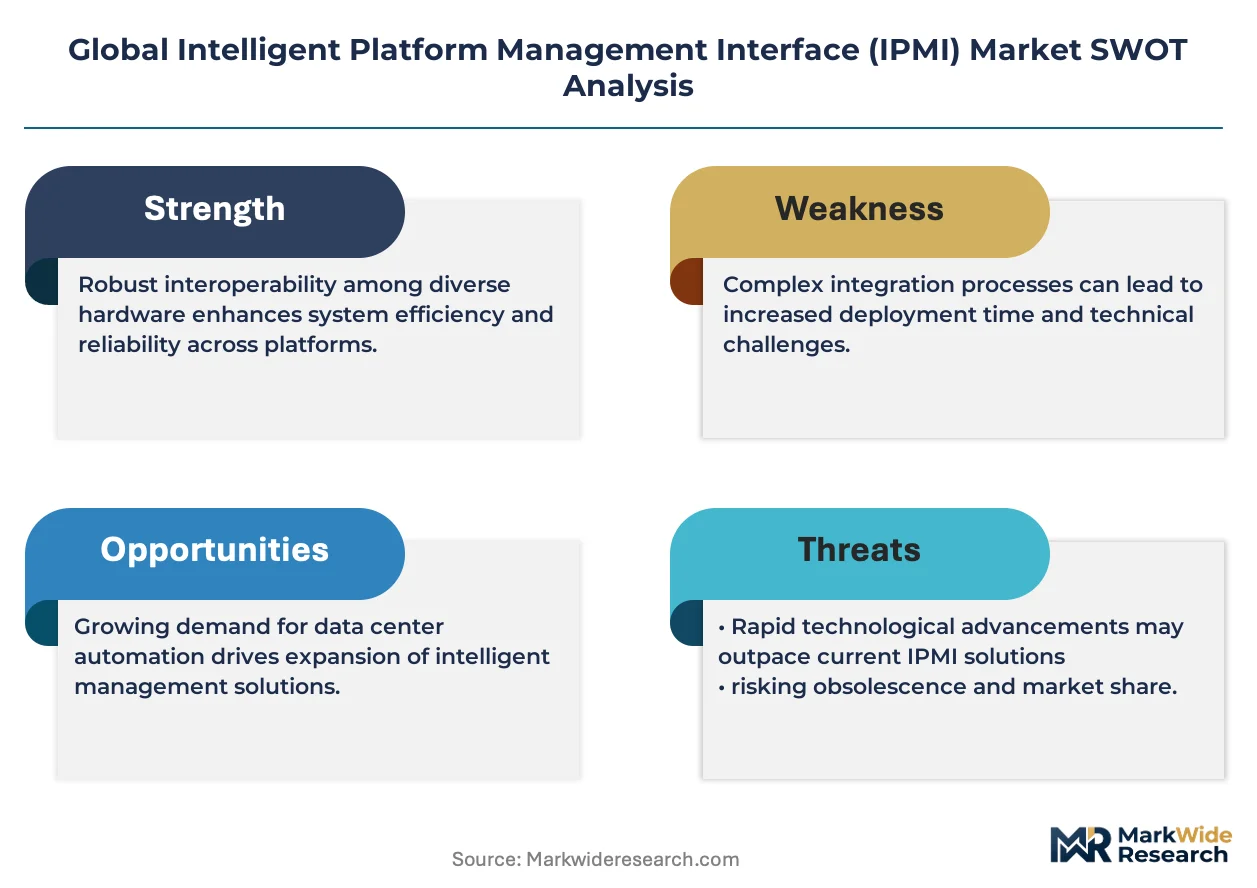
The industry's migration from the legacy IPMI 2.0 protocol to the modern Redfish API standard is the central force reconfiguring the market. This shift compels vendors to overhaul firmware, security protocols, and product roadmaps.
Growth Catalysts
- Edge Computing Expansion:The deployment of compute resources in remote locations for 5G networking and industrial automation necessitates robust out-of-band management, driving demand for embedded IPMI solutions.
- Hyperscale Data Center Construction:Continued massive investment in new data center capacity, particularly in the United States and China, directly fuels volume demand for server motherboards with integrated baseboard management controllers.
- NIST Security Frameworks:Guidelines from the US National Institute of Standards and Technology, such as Platform Firmware Resiliency standards, create demand for more secure IPMI implementations with features like cryptographic validation.
Market Restraints
- Legacy Protocol Insecurity:Well-documented security vulnerabilities in the IPMI 2.0 specification act as a significant restraint, forcing costly mitigation efforts and accelerating its obsolescence.
- Redfish Transition Costs:While a necessary evolution, the transition to the Redfish API standard requires substantial R&D investment in new firmware stacks, creating a financial barrier for smaller vendors.
- BMC Silicon Dependencies:The market's reliance on a concentrated number of vendors for Baseboard Management Controller (BMC) silicon creates potential supply chain bottlenecks and limits design flexibility for server OEMs.
Strategic Opportunities
- Predictive Analytics Integration:Integrating AI and machine learning algorithms into BMC firmware for predictive hardware failure analysis offers a new value proposition beyond simple remote management.
- Management for IoT and Embedded Systems:Extending IPMI-like management principles to industrial IoT gateways and other complex embedded systems represents a new frontier for growth outside of traditional data centers.
- Tier-2 Cloud Provider Markets:Targeting regional cloud and hosting providers in fast-growing digital economies, such as those in India and Brazil, offers a path for expansion beyond the saturated hyperscale segment.
Industry Challenges
- Firmware Talent Scarcity:A shortage of software engineers with specialized skills in both embedded systems programming and secure API development hinders product innovation and security hardening.
- Redfish Profile Standardization:The pace of creating and ratifying specific Redfish profiles for new hardware types, such as accelerators, can lag behind hardware innovation, causing implementation friction.
- Backward Compatibility Issues:Managing a graceful transition from IPMI 2.0 to Redfish within a heterogeneous data center environment presents a major operational challenge for enterprise IT administrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Platform Management Interface (IPMI) Market |
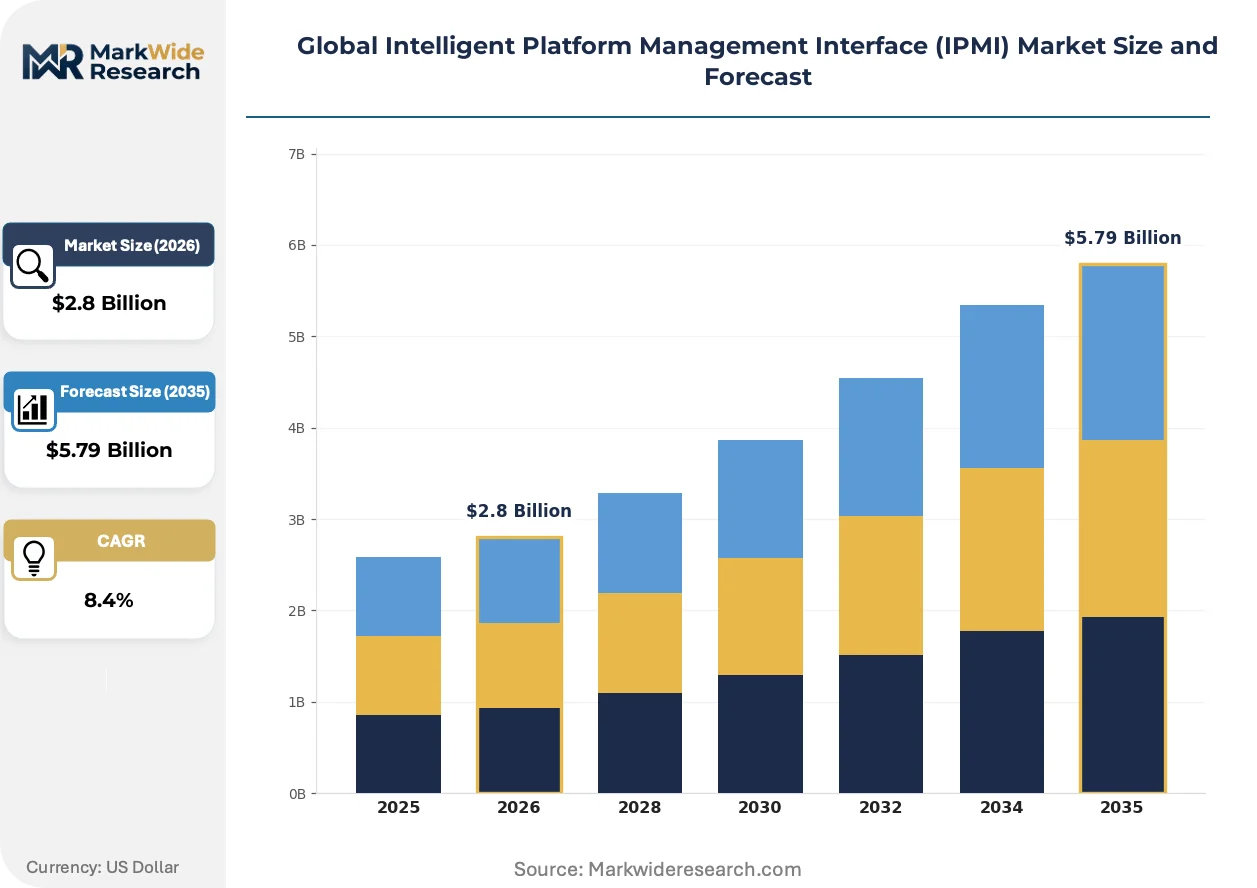
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Standalone Systems, Embedded Solutions, Remote Management, Cloud-Integrated Units, On-Premise Models Technology: Serial-over-LAN, KCS Interface, SMS/Redirection, SOL Serial Console, RMCP Protocol Application: Data Centers, Server Farms, High Performance Computing, Telecommunication Nodes, Edge Computing End User: OEMs, Managed Service Providers, System Integrators, Telecommunications Operators, Hosting Facilities |
| Companies Covered | Super Micro Computer, Cisco Systems, Hewlett Packard Enterprise, Emerson Electric Company, ARM Holdings, Intel Corporation, Dell, Microsoft Corporation, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Platform Management Interface (IPMI) Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from basic remote control to intelligent, automated infrastructure orchestration. This transition is driven by new API standards, stringent data governance rules, and changing server procurement models.
A modern, RESTful API known as Redfish provides a standardized way to manage servers and other data center hardware. Hyperscale and enterprise clients are rapidly adopting this standard for its programmatic and secure interface. The Redfish API is supplanting the older, less secure IPMI 2.0 protocol, enabling seamless integration with contemporary DevOps automation and infrastructure-as-code toolchains.
Regulatory frameworks like the EU's General Data Protection Regulation (GDPR) are influencing management interface design. GDPR's strict requirements for data handling and user access apply even to administrative functions, compelling vendors to enhance security. Consequently, IPMI and Redfish implementations destined for Europe require more granular audit logging, stronger authentication mechanisms, and explicit privacy controls.
Altered buying behaviors from hyperscale cloud providers are reshaping the supply chain. These large-scale buyers now frequently co-design server specifications directly with Original Design Manufacturers (ODMs), largely bypassing traditional OEM sales channels. This procurement model, most visible in data center clusters in the United States and China, prioritizes cost efficiency and customization over brand loyalty.
Global Intelligent Platform Management Interface (IPMI) Market Segmentation
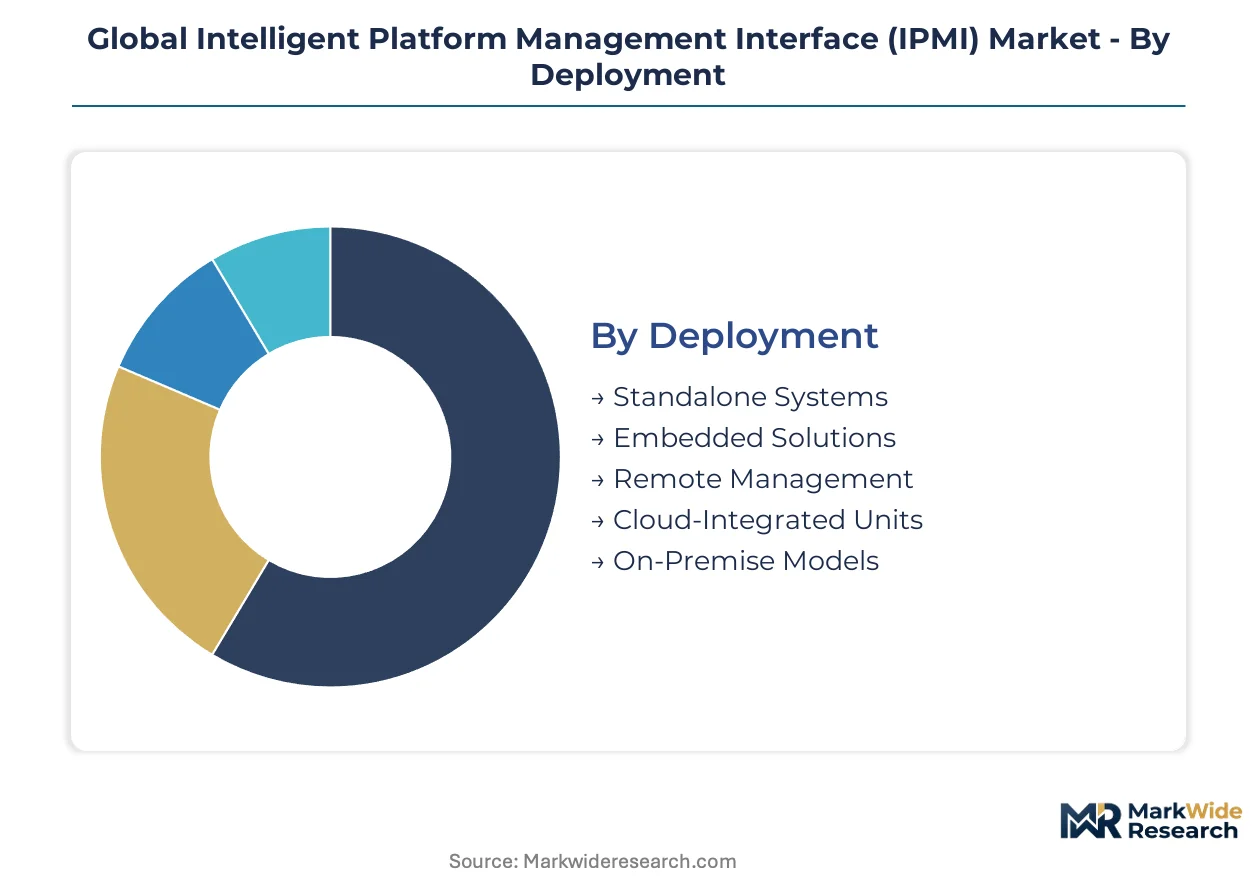
The Intelligent Platform Management Interface (IPMI) market segments into distinct categories that reveal critical shifts in technology adoption and infrastructure deployment. Understanding these segments helps identify where innovation is concentrated and how different end-user requirements shape product development. This segmentation highlights the diverse operational contexts for IPMI, from traditional data centers to emerging edge environments.
Deployment:
Deployment models for IPMI solutions exhibit distinct adoption patterns across different geographies, reflecting varying infrastructure maturity and regulatory landscapes.
- Standalone Systems:These traditional setups involve a dedicated BMC chip and firmware on a server motherboard, managed via a direct network connection. Adoption is still present in older enterprise environments and smaller data centers.
- Embedded Solutions:IPMI functionality is integrated directly into the server motherboard chipset or a dedicated BMC, becoming a standard feature for most new server procurements. Demand for these solutions is significant in the United States and China, driven by hyperscale data center expansion.
- Remote Management:This segment encompasses solutions enabling out-of-band control and monitoring of servers from geographically distant locations. These systems are crucial for distributed IT infrastructures and facilities with limited on-site personnel.
- Cloud-Integrated Units:These units offer IPMI capabilities designed for seamless integration with public or private cloud management platforms, leveraging APIs for automated orchestration. Hyperscale cloud providers in the United States and Europe increasingly demand these integrated solutions for their vast server fleets.
- On-Premise Models:IPMI implementations designed for deployment within an organization's own data center or local server rooms, emphasizing internal network security and control. These models are common among enterprise clients with strict data governance requirements.
Embedded Solutions holds the largest share; momentum sits with Cloud-Integrated Units.
Technology:
Different IPMI technologies offer varying levels of functionality and cost efficiency, influencing their adoption across diverse system architectures.
- Serial-over-LAN:This technology enables remote access to the server's serial console over an IP network, allowing command-line interaction with the system. It remains a fundamental method for basic out-of-band management in many data centers.
- KCS Interface:The Keyboard Controller Style (KCS) interface provides a basic communication channel between the host CPU and the BMC, primarily used for local management and initial system configuration. This interface is foundational for BMC operation.
- SMS/Redirection:This includes System Management Software (SMS) and console redirection features, allowing administrators to view and interact with the server's console output remotely. It provides a visual interface for troubleshooting and OS installation.
- SOL Serial Console:This refers to the Serial-over-LAN (SOL) feature of IPMI, which redirects the server's serial port output to a network connection for remote access. It is vital for debugging and managing systems without a graphical interface.
- RMCP Protocol:The Remote Management Control Protocol (RMCP) is the network protocol used by IPMI for transmitting management commands and responses over UDP. This protocol is central to the IPMI 2.0 specification, which is being displaced by the Redfish API standard.
While Serial-over-LAN remains foundational, RMCP Protocol is rapidly being superseded.
Application:
The volume of IPMI deployments varies significantly across different application environments, driven by specific operational requirements and infrastructure scales.
- Data Centers:These facilities house vast numbers of servers, requiring robust IPMI for efficient remote management, monitoring, and maintenance. Hyperscale data centers in China and the United States represent the largest demand segment.
- Server Farms:Similar to data centers but often on a smaller scale, server farms utilize IPMI for managing clusters of servers dedicated to specific tasks. These environments prioritize cost-effective and reliable remote access.
- High Performance Computing:HPC clusters demand highly reliable and responsive out-of-band management for their complex and often densely packed server configurations. IPMI ensures system stability and rapid issue resolution.
- Telecommunication Nodes:Remote telecommunication infrastructure, including 5G base stations and central offices, relies on IPMI for managing servers in often unattended and geographically dispersed locations. This application requires extreme reliability and security.
- Edge Computing:The deployment of compute resources at the network edge, closer to data sources, necessitates robust IPMI for managing systems in remote or challenging environments. Edge computing represents the fastest-growing area for new deployments, particularly for industrial automation and IoT.
Data Centers represent the largest volume, while Edge Computing is experiencing the steepest expansion trajectory.
End User:
IPMI solutions are tailored to distinct end-user types, each with unique procurement patterns and integration needs across the ecosystem.
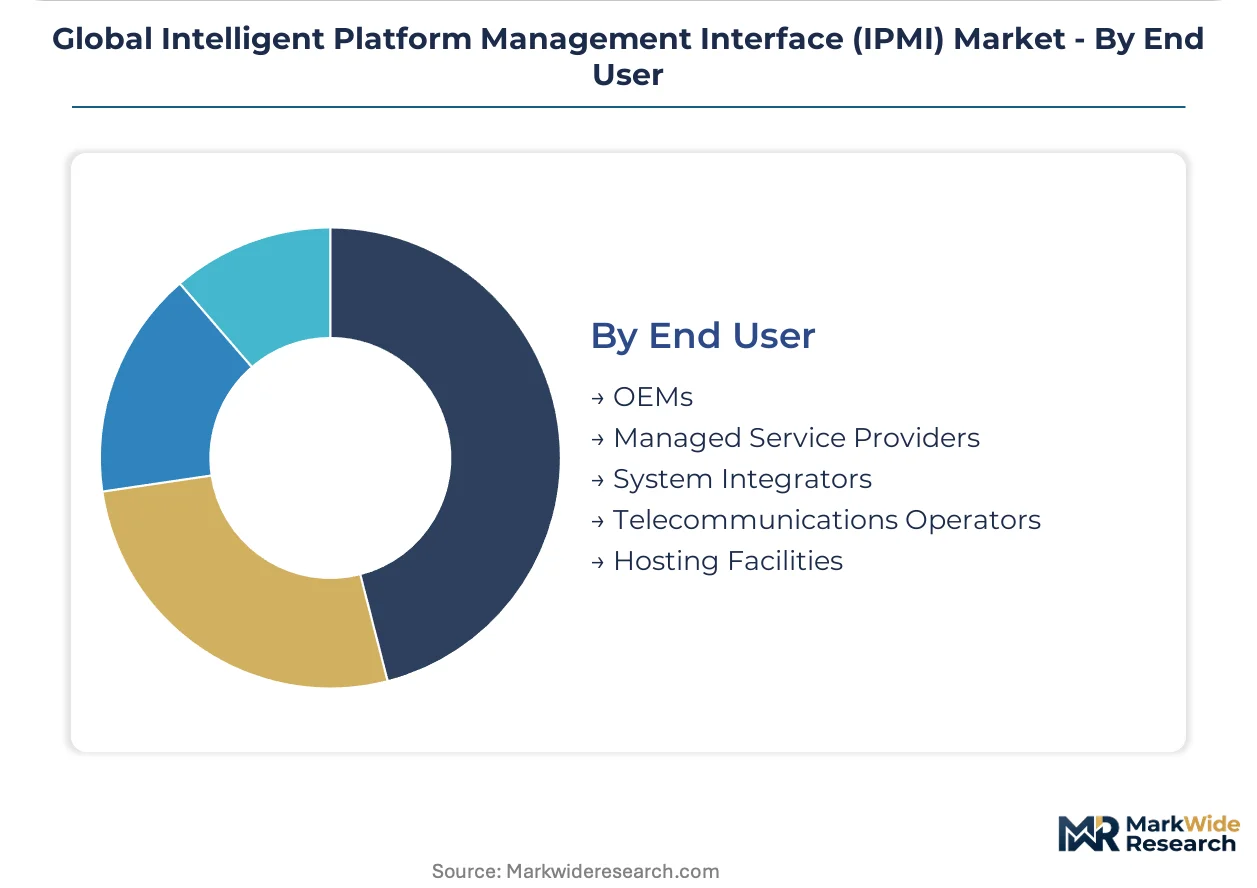
- OEMs:Original Equipment Manufacturers integrate IPMI functionality directly into their server motherboards and systems during the manufacturing process. These companies influence the baseline features and standards of IPMI implementations.
- Managed Service Providers:MSPs utilize IPMI to remotely manage and maintain their clients' server infrastructure, ensuring uptime and delivering consistent service levels. Remote management capabilities are critical for their business model.
- System Integrators:SIs deploy and configure IPMI solutions as part of larger IT infrastructure projects for enterprise and government clients. They often customize IPMI setups to meet specific client requirements.
- Telecommunications Operators:Telecom operators use IPMI to manage their extensive network infrastructure, including servers deployed in remote central offices and edge locations. Their focus is on scalability and resilience.
- Hosting Facilities:These providers offer server hosting services, relying on IPMI for efficient remote management of customer servers within their data centers. Rapid provisioning and troubleshooting are key for hosting operations.
OEMs remain central to initial integration, with Managed Service Providers showing significant growth in service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global intelligent platform management interface market exhibits distinct regional dynamics, largely influenced by the proliferation of hyperscale data centers and the expansion of edge computing infrastructure. The substantial investment in digital infrastructure globally drives demand for sophisticated out-of-band management solutions. These regional variations underscore diverse operational priorities and regulatory environments across key geographies.
United States
Massive hyperscale data center construction and the rapid deployment of 5G infrastructure fuel demand for advanced IPMI solutions. NIST security frameworks, such as Platform Firmware Resiliency standards, mandate more secure implementations with cryptographic validation. Silicon Valley and Northern Virginia represent major data center clusters, driving innovation in integrated BMCs and Redfish API adoption for cloud providers.
China
Continued investment in cloud infrastructure and the national push for industrial automation significantly boost IPMI adoption for server farms and edge deployments. China's GB standards and national digital transformation policies emphasize localized and secure management solutions. The Yangtze River Delta and Beijing-Tianjin-Hebei regions are central to hyperscale data center expansion, integrating embedded IPMI for vast server fleets.
Germany
The strong focus on industrial automation and the growing demand for secure data centers drive the adoption of embedded IPMI solutions. GDPR compliance considerations heavily influence how remote access and data monitoring are handled through management interfaces. Frankfurt and Berlin serve as key data center hubs, where colocation facilities prioritize Redfish API for enhanced security and automated orchestration.
Japan
Digital transformation initiatives and the expansion of telecommunication nodes for 5G services create substantial demand for reliable out-of-band management. METI guidelines encourage the integration of secure and efficient IT infrastructure, including advanced IPMI features. Tokyo and Osaka remain primary technology centers, fostering the deployment of cloud-integrated IPMI units for enterprise and hosting providers.
Global Intelligent Platform Management Interface (IPMI) Market Key Industry Players
Concentration sits with established technology conglomerates and specialized server manufacturers that integrate IPMI functionality into their core offerings. The market structure exhibits a tiered landscape, where foundational silicon providers influence standards, and system integrators customize solutions for diverse enterprise needs. This environment fosters competition among vendors to differentiate through enhanced security features and API compatibility. Dominant competitive moves include strategic partnerships for Redfish API development and continuous R&D investment in firmware security and predictive analytics integration.
Within the specialized server solutions segment, Super Micro Computer exemplifies an OEM focusing on optimized server solutions with integrated IPMI functionalities for hyperscale providers. Intel Corporation anchors the foundational silicon and BMC firmware layer, influencing standards across the entire ecosystem with its robust offerings and extensive developer support. Hewlett Packard Enterprise occupies a position as a provider of integrated management platforms, such as iLO, extending beyond base IPMI capabilities for its enterprise clients and offering enhanced features for remote management and diagnostics. These companies collectively shape the technological direction and market adoption of IPMI and Redfish standards.
| Leading Market Players |
|---|
| Super Micro Computer |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Emerson Electric Company |
| ARM Holdings |
| Intel Corporation |
| Dell |
| Microsoft Corporation |
| NEC Corporation |
| Others |
Cost & Logistics Intelligence
Lengthy lead times for specialized Baseboard Management Controller (BMC) silicon concentrate pricing power among a few foundational manufacturers. This directly influences the cost structure of integrated Intelligent Platform Management Interface (IPMI) solutions for server Original Equipment Manufacturers (OEMs).
Pricing Analysis
Volume-based tiered pricing structures dominate the Intelligent Platform Management Interface market. Price differentiation stems from customization levels for Redfish API profiles and comprehensive after-sales support packages. Pricing softness affects entry-level embedded solutions due to intense competition among server OEMs. Hyperscale cloud providers exhibit high price sensitivity, while enterprise clients often prioritize feature sets and security for their integrated management platforms.
Supply Chain Analysis
The concentrated production of advanced semiconductor fabrication in Taiwan and South Korea underpins the supply chain for Baseboard Management Controller (BMC) silicon. Key inputs include specialized integrated circuits and firmware development expertise, sourced primarily from these regions and China. A structural risk involves single-source vulnerability for critical components, impacting multiple server manufacturers. Distribution runs through direct sales channels to large Original Equipment Manufacturers and Original Design Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant fragmentation opportunity as the shift towards edge computing and specialized workloads creates diverse management interface requirements. New demand signals emerge from industrial automation and 5G infrastructure deployments.
For Market Incumbents: Secure long-term contracts with hyperscale cloud providers for Redfish API-compliant solutions, ensuring stable volume demand. Invest in advanced firmware security certifications like NIST Platform Firmware Resiliency standards to counter emerging open-source BMC alternatives. Deepen vertical integration into BMC silicon design to mitigate supply chain dependencies. Prioritize R&D in predictive analytics for hardware failure, enhancing value beyond basic remote management.
For New Entrants and Emerging Players: Unaddressed needs in management for IoT and specialized embedded systems represent a prime entry point. Target regional cloud providers in India and Brazil, which are less saturated than hyperscale segments. Focus on edge computing deployments requiring customized Redfish profiles for specific industrial automation use cases. Offer flexible, API-first management platforms with strong security features to differentiate from legacy solutions.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger technology conglomerates with non-core embedded systems divisions. The market offers long-term viability for niche specialists providing secure, Redfish-native solutions over the next decade. Seek specialized firmware development houses or Redfish API integration experts with strong intellectual property. The acceleration of Redfish profile standardization for new hardware types signals market readiness for scalable acquisitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Redfish API Development | Accelerates the transition from legacy IPMI 2.0, enhancing security and automation for data center operators. |
| Edge Computing Solutions | Expands market reach into 5G infrastructure and industrial IoT, addressing new out-of-band management needs. |
| Firmware Security Certification | Builds trust with enterprise and government clients, meeting stringent NIST and GDPR compliance requirements. |
| Predictive Analytics Integration | Adds value by enabling proactive hardware maintenance, reducing downtime for hyperscale cloud providers. |
| Strategic Partnerships for BMC Silicon | Mitigates supply chain risks and fosters innovation in foundational components for server OEMs. |
Research Approach
The analysis maps intelligent platform management interface sub-sectors, each validated through extensive primary interviews with industry stakeholders. These included server architects, data center managers, firmware engineers, and IT procurement specialists. Secondary data sources comprised SEC filings of public technology companies, industry association reports (e.g., DMTF), and technical specifications from standards bodies (e.g., NIST). Bottom-up modeling and top-down market sizing ensure data accuracy through iterative triangulation.
Forecast outputs were consistently validated against external industry benchmarks and historical market performance trends. The quantitative model leverages historical data and projected technology adoption rates over the projection horizon. Segmentation dimensions included deployment models, technology types, and key application environments. Compound Annual Growth Rates were derived from multi-variable regression, incorporating hyperscale data center construction and 5G infrastructure.
Forecasts assume regulatory continuity in US, EU, and Chinese regimes; material policy shifts would require re-modeling. The analysis accounts for unforeseen supply chain disruptions or Redfish API standardization shifts. Practitioners should keep alternative scenarios live as technology adoption rates and security threats evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Shipping Software Market
Digital Solutions
Global Application Container Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
EHS Software Market