
 Headsets for PC Market | 2026-2036
Headsets for PC Market Size, Share, and Industry Trends Forecast 2026-2036
Headsets for PC Market Insights
China is tilting toward expanded manufacturing capacity for wireless audio components serving PC peripheral supply chains. Logitech International SA leverages its Swiss-engineered R&D pipeline to sustain premium positioning across European and North American distribution channels. Razer Inc. anchors its competitive stance through deep specialization in RGB-integrated gaming headsets with proprietary software ecosystems. Turtle Beach Corporation differentiates via console-crossover designs that occupy a unique bridge segment between PC and living-room gaming.
Headsets for PC constitute audio reproduction devices engineered with 20 Hz–20 kHz frequency response, detachable cardioid microphones, and USB or 3.5 mm analog connectivity for desktop and laptop integration. Their primary commercial purpose centers on delivering spatial audio cues for competitive gaming, noise-isolated voice communication for distributed workforces, and immersive playback for multimedia consumption. Wireless Bluetooth configurations are capturing the fastest expansion trajectory as latency compression technologies mature, while wired USB segments retain margin concentration among tournament-grade buyers demanding zero-lag signal transmission. Virtual 7.1 surround technology leads the premium tier as game developers optimize spatial audio engines for directional accuracy.
FCC equipment authorization requirements in the United States govern radio-frequency emissions for wireless headset models, directly conditioning product development timelines and certification costs for manufacturers targeting North American retail placement. The EU RoHS directive restricts hazardous substance thresholds in electrical equipment, compelling reformulation of solder alloys and cable insulation across production lines serving European consumers. Ecodesign regulations under the EU Green Deal are tightening energy-consumption benchmarks for battery-powered peripherals, forcing trade-offs between wireless endurance and component miniaturization. Stakeholders must monitor evolving interoperability standards between proprietary dongle protocols and native Bluetooth LE Audio to anticipate which connectivity architecture secures platform dominance across PC OEM bundling agreements.
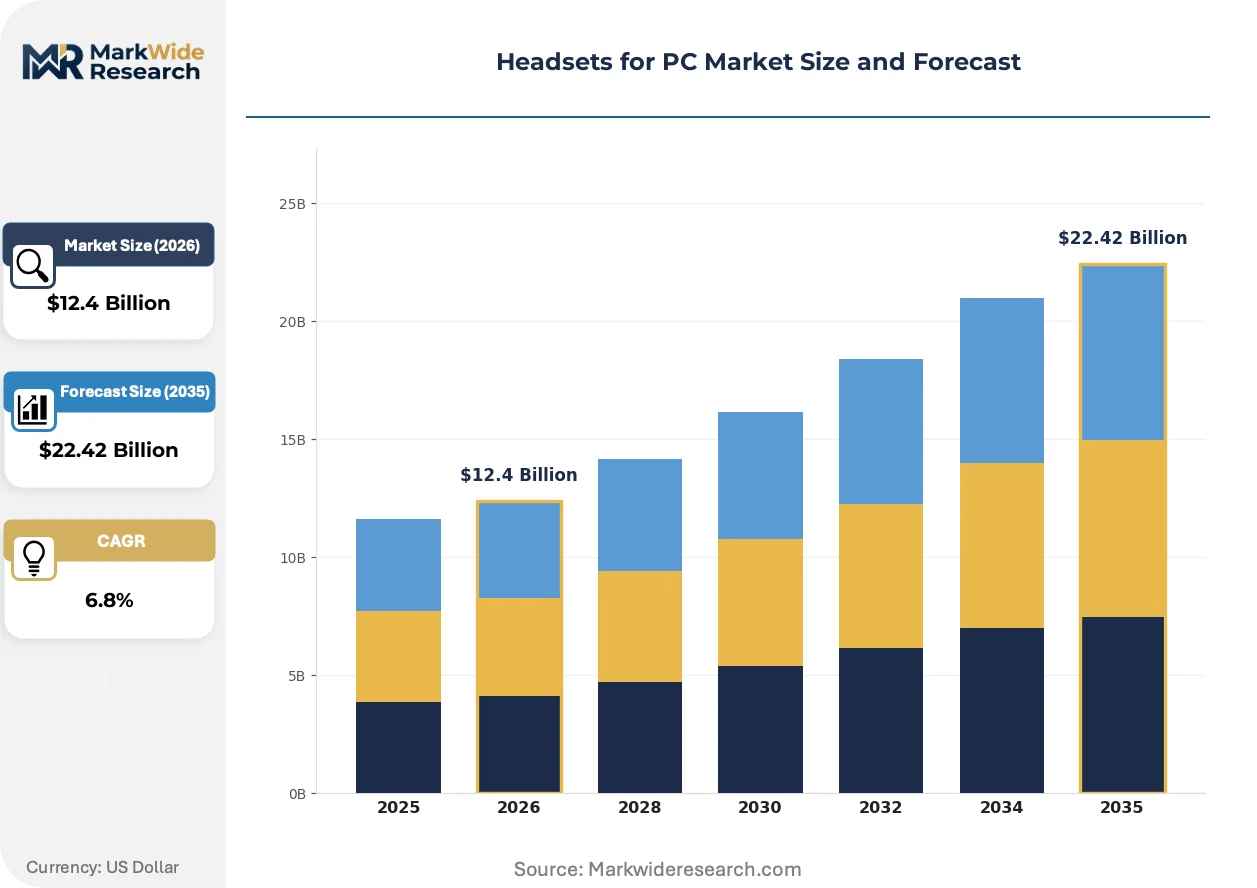
Market Dynamics
Latency compression algorithms and LE Audio protocol maturation are restructuring competitive positioning across wireless PC peripherals, compressing the historical performance gap that tethered tournament-grade buyers to USB-C cables.
Growth Catalysts
- REACH Directive reformulation:EU restrictions on restricted substances in electronics are accelerating material innovation for ear cushions and headbands, opening premium positioning for compliant manufacturers.
- Esports broadcasting infrastructure:Gaming streamers on Twitch and YouTube are intensifying live broadcasting requirements, pulling multi-channel audio and broadcast-grade microphone specifications into mainstream SKU tiers.
- Spatial audio engine optimization:Game developers are hardening directional accuracy algorithms for virtual 7.1 surround, expanding the addressable base beyond competitive gaming into immersive multimedia consumption.
Market Restraints
- Rare earth magnet supply concentration:Neodymium driver assembly depends on processing capacity concentrated in China, exposing cost volatility and geopolitical sourcing risk for premium driver units.
- RoHS solder alloy reformulation:European hazardous substance thresholds are forcing production line retooling and yield compression during transition periods for cable termination and PCB assembly.
- Bluetooth dongle protocol fragmentation:Proprietary wireless stacks from peripheral OEMs create interoperability dead zones with native motherboard Bluetooth controllers, fragmenting the wireless upgrade path.
Strategic Opportunities
- PC gaming café bulk procurement:China's domestic esports leagues sustain concentrated demand for surround-sound units in venue deployment, creating volume anchor contracts for certified suppliers.
- EU Green Deal ecodesign benchmarks:Tightening energy-consumption standards for battery-powered peripherals are forcing trade-offs that favor suppliers with advanced power management silicon integration.
- Console-crossover bridge designs:Living-room gaming migration is opening SKU differentiation that spans PC and console ecosystems through dual-connectivity architectures.
Industry Challenges
- FCC equipment authorization timelines:Radio-frequency emissions certification for wireless headset models conditions North American retail placement schedules, compressing product launch windows.
- Legacy 3.5 mm analog integration:Maintaining backward compatibility with aging motherboard audio codecs while advancing USB-C digital audio stacks burdens firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Headsets for PC Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Bluetooth, USB, Surround Sound Technology: Active Noise Cancellation, Passive Noise Isolation, Virtual 7.1, Stereo, Bone Conduction Application: Gaming, Remote Work, Multimedia, Online Learning, Communication End User: Gamers, Content Creators, Business Professionals, Educators, Streamers |
| Companies Covered | Razer Inc., Logitech International SA, Corsair Gaming Inc., HyperX (HP Inc.), SteelSeries ApS, Sony Interactive Entertainment, Turtle Beach Corporation, Astro Gaming, Audeze LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Headsets for PC Market Trends and Innovations
Connectivity architecture decisions are hardening into platform-defining bets as dongle protocols, native Bluetooth LE Audio, and USB-C digital stacks compete for OEM bundling dominance across laptop and desktop supply chains.
Bluetooth LE Audio with Auracast broadcast capabilities is migrating from mobile-first deployment into PC peripheral ecosystems. Gaming peripheral manufacturers are integrating the codec stack into 2.4 GHz dongle alternatives. The technology is migrating from latency-sensitive competitive segments toward mainstream wireless replacement cycles.
Ecodesign regulations under the EU Green Deal are tightening energy-consumption benchmarks for battery-powered peripherals. Manufacturers serving European consumers face forced trade-offs between wireless endurance and component miniaturization. Battery chemistry selection and power management IC integration now determine market access eligibility for the region.
Enterprise distributed workforces are consolidating voice communication hardware procurement around certified Teams and Zoom device programs. IT departments are displacing ad-hoc consumer headset purchases with managed peripheral fleets. China and Germany exhibit the fastest program formalization, compressing the unmanaged retail channel for business-grade SKUs.
Headsets for PC Market Segmentation
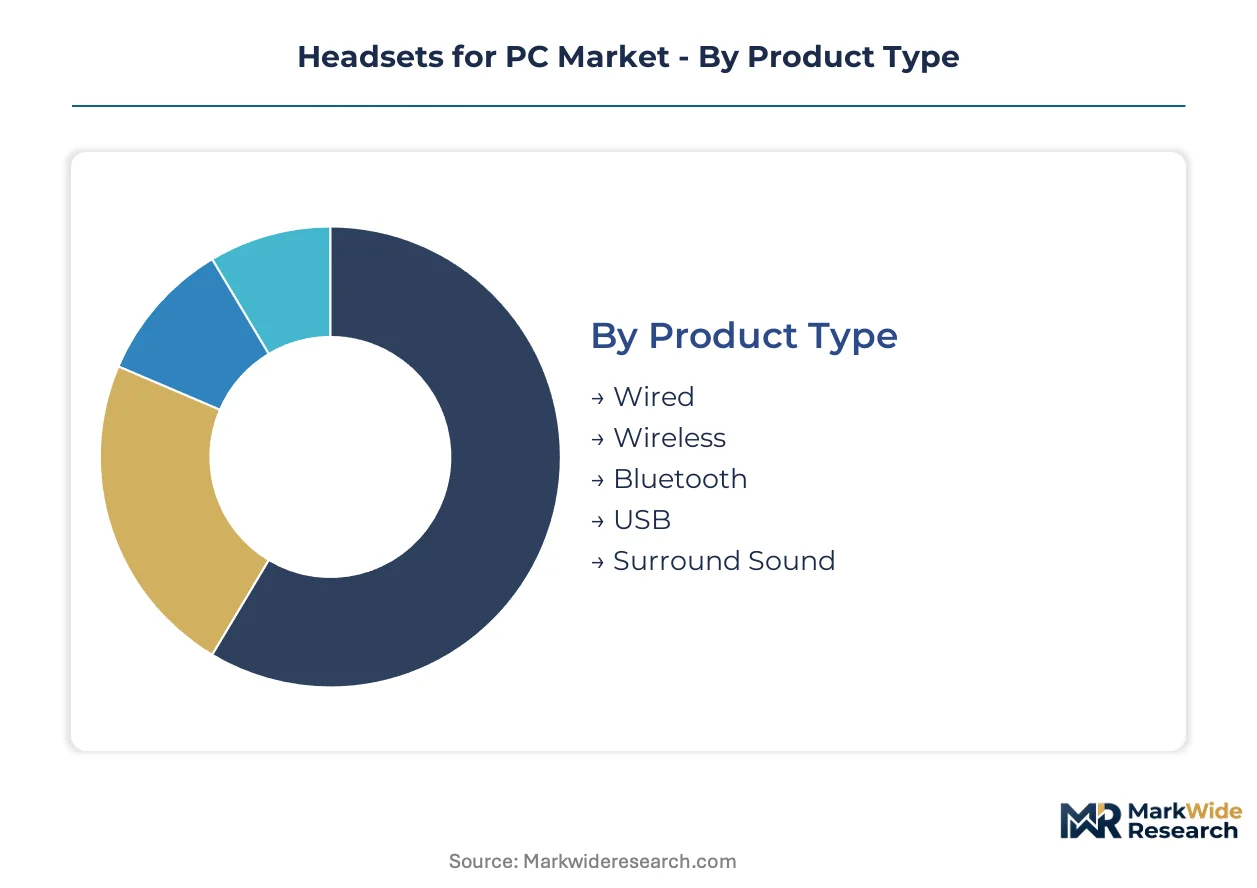
PC headset purchasing cycles vary dramatically across use cases. Tournament-grade wired units face replacement pressure from wireless latency improvements, while enterprise fleet deployments refresh on predictable IT budget cycles.
Product Type:
Wired configurations turn over slowest among enthusiast holdouts, while Bluetooth variants face the shortest replacement windows as codec generations advance.
- Wired:USB-C and 3.5 mm analog configurations deliver zero-latency signal transmission for competitive gaming. Demand concentrates in South Korea and Germany where esports tournament infrastructure mandates tethered connectivity for regulatory compliance. FCC equipment authorization timelines compress launch windows for wireless alternatives, extending wired SKU relevance.
- Wireless:2.4 GHz dongle protocols with proprietary compression stacks now achieve sub-20ms latency. China's domestic gaming cafés sustain bulk procurement of wireless surround-sound units as venue operators prioritize cable-free player mobility. LE Audio protocol maturation is restructuring upgrade cycles across European retail channels.
- Bluetooth:Native motherboard integration eliminates dongle dependency for casual users. Battery chemistry selection determines EU Green Deal market access eligibility.
- USB:Digital audio stacks with firmware-upgradeable DSP dominate enterprise procurement. IT departments in Germany and China favor certified Teams and Zoom device programs.
- Surround Sound:Virtual 7.1 spatial processing requires dedicated driver tuning per game engine. Game developers optimizing directional accuracy algorithms expand the addressable base beyond competitive segments.
Wired configurations dominate installed base. Wireless is where expansion concentrates.
Technology:
Cost tiers separate professional-grade active cancellation from entry-level passive isolation, with virtual spatial audio commanding premium positioning.
- Active Noise Cancellation:Hybrid feedforward-feedback architectures with dedicated ANC silicon target enterprise distributed workforces. RoHS solder alloy reformulation pressures PCB assembly yields for microphone array integration.
- Passive Noise Isolation:Memory foam ear cushion density and clamping force geometry determine attenuation performance. EU REACH directive restrictions on restricted substances accelerate material innovation for compliant manufacturers.
- Virtual 7.1:HRTF-based spatial rendering with head-tracking compatibility spans PC and console ecosystems. Dual-connectivity architectures capture living-room gaming migration.
- Stereo:Neodymium driver assembly depends on rare earth magnet processing concentrated in China. Cost volatility exposes margin compression risk for premium driver units.
- Bone Conduction:Transducer placement at temporal bone bypasses ear canal occlusion for situational awareness use cases. Niche positioning limits volume scale.
Passive isolation dominates installed base. Active cancellation is climbing the fastest.
Application:
Volume concentrates in gaming, though remote work formalization is displacing ad-hoc consumer purchases with managed peripheral fleets.
- Gaming:Spatial audio engine optimization for directional accuracy pulls multi-channel specifications into mainstream SKU tiers. Twitch and YouTube streamers intensify live broadcasting requirements for broadcast-grade microphone arrays.
- Remote Work:Certified device programs consolidate voice communication hardware procurement around Teams and Zoom ecosystems. IT departments in China and Germany exhibit the fastest program formalization.
- Multimedia:Immersive playback consumption benefits from virtual 7.1 hardening across game engines. Frequency response tuning emphasizes low-end extension for cinematic content.
- Online Learning:Cost-optimized stereo configurations with basic boom microphones address student budget constraints. Institutional bulk procurement in India favors durability over feature depth.
- Communication:Cardioid polar patterns with noise suppression algorithms target open-office environments. Firmware development resources strain under legacy 3.5 mm analog compatibility burdens.
Gaming dominates installed base. Remote work is gaining share fastest.
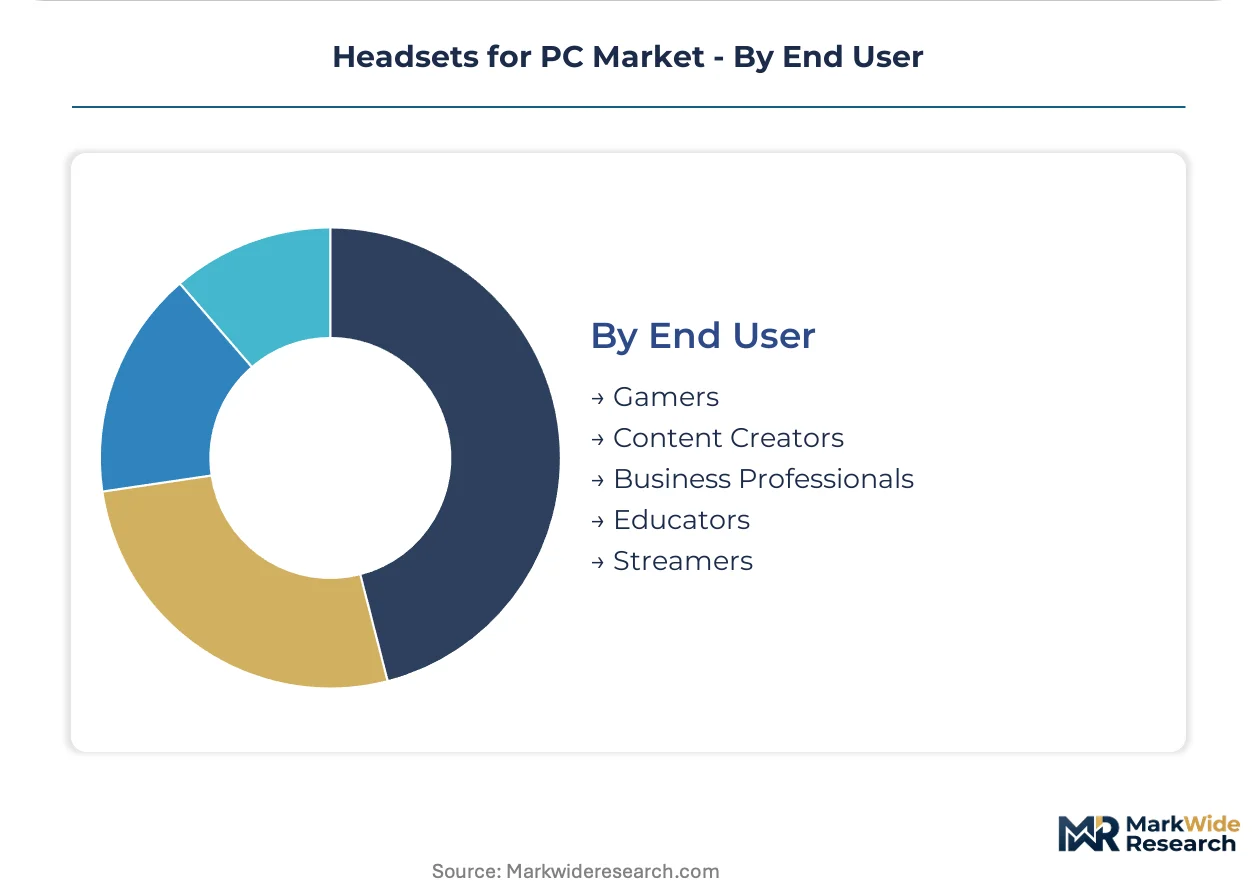
End User:
Customer type determines margin structure, with content creators and streamers driving premium tier specification inflation.
- Gamers:Competitive and casual segments split on latency tolerance versus convenience priorities. Tournament-grade buyers demand zero-lag signal transmission through USB-C tethering.
- Content Creators:Multi-channel audio and broadcast-grade microphone specifications define professional workflows. RGB-integrated designs with proprietary software ecosystems anchor competitive differentiation.
- Business Professionals:Enterprise device program certification compresses unmanaged retail channel access. Ecodesign energy-consumption benchmarks force trade-offs between wireless endurance and miniaturization.
- Educators:Durability and basic intelligibility supersede spatial audio or aesthetic features. Institutional procurement cycles lag consumer replacement patterns.
- Streamers:Live broadcasting infrastructure requirements intensify across Twitch and YouTube platforms. Console-crossover bridge designs occupy unique positioning between PC and living-room ecosystems.
Gamers dominate installed base. Streamers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium driver assembly concentrates processing capacity in China, exposing cost volatility for premium headset units worldwide. Manufacturing clusters in Shenzhen and Dongguan feed peripheral supply chains across North America and Europe. Regulatory fragmentation across major demand centers now conditions market access eligibility.
United States
Tournament-grade wired configurations dominate esports infrastructure where zero-latency transmission remains mandatory. FCC equipment authorization timelines compress product launch windows for wireless alternatives. Austin and Los Angeles anchor content creator demand for broadcast-grade microphone arrays serving Twitch and YouTube streamers.
Germany
Enterprise IT departments formalize peripheral fleet procurement around certified Teams and Zoom device programs. RoHS solder alloy reformulation pressures PCB assembly yields for cable termination and driver integration. Berlin and Munich concentrate gaming café deployment of surround-sound units for venue-based esports leagues.
China
Domestic esports leagues and PC gaming cafés sustain bulk procurement of wireless surround-sound configurations. MIIT radio-frequency certification governs 2.4 GHz dongle protocol deployment for peripheral OEMs. Dongguan and Shenzhen manufacturing corridors supply driver assemblies and wireless components to global peripheral brands.
South Korea
Esports tournament infrastructure mandates tethered USB-C connectivity for regulatory compliance in competitive gaming. National broadcast standards shape microphone array specifications for streaming professionals. Seoul anchors the fastest replacement cycles for latency-sensitive peripheral upgrades.
United Kingdom
Enterprise distributed workforces displace ad-hoc consumer purchases with managed peripheral fleets. CE marking and REACH substance restrictions accelerate material innovation for ear cushion compliance. London concentrates financial services procurement of certified communication hardware.
Headsets for PC Market Competitive Landscape
Specialist gaming peripheral manufacturers and diversified consumer electronics conglomerates split the market along specialization-versus-scale axes. The vendor base concentrates around three strategic archetypes: RGB-integrated gaming specialists, Swiss-engineered premium audio engineers, and console-crossover bridge designers. Capacity expansion in Dongguan corridor facilities and strategic partnerships for LE Audio protocol licensing dominate competitive maneuvering.
Within the gaming-specialist tier, Razer Inc. and Corsair Gaming Inc. exemplify deep software ecosystem integration. Logitech International SA represents the Swiss-engineered premium positioning archetype. Turtle Beach Corporation anchors the console-crossover bridge segment between PC and living-room ecosystems.
| Leading Market Players |
|---|
| Razer Inc. |
| Logitech International SA |
| Corsair Gaming Inc. |
| HyperX (HP Inc.) |
| SteelSeries ApS |
| Sony Interactive Entertainment |
| Turtle Beach Corporation |
| Astro Gaming |
| Audeze LLC |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen wireless component foundries is compressing supplier margins while amplifying bargaining power for peripheral OEMs sourcing 2.4 GHz transceiver modules. This utilization dynamic forces contract manufacturers to absorb FCC pre-certification costs and extend payment terms, reshaping procurement economics across premium and mass-market tiers.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across European distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade microphone arrays from basic stereo configurations, with certification grade and volume scale as primary differentiation drivers. Cost compression in the standard tier is intensifying because RoHS solder alloy reformulation has raised PCB assembly yields. Enterprise fleet buyers exhibit lowest price sensitivity due to managed procurement programs, while student segments in online learning drive economy-tier volume.
Supply Chain Analysis
Extended payment terms from Dongguan assembly facilities now stretch to 90 days for qualified peripheral OEMs, reflecting liquidity stress in the manufacturing corridor. Neodymium magnet processing draws from China, with secondary sourcing from Vietnam and Malaysia for cable insulation compounds. Single-source vulnerability concentrates in MIIT-certified 2.4 GHz module suppliers. Distribution runs through direct-to-retail channels for gaming specialists and IT reseller networks for enterprise fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LE Audio protocol maturation constitutes a technological inflection disrupting legacy dongle architectures and compressing replacement cycles across wireless segments.
For Market Incumbents: Pre-empt proprietary protocol obsolescence by integrating native Bluetooth LE Audio stacks alongside existing 2.4 GHz dongle alternatives. Anchor backward integration into Dongguan battery management IC sourcing to defend margins against power silicon cost volatility. Certification investment in EU Green Deal ecodesign benchmarks locks out mid-tier competitors from European retail placement. For New Entrants and Emerging Players: India's institutional online learning procurement represents the most penetrable entry point for cost-optimized stereo configurations with durability-focused engineering. China's PC gaming café bulk procurement contracts offer volume anchor positioning for surround-sound units with venue-grade cable reinforcement. Direct-to-venue sales teams bypass established retail channel gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise fleet management providers with certified Teams and Zoom device programs. Long-term viability over a multi-year horizon favors acquisition targets with captive Dongguan manufacturing relationships and MIIT radio-frequency certification capabilities. Monitor LE Audio adoption velocity in European retail channels as the critical inflection indicator for protocol architecture dominance.| Strategic Initiative | Industry Significance |
|---|---|
| LE Audio Protocol Integration | Native Bluetooth LE Audio migration from mobile-first deployment into PC peripheral ecosystems restructures upgrade cycles. |
| EU Green Deal Ecodesign Compliance | Battery chemistry selection and power management IC integration now determine market access eligibility for European consumers. |
| Enterprise Fleet Certification | Certified Teams and Zoom device programs in China and Germany compress unmanaged retail channel access for business-grade SKUs. |
| Console-Crossover Bridge Design | Dual-connectivity architectures spanning PC and console ecosystems capture living-room gaming migration. |
| Dongguan Capacity Partnership | Strategic alliances for wireless component supply secure volume anchor contracts from domestic esports leagues. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with peripheral OEM product managers, esports venue procurement directors, enterprise IT fleet managers, and gaming café chain operators. Secondary validation drew from FCC equipment authorization databases, MIIT radio-frequency certification registries, EU REACH substance restriction updates, and SEC filings of listed peripheral manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across connectivity architecture, technology tier, and end-user segmentation dimensions.
Calibration against historical replacement cycle data and announced product launch timelines anchored projections across the analysis window. Segmentation dimensions modeled include product type, technology tier, application use case, and end-user archetype. CAGRs were derived from slope analysis of adoption curves for wireless protocols and enterprise fleet formalization patterns. Spatial audio engine optimization velocity and LE Audio codec penetration served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, rare earth magnet pricing, or trade tariff schedules would shift the trajectory. Forecasts reflect documented assumptions about protocol adoption timelines and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market