
 Foldable Phone Market | 2026-2036
Foldable Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Phone Market Analysis
Ultra-thin glass substrate engineering is tilting the foldable phone technology stack toward higher durability and slimmer hinge mechanisms. Samsung Electronics leverages its vertically integrated display division to sustain cost advantages in clamshell production. Huawei Technologies anchors premium flip-phone positioning through proprietary hinge patents and domestic supply chain control. Xiaomi competes aggressively on price while extending its offline retail footprint across tier-one Chinese cities.
A foldable phone incorporates a flexible display panel, typically OLED-based, mounted on a precision-engineered hinge mechanism that permits repeated bending cycles exceeding hundreds of thousands of operations; its primary commercial purpose is to deliver expanded screen real estate within a pocketable form factor. The clamshell segment dominates volume shipments due to lower price points and mainstream consumer accessibility, while the rollable category occupies the frontier of engineering investment with limited commercial traction. OLED technology leads the display stack with mature supply chains, whereas Mini-LED remains nascent in this application with concentrated R&D at select panel makers.
The US FCC governs electromagnetic emissions and device certification requirements that foldable phones must satisfy before market entry, while China's SAMR enforces national standard GB protocols for battery safety and product quality labeling. South Korea's METI-equivalent technical regulations and the EU's RoHS and REACH frameworks restrict hazardous substances in display manufacturing, directly shaping material selection and supplier qualification timelines. Stakeholders must monitor how divergent e-waste and right-to-repair mandates across these jurisdictions will force modular design investments and alter after-service economics.
Market Dynamics
Ultra-thin glass substrate engineering is collapsing the durability-cost trade-off that previously constrained foldable phone mass adoption, forcing manufacturers to reconfigure hinge supply chains and assembly processes.
Growth Catalysts
- OLED Display Maturity:Panel yield improvements at Korean and Chinese fabs are lowering unit economics for flexible substrates. Enterprise procurement of clamshell devices for field sales teams is accelerating replacement cycles.
- China's Dual Carbon Goals:MIIT mandates for greener display production are redirecting capital toward low-temperature manufacturing processes. This regulatory pressure is compressing qualification timelines for domestic suppliers.
- South Korean Consumer Preference:Domestic demand concentration supports Samsung Electronics' captive supply chain economics. Local carrier subsidy structures favor premium foldable tiers over conventional flagships.
Market Restraints
- Ultra-Thin Glass Input Costs:Schott AG and Corning control specialized glass draw capacity, creating pricing power asymmetry against downstream assemblers.
- Supply Concentration in South Korea:Display driver IC and polarizer film production clusters in Gyeonggi Province expose the market to single-point geopolitical disruption.
- EU REACH Compliance Burden:Restricted substance lists for display adhesives and hinge lubricants are extending supplier qualification timelines by 8-14 months.
Strategic Opportunities
- India Market Underpenetration:Domestic assembly incentives under PLI schemes are attracting module-level investment from Chinese and Korean panel makers seeking tariff arbitrage.
- Rollable Display Convergence:Sliding mechanism patents from laptop hinge specialists are transferring to phone form factors, enabling new aspect ratio categories.
- Japan METI Carbon Neutrality Roadmap:Subsidies for low-power OLED deposition equipment are creating procurement advantages for manufacturers with Japanese fab partnerships.
Industry Challenges
- Precision Hinge Engineering Talent Scarcity:Mechanical design expertise for sub-2mm tolerance mechanisms concentrates at Korean and Japanese tier-one suppliers, constraining new entrant scaling.
- FCC Certification Timeline Compression:Electromagnetic emissions testing for flexible antenna configurations requires iterative redesign cycles that delay US market entry.
- Patent Thicket Navigation:Proprietary crease-minimization IP held by incumbent display divisions forces licensing negotiations or work-around R&D expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Phone Market |
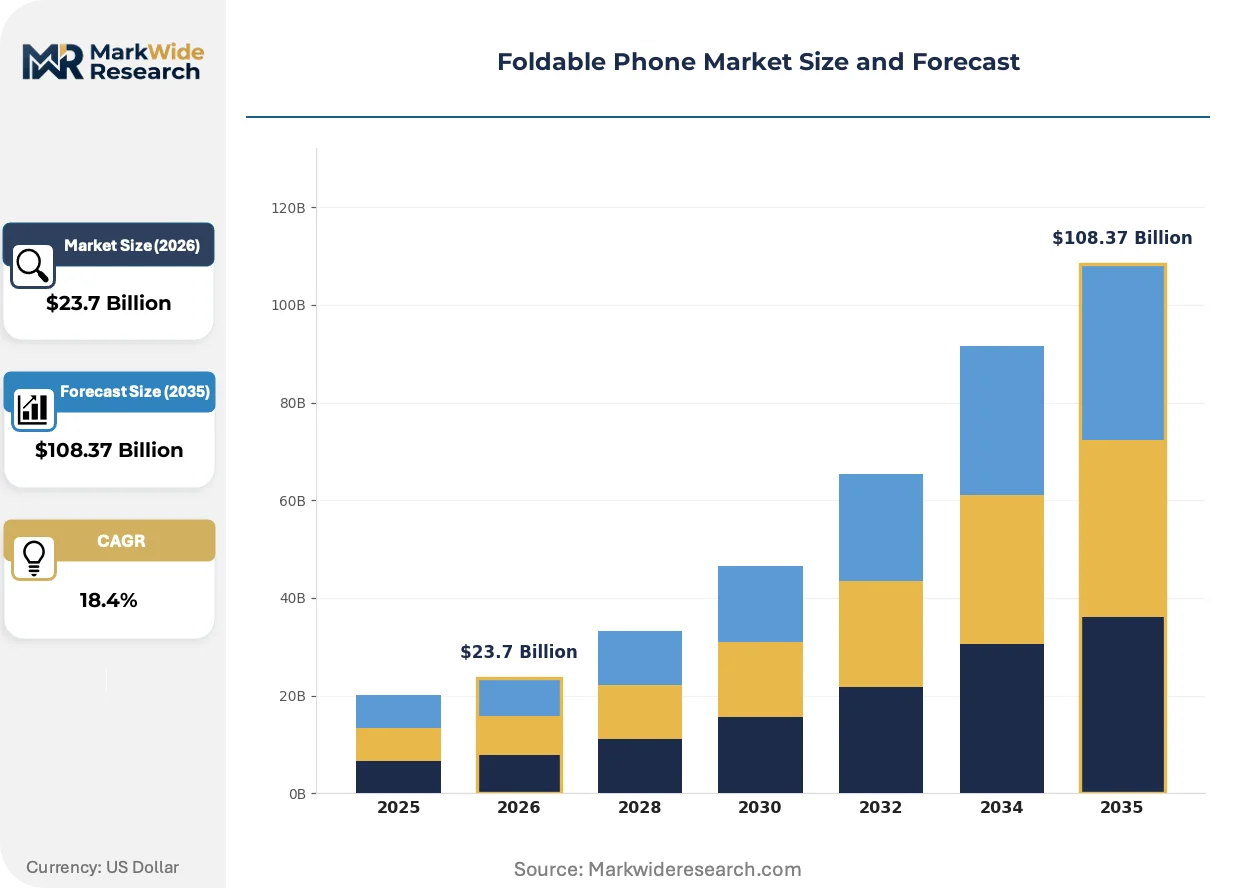
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $108.37 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshell, Flip, Tablet, Rollable Technology: OLED, Mini-LED, LCD, Micro-LED End User: Consumer, Enterprise, Education, Gaming Distribution Channel: Online Retail, Offline Retail, Direct Sales, Resellers |
| Companies Covered | Samsung Electronics Co., Ltd., Huawei Technologies Co., Ltd., Motorola Mobility LLC, Oppo Mobile Telecommunications Corp., Ltd., Xiaomi Corporation, vivo Communication Technology Co., Ltd., Honor Device Co., Ltd., OnePlus Technology (Shenzhen) Co., Ltd., Royale Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Phone Market Emerging Trajectories
Waterfall-shaped display edges and under-panel camera integration are erasing the visual compromises that differentiated early foldable generations from conventional smartphones.
Ultra-thin glass with chemically strengthened zirconia layers is collapsing the gap between foldable screen durability and traditional Gorilla Glass performance. Enterprise fleet buyers are specifying 200,000-cycle hinge ratings as standard procurement criteria. This durability threshold is compressing warranty cost reserves and enabling longer depreciation schedules for corporate device programs.
China's SAMR enforcement of revised GB battery safety protocols is mandating dual-cell isolation architectures in foldable devices. Manufacturers must redesign internal layouts to accommodate separated power cells with independent thermal management. The clamshell segment faces the steepest compliance cost adjustment due to constrained chassis volume.
Carrier-direct bulk purchasing agreements are displacing traditional retail channel distribution for enterprise foldable deployments. IT departments are negotiating three-year refresh cycles with integrated device management and insurance bundles. This procurement consolidation is most visible in South Korea and Japan where corporate subscriber bases exceed consumer prepaid volumes.
Foldable Phone Market Segmentation
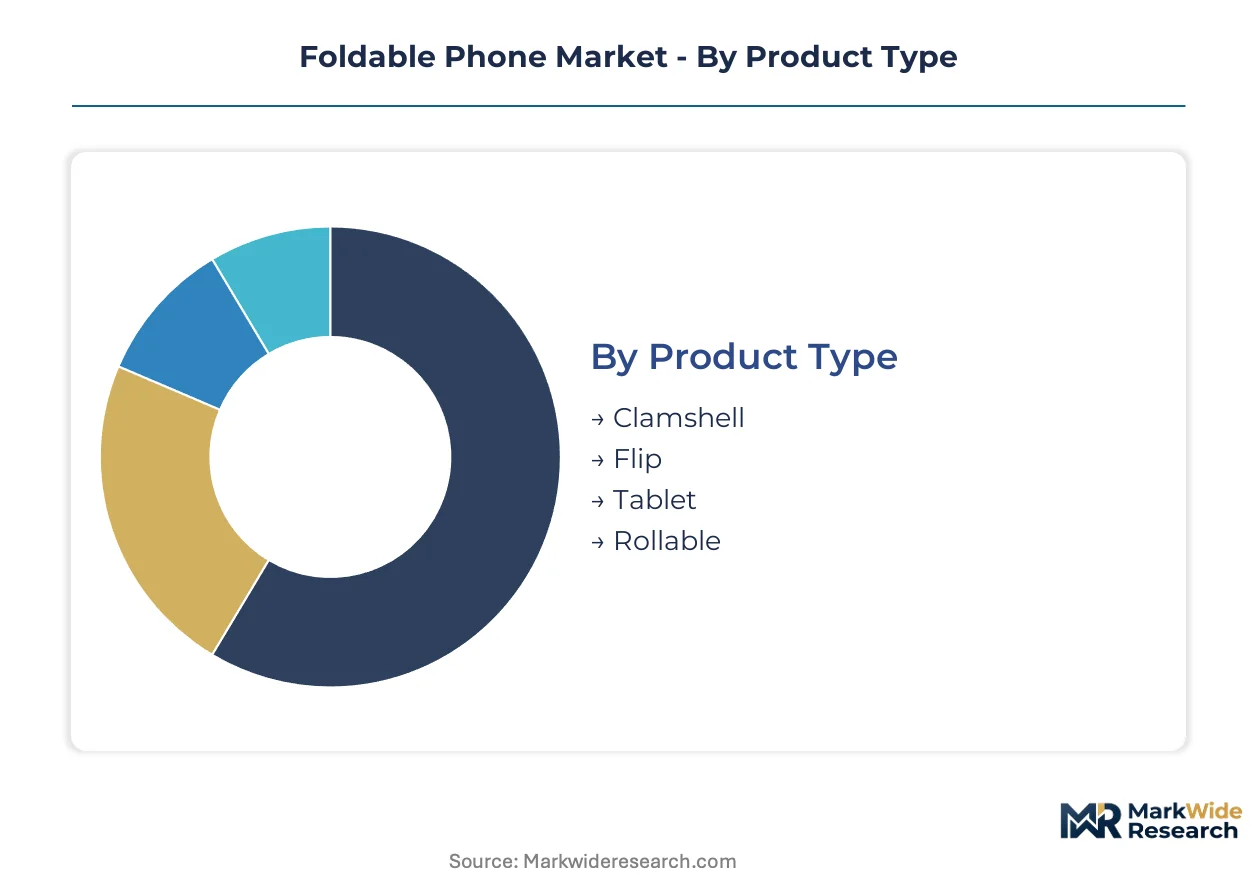
Foldable phone segmentation reveals divergent replacement rhythms across form factors and buyer categories. Enterprise procurement cycles stretch three to four years while consumer clamshell turnover compresses below twenty-four months in carrier-subsidized markets.
Product Type:
Clamshell devices turn inventory fastest through mass-market carrier channels, while rollable prototypes remain captive to engineering labs with undefined commercial horizons.
- Clamshell:Hinge mechanisms fold along a horizontal axis, producing pocketable devices with external cover displays for notification preview. South Korean carrier subsidy structures concentrate volume here, with corporate fleet buyers specifying 200,000-cycle durability ratings as procurement baselines.
- Flip:Vertical folding creates taller aspect ratios when opened, emphasizing one-handed operation and portrait media consumption. Huawei Technologies anchors premium positioning through proprietary waterdrop hinge patents that minimize crease visibility.
- Tablet:Unfolded screen real estate approaches eight inches diagonally, targeting productivity workflows and stylus input. Samsung Electronics dominates this segment through Display Division captive supply of ultra-thin glass substrates.
- Rollable:Motorized extension mechanisms enable variable aspect ratios without folding creases. LG Display and BOE Technology hold concentrated patent positions in sliding panel architectures.
Clamshell dominates installed base. Tablet is where expansion concentrates.
Technology:
Display stack choices stratify sharply by manufacturing maturity and capital intensity, with deposition equipment requirements separating feasible production from experimental lines.
- OLED:Organic emissive layers deposited on polyimide substrates enable true flexible panels with sub-millimeter bend radii. Korean and Chinese fabs in Gyeonggi Province and Suzhou cluster supply the entire commercial foldable base.
- Mini-LED:Local dimming zones improve contrast on rigid backplanes but face mechanical reliability challenges under repeated flexing. Apple supplier Luxshare Precision holds concentrated R&D investment in this hybrid approach.
- LCD:Liquid crystal orientation requires rigid glass sandwiches, limiting application to fixed-curve or non-flexing implementations. Cost advantages persist only in entry-tier markets where form factor novelty outweighs true folding function.
- Micro-LED:Inorganic chiplet transfer enables theoretical durability advantages but pixel density yields remain below commercial thresholds. PlayNitride and VueReal lead transfer equipment development for eventual phone-scale production.
OLED commands current production volume. Micro-LED carries the steepest expansion trajectory once transfer yields mature.
End User:
Buyer category segmentation maps directly to price tolerance and durability specification stringency, with enterprise procurement teams extracting warranty concessions unavailable to consumer channels.
- Consumer:Individual purchasers prioritize aesthetic differentiation and social signaling value in flagship-tier acquisition. Chinese tier-one city retail footprints from Xiaomi and OPPO concentrate distribution here.
- Enterprise:IT departments negotiate bulk agreements with integrated device management and three-year refresh cycles. Field sales team deployments in Japan and South Korea drive clamshell volume through carrier-direct structures.
- Education:Institutional procurement emphasizes ruggedized hinges and extended warranty terms for student deployment scenarios. K-12 budgets constrain penetration to donation-funded pilot programs.
- Gaming:Enthusiast buyers demand high-refresh-rate panels and thermal headroom for sustained GPU load. ASUS ROG and REDMAGIC target this niche with active cooling integration.
Consumer absorbs mainstream volume. Enterprise is climbing the fastest as fleet refresh cycles institutionalize.
Distribution Channel:
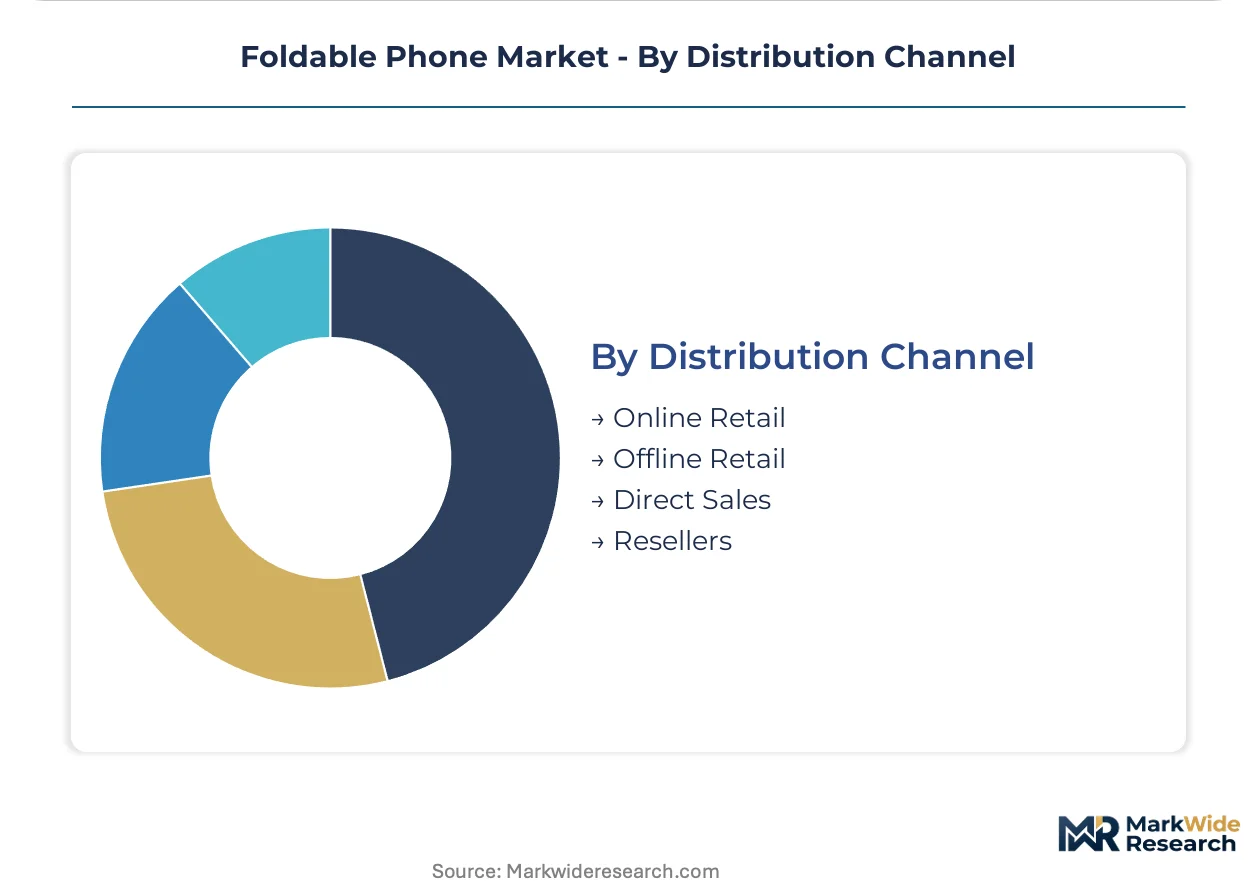
Channel mix reflects geographic retail infrastructure maturity and carrier market structure, with direct sales penetration correlating to enterprise buyer concentration.
- Online Retail:E-commerce platforms enable specification comparison and launch-window inventory access without physical inspection. Amazon and JD.com dominate premium electronics traffic in their respective home markets.
- Offline Retail:Flagship stores and carrier outlets provide hands-on hinge testing and immediate activation services. Samsung Experience stores anchor brand presence in Indian metro markets.
- Direct Sales:Manufacturer-controlled channels capture enterprise procurement and enthusiast early-adopter segments. Apple and Samsung deploy dedicated B2B sales teams for fleet negotiations.
- Resellers:Authorized distributors extend geographic reach where direct retail economics fail. Regional electronics chains in Southeast Asia rely on this structure for inventory financing.
Offline retail holds installed base depth. Online channels are gaining share fastest as logistics infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean display fabs export flexible OLED substrates to assembly plants in Vietnam and India, creating a triangular trade flow that concentrates component value-add in East Asia while final device integration shifts toward tariff-advantaged manufacturing zones.
South Korea
Samsung Electronics' Display Division anchors domestic demand for clamshell devices through carrier-direct enterprise procurement. METI-equivalent technical regulations from the Korean Agency for Technology and Standards enforce battery isolation standards that shape internal chassis layouts. Gyeonggi Province clusters display driver IC and polarizer film production, exposing supply chains to concentrated geopolitical risk.
China
Huawei Technologies and Xiaomi drive premium flip-phone volume through tier-one city retail expansion and proprietary hinge patent portfolios. MIIT mandates for greener display production under dual carbon goals compress supplier qualification timelines for low-temperature manufacturing processes. Suzhou and Shenzhen host the principal flexible OLED fab clusters serving domestic brands.
United States
Enterprise IT departments accelerate clamshell procurement for field sales teams, institutionalizing three-year refresh cycles with integrated device management. FCC electromagnetic emissions certification requirements for flexible antenna configurations force iterative redesign cycles that delay market entry. California-based technology buyers concentrate early-adopter demand for tablet-form-factor productivity devices.
Japan
Corporate subscriber bases exceed consumer prepaid volumes, driving carrier-direct bulk purchasing agreements for enterprise foldable deployments. METI carbon neutrality roadmap subsidies for low-power OLED deposition equipment create procurement advantages for manufacturers with Japanese fab partnerships. Tokyo-Osaka corridor concentrates precision mechanical engineering talent for sub-2mm tolerance hinge mechanisms.
India
Domestic assembly incentives under PLI schemes attract module-level investment from Chinese and Korean panel makers seeking tariff arbitrage against fully-imported devices. BIS certification requirements for battery safety and electromagnetic compatibility extend product launch timelines. Maharashtra and Karnataka host emerging final assembly capacity for South Korean brand subsidiaries.
Foldable Phone Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated display divisions and captive hinge manufacturing capabilities. Korean and Chinese conglomerates with in-house panel production control cost structures at volume, while specialized mechanical engineering houses retain pricing power in precision sub-assemblies. Three strategic archetypes dominate: integrated electronics conglomerates with display divisions, dedicated mobile device specialists with proprietary hinge IP, and emerging challengers competing on price through retail footprint expansion. Capacity expansion in Vietnam and India and technology licensing for crease-minimization algorithms constitute the dominant competitive moves.
Within the integrated conglomerate tier, Samsung Electronics Co., Ltd. and Huawei Technologies Co., Ltd. exemplify the archetype of companies controlling upstream display supply and downstream brand distribution simultaneously. Xiaomi Corporation occupies a distinct position as a price-competitive challenger extending offline retail presence. These three entities collectively represent the spectrum from captive supply chain economics to retail-driven market penetration strategies.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| Motorola Mobility LLC |
| Oppo Mobile Telecommunications Corp., Ltd. |
| Xiaomi Corporation |
| vivo Communication Technology Co., Ltd. |
| Honor Device Co., Ltd. |
| OnePlus Technology (Shenzhen) Co., Ltd. |
| Royale Corporation |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Schott AG and Corning for ultra-thin glass draw capacity determines both premium-tier pricing spreads and the triangular supply chain shape linking Korean display fabs to Vietnamese and Indian assembly plants. Tariff exposure on fully-imported devices compresses margin structures for non-integrated assemblers while rewarding module-level localization strategies.
Pricing Analysis
Current-generation clamshell devices command substantial premiums over prior-generation foldables with plastic substrates, while next-generation rollable prototypes occupy undefined pricing territories pending commercialization. Three-tier pricing structure across premium, standard, and economy levels separates Samsung and Huawei flagship tiers from Xiaomi mid-market positioning and entry-level LCD alternatives. Cost compression in the clamshell segment intensifies as Chinese fabs improve OLED yields and erode Korean cost advantages. Enterprise buyers exhibit the lowest price sensitivity due to three-year depreciation schedules and bundled device management, while consumer retail channels in Indian metro markets show acute responsiveness to subsidy adjustments.
Supply Chain Analysis
Ultra-thin glass substrate feedstock draws from specialized melt facilities in Germany and the United States, with flexible OLED panel production anchored in South Korea and China. Hinge mechanism sub-assemblies rely on precision stamping capacity in Japan and Taiwan, while final device integration concentrates in Vietnam and India under PLI incentives. Single-source vulnerability in Gyeonggi Province display driver IC clusters exposes the entire assembly network to geopolitical disruption. Distribution runs through carrier-direct bulk agreements for enterprise procurement, with offline retail flagship stores capturing consumer tactile evaluation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement consolidation through carrier-direct bulk agreements has shifted buyer power toward IT departments negotiating three-year refresh cycles with integrated warranty bundles. This concentration fragments pricing power away from retail channel intermediaries.
For Market Incumbents: Pre-empt margin erosion from Chinese OLED yield improvements by securing captive ultra-thin glass supply through long-term offtake agreements with Schott AG or Corning. Deepen backward integration into hinge mechanism production to protect proprietary crease-minimization IP against licensing demands from emerging competitors. Defensive patent thickets around waterdrop hinge architectures constrain new entrant design freedom. For New Entrants and Emerging Players: India's underpenetrated enterprise segment represents the most penetrable entry point for module-level assemblers leveraging PLI tariff arbitrage against fully-imported Korean devices. Tier-two Chinese city retail footprints offer white-space expansion for price-competitive clamshell alternatives to Xiaomi and OPPO. Direct sales teams targeting field sales fleet managers bypass saturated consumer channel competition. For Investors and Strategic Acquirers: The market sits at a manufacturing-scale phase that favors integrated conglomerates with captive display divisions over pure-brand assemblers. Long-term viability over the next decade hinges on controlling upstream substrate supply and precision mechanical engineering talent pools concentrated in East Asia. Acquisition targets should demonstrate Japanese or Korean hinge patent portfolios and established carrier-direct enterprise relationships. The signal to watch is OLED deposition equipment order flows from Chinese fabs as inflection indicator for yield-driven cost compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Crease-Minimization Patent Licensing | Proprietary hinge IP from Samsung Display and Huawei generates royalty revenue streams from second-tier assemblers. |
| Module-Level Localization in India | PLI scheme incentives attract Chinese and Korean panel makers to Maharashtra and Karnataka assembly zones. |
| Ultra-Thin Glass Supply Agreement | Long-term offtake contracts with Schott AG or Corning secure input cost predictability for volume production. |
| Enterprise Fleet Management Integration | Three-year refresh cycles with bundled device management and insurance capture sticky corporate subscriber bases. |
| Low-Temperature Manufacturing Transition | MIIT dual carbon mandates redirect capital toward greener deposition processes qualifying domestic Chinese suppliers. |
Methodological Framework
A standing panel of display division executives, hinge mechanism engineering directors, carrier procurement managers, and enterprise IT fleet administrators provided ongoing calibration against secondary validation from SEC filings, MIIT regulatory disclosures, customs trade databases, and OLED equipment capex announcements. Primary interviews with Samsung Display, BOE Technology, and tier-one hinge suppliers in Japan and Taiwan supplied capacity and yield assumptions. Bottom-up assembly volume estimates triangulated against top-down display substrate output figures.
Scenario-bracketing around OLED yield trajectories, tariff regime stability, and enterprise procurement cycle lengths structured the analytical framework across the projection horizon. Segmentation dimensions modeled include form factor category, display technology stack, end-user archetype, and regional regulatory cluster. CAGRs derived from unit economics trajectories incorporating substrate cost curves and depreciation schedules for deposition equipment. Industry-specific forecast inputs encompassed carrier subsidy structures in South Korea and Japan, plus BIS certification timeline assumptions for Indian market entry.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices, semiconductor equipment capex cycles, or cross-border tariff rates would shift the trajectory substantially. Forecasts reflect documented assumptions regarding yield improvement timelines and regulatory enforcement intensity. Cross-checking against display equipment order backlogs and carrier-reported device activation data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
Advanced Baby Monitors Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Android TV Box Market