
 Baby Monitor Market | 2026-2036
Baby Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Monitor Market Intelligence
FCC Part 15 is repositioning the cost-of-entry calculus for baby monitor manufacturers by mandating stricter electromagnetic interference testing and labeling protocols. VTech Communications leverages its vertically integrated manufacturing base in Dongguan to sustain cost leadership across audio and video categories. Owlet Baby Care differentiates through FDA-cleared pulse oximetry integration, while Nanit dominates the computer-vision segment with breathing-wear analytics.
A baby monitor is an electronic surveillance device comprising a transmitter unit with microphone and camera sensors and a receiver unit with display or audio output, operating on radio frequencies between 1.9 GHz and 2.4 GHz or via Internet Protocol networks. Its primary commercial purpose is to enable remote observation of infant safety parameters including sound, video, movement, and vital signs. Smart monitors represent the fastest-expanding product type as parents shift from passive listening to predictive health analytics. Wi-Fi connectivity captures the highest margin pool due to recurring subscription revenue for cloud storage and AI-generated sleep reports, while DECT retains share among privacy-conscious buyers seeking closed-network operation.
The FDA regulates wearable monitors with medical-grade biometrics under 510(k) clearance pathways, while the Consumer Product Safety Commission enforces cord-safety standards to prevent strangulation hazards. ETSI standards in Europe and MIC radio law in Japan create divergent certification burdens that fragment go-to-market timelines. Stakeholders must monitor whether emerging AI Act risk classifications in Europe will reclassify predictive health algorithms as high-risk medical software, triggering conformity assessment requirements that reshape competitive positioning.
Market Dynamics
Millennial parents are demanding predictive health analytics over passive monitoring, forcing manufacturers to integrate computer-vision algorithms and biometric sensors into nursery ecosystems while navigating fragmented electromagnetic compliance regimes across selling jurisdictions.
Growth Catalysts
- FCC Part 15 certification:Stricter electromagnetic interference testing is filtering out low-quality imports and creating premium positioning for compliant manufacturers in the United States market.
- Wi-Fi protocol adoption:Internet Protocol connectivity enables recurring subscription revenue streams through cloud storage and AI-generated sleep analytics.
- Computer-vision integration:Breathing-wear analytics and movement detection algorithms are expanding addressable use cases beyond basic audio-visual surveillance.
Market Restraints
- Semiconductor supply concentration:Radio frequency chip fabrication concentrates in East Asian foundries, exposing manufacturers to input volatility and allocation constraints.
- DECT frequency limitations:Digital Enhanced Cordless Telecommunications protocols lack bandwidth for high-resolution video transmission, capping functionality for privacy-focused closed-network buyers.
- ETSI certification burden:European electromagnetic compatibility testing adds six to nine months to product launch timelines and requires redundant engineering for multi-region portfolios.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting contract assembly investments to serve price-sensitive South Asian demand.
- AI Act risk classification:Pending European Union algorithmic regulation may reclassify predictive health software as high-risk, creating first-mover advantage for pre-certified medical-grade platforms.
- Pediatric telehealth convergence:Integration with remote consultation platforms is opening enterprise sales channels to healthcare systems and employer benefit programs.
Industry Challenges
- Embedded systems engineering talent:Shortage of firmware developers with radio frequency optimization expertise is extending development cycles and inflating compensation costs.
- 510(k) clearance timelines:FDA wearable device pathways for pulse oximetry integration require clinical validation studies that compress margin structures for smaller competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Monitor Market |
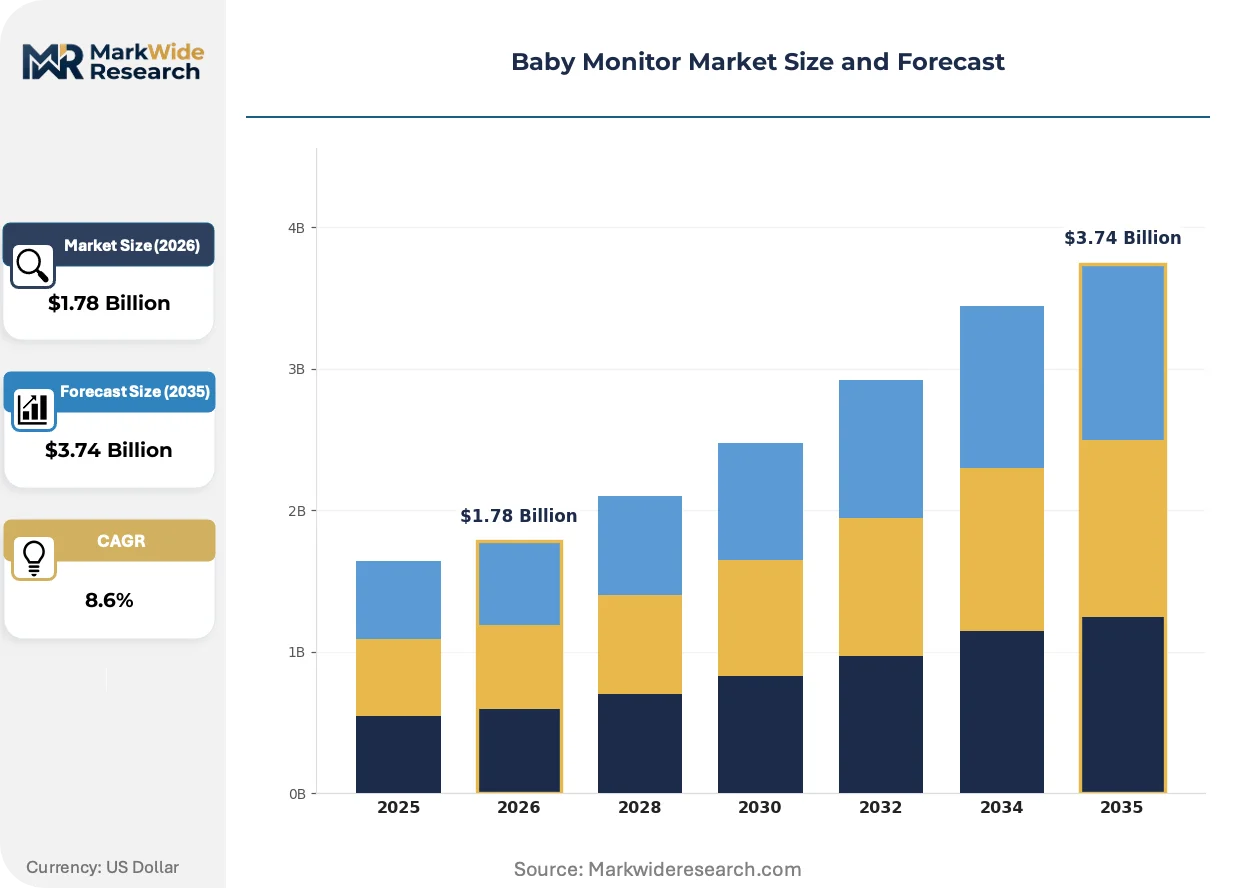
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.74 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Monitor, Video Monitor, Smart Monitor, Wearable Monitor Connectivity: Wi-Fi, Bluetooth, DECT, Wired End User: Parents, Caregivers, Hospitals, Daycares Features: Temperature Monitoring, Night Vision, Two-Way Audio, Motion Detection |
| Companies Covered | VTech Communications, Summer Infant, Angelcare Monitors, Owlet Baby Care, Motorola, Philips, Arlo Technologies, Nanit, Infant Optics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Monitor Market Strategic Shifts & Innovations
Sensor fusion and edge computing are redefining what parents expect from nursery surveillance, shifting competitive advantage from hardware specifications to predictive algorithm accuracy and data interoperability with pediatric health platforms.
Multi-modal sensing architectures are unifying audio, video, radar, and capacitive touch data streams into single-chip edge processors. Premium smart monitor buyers in the United States and Western Europe are adopting these unified platforms at replacement-cycle intervals of eighteen to twenty-four months. This convergence is compressing standalone sensor supplier margins while rewarding semiconductor houses with integrated system-on-chip portfolios.
EU AI Act risk-tier definitions are forcing algorithm documentation and conformity assessment for breathing-pattern prediction software. Manufacturers serving European markets must now maintain technical files demonstrating bias testing and clinical validation for computer-vision health claims. Pediatric telehealth integrators and hospital procurement departments are prioritizing suppliers with pre-submitted high-risk software certifications.
Millennial buyers are abandoning retail big-box channels for direct-to-consumer subscription bundles that bundle hardware with pediatric sleep coaching and developmental milestone tracking. Amazon and specialty baby boutiques are losing share to manufacturer-owned e-commerce portals with recurring revenue attachment rates above forty percent in coastal United States metropolitan markets. This channel rotation is forcing legacy distributors to unbundle after-sales service or exit the category entirely.
Baby Monitor Market Segmentation
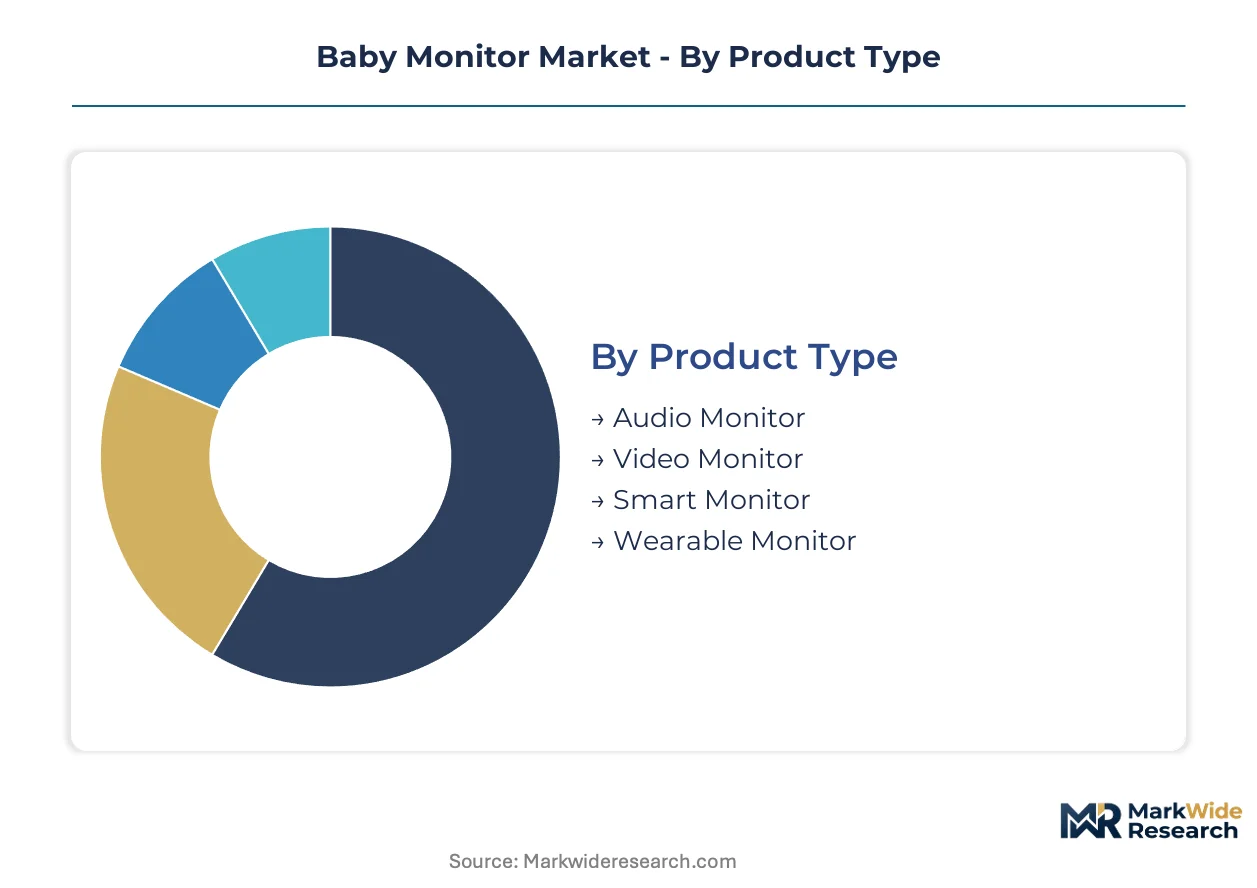
Baby monitor segmentation tracks how millennial parents upgrade nursery technology every eighteen to twenty-four months. Product type and connectivity choices reveal divergent margin pools between subscription-driven smart platforms and privacy-focused closed networks.
Product Type:
Replacement cycles accelerate as parents move from basic surveillance to predictive health analytics, with FDA-cleared biometrics commanding premium positioning.
- Audio Monitor:Single-channel or dual-receiver units transmitting on DECT 1.9 GHz bands with analog or digital modulation. Demand concentrates in price-sensitive secondary bedrooms and grandparent households, constrained by the inability to transmit visual data streams.
- Smart Monitor:Cloud-connected platforms integrating computer-vision algorithms, edge-processed breathing analytics, and pediatric sleep coaching subscriptions. Coastal United States metropolitan buyers drive volume through manufacturer-direct e-commerce portals with recurring revenue attachment above forty percent.
- Video Monitor:Closed-circuit 2.4 GHz or 5 GHz systems with dedicated parent-unit displays and pan-tilt-zoom mechanical housings. European buyers favor these for GDPR-compliant local storage without cloud dependency.
- Wearable Monitor:Sock or band form factors with pulse oximetry, accelerometry, and skin conductance sensors requiring FDA 510(k) clearance for medical-grade biometrics. Owlet's FDA-cleared platform anchors this segment despite compressed margins from clinical validation requirements.
Smart monitors sit at the top of the volume ranking, with wearable monitors climbing the fastest.
Connectivity:
Protocol selection determines whether manufacturers capture recurring software revenue or one-time hardware margins.
- Wi-Fi:Internet Protocol transmission enabling AES-256 encrypted cloud storage, firmware-over-the-air updates, and multi-device streaming to smartphones. United States buyers generate the highest subscription attach rates for AI-generated sleep reports and developmental milestone tracking.
- DECT:Digital Enhanced Cordless Telecommunications operating at 1.9 GHz with frequency-hopping spread spectrum for interference resistance. Privacy-conscious buyers in Germany and France accept limited video bandwidth for closed-network security guarantees.
- Bluetooth:Short-range 2.4 GHz protocol for wearable-to-smartphone pairing with sub-10 meter range constraints. Secondary backup connectivity for travel scenarios where Wi-Fi infrastructure is unreliable.
- Wired:Ethernet or USB-C tethered connections eliminating radio frequency exposure concerns and ensuring zero-latency transmission. Niche demand from electromagnetic hypersensitivity communities and hospital IT departments with strict air-gapping policies.
Wi-Fi captures the highest margin pool, while DECT retains defensive positioning among privacy-focused segments.
End User:
Customer type shapes procurement channels, with institutional buyers demanding enterprise-grade cybersecurity and consumer buyers prioritizing app ecosystem integration.
- Parents:Primary residential purchasers evaluating nursery ecosystems on predictive algorithm accuracy and pediatrician recommendation networks. Direct-to-consumer subscription bundles displace Amazon and specialty retail channels.
- Hospitals:Neonatal intensive care and postpartum wards requiring IEC 60601 medical electrical safety certification and HIPAA-compliant audit trails. Procurement departments prioritize pre-certified platforms with existing health system integrations.
- Caregivers:Extended family and professional nannies utilizing shared-access app permissions and activity logging for parental transparency. Secondary hardware purchasers with lower price elasticity than primary parents.
- Daycares:Multi-child facilities mandating centralized monitoring dashboards with regulatory compliance documentation for state licensing inspections. Volume purchasers negotiating fleet pricing for standardized platform deployments.
Parents dominate absolute volume, with hospitals expanding most quickly through pediatric telehealth convergence.
Features:
Feature bundling determines tiered pricing architecture, with computer-vision capabilities separating premium positioning from commoditized baseline functionality.
- Motion Detection:Passive infrared or radar-based movement sensing with configurable sensitivity thresholds and smartphone push notification delivery. Baseline expectation across all price tiers with diminishing differentiation value.
- Two-Way Audio:Full-duplex speaker-microphone arrays enabling real-time parental voice intervention without physical nursery presence. Table-stakes feature with codec quality separating premium from economy positioning.
- Night Vision:Near-infrared LED illumination with CMOS sensor sensitivity below 0.1 lux for monochrome video capture in unlit nurseries. Computer-vision accuracy for breathing analytics depends on this illumination infrastructure.
- Temperature Monitoring:Integrated thermistor or infrared pyrometer sensors with configurable alert thresholds for overheating or hypothermia risk. Pediatrician-endorsed safety feature driving replacement upgrades from legacy audio-only systems.
Motion detection holds the broadest installed base, with night vision gaining share fastest through computer-vision integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The baby monitor industry traces its commercial origins to the United States, where Zenith Radio Corporation introduced the first wireless nursery intercom in 1937, establishing the product category before Japanese and European manufacturers entered during the 1980s and 1990s.
United States
Millennial parents in coastal metropolitan markets drive replacement cycles toward computer-vision smart monitors with subscription sleep analytics. FCC Part 15 certification requirements filter low-quality imports and elevate compliant domestic brands. San Francisco and Seattle anchor venture-backed nursery technology development, with FDA-cleared wearable biometrics clustering in Salt Lake City.
Germany
Privacy-conscious buyers in Bavaria and Baden-Württemberg favor DECT-based closed-network systems avoiding cloud dependency. ETSI electromagnetic compatibility testing extends product launch timelines by six to nine months. Berlin hosts regulatory compliance consultancies specializing in CE marking and EU AI Act algorithmic risk classification for predictive health software.
China
Dongguan and Shenzhen manufacturing clusters supply radio frequency chipsets and camera modules to global brands while domestic demand concentrates in tier-one cities. MIIT radio transmission regulations govern 2.4 GHz and 5 GHz device certification. Yangtze River Delta contract electronics assemblers capture production-linked incentive schemes for export-oriented manufacturing.
Japan
Tokyo and Osaka metropolitan parents prioritize compact form factors with minimal electromagnetic footprint for small urban nurseries. METI radio law enforcement creates distinct certification pathways from European and North American regimes. Kyushu semiconductor foundries supply specialized image sensors for night-vision camera modules.
India
Maharashtra and Karnataka urban households represent emerging demand as nuclear family structures replace multi-generational childcare. BIS electronics safety standards and TRAI wireless spectrum allocation shape product specifications. Delhi-NCR and Bengaluru electronics manufacturing clusters attract PLI scheme investments for price-sensitive South Asian market assembly.
Baby Monitor Market Key Industry Players
The competitive structure tilts toward vertically integrated electronics specialists with captive radio frequency engineering capabilities. Market concentration remains moderate, with tier-one players commanding premium positioning through FDA-cleared biometrics and computer-vision patents while mid-tier assemblers compete on cost. Three archetypes dominate: vertically integrated manufacturers with Dongguan-based production, medical-grade wearable specialists with 510(k) clearance pathways, and cloud-native software platforms with recurring subscription models. Strategic moves center on backward integration into semiconductor sourcing and portfolio diversification into pediatric telehealth integrations.
Among vertically integrated specialists, VTech Communications exemplifies cost leadership through Dongguan-based manufacturing scale, while Owlet Baby Care anchors the medical-grade wearable tier with FDA-cleared pulse oximetry platforms. Nanit occupies the computer-vision premium position, representing the shift from hardware specifications to predictive algorithm accuracy in coastal United States metropolitan markets.
| Leading Market Players |
|---|
| VTech Communications |
| Summer Infant |
| Angelcare Monitors |
| Owlet Baby Care |
| Motorola |
| Philips |
| Arlo Technologies |
| Nanit |
| Infant Optics |
| Others |
Cost & Logistics Intelligence
FDA-cleared biometrics versus basic audio surveillance bifurcates pricing power and sourcing complexity across the baby monitor landscape. Premium wearable platforms command subscription-anchored revenue models that justify dedicated semiconductor procurement teams, while commodity audio units compete on Dongguan assembly economics with minimal margin buffer.
Pricing Analysis
Bundled subscription services versus unbundled hardware transactions define the dominant pricing split in this market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wearable biometrics from computer-vision smart monitors and basic DECT audio units. Certification grade and cloud service attachment drive price differentiation, with clinical validation requirements compressing margins in the wearable tier. Pricing pressure stems from millennial buyers demanding predictive analytics without proportional willingness to pay upfront premiums. Parents in coastal United States metropolitan markets exhibit lowest price sensitivity, while grandparent households and secondary bedroom purchasers anchor the economy tier.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Rotterdam, and Singapore anchor hub-and-spoke patterns for finished goods fulfillment. Radio frequency chip fabrication concentrates in Taiwan, South Korea, and Japan, with Dongguan and Shenzhen providing camera modules and plastic housings. CMOS image sensors, edge AI processors, and lithium-polymer batteries constitute critical input dependencies. Single-source vulnerability in specialized night-vision sensor supply creates exposure to allocation constraints. Distribution runs through manufacturer-direct e-commerce portals, Amazon marketplace, and specialty baby retail chains with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby monitor market compounds steadily as millennial parents replace nursery technology every eighteen to twenty-four months, creating predictable hardware refresh cycles alongside expanding subscription attach rates.
For Market Incumbents: Anchor defensive positioning through backward integration into radio frequency chip sourcing and captive edge AI processor development. Consolidate channel control by acquiring pediatric sleep coaching platforms and developmental milestone tracking applications. FDA 510(k) clearance timelines threaten smaller wearable competitors, creating acquisition opportunities for compliant platforms. Certification investment in EU AI Act high-risk software conformity assessment separates defensible premium positioning from commoditized hardware.
For New Entrants and Emerging Players: Capture white-space opportunity in India's price-sensitive nuclear family segment through PLI scheme contract assembly partnerships. Target electromagnetic hypersensitivity communities with wired Ethernet solutions and hospital IT departments with air-gapped deployment options. Direct-to-consumer subscription bundles with pediatric telehealth integration offer the most penetrable go-to-market angle against entrenched retail distribution.
For Investors and Strategic Acquirers: Consolidation pressure builds where FDA clearance requirements and EU AI Act algorithmic risk classification create compliance moats too expensive for sub-scale players to cross. Five-to-ten year viability favors platforms with recurring revenue attachment above thirty percent and existing health system procurement relationships. Acquisition target archetype: computer-vision specialists with pre-submitted high-risk software certifications and established pediatrician recommendation networks. Signal to watch: hospital procurement departments mandating IEC 60601 medical electrical safety certification for neonatal intensive care deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Clinical validation requirements compress margins for non-compliant wearable competitors. |
| EU AI Act Conformity Assessment | Algorithm documentation mandates reshape competitive positioning for predictive health software. |
| Pediatric Telehealth Integration | Hospital system partnerships open enterprise sales channels beyond consumer retail. |
| Backward Integration into Semiconductors | Captive supply of edge AI processors insulates against foundry allocation volatility. |
| Direct-to-Consumer Subscription Launch | Manufacturer-owned e-commerce portals capture forty-plus percent recurring revenue attachment. |
Research Approach
Direct dialogue with baby monitor product managers, FCC certification consultants, pediatric telehealth platform executives, and hospital biomedical engineering directors grounded qualitative insights. Secondary validation drew from FDA 510(k) device listings, FCC Part 15 equipment authorization databases, ETSI electromagnetic compatibility test reports, and EU AI Act implementation guidance documents. Bottom-up shipment modeling triangulated against top-down consumer electronics spending patterns.
Bottom-up volume builds aggregated parent-unit and camera-unit shipments across product type, connectivity protocol, and end-user segments over the projection horizon. Segmentation dimensions modeled include hardware form factor, transmission technology, certification tier, and procurement channel. CAGRs derived from replacement cycle velocity analysis and subscription attach rate trajectories. Forecast inputs incorporated semiconductor foundry capacity utilization and pediatric sleep coaching service adoption curves.
Semiconductor supply disruption, regulatory reclassification of predictive algorithms, and channel migration acceleration are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
TV Mirror Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Tablet Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Smart DJ Controller Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Europe Soundbar Market