
 Smart Pet Wearable Product Market | 2026-2036
Smart Pet Wearable Product Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pet Wearable Product Market Insights
Subscription bundling of hardware with cloud-based veterinary analytics is pivoting how pet owners evaluate total cost of ownership. Garmin Ltd. leverages its GPS heritage to dominate rugged outdoor tracking segments. FitBark anchors its position through deep veterinary research partnerships and behavior-science credibility. Tractive competes aggressively on cellular coverage breadth across European and North American networks.
Smart pet wearables comprise electronic devices affixed to collars, harnesses, or implants that capture biometric, locomotive, or positional data through accelerometers, photoplethysmography sensors, and multi-band GNSS receivers, transmitting via Bluetooth Low Energy or LTE-M protocols to mobile applications for real-time monitoring and longitudinal health profiling. Cellular-enabled GPS trackers lead unit shipments due to escape-recovery anxiety among dog owners, while health monitors command premium pricing through veterinary-grade ECG and temperature sensing that supports remote diagnostic workflows. Activity trackers sustain volume in the cat segment where lighter form factors and extended battery life outweigh location precision.
FDA Center for Veterinary Medicine guidelines on wellness device claims, FCC Part 15 rules for unlicensed radio transmitters, and EU REACH restrictions on nickel-containing alloys in prolonged skin contact collectively shape product design, labeling, and material selection for devices marketed across the United States and European Union. Stakeholders must monitor evolving interoperability standards between wearable data streams and practice management software to capture value from the veterinary channel.
Market Dynamics
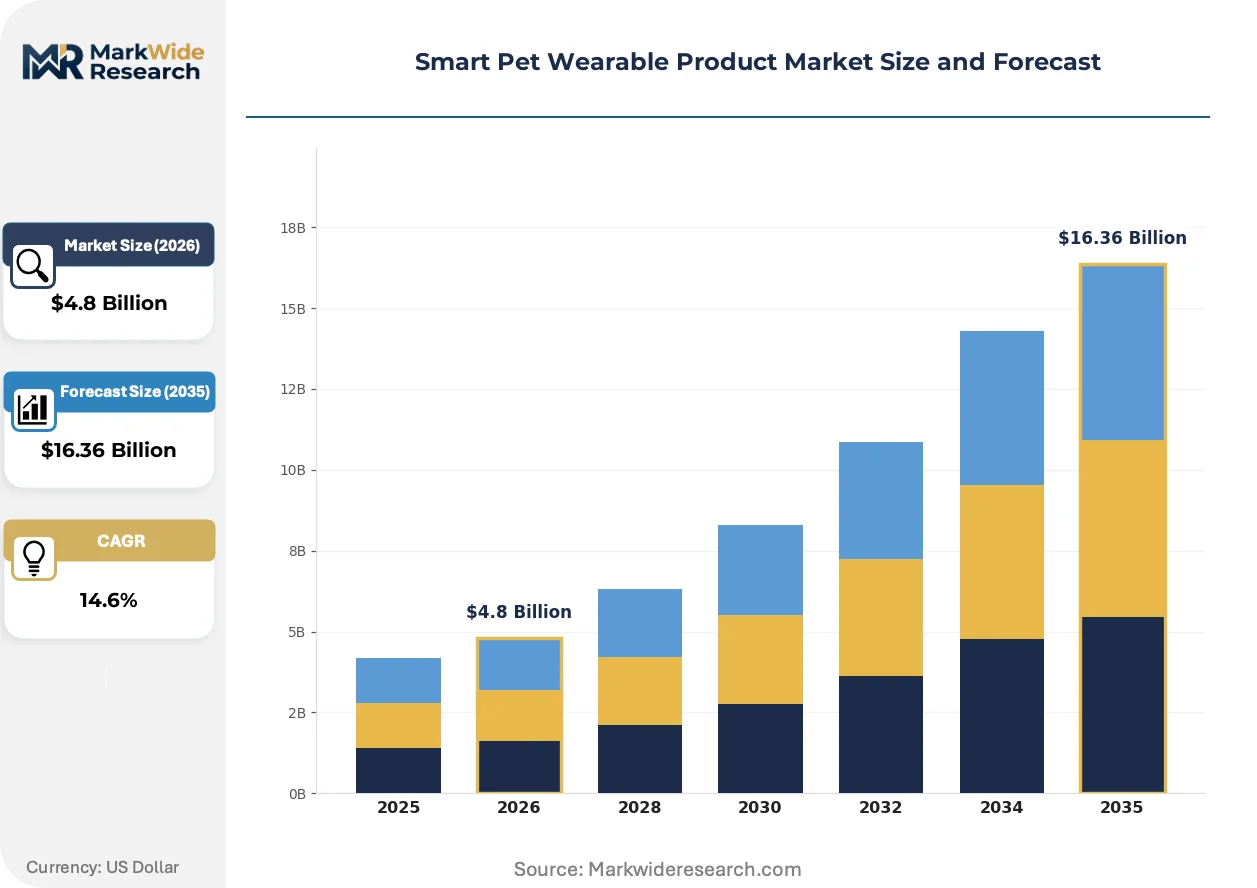
Subscription bundling of hardware with cloud-based veterinary analytics is restructuring how pet owners evaluate total cost of ownership, shifting purchase decisions from one-time device sales toward recurring service relationships that embed wearables into longitudinal health management workflows.
Growth Catalysts
- EU Green Deal circular electronics requirements:Repairable design mandates are pressuring manufacturers toward modular architectures that extend product lifecycles and reduce replacement frequency.
- Veterinary telehealth integration:Remote diagnostic workflows in Germany and France are validating biometric data streams from wearables as clinically actionable inputs for preventive care protocols.
- LTE-M protocol adoption:Low-power cellular connectivity is enabling real-time GPS tracking with extended battery life that satisfies escape-recovery anxiety among outdoor dog owners.
Market Restraints
- REACH nickel restrictions:EU regulations on nickel-containing alloys in prolonged skin contact are forcing material substitutions that increase per-unit manufacturing costs for collar-mounted devices.
- Battery chemistry concentration:Lithium-polymer cell supply chains cluster in East Asian manufacturing hubs, exposing vendors to logistics bottlenecks and input price volatility.
- Photoplethysmography accuracy limits:Motion artifacts in active animals degrade heart-rate measurement precision, constraining clinical-grade health monitoring claims.
Strategic Opportunities
- Cat segment underpenetration:Lighter form factors and extended battery architectures tailored to feline behavior patterns remain largely unaddressed by current GPS-dominant offerings.
- CSRD reporting alignment:EU corporate sustainability disclosure requirements create procurement tailwinds for pet wearables that generate quantifiable carbon-offset data through reduced veterinary travel.
- Behavior-science convergence:Integration of accelerometer data with machine learning models for anxiety detection and training optimization opens subscription revenue streams beyond location tracking.
Industry Challenges
- Veterinary software interoperability:Fragmented practice management systems resist standardized data ingestion, forcing wearable vendors to maintain multiple API integrations.
- FCC Part 15 certification timelines:Unlicensed radio transmitter approvals for multi-band GNSS receivers extend product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pet Wearable Product Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Trackers, Health Monitors, Activity Trackers, Smart Collars Technology: Bluetooth, RFID, NFC, Cellular End User: Pet Owners, Veterinarians, Pet Groomers, Trainers Application: Fitness Tracking, Health Monitoring, Training, Behavior Analysis |
| Companies Covered | Garmin Ltd., Whistle, Tractive, PetPace, FitBark, Datamars, Loc8tor Ltd., Dogtra, Petcube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pet Wearable Product Market Trends and Innovations
Veterinary-grade sensor miniaturization and cloud-native analytics architectures are converging to transform pet wearables from simple location devices into preventive health platforms that capture biometric data streams previously confined to clinical settings.
Photoplethysmography combined with temperature sensing is expanding into continuous health profiling applications that support early illness detection algorithms. Premium device buyers in Germany and the Netherlands are adopting these capabilities fastest, validating subscription pricing for diagnostic-grade monitoring. The technology is expanding into remote veterinary workflows that reduce in-person consultation frequency while maintaining care continuity.
EU AI Act risk classification rules are reshaping algorithm development practices for behavior-prediction features in pet wearables. Manufacturers must document training data provenance and establish human oversight protocols for automated health alerts. High-risk biometric inference systems face conformity assessment burdens that favor established veterinary research partnerships over pure hardware vendors.
Pet owner purchasing behavior is gravitating toward bundled hardware-service contracts that amortize device costs across multi-year veterinary analytics subscriptions. Traditional retail channels with upfront hardware margins are losing ground to direct-to-consumer platforms that emphasize total wellness value. This pattern concentrates in Scandinavia and German-speaking markets where telehealth penetration already exceeds Southern European levels.
Smart Pet Wearable Product Market Segmentation
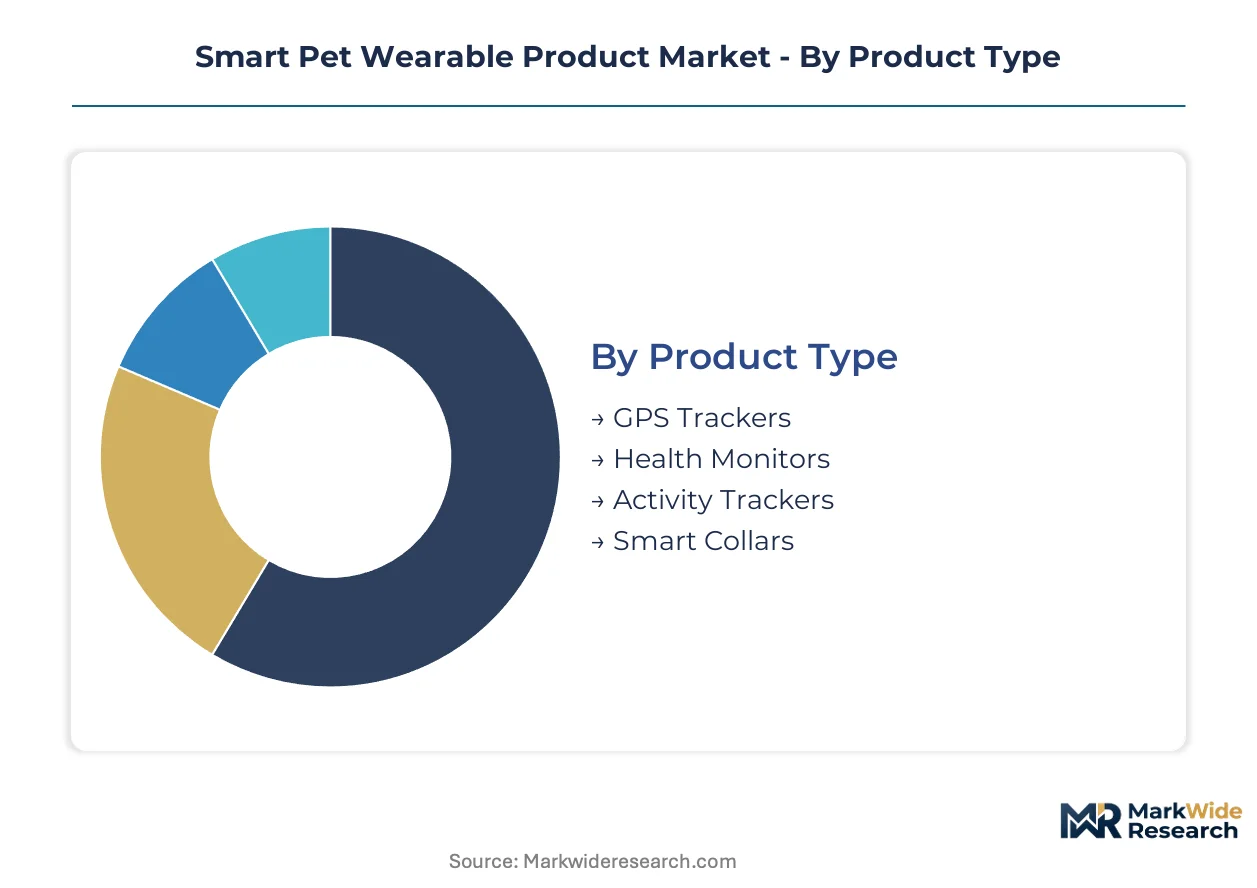
Smart pet wearable manufacturers calibrate R&D investment and channel strategy against four distinct segmentation axes. Product type determines sensor architecture and battery requirements. Technology choice shapes geographic coverage and subscription economics. End-user targeting dictates whether devices emphasize consumer simplicity or clinical integration. Application focus separates recreational fitness tools from diagnostic-grade health platforms.
Product Type:
Supply concentration in cellular-enabled GPS modules favors vendors with established carrier partnerships and FCC certification pipelines.
- GPS Trackers:Multi-band GNSS receivers with LTE-M backhaul deliver real-time positional accuracy within three meters for escape-recovery scenarios. Demand concentrates among outdoor dog owners in Germany and the Netherlands where off-leash recreation is culturally prevalent and cellular infrastructure is dense.
- Health Monitors:Photoplethysmography sensors combined with temperature probes enable continuous cardiac and thermal profiling previously confined to veterinary clinics. Veterinarians in France and Germany are adopting these for remote patient monitoring, validating premium pricing through reduced consultation frequency.
- Activity Trackers:Accelerometer-based devices with 30-day battery life dominate feline applications where GPS precision matters less than form factor weight.
- Smart Collars:Integrated platforms combining location, health, and training functions through unified mobile applications.
Today's leader: GPS Trackers. Tomorrow's challenger: Health Monitors.
Technology:
Cost tier stratification separates consumer-grade proximity solutions from enterprise cellular deployments with recurring service obligations.
- Cellular:LTE-M and NB-IoT protocols enable real-time data transmission across national boundaries without smartphone tethering. Network coverage breadth in rural Scandinavia and Alpine regions determines competitive positioning for outdoor tracking applications.
- Bluetooth:Low-energy protocols support indoor proximity alerts and smartphone-tethered fitness logging at sub-$50 hardware price points. Urban apartment dwellers in Paris and Milan represent the primary adoption cluster for short-range solutions.
- RFID:Passive identification systems embedded in microchips provide permanent identification without battery dependency.
- NFC:Near-field communication enables tap-to-access pet profiles and emergency contact retrieval by finders.
Cellular commands the premium tier. Bluetooth anchors volume shipments.
End User:
Customer type fragmentation requires parallel channel strategies: direct-to-consumer platforms, veterinary distributor networks, and professional trainer procurement programs.
- Pet Owners:Consumer purchasers evaluate total cost of ownership across hardware and subscription bundles, with escape-anxiety mitigation and preventive health insights driving purchase decisions in German-speaking markets.
- Veterinarians:Clinical adopters require FDA Center for Veterinary Medicine-compliant wellness claims and seamless practice management software integration. French veterinary groups are piloting remote diagnostic workflows using wearable biometric streams.
- Pet Groomers:Service providers utilize location verification for appointment logistics and basic activity confirmation during daycare stays.
- Trainers:Behavior specialists leverage accelerometer data for anxiety detection and training optimization protocols.
Pet Owners generate unit volume. Veterinarians unlock margin expansion.
Application:
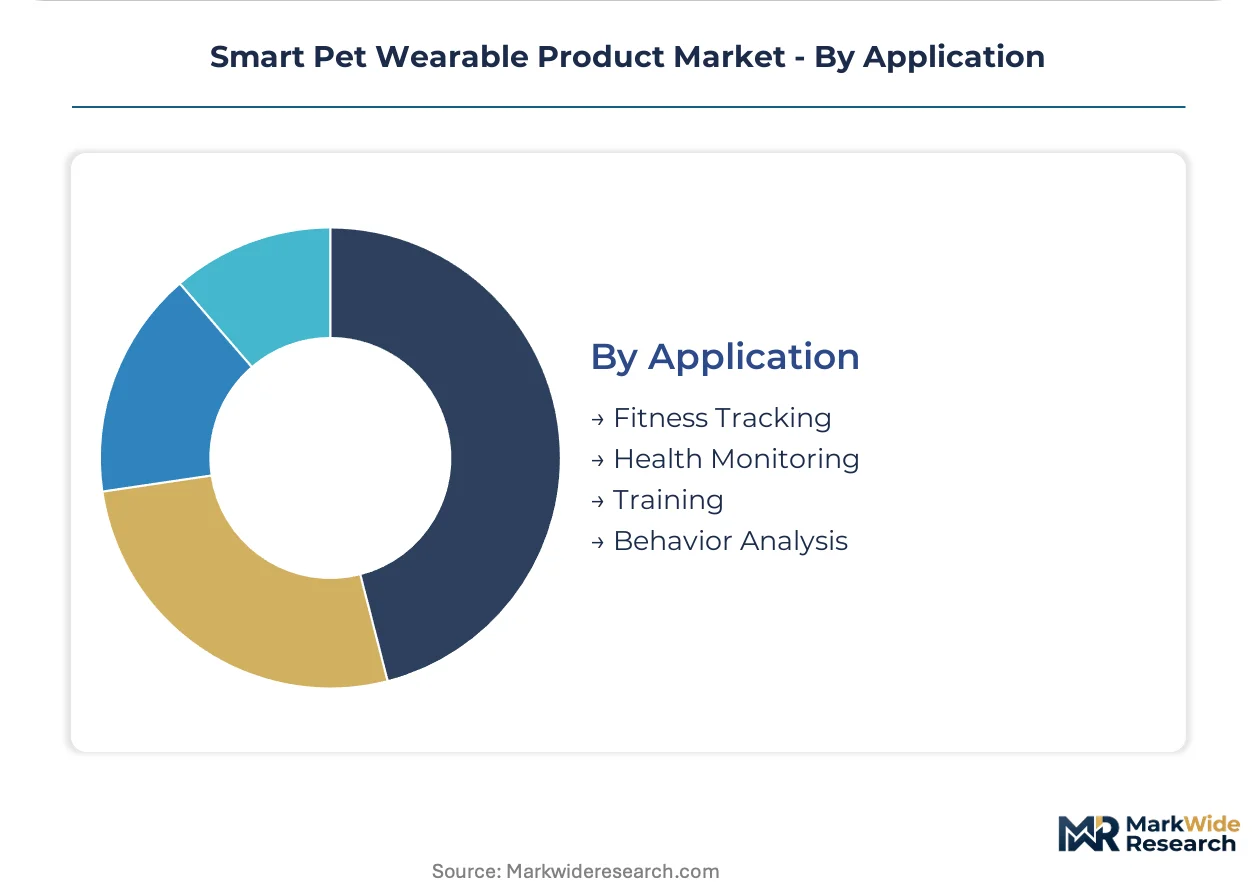
Maturity gradients separate established fitness tracking from emerging behavior-science applications requiring machine learning infrastructure.
- Health Monitoring:Continuous ECG, temperature, and respiratory rate tracking supports early illness detection algorithms. German and Dutch buyers are adopting diagnostic-grade capabilities fastest, validating subscription pricing for clinical-tier monitoring.
- Behavior Analysis:Machine learning models processing accelerometer patterns for anxiety, stress, and sleep quality assessment. EU AI Act conformity assessment requirements favor vendors with documented training data provenance and veterinary research partnerships.
- Fitness Tracking:Step counting, calorie estimation, and activity goal setting represent the most penetrated use case across all geographies.
- Training:Geofencing, remote correction, and positive reinforcement timing systems for obedience and boundary training.
Health Monitoring is climbing the fastest. Behavior Analysis holds steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart pet wearable industry traces its commercial roots to GPS tracking applications developed for hunting and sporting dogs in the United States during the early 2000s, with European veterinary telehealth integration subsequently elevating health monitoring capabilities to clinical-grade standards.
United States
Escape-recovery anxiety among suburban dog owners drives GPS tracker adoption, with FCC Part 15 certification requirements shaping radio transmitter design timelines. The FDA Center for Veterinary Medicine maintains wellness claim boundaries that manufacturers must navigate for health-adjacent marketing. Austin and Denver host concentrated startup activity focused on behavior-science analytics platforms.
Germany
Veterinary telehealth penetration exceeds European averages, validating subscription pricing for diagnostic-grade wearables through remote patient monitoring workflows. EU REACH restrictions on nickel-containing alloys force material substitutions in collar-mounted devices. Munich and Stuttgart anchor manufacturing clusters for precision sensor modules serving premium health monitor segments.
United Kingdom
Urban apartment dwellers favor Bluetooth-tethered proximity solutions at accessible price points, while rural estates drive demand for multi-band GNSS receivers. The UK Veterinary Medicines Directorate aligns with EU regulatory precedents on device classification. London fintech integration enables embedded insurance products that subsidize hardware costs through behavioral data monetization.
France
French veterinary groups pilot remote diagnostic workflows using wearable biometric streams, reducing in-person consultation frequency for chronic condition management. EU AI Act conformity assessment requirements favor vendors with documented training data provenance. Lyon hosts accelerometer calibration facilities supporting anxiety-detection algorithm development.
Netherlands
Premium device buyers adopt photoplethysmography-enabled health monitors fastest, validating clinical-tier subscription pricing. CSRD reporting alignment creates procurement tailwinds for wearables generating quantifiable carbon-offset data through reduced veterinary travel. Eindhoven's semiconductor ecosystem supplies low-power sensor modules optimized for extended battery architectures.
Smart Pet Wearable Product Market Competitive Landscape
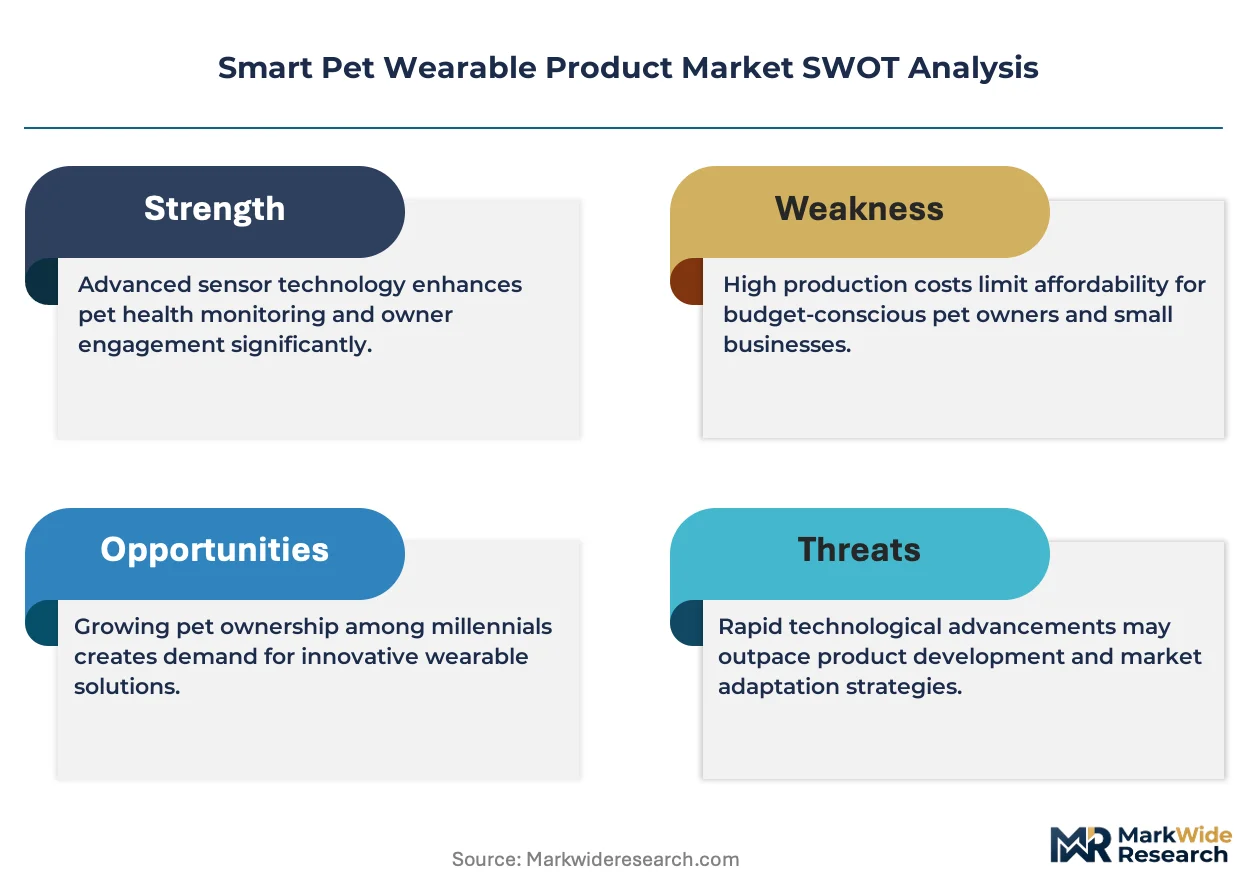
The competitive structure tilts toward technology-heritage specialists with established certification pipelines and veterinary research credibility. Garmin Ltd. leverages its GPS heritage to dominate rugged outdoor tracking segments, while FitBark anchors position through deep veterinary research partnerships and behavior-science credibility. Tractive competes aggressively on cellular coverage breadth across European and North American networks. Strategic moves concentrate on subscription bundling of hardware with cloud-based veterinary analytics and modular design architectures responding to EU Green Deal circular electronics requirements.
Within the GPS-tracking specialist tier, Garmin Ltd. and Tractive exemplify divergent geographic positioning strategies. Garmin Ltd., an American technology company, represents the heritage navigation archetype with established FCC certification infrastructure. Tractive, an Austrian limited liability company, occupies a position emphasizing pan-European cellular network partnerships. FitBark, a research-oriented entity, sits within the veterinary-credibility archetype through documented behavior-science partnerships. These three anchors illustrate how competitive differentiation flows from foundational technology lineages rather than interchangeable hardware specifications.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Whistle |
| Tractive |
| PetPace |
| FitBark |
| Datamars |
| Loc8tor Ltd. |
| Dogtra |
| Petcube |
| Others |
Pricing and Supply Chain Analysis
EU REACH nickel restrictions on prolonged skin contact are forcing collar-mounted device manufacturers toward surgical-grade stainless steel and titanium alloys, compressing margins in the mid-tier hardware segment while premium vendors absorb costs through subscription bundling. This regulatory-driven material substitution cascades through assembly economics, widening the cost gap between entry-level Bluetooth trackers and cellular-enabled GPS platforms.
Pricing Analysis
Hardware-plus-subscription bundling dominates revenue architecture across the smart pet wearable landscape. Price differentiation separates veterinary-grade health monitors with FDA Center for Veterinary Medicine-aligned wellness claims from consumer proximity trackers lacking clinical validation. Pricing pressure stems from lithium-polymer cell supply volatility in East Asian manufacturing hubs, squeezing gross margins on battery-dependent GPS units. Urban apartment dwellers purchasing Bluetooth-tethered devices exhibit highest price sensitivity, while German veterinary clinics accepting remote diagnostic workflows tolerate premium positioning for continuous biometric monitoring.
Supply Chain Analysis
Precision sensor module assembly clusters in Bavaria and Baden-Württemberg draw from specialized electromechanical workforces with heritage automotive and medical device training. Raw material dependencies center on lithium-polymer cells from South Korean and Japanese chemical suppliers, multi-band GNSS receivers from Taiwanese semiconductor fabricators, and photoplethysmography sensors from Dutch MEMS foundries. Single-source vulnerability concentrates in LTE-M modem chipsets, where Qualcomm and MediaTek dominate cellular IoT component supply. Distribution runs through veterinary distributor networks in German-speaking markets and direct-to-consumer platforms in Scandinavia, with Amazon and specialized pet retail chains anchoring volume channels elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart pet wearable market functions as a geographic-arbitrage play where EU regulatory stringency on circular electronics and AI accountability creates compliance cost differentials that favor established vendors with certification infrastructure over hardware-only entrants lacking veterinary research partnerships.
For Market Incumbents: Lock in veterinary software interoperability through API standardization investments that embed wearable data streams into practice management workflows, defending against pure-play hardware vendors lacking clinical channel credibility. Deepen backward integration into precision sensor module production across Munich-Stuttgart manufacturing corridors to capture margin from REACH-driven material substitution costs while accelerating FCC Part 15 certification timelines through captive radio transmitter testing facilities. For New Entrants and Emerging Players: Begin with feline-specific form factors and extended battery architectures, exploiting underpenetration in cat segments where GPS precision matters less than weight minimization and collar acceptance. Target French veterinary groups piloting remote diagnostic workflows, where biometric data stream validation creates reference customer momentum for subscription pricing models. Pursue direct-to-consumer launch with embedded insurance product partnerships that subsidize hardware costs through behavioral data monetization. For Investors and Strategic Acquirers: Asymmetric upside sits with research-oriented entities possessing documented behavior-science partnerships and EU AI Act conformity assessment documentation, as algorithm development burdens favor established veterinary credibility over pure hardware scale. Long-term viability hinges on recurring service revenue attachment rates rather than device shipment volumes. Watch veterinary telehealth reimbursement policy evolution in Germany and France as the inflection signal for diagnostic-grade wearable adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Software Integration | API standardization with IDEXX and Covetrus practice management systems embeds wearables into clinical workflows. |
| Modular Design Architecture | EU Green Deal repairability mandates favor component-swappable devices that extend product lifecycles beyond three years. |
| Behavior-Science Platform Development | Machine learning anxiety-detection algorithms trained on veterinary research partnerships unlock subscription revenue beyond location tracking. |
| Cellular Coverage Expansion | Pan-European LTE-M roaming agreements with Deutsche Telekom and Vodafone eliminate dead zones for Alpine and Scandinavian outdoor dog owners. |
| CSRD Reporting Alignment | Carbon-offset quantification through reduced veterinary travel creates procurement tailwinds among sustainability-reporting enterprise buyers. |
Research Methodology
Bottom-up veterinary channel modeling reconciled against top-down cellular IoT module shipment tracking forms the analytical core of this study. Primary interviews with veterinary practice owners, pet wearable product managers, carrier IoT partnership leads, and regulatory affairs specialists at FDA Center for Veterinary Medicine and ECHA combined with secondary validation from FCC equipment authorization databases, EU MDR vigilance reports, carrier coverage maps, and veterinary telehealth platform disclosures. Triangulation across stakeholder perspectives and data sources ensures segmentation integrity across product type, technology protocol, and end-user archetype dimensions.
Input-output matrices connect sensor component costs, subscription pricing elasticity, and veterinary adoption curves across the projection horizon. Segmentation dimensions modeled include GPS tracker versus health monitor versus activity tracker product categories, cellular versus Bluetooth versus RFID technology tiers, pet owner versus veterinarian versus trainer end-user types, and fitness tracking versus behavior analysis versus health monitoring application focus. CAGRs derive from regression analysis of historical subscription attachment rates and veterinary telehealth penetration trajectories, with LTE-M network deployment schedules and EU AI Act implementation timelines serving as industry-specific forecast modifiers.
Several conditions sit outside the modeled scope, including hypothetical breakthroughs in non-invasive glucose monitoring, shifts in pet insurance reimbursement policy for preventive wearable data, and geopolitical disruptions to lithium supply chains. Forecasts reflect documented assumptions regarding carrier roaming agreement stability and veterinary software API standardization velocity. Practitioners should monitor ECHA substance restriction proposal timelines and FDA wellness claim enforcement patterns for early signals of regulatory cost trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Global Smart Watch Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Europe Watch Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Smart Band Market
Wearable Technology
Women's Watch Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Wearable Computing Market