
 Asia-Pacific Wearable Technology Market | 2026-2036
Asia-Pacific Wearable Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wearable Technology Market Analytics
Edge AI inference on-device is reconfiguring how wearable devices process biometric data without cloud dependency. Huawei Technologies leverages its Kirin chip architecture to sustain vertical integration across sensors-to-software stacks. Samsung Electronics anchors premium smartwatch production through in-house display and semiconductor capabilities. Xiaomi competes on manufacturing scale, controlling cost structures that dominate entry-level fitness tracker segments across India and Southeast Asia.
Asia-Pacific wearable technology encompasses body-worn electronic devices integrating microprocessors, biometric sensors, and wireless communication modules operating at 2.4 GHz Bluetooth frequencies, designed for continuous physiological monitoring and contextual computing. These systems employ photoplethysmography and accelerometer arrays to capture heart rate variability, SpO2, and motion patterns for real-time health analytics and activity classification. Smartwatches occupy the largest revenue pool, though wearable medical devices command superior margins where regulatory clearance creates defensible market positions. Fitness trackers lead unit volumes across price-sensitive demographics, while smart glasses remain nascent with enterprise applications in Japan's manufacturing sector outpacing consumer traction.
Japan's PMDA and South Korea's MFDS enforce medical-grade validation for wearable devices claiming diagnostic functions, elevating compliance costs but filtering low-reliability entrants. China's NMPA and India's CDSCO maintain divergent classification thresholds for wellness versus medical claims, fragmenting product registration strategies across the region. India's BIS mandatory certification for wireless devices adds testing layers that shape go-to-market timelines. Stakeholders must monitor regulatory convergence pressures as ASEAN nations develop harmonized medical device frameworks that could unify or complicate cross-border certification requirements.
Market Dynamics
Edge AI inference on-device is compressing cloud dependency while fragmenting competitive advantage across sensor-to-software stacks. This structural shift forces hardware vendors to reconfigure silicon roadmaps around biometric processing autonomy rather than connectivity bandwidth.
Growth Catalysts
- Remote patient monitoring protocols:Japan's PMDA and South Korea's MFDS now reimburse connected wearable diagnostics under national health schemes, pulling medical-grade devices into chronic disease management workflows.
- Photoplethysmography miniaturization:Optical sensor arrays achieve clinical-grade SpO2 accuracy in sub-5mm form factors, enabling ring and earbud form factors previously constrained by measurement fidelity.
- India's PLI scheme for electronics:Component-level incentives localize PCB assembly and battery pack production, shortening landed costs for entry-level fitness trackers distributed across Southeast Asia.
Market Restraints
- Lithium-polymer cell volatility:Battery raw material concentration in China's Qinghai and Jiangxi provinces exposes margin structures to cathode powder price swings and export quota unpredictability.
- Medical-wearable certification divergence:China's NMPA wellness-versus-medical classification threshold sits at diagnostic claim specificity, forcing dual-track registration strategies that duplicate clinical testing expenditure.
- Smart glasses substitution pressure:Industrial AR headsets from Japan's manufacturing automation sector face displacement by tablet-based remote assistance platforms requiring no head-worn hardware deployment.
Strategic Opportunities
- Indonesia's archipelago healthcare gaps:17,000+ islands create last-mile monitoring demand where cellular-enabled wearables bypass clinic infrastructure scarcity for diabetes and hypertension management.
- Biometric-authentication convergence:ECG pattern recognition is hybridizing with payment tokenization, positioning wearable vendors for financial services licensing in Singapore and Australia's open banking frameworks.
- ASEAN harmonized medical device framework:Draft mutual recognition protocols would collapse multi-country registration into single-market clearance, compressing 18-month compliance timelines for regional product launches.
Industry Challenges
- Edge AI firmware engineering scarcity:Embedded machine learning optimization for sub-1mW inference demands skill sets concentrated in Taiwan's semiconductor design houses and South Korea's system LSI divisions.
- Legacy hospital IT integration friction:HL7 FHIR interoperability gaps force manual data bridge construction for wearable feeds entering Japan's hospital information systems, extending enterprise sales cycles.
- IP fragmentation across wireless stacks:Bluetooth Low Energy 5.3 and proprietary ultra-wideband positioning patents scatter across Nordic Semiconductor, Apple, and Samsung portfolios, complicating royalty stacking for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wearable Technology Market |
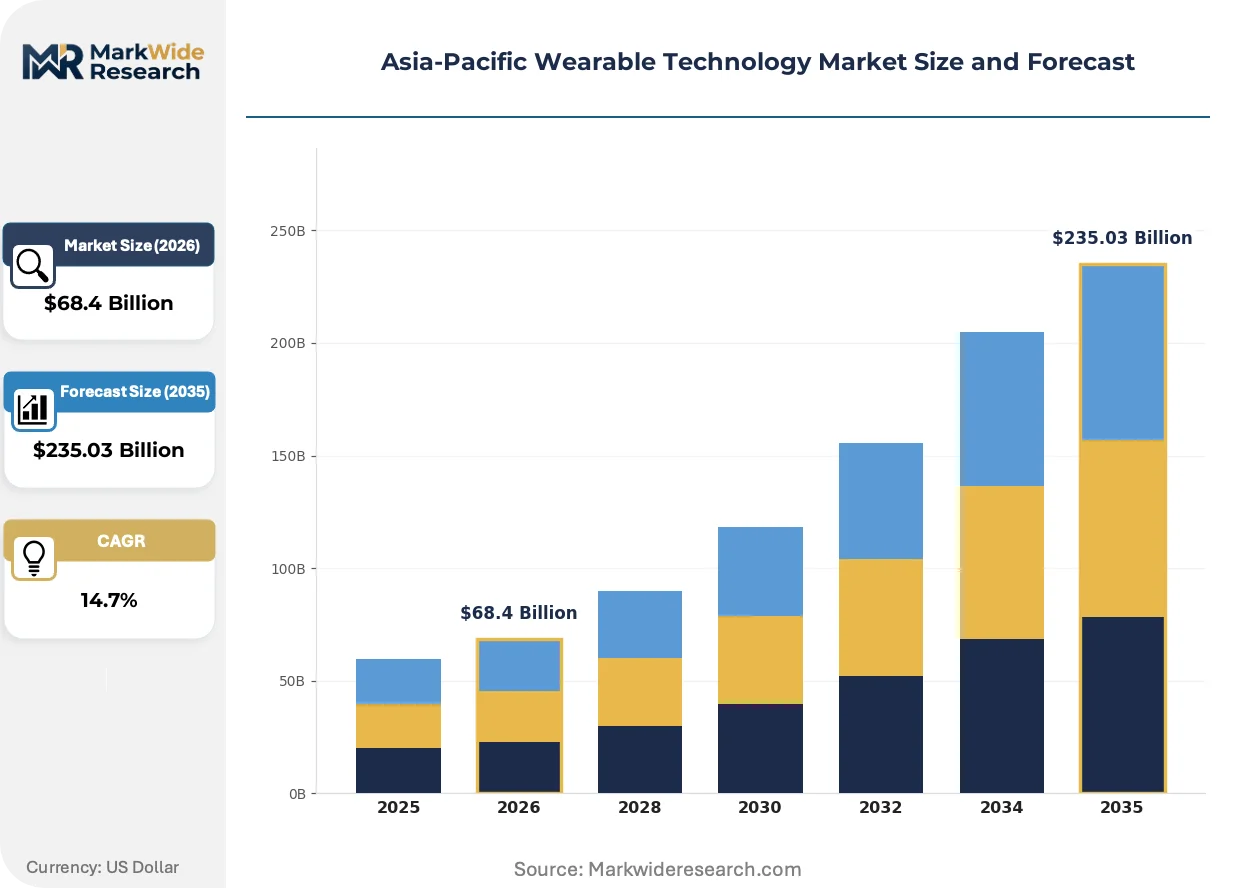
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $235.03 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Wearable Medical Devices Technology: Bluetooth, NFC, Wi-Fi, RFID End User: Health Enthusiasts, Sports Professionals, Elderly Users, Patients Application: Health Monitoring, Fitness Tracking, Mobile Payments, Remote Diagnostics |
| Companies Covered | Huawei Technologies, Sony Group Corporation, Apple Inc., LG Electronics, Imagine Marketing Limited, Samsung Electronics, Garmin Ltd., Fitbit Inc., Xiaomi, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wearable Technology Market Evolving Landscape
Biometric sensor fusion is collapsing single-function devices into multi-parameter platforms, while regulatory clarity around diagnostic claims separates reimbursable medical hardware from wellness accessories.
Photoplethysmography is hybridizing with accelerometer arrays and galvanic skin response electrodes in next-generation health rings. Chronic disease management programs in Australia's aged care sector and Japan's corporate wellness mandates are adopting these devices for nocturnal autonomic monitoring. This convergence is compressing the addressable market for standalone pulse oximeters and basic fitness bands by delivering equivalent clinical signals through jewelry-form hardware.
Japan's PMDA revised its Software as a Medical Device guidance in 2023 to explicitly address machine learning-enabled wearables, requiring locked algorithm versions for regulatory submission rather than continuous learning deployments. Manufacturers must now freeze diagnostic models at approval, creating version control complexity for cloud-connected devices. South Korea's MFDS is observing this precedent, with domestic smartwatch vendors pre-positioning segregated on-device inference architectures to satisfy both markets.
Hospital procurement committees in China and India are unbundling device acquisition from data platform subscriptions, reversing earlier bundled SaaS contracts. This disaggregation forces wearable vendors to compete on hardware margin alone while separately licensing analytics software through hospital IT procurement channels. The shift is most visible in tier-2 Chinese cities where provincial health bureaus mandate open API standards preventing vendor lock-in through exclusive data formats.
Asia-Pacific Wearable Technology Market Segmentation
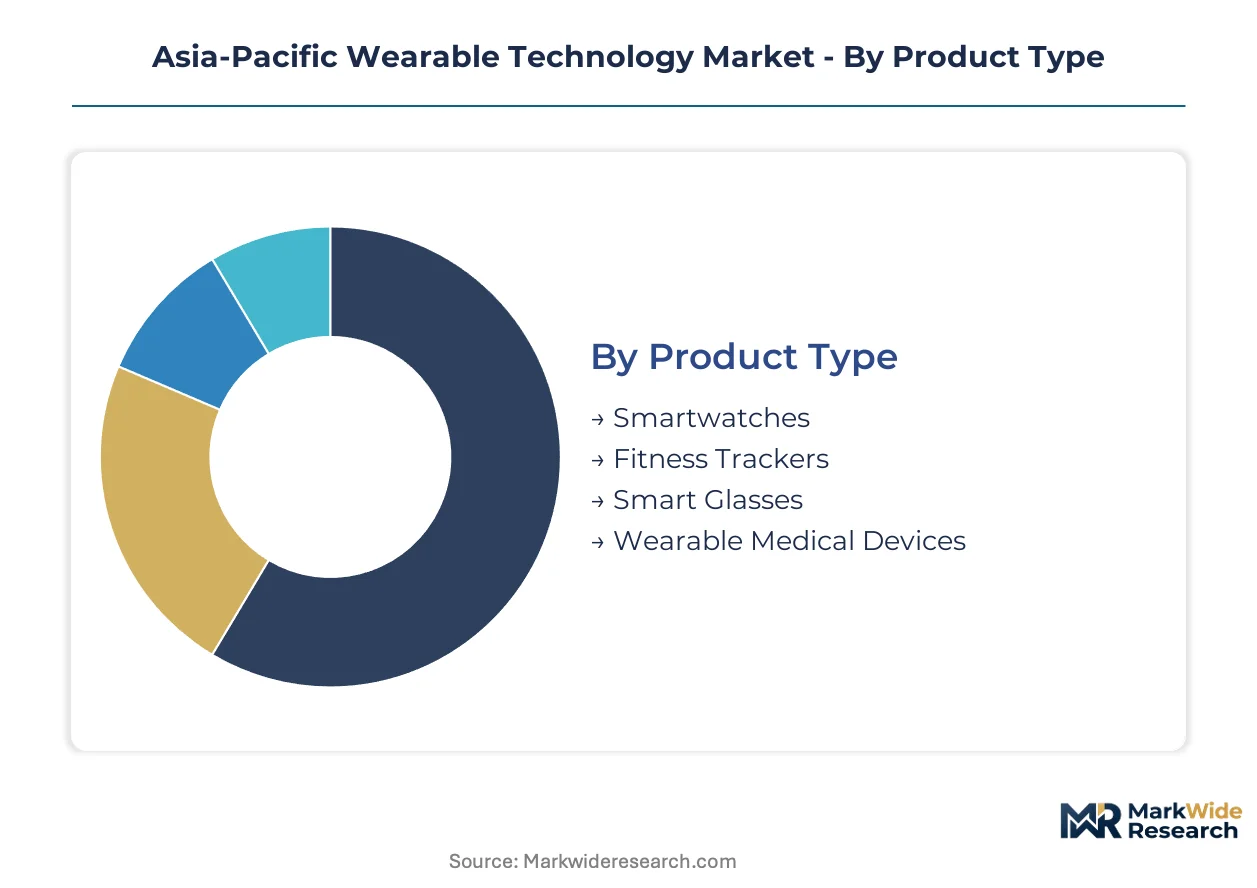
Segmentation in Asia-Pacific wearable technology reveals distinct service intensity profiles across hardware categories. Medical-grade devices demand calibration maintenance and regulatory recertification, while consumer fitness trackers operate on minimal post-sale engagement.
Product Type:
After-sales service intensity varies dramatically across form factors, with medical devices requiring ongoing calibration support and consumer wearables relying on self-service firmware updates.
- Smartwatches:Multi-sensor platforms integrate photoplethysmography, accelerometry, and galvanic skin response in wrist-worn architectures. Demand concentrates in China's Guangdong province where Shenzhen's hardware ecosystem supplies Bluetooth-enabled health monitors for Southeast Asian distribution. Samsung Electronics and Huawei Technologies anchor premium production through captive semiconductor and display capabilities.
- Wearable Medical Devices:Diagnostic-grade hardware employs locked algorithm versions meeting Japan's PMDA Software as a Medical Device guidance for regulatory submission. Japan and South Korea now reimburse connected wearable diagnostics under national health schemes, pulling these devices into chronic disease management workflows with mandated calibration protocols.
- Fitness Trackers:Entry-level units dominate unit volumes across India's price-sensitive demographics through Xiaomi's manufacturing scale advantages.
- Smart Glasses:Enterprise applications in Japan's manufacturing automation sector currently outpace consumer traction.
Smartwatches hold the largest share; momentum sits with wearable medical devices.
Technology:
Connectivity specifications determine interoperability certification burdens and royalty exposure across the region's fragmented patent landscape.
- Bluetooth:Low Energy 5.3 operates at 2.4 GHz frequencies enabling continuous physiological monitoring with sub-1mW power budgets. India's BIS mandatory certification for wireless devices adds testing layers that shape go-to-market timelines for Bluetooth-enabled hardware.
- NFC:Short-range protocols enable payment tokenization hybridized with ECG pattern recognition for financial services licensing in Singapore and Australia's open banking frameworks.
- Wi-Fi:Higher bandwidth supports cloud-dependent analytics in hospital procurement settings where China's tier-2 cities mandate open API standards.
- RFID:Passive identification supports inventory and access control applications with minimal power requirements.
Bluetooth dominates installed base; NFC is climbing the fastest on biometric-payment convergence.
End User:
User sophistication dictates pricing tolerance and feature complexity requirements across the region's diverse demographic profiles.
- Patients:Chronic disease management programs in Australia's aged care sector and Japan's corporate wellness mandates drive nocturnal autonomic monitoring demand through ring-form devices.
- Elderly Users:Australia's aged care infrastructure and Japan's aging population create sustained demand for fall detection and medication adherence features.
- Health Enthusiasts:Wellness-focused consumers drive fitness tracker volumes across India's PLI-accelerated local assembly operations.
- Sports Professionals:Performance optimization applications concentrate in South Korea's MFDS-regulated environments and Australia's institute-backed athletic programs.
Patients command premium pricing; health enthusiasts drive volume scale.
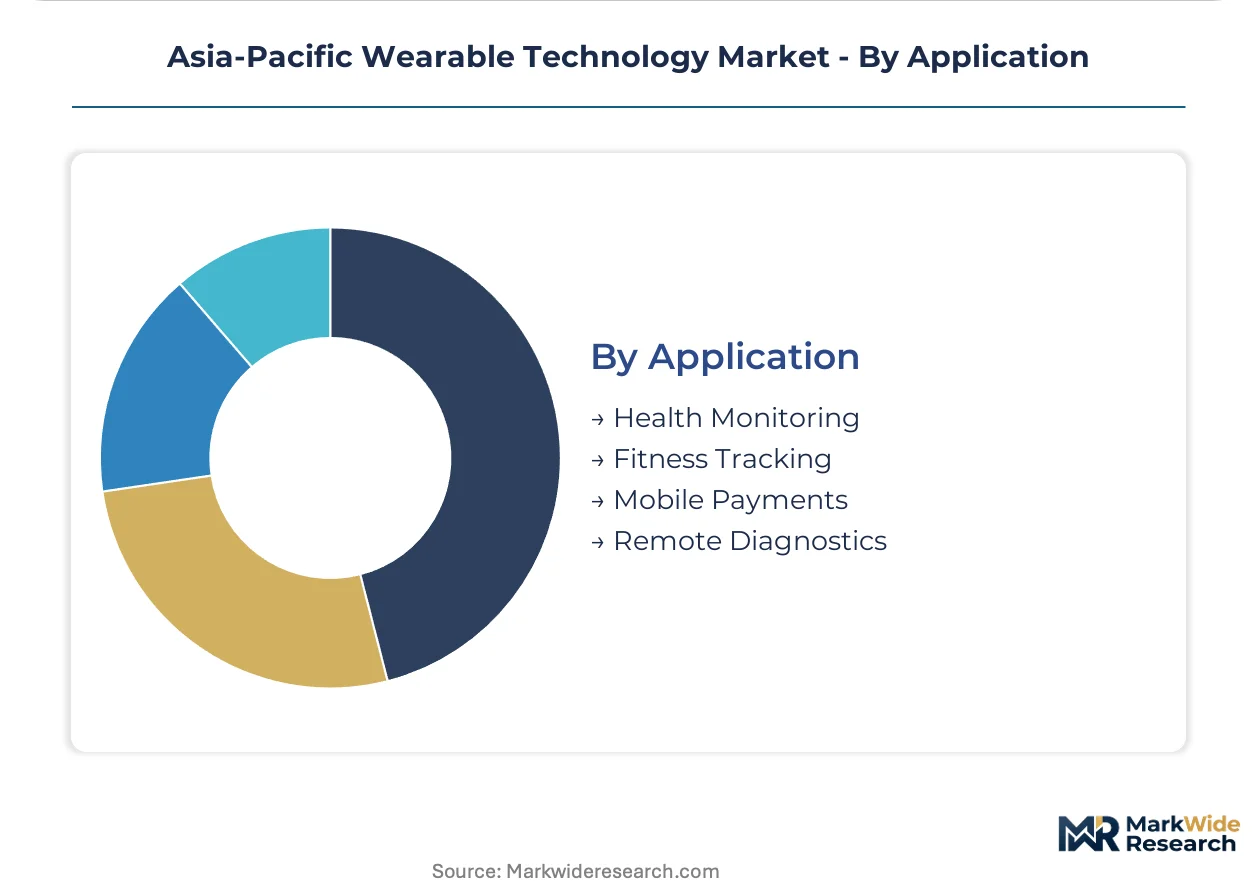
Application:
Application segmentation separates reimbursable clinical functions from discretionary wellness features, with regulatory classification determining margin structures.
- Health Monitoring:Continuous SpO2 and heart rate variability tracking employs photoplethysmography miniaturized to sub-5mm optical sensor arrays enabling ring and earbud form factors.
- Remote Diagnostics:Cellular-enabled wearables bypass clinic infrastructure scarcity across Indonesia's 17,000+ islands for diabetes and hypertension management.
- Fitness Tracking:Activity classification algorithms process accelerometer arrays for step counting and sleep staging in entry-level hardware.
- Mobile Payments:Biometric-authentication convergence positions wearable vendors for financial services licensing through tokenized ECG pattern recognition.
Health monitoring captures the largest revenue pool; remote diagnostics shows steepest expansion trajectory on archipelago healthcare gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's hardware ecosystem exports Bluetooth-enabled health monitor components throughout Southeast Asia, while Japan and South Korea import medical-grade wearable diagnostics for chronic disease management workflows. India's PLI-accelerated assembly operations feed entry-level fitness trackers into Bangladesh and Nepal markets.
China
Guangdong province concentrates demand for multi-sensor smartwatch platforms integrating photoplethysmography and accelerometry arrays. NMPA maintains divergent wellness-versus-medical classification thresholds that fragment product registration strategies. Shenzhen's component suppliers serve Southeast Asian distributors with sub-5mm optical sensor arrays for ring-form devices.
Japan
PMDA reimbursement protocols now pull connected wearable diagnostics into national health schemes for chronic disease management. METI corporate wellness mandates drive nocturnal autonomic monitoring adoption through jewelry-form hardware. Tokyo's hospital procurement committees unbundle device acquisition from data platform subscriptions.
South Korea
MFDS enforces medical-grade validation for wearable devices claiming diagnostic functions, elevating compliance costs but filtering low-reliability entrants. Domestic smartwatch vendors pre-position segregated on-device inference architectures to satisfy locked algorithm requirements. Seoul's system LSI divisions concentrate embedded machine learning optimization skill sets.
India
BIS mandatory certification for wireless devices adds testing layers that shape go-to-market timelines for Bluetooth-enabled hardware. CDSCO maintains classification thresholds for wellness versus medical claims that diverge from Chinese and Japanese frameworks. Karnataka and Tamil Nadu PLI-accelerated facilities localize PCB assembly and battery pack production for Southeast Asian distribution.
Australia
Aged care infrastructure creates sustained demand for fall detection and medication adherence features in wearable medical devices. TGA observes PMDA's locked algorithm precedent for machine learning-enabled diagnostics. Sydney and Melbourne health systems adopt ring-form devices for nocturnal autonomic monitoring in corporate wellness programs.
Asia-Pacific Wearable Technology Market Competitive Landscape
On the supply side, the industry is consolidating around captive semiconductor capabilities and in-house display manufacturing. Tiered competitive positioning separates premium smartwatch vendors with full-stack control from entry-level fitness tracker assemblers competing on manufacturing scale. Three archetypes dominate: integrated technology conglomerates with sensor-to-software stacks, contract manufacturing specialists leveraging PLI incentives, and medical-grade device developers navigating PMDA/MFDS reimbursement pathways. Dominant competitive moves include backward integration into semiconductor design and strategic partnerships with hospital IT procurement channels.
Within the integrated technology tier, Huawei Technologies and Samsung Electronics exemplify full-stack control through captive chip architectures and display capabilities. Xiaomi occupies the scale-driven position, leveraging manufacturing cost structures that dominate entry-level segments across India and Southeast Asia. Garmin Ltd. represents the medical-grade specialization archetype, navigating regulatory clearance requirements that create defensible margin positions in reimbursable diagnostic hardware.
| Leading Market Players |
|---|
| Huawei Technologies |
| Sony Group Corporation |
| Apple Inc. |
| LG Electronics |
| Imagine Marketing Limited |
| Samsung Electronics |
| Garmin Ltd. |
| Fitbit Inc. |
| Xiaomi |
| Others |
Value Network & Pricing Analysis
Overcapacity in Guangdong province's Bluetooth module foundries is compressing component pricing and forcing suppliers toward medical-grade certification investments to escape commodity margin erosion. This utilization dynamic simultaneously rewards vendors with PMDA-cleared devices and punishes undifferentiated fitness tracker assemblers competing solely on landed cost.
Pricing Analysis
Next-generation photoplethysmography sensors command 40-60% premiums over prior-generation optical arrays, while legacy accelerometer-based fitness bands face sustained cost compression. Pricing stratifies across premium, standard, and economy tiers based on diagnostic certification grade and after-sales calibration bundling. Price erosion runs through entry-level segments as India's PLI-accelerated facilities flood Southeast Asian channels with sub-$15 units. Health enthusiasts in Bangladesh and Nepal exhibit extreme price sensitivity, whereas Japan's hospital procurement committees prioritize locked-algorithm reliability over unit cost.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment are constraining foundry capacity expansion for sub-5nm biometric processing chips across Taiwan and South Korea. Lithium-polymer cell production draws from cathode powder concentration in China's Qinghai and Jiangxi provinces, with battery pack assembly migrating to Karnataka and Tamil Nadu under India's PLI scheme. Single-source vulnerability sits with optical sensor array supply from Shenzhen's hardware ecosystem. Distribution runs through tier-1 electronics distributors serving Southeast Asian retail channels and direct hospital procurement committees in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tablet-based remote assistance platforms threaten to displace industrial AR headsets in Japan's manufacturing automation sector, forcing wearable vendors to defend hardware attach rates through diagnostic-grade certification moats.
For Market Incumbents: Insulate premium positioning by securing PMDA and MFDS locked-algorithm approvals before regulatory guidance hardens. Deepen backward integration into Kirin-class semiconductor architectures to sustain sensor-to-software autonomy against fabless competitors. Channel control through hospital IT procurement relationships in China's tier-2 cities prevents disaggregation of hardware from analytics subscriptions.
For New Entrants and Emerging Players: Establish a beachhead in Indonesia's cellular-enabled remote diagnostics segment where archipelago geography creates infrastructure-bypass demand. Target nocturnal autonomic monitoring rings for Australia's aged care sector, where reimbursement pathways remain underdeveloped relative to Japan. A go-to-market angle through Singapore's open banking biometric-authentication licensing sidesteps saturated fitness tracker channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among medical-grade device developers with calibration-maintenance contracts and regulatory recertification obligations. Long-term viability favors vendors with segregated on-device inference architectures satisfying both PMDA locked-algorithm requirements and cloud-connected feature roadmaps. The signal to watch is ASEAN harmonized medical device framework ratification collapsing multi-country registration timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Locked-Algorithm Regulatory Submission | PMDA-compliant version control creates defensible margin positions in reimbursable diagnostics. |
| On-Device Inference Architecture Segregation | Satisfies both Japanese locked-model requirements and Korean continuous-learning feature expectations. |
| Hospital IT Procurement Channel Partnership | Prevents unbundling of device acquisition from analytics platform subscriptions in China's tier-2 cities. |
| Cellular-Enabled Remote Diagnostics Deployment | Bypasses clinic infrastructure scarcity across Indonesia's 17,000+ islands for chronic disease management. |
| Biometric-Authentication Financial Services Licensing | Positions wearable vendors for ECG-pattern payment tokenization in Singapore's open banking framework. |
Research Methodology
A spread of perspectives from semiconductor design engineers, hospital biomedical equipment procurement managers, PLI scheme facility operators, and regulatory affairs specialists at PMDA and MFDS converged on the working assumptions. Primary interview intelligence combined with secondary validation from NMPA device registration databases, BIS wireless certification records, ASEAN medical device harmonization draft protocols, and SEC filings of listed wearable technology vendors. Bottom-up unit shipment estimates triangulated against top-down healthcare expenditure allocation models.
Demand-supply balance dynamics across sensor component foundries, battery cell capacity, and finished device assembly facilities anchored the analytical framework throughout the projection horizon. Segmentation modeling incorporated product type, connectivity technology, end-user sophistication, and application regulatory classification dimensions. CAGRs derived from slope-consistency checks against historical medical device reimbursement expansion patterns and electronics manufacturing incentive scheme uptake curves. Forecast inputs included PLI scheme capacity commissioning timelines and PMDA Software as a Medical Device guidance implementation trajectories.
Stress conditions across lithium-polymer raw material export quotas, ASEAN harmonization protocol ratification delays, and edge AI firmware engineering scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement pathway expansion and semiconductor foundry utilization rates. Material shifts in Japan's corporate wellness mandate enforcement or India's BIS certification processing timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Kids Watch Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Asia Pacific Smartwatch Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Smart Bra Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
3D Printed Wearables Market