
 UK Wearable Technology Market | 2026-2036
UK Wearable Technology Market Size, Share, and Industry Trends Forecast 2026-2036
UK Wearable Technology Market Outlook
Aftermarket service revenue is tilting toward subscription-based health analytics and extended warranty ecosystems. Apple leverages its vertical integration across hardware, software, and health services to sustain premium positioning in the smartwatch category. Samsung Electronics anchors its UK presence through broad retail distribution and Galaxy ecosystem lock-in. Garmin specializes in ruggedized devices for industrial workers and outdoor enthusiasts, occupying a defensible niche against generalist competitors.
Wearable technology encompasses body-borne electronic devices integrating sensors, wireless connectivity modules, and embedded processors to capture physiological, kinematic, or environmental data for real-time feedback or subsequent analysis. These devices typically incorporate accelerometers, photoplethysmography sensors, and lithium-polymer cells within injection-molded polymer housings designed for sweat resistance and skin contact compliance. Fitness trackers lead unit volumes due to accessible price points and NHS-backed wellness initiatives, while smartwatches capture disproportionate value through recurring software revenue and health platform integration. Smart clothing remains embryonic but attracts R&D investment from textile-electronics hybrid ventures targeting industrial safety applications.
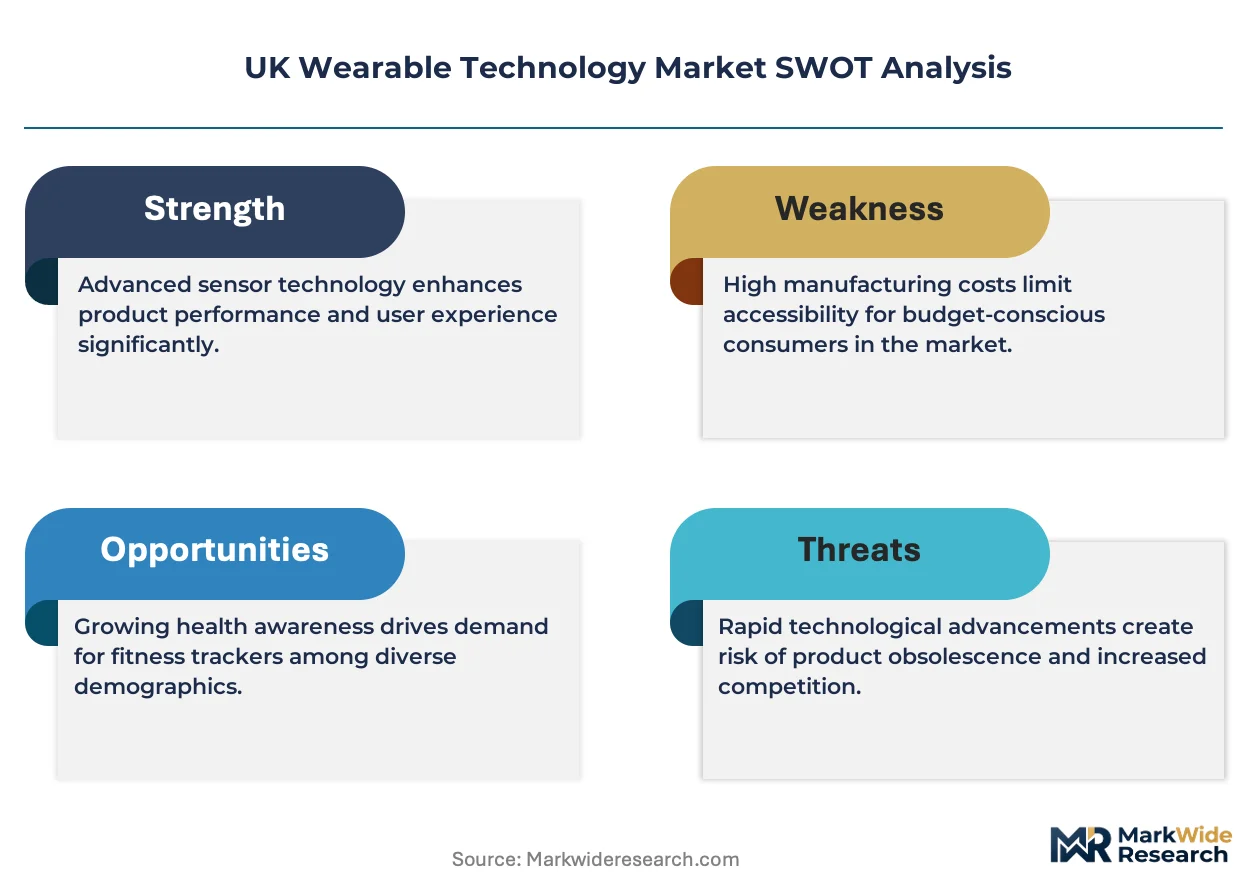
The Medicines and Healthcare products Regulatory Agency governs clinical-grade wearables through medical device classification pathways, while the UK GDPR regime imposes strict biometric data processing requirements that shape product architecture and vendor liability. The Competition and Markets Authority scrutinizes platform exclusivity arrangements between device makers and health data aggregators, influencing partnership strategies. Stakeholders must monitor evolving MHRA guidance on software-as-a-medical-device classifications that could reclassify consumer fitness trackers into regulated healthcare products.
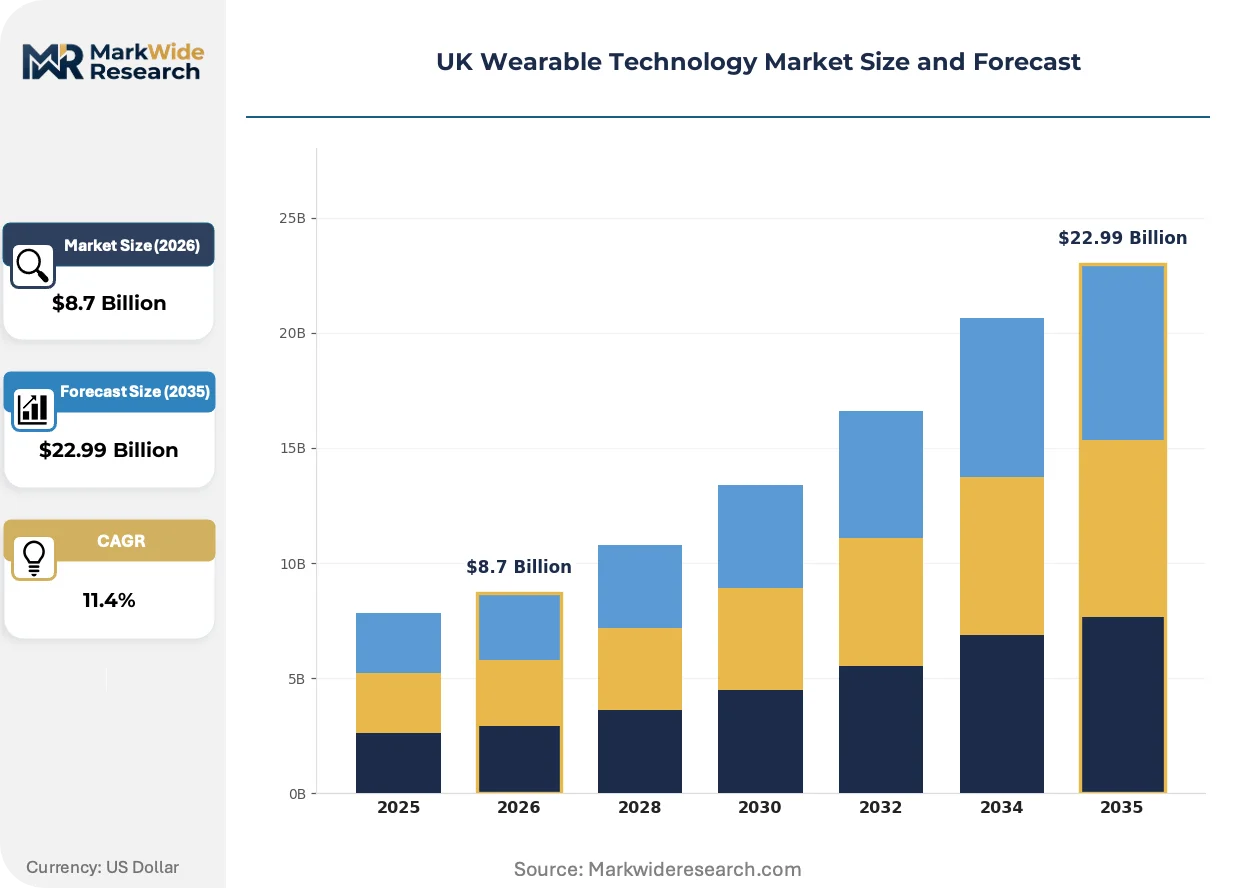
Market Dynamics
NHS remote patient monitoring mandates are compressing procurement cycles for clinical-grade wearables, forcing vendors to restructure software architectures around UK GDPR biometric compliance before hardware shipment.
Growth Catalysts
- MHRA Software-as-a-Medical-Device pathways:Regulatory clarity accelerates clinical validation timelines for consumer devices seeking healthcare reimbursement eligibility.
- Corporate wellness mandates:London-based financial services firms deploy fitness trackers as preventive health infrastructure, expanding enterprise contract values.
- Photoplethysmography miniaturization:Advanced optical sensors enable continuous blood pressure monitoring without cuff inflation, opening cardiovascular management applications.
Market Restraints
- Lithium-polymer supply concentration:Battery cell production clusters in East Asian manufacturing zones, exposing UK vendors to shipping cost volatility and customs processing delays.
- UK GDPR biometric friction:Explicit consent requirements for health data processing increase user onboarding abandonment rates and legal compliance overhead.
- Smartphone dependency:Wearable functionality remains tethered to handset ecosystem compatibility, limiting addressable market among non-smartphone users.
Strategic Opportunities
- Industrial safety wearables:Construction and logistics sectors in the Midlands adopt ruggedized biometric monitors for workforce fatigue management and insurance premium reduction.
- Galaxy ecosystem integration:Cross-device health data synchronization between wearables, tablets, and home appliances creates sticky subscription revenue streams.
- Textile-electronics hybrid R&D:Conductive fiber weaving techniques enable garment-integrated sensors for continuous monitoring without device charging interruptions.
Industry Challenges
- ISO 14155 clinical investigation timelines:Medical device certification requires 18-24 month study protocols, delaying revenue recognition for upgraded sensor generations.
- Legacy NHS IT integration:Hospital electronic health record systems demand proprietary API development, fragmenting engineering resources across incompatible data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Wearable Technology Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smartwatches, Smart Clothing, Wearable Cameras Technology: Bluetooth, NFC, Wi-Fi, Sensor Technology End User: Fitness Enthusiasts, Healthcare Providers, Tech Savvy Consumers, Industrial Workers Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Third-party Retailers |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Fitbit LLC, Huawei Technologies Co. Ltd., Xiaomi Inc., Garmin Ltd., Fossil Group Inc., OnePlus Technology (Shenzhen) Co. Ltd., Sekonda Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Wearable Technology Market Strategic Shifts
Sensor fusion architectures and edge computing migration are redistributing processing loads from smartphones to wrist-worn devices, enabling real-time health alerts without cloud latency.
Photoplethysmography signal processing is collapsing the distinction between consumer fitness tracking and clinical-grade cardiac monitoring. NHS trusts in Greater Manchester pilot these sensors for atrial fibrillation screening in primary care settings. The compression of hardware cost curves is forcing traditional medical device manufacturers to defend reimbursement codes against consumer electronics entrants.
UK GDPR Article 9 special category data rules now require explicit opt-in workflows for any wearable collecting biometric information. The Information Commissioner's Office has issued enforcement notices against three health app aggregators for inadequate consent mechanisms. Vendors respond by deploying on-device processing architectures that minimize cloud data transmission and reduce regulatory exposure.
Employer-sponsored wellness programmes are displacing direct-to-consumer retail as the dominant acquisition channel for fitness trackers. Large professional services firms in the Square Mile negotiate bulk deployment contracts with customized analytics dashboards for occupational health teams. This shift concentrates purchasing power among benefits managers rather than individual consumers, compressing average selling prices while extending contract durations.
UK Wearable Technology Market Segmentation
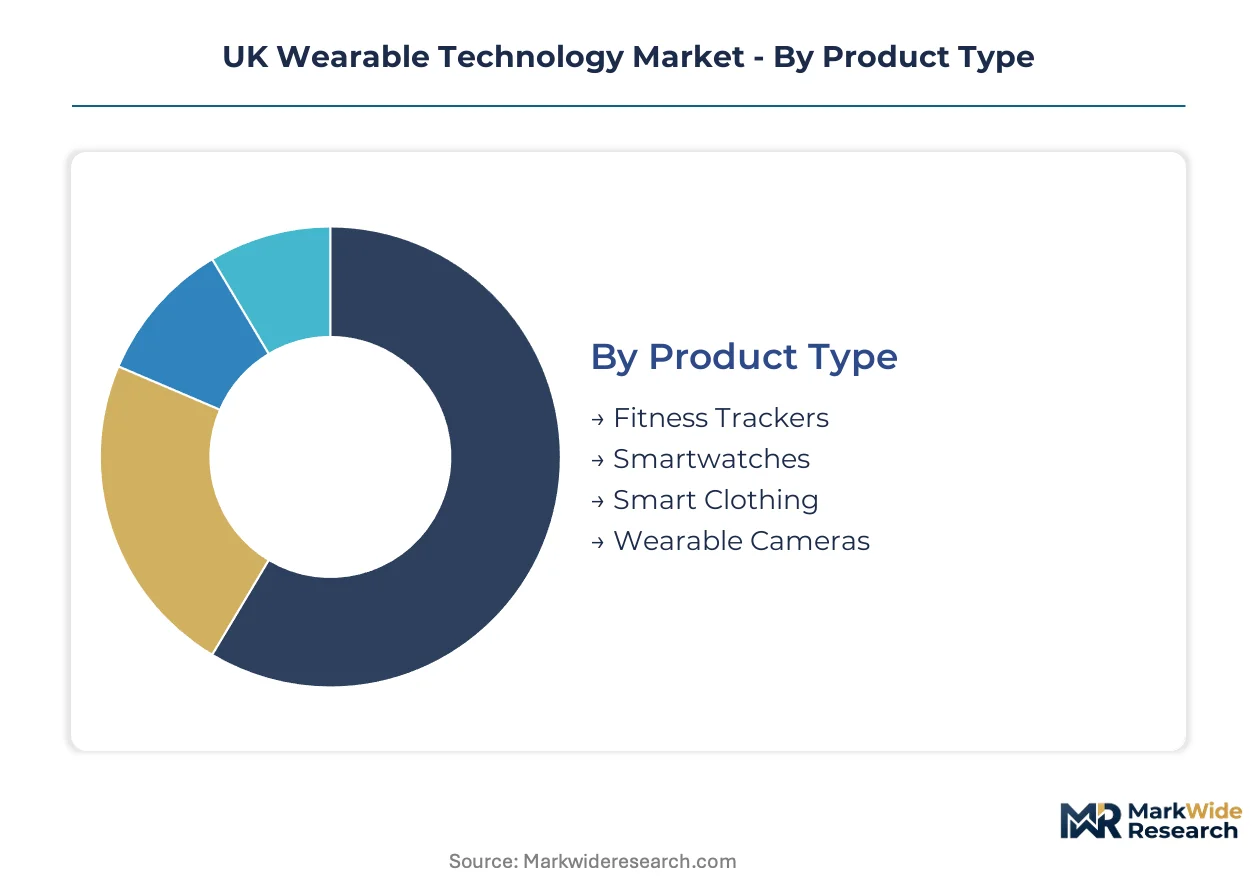
Wearable technology segmentation reveals distinct value capture patterns across hardware form factors, connectivity protocols, and procurement channels. Understanding these divisions enables vendors to align R&D investment with reimbursement pathways and enterprise contract structures.
Product Type:
Use-case spectrum spans preventive wellness monitoring through clinical-grade diagnostics, with form factor determining regulatory pathway and pricing power.
- Fitness Trackers:Wrist-worn devices integrate accelerometers and photoplethysmography sensors for step counting and heart rate monitoring. NHS-backed wellness initiatives in London and the South East concentrate procurement through corporate wellness mandates, compressing unit economics while extending contract volumes.
- Smartwatches:Multi-function wrist computers combine cellular connectivity, app ecosystems, and FDA-cleared ECG capabilities. Tech-savvy consumers in metropolitan clusters drive replacement cycles, with recurring software revenue streams offsetting hardware margin compression.
- Smart Clothing:Textile-integrated conductive fibers embed sensors within garments for continuous biometric capture without charging interruptions.
- Wearable Cameras:Body-mounted recording devices serve industrial safety documentation and outdoor recreation applications.
The dominant share belongs to fitness trackers, while smartwatches are closing the gap fastest through health platform integration and enterprise contract expansion.
Technology:
Connectivity architecture determines data latency, power consumption, and interoperability with existing health IT infrastructure.
- Bluetooth:Low-energy protocols dominate wrist-worn device connectivity, enabling smartphone tethering with minimal battery drain. Fitness trackers and smartwatches across UK retail channels standardize on Bluetooth 5.0 and above for reliable synchronization with iOS and Android handsets.
- Sensor Technology:Multi-modal arrays combining accelerometry, optical heart rate, and skin temperature sensing enable FDA-cleared cardiac monitoring. NHS trusts in Greater Manchester pilot these architectures for atrial fibrillation screening, accelerating clinical validation timelines.
- NFC:Near-field communication enables contactless payment authentication and medical device pairing in hospital settings.
- Wi-Fi:Direct cloud connectivity supports standalone smartwatches and industrial safety wearables requiring real-time alert transmission.
Bluetooth retains the installed base majority, though sensor technology is expanding most quickly through clinical-grade certification pathways.
End User:
Customer archetypes range from self-directed consumers to institutional procurement with distinct compliance and integration requirements.
- Healthcare Providers:NHS trusts and private hospitals procure clinical-grade wearables through remote patient monitoring mandates. MHRA software-as-a-medical-device pathways accelerate procurement cycles, forcing vendors to restructure architectures around UK GDPR biometric compliance.
- Industrial Workers:Construction and logistics operators in the Midlands adopt ruggedized biometric monitors for fatigue management. Insurance premium reduction incentives drive fleet deployments, with Garmin and specialized vendors capturing defensible niche positions.
- Fitness Enthusiasts:Recreational athletes and amateur sports participants purchase through direct-to-consumer retail and specialty channels.
- Tech Savvy Consumers:Early adopters in London and the South East drive premium smartwatch replacement cycles and ecosystem lock-in.
Healthcare providers command the highest contract values, while industrial workers are gaining share fastest through occupational safety mandates.
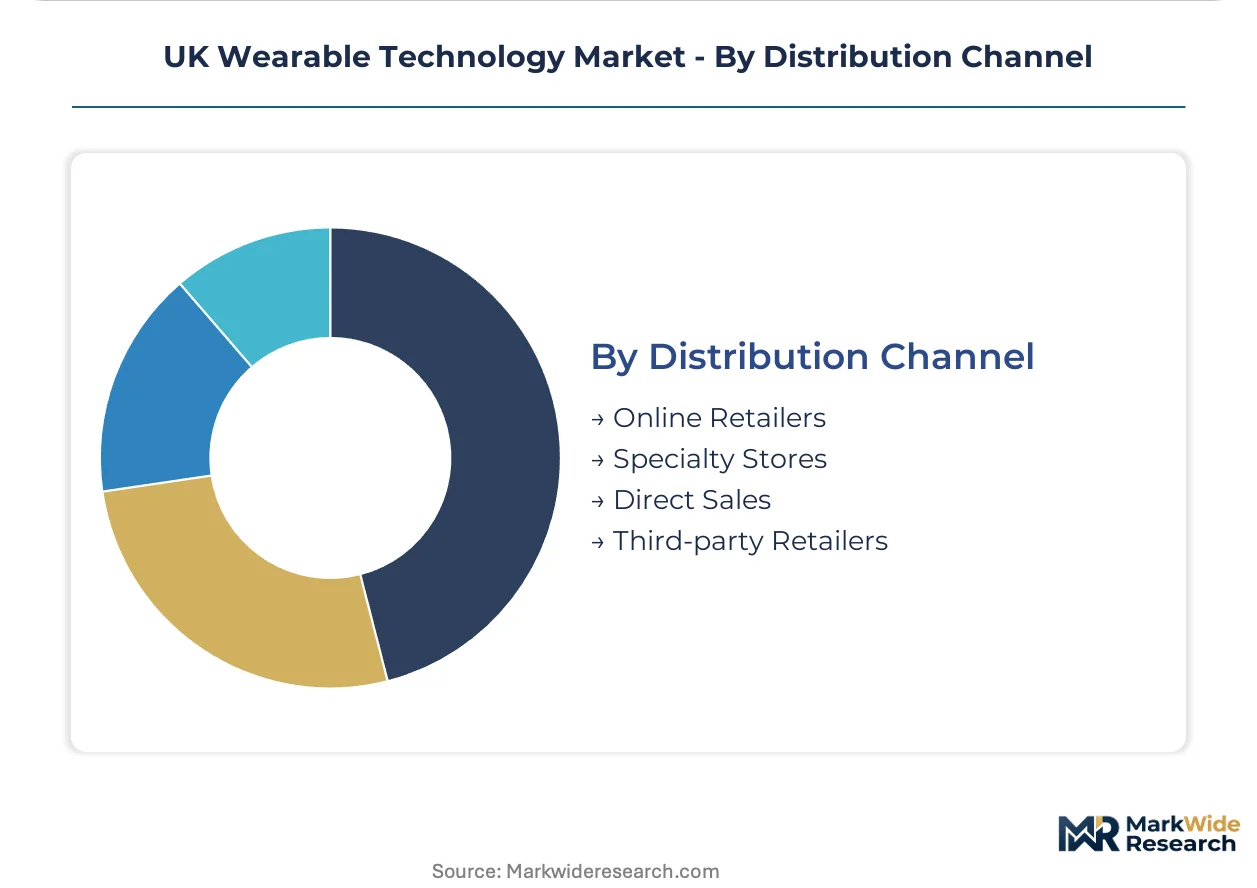
Distribution Channel:
Channel strategy determines customer acquisition cost, brand positioning, and post-sale service attachment rates.
- Online Retailers:Amazon and direct-to-consumer platforms dominate fitness tracker volumes with price transparency and comparison tools. Corporate wellness bulk orders increasingly route through specialized B2B portals with customized analytics dashboards.
- Direct Sales:Apple and Samsung flagship stores and enterprise sales teams capture premium smartwatch volumes with ecosystem demonstration and trade-in programs.
- Specialty Stores:Running and outdoor retailers provide fitting expertise for sports-specific wearables.
- Third-party Retailers:Currys, Argos, and mobile network operators distribute mid-range devices with installment financing.
Online retailers hold volume leadership, though direct sales are climbing the fastest through enterprise wellness contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across UK sub-regions. London and the South East absorb premium pricing through corporate wellness budgets, while Northern England and Wales remain price-sensitive markets where NHS procurement concentrates volume.
London and the South East
Financial services firms in the Square Mile negotiate bulk fitness tracker deployments with customized analytics dashboards. The UK GDPR regime shapes product architecture through explicit consent requirements for biometric data processing. Tech-savvy consumers in Canary Wharf and Shoreditch drive smartwatch replacement cycles through ecosystem lock-in.
Midlands
Construction and logistics operators adopt ruggedized biometric monitors for workforce fatigue management and insurance premium reduction. The Health and Safety Executive mandates fatigue monitoring in high-risk sectors, accelerating industrial wearable adoption. Birmingham and Coventry host distribution hubs serving manufacturing clusters across the West Midlands.
North England
NHS trusts in Greater Manchester pilot photoplethysmography sensors for atrial fibrillation screening in primary care settings. MHRA software-as-a-medical-device pathways compress procurement timelines for clinical-grade devices. Sheffield and Leeds concentrate health tech startups developing remote patient monitoring solutions.
Scotland
Remote patient monitoring programmes expand across Highland and Island health boards where geographic dispersion complicates in-person care. NHS Scotland's Digital Health and Care Strategy accelerates wearable procurement for chronic disease management. Edinburgh's informatics cluster supports health data analytics infrastructure.
Wales
Cost-conscious procurement dominates wearable adoption through NHS Wales bulk purchasing agreements. The Welsh Government's Digital Strategy for Health prioritizes affordable preventive monitoring solutions. Cardiff anchors distribution networks serving rural communities with limited specialist access.
UK Wearable Technology Market Competitive Environment
Capability concentration sits with vertically integrated technology conglomerates; scale advantage sits with consumer electronics specialists with broad retail footprints. The market structures around three tiers: premium ecosystem providers, mid-range generalists, and defensible niche specialists. Two dominant competitive moves reshape positioning: backward integration into sensor manufacturing and strategic partnerships with health data aggregators.
Within the premium ecosystem tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify platform lock-in strategies spanning hardware, software, and services. Garmin Ltd. occupies a defensible specialist position in ruggedized industrial applications. These three anchors represent contrasting archetypes: vertical integration, ecosystem breadth, and niche durability.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Fitbit LLC |
| Huawei Technologies Co. Ltd. |
| Xiaomi Inc. |
| Garmin Ltd. |
| Fossil Group Inc. |
| OnePlus Technology (Shenzhen) Co. Ltd. |
| Sekonda Ltd. |
| Others |
Value Chain & Pricing Dynamics
Lithium-polymer supply concentration in East Asian manufacturing zones exposes UK vendors to shipping cost volatility and customs processing delays, compressing margin structures across premium smartwatches while forcing economy-tier fitness trackers toward direct-from-factory procurement models.
Pricing Analysis
Subscription-based health analytics and extended warranty ecosystems now drive lifetime value capture beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates Apple and Samsung ecosystem bundles from mid-range generalists and NHS bulk-procurement white-label devices. Price differentiation hinges on MHRA software-as-a-medical-device certification status and enterprise analytics customization depth. Cost compression in the economy tier intensifies because Chinese OEMs bypass UK retail markups through direct-to-consumer channels. NHS procurement managers exhibit highest price sensitivity, while corporate wellness benefits administrators accept premium positioning for dashboard integration capabilities.
Supply Chain Analysis
Photoplethysmography sensor modules and lithium-polymer battery cells draw from concentrated production bases in China, South Korea, and Taiwan. Raw material dependencies span rare-earth magnet components for haptic feedback, sapphire glass for display durability, and medical-grade silicone for skin-contact compliance. Single-source vulnerability in advanced optical sensor fabrication threatens clinical-grade wearable output schedules when foundry capacity reallocates to smartphone camera arrays. Distribution runs through Shenzhen and Hong Kong logistics hubs before customs clearance at Felixstowe and Southampton, with final-mile fulfillment splitting between Amazon FBA networks and NHS supply chain depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are flattening while recurring revenue from health analytics subscriptions and enterprise wellness platform fees expands at double the rate of device sales, repositioning vendor economics toward service-attach models.
For Market Incumbents: Build ecosystem lock-in moats through cross-device health data synchronization between wearables, tablets, and home appliances. Deepen backward integration into photoplethysmography sensor manufacturing to secure clinical-grade certification timelines against supply chain bottlenecks. Expand dedicated NHS IT integration teams to accelerate proprietary API development for electronic health record compatibility. For New Entrants and Emerging Players: Pursue industrial safety wearable white-space in Midlands construction and logistics sectors where fatigue monitoring mandates create procurement urgency. Target NHS Scotland remote patient monitoring programmes in Highland and Island health boards where geographic dispersion favors new vendor relationships over incumbent switching costs. Deploy direct sales teams with occupational health expertise rather than competing through saturated consumer retail channels. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors vertically integrated health data aggregators with regulatory clearance momentum. Long-term viability rests on capturing recurring subscription revenue streams rather than hardware shipment volumes. Signal to watch: MHRA reclassification of consumer fitness trackers into regulated healthcare products, which would trigger acquisition premiums for pre-cleared software architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Medical-Device Certification | MHRA pathway unlocks NHS reimbursement eligibility and enterprise contract expansion. |
| Galaxy Ecosystem Integration | Cross-device synchronization creates sticky subscription revenue streams across Samsung appliances. |
| Industrial Safety Partnership | Health and Safety Executive mandates accelerate ruggedized biometric monitor fleet deployments. |
| Textile-Electronics Hybrid R&D | Conductive fiber weaving enables garment-integrated sensors without charging interruptions. |
| On-Device Processing Architecture | Edge computing migration minimizes UK GDPR cloud data transmission and regulatory exposure. |
Study Parameters
The analysis maps fitness trackers, smartwatches, smart clothing, and wearable cameras, each validated through procurement directors at NHS trusts, occupational health managers at Midlands construction firms, and benefits administrators at London financial services companies. Primary interviews with biomedical engineers, GPO contracts managers, and health tech startup founders combined with secondary validation against MHRA device registrations, NHS Digital procurement databases, and Information Commissioner's Office enforcement notices. Bottom-up shipment estimates triangulated with top-down enterprise contract value aggregation.
Assumptions held fixed include continued NHS remote patient monitoring mandate expansion and sustained UK GDPR biometric data processing requirements; variables tested encompass lithium-polymer supply chain disruption scenarios and MHRA software-as-a-medical-device reclassification timing. Segmentation dimensions modeled span product type, connectivity protocol, end-user archetype, and procurement channel across the analysis window. CAGRs derived from regression analysis of historical shipment data against corporate wellness contract growth curves and clinical validation timeline compression.
Macroeconomic conditions sit as an overlay; deviation in sterling exchange rates against East Asian currencies or NHS capital allocation priorities would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and supply chain continuity. Cross-checking against NHS Digital annual reports and Office for National Statistics technology adoption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Computing Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Smart Bra Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Kids Watch Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Women's Watch Market