
 Smartphone Screen Protector Market | 2026-2036
Smartphone Screen Protector Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Screen Protector Market Intelligence
Asset-light e-commerce models, relying on outsourced manufacturing, is tilting the competitive landscape away from traditional vertically integrated players. This dynamic allows brands like Spigen Inc. to compete effectively on marketing and rapid product iteration for new phone models. In contrast, Corning Incorporated sustains its market position through deep material science expertise in specialty glass. ZAGG Inc. leverages its broad portfolio and strong retail channel presence to serve diverse consumer segments.
A smartphone screen protector is a transparent layer of material, typically tempered glass or thermoplastic polyurethane, applied to a device's display. These products are engineered for specific hardness ratings, such as 9H for glass, to resist scratches from everyday objects. Tempered glass continues to dominate the market by type due to its superior feel and impact absorption. Online retail has become the primary distribution channel, enabling smaller brands to reach a wide consumer base without significant physical store investment.
Material safety regulations, such as the EU's REACH and RoHS directives, influence the chemical compositions used in protectors and their adhesives. In China, adherence to GB standards for material quality and durability is essential for market access. These frameworks ensure a baseline of consumer safety and product performance. The critical decision for manufacturers remains balancing investments in next-generation materials like hybrid glass against intense price competition in the mass market.
Market Dynamics
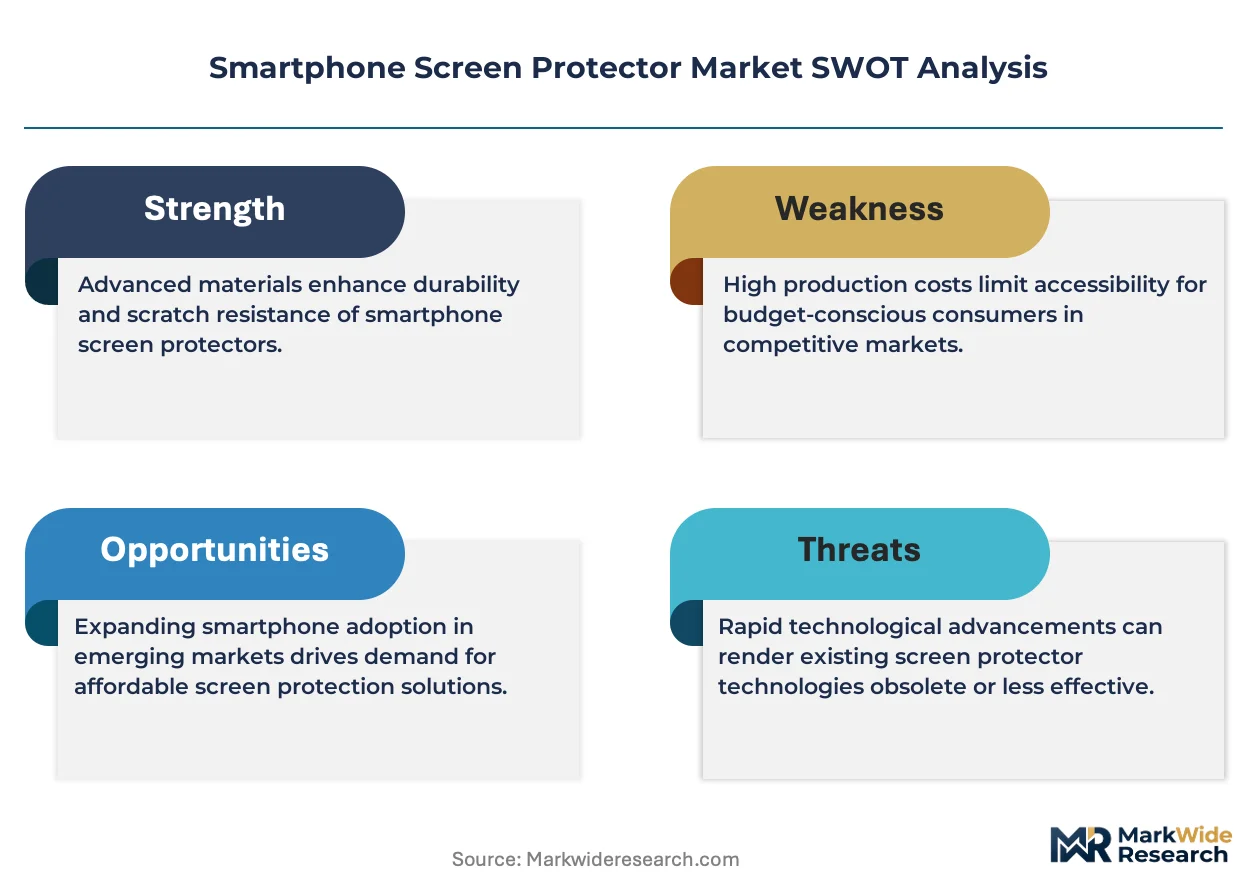
The central dynamic shaping the smartphone screen protector market is the bifurcation between advanced material science innovation and the commoditizing force of asset-light e-commerce models. This creates a market defined by both premium, feature-rich products and mass-market price competition.
Growth Catalysts
- Smartphone Value Escalation:The rising cost of flagship smartphones makes screen protectors a high-value, low-cost insurance purchase for consumers, directly tying protector demand to new device sales cycles.
- Demand in Southeast Asia:A high concentration of new smartphone owners in countries like Vietnam and Indonesia, who prioritize device longevity and resale value, creates a significant demand-side pull for protective accessories.
- Advanced Film Technologies:Innovations such as self-healing thermoplastic polyurethane (TPU) films and enhanced oleophobic coatings are increasing perceived value and justifying premium price points for consumers seeking more than basic scratch resistance.
Market Restraints
- Intense Price Commoditization:The proliferation of low-cost online sellers and direct-from-factory brands creates severe margin pressure, making it difficult for differentiated products to command a sustained premium in the mass market.
- Foldable Form Factor Limitations:Traditional tempered glass, the market's dominant material, is incompatible with the flexible displays of foldable smartphones, creating a technical barrier and performance gap for this growing device segment.
- Native Screen Durability:Advances in chemically strengthened glass used for smartphone displays, such as those in the Gorilla Glass series, can reduce the perceived necessity of a third-party screen protector for some consumers.
Strategic Opportunities
- Functional Integration:There is a clear opportunity to embed additional features into screen protectors, such as integrated privacy filters, anti-blue-light layers, and enhanced compatibility with under-display fingerprint sensors.
- Adjacent Device Categories:The core technologies can be adapted for other consumer electronics with displays, including smartwatches, handheld gaming consoles, and in-vehicle infotainment systems, opening new revenue streams.
- Emerging Markets in Africa:As smartphone penetration increases across countries like Nigeria and Kenya, a new wave of first-time users will create a substantial, untapped market for entry-level and mid-tier device protection.
Industry Challenges
- Rapid-Cycle Product Alignment:Manufacturers face the operational challenge of quickly designing, tooling, and distributing protectors for a vast number of new smartphone models each year, demanding highly agile supply chains.
- Multi-Regional Regulatory Compliance:Adhering to divergent material safety standards, such as the EU's REACH directive and China's GB standards for adhesives and coatings, adds significant complexity and cost to global operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Screen Protector Market |
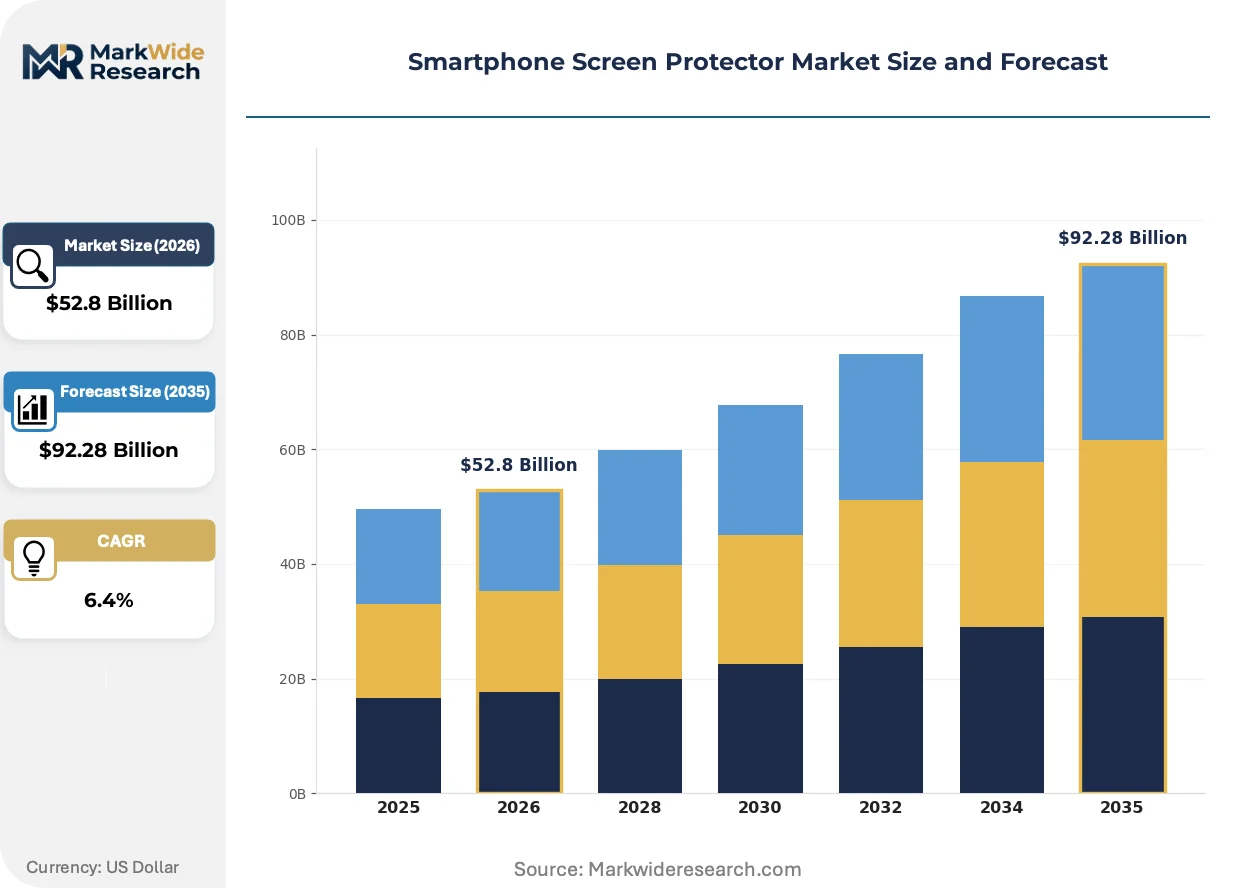
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tempered Glass, Film, Liquid, Hybrid Application: Smartphones, Tablets, Smartwatches, Laptops Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Electronic Shops End User: Consumers, Businesses, Educational Institutions, Government |
| Companies Covered | OtterBox, Nippon Electric Glass Co. Ltd, ZAGG Inc., AGC Inc., Spigen Inc., Belkin International Inc., BodyGuardz, Xtreme Guard, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Screen Protector Market Strategic Shifts & Innovations
A fundamental shift is underway, moving the market's focus from simple scratch and impact resistance toward integrated, multi-functional screen solutions. This evolution transforms the protector from a passive accessory into an active component that enhances the device's usability and security.
Hybrid glass-polymer materials are a key product evolution. These composites blend the hardness and clarity of glass with the flexibility and impact-absorbing properties of polyurethane. Consumers with curved-screen or foldable devices are the primary adopters. This technology is hybridizing the market by creating a distinct performance tier that bridges the gap between flexible films and rigid tempered glass.
The EU's REACH regulation is a significant policy driver influencing material composition. This framework restricts the use of certain hazardous substances in products sold within the European Union. Its primary industrial consequence is forcing manufacturers to reformulate adhesives and coatings, often increasing raw material costs. This shift most affects mass-market producers, who must invest in compliance to maintain access to the lucrative European consumer base.
Consumer purchasing behavior is decisively moving toward online, direct-to-consumer channels. This pattern often involves bundling a screen protector with a case at the point of the new phone purchase, bypassing traditional retail. The shift disrupts brick-and-mortar electronics stores and empowers smaller, digitally native brands. This trend is most visible in North America and Western Europe, facilitated by major e-commerce platforms.
Smartphone Screen Protector Market Segmentation
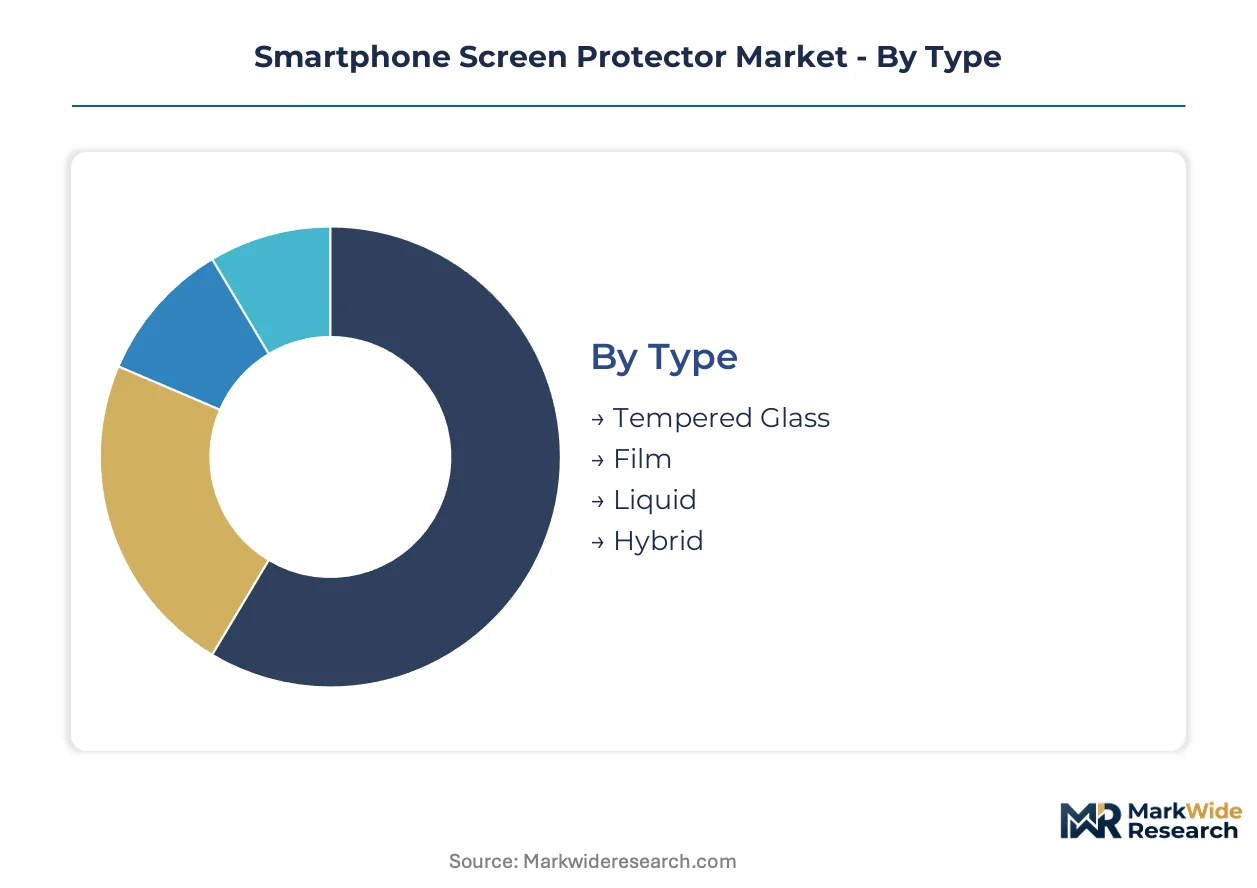
The smartphone screen protector market's segmentation reveals distinct consumer preferences and technological trajectories across product types and end-use applications. Understanding these divisions is essential for manufacturers to tailor offerings and distribution strategies effectively. This granular view highlights where innovation is most impactful and where market saturation presents pricing challenges.
Type:
The after-sales service intensity varies significantly across screen protector types, influencing customer satisfaction and repeat purchases for different material compositions.
- Tempered Glass:This material consists of a multi-layered structure, chemically treated for enhanced strength and scratch resistance, typically rated 9H. Demand concentrates in developed markets like the United States and Germany, driven by consumers seeking premium feel and superior impact absorption for expensive devices.
- Hybrid:These advanced composites combine the clarity and hardness of glass with the flexibility and impact-dissipation properties of polymer films. Consumers with curved-edge or foldable smartphones in South Korea and China are primary adopters, valuing the enhanced durability and form factor compatibility.
- Film:Flexible thermoplastic polyurethane (TPU) or polyethylene terephthalate (PET) films offer basic scratch protection and are known for their self-healing properties.
- Liquid:A silica-based solution that forms an invisible layer, providing microscopic scratch resistance and enhancing oleophobic properties on the native screen.
By volume, Tempered Glass leads. By growth pace, Hybrid is ahead.
Application:
Volume considerations heavily influence product design and marketing efforts within the screen protector application segments, dictating production scale and material choices.
- Smartphones:Screen protectors for smartphones are precisely cut to fit various models, offering protection against scratches, cracks, and impacts to the primary display. Demand for these protectors is highest in populous countries like India and Indonesia, correlating directly with high smartphone penetration and new device sales.
- Smartwatches:These protectors are designed for smaller, often curved displays, requiring precise fit and optical clarity to maintain touch sensitivity and aesthetic appeal. Growth is particularly strong in Japan and the UK, driven by the expanding wearables market and consumers' desire to protect high-value personal tech.
- Tablets:Larger format protectors for tablets focus on scratch resistance and anti-glare properties, catering to devices used for media consumption and productivity.
- Laptops:Screen protectors for laptops are typically larger films or rigid panels, often incorporating privacy filters or blue light reduction features for professional users.
The market's center of gravity for application is shifting towards Smartwatches due to their expanding user base and higher average selling prices for protective accessories.
Distribution Channel:
Customer type significantly shapes the preferred distribution channel, with different segments valuing convenience, product expertise, or immediate availability.
- Online Retail:This channel includes e-commerce platforms and brand-specific websites, offering extensive product catalogs, competitive pricing, and direct-to-consumer shipping. Consumers in the United States and Germany increasingly prefer online purchases, valuing convenience and the ability to compare multiple brands and reviews.
- Electronic Shops:These brick-and-mortar stores provide in-person product viewing, expert advice, and professional installation services for screen protectors. Shoppers in countries like Japan and South Korea often visit electronic shops for high-value purchases, seeking assurance and immediate application.
- Specialty Stores:Dedicated mobile accessory shops offer a curated selection of screen protectors, often paired with other protective gear like cases and skins.
- Supermarkets:Mass-market retailers stock basic, universally sized screen protectors, catering to impulse purchases and budget-conscious consumers seeking convenience.
The evolution of distribution channels is heavily influenced by consumer digital literacy, leading to Online Retail gaining prominence globally.
End User:
Margin considerations drive differentiation in the end-user segments, as manufacturers seek to capture higher value from specific customer groups through tailored offerings.
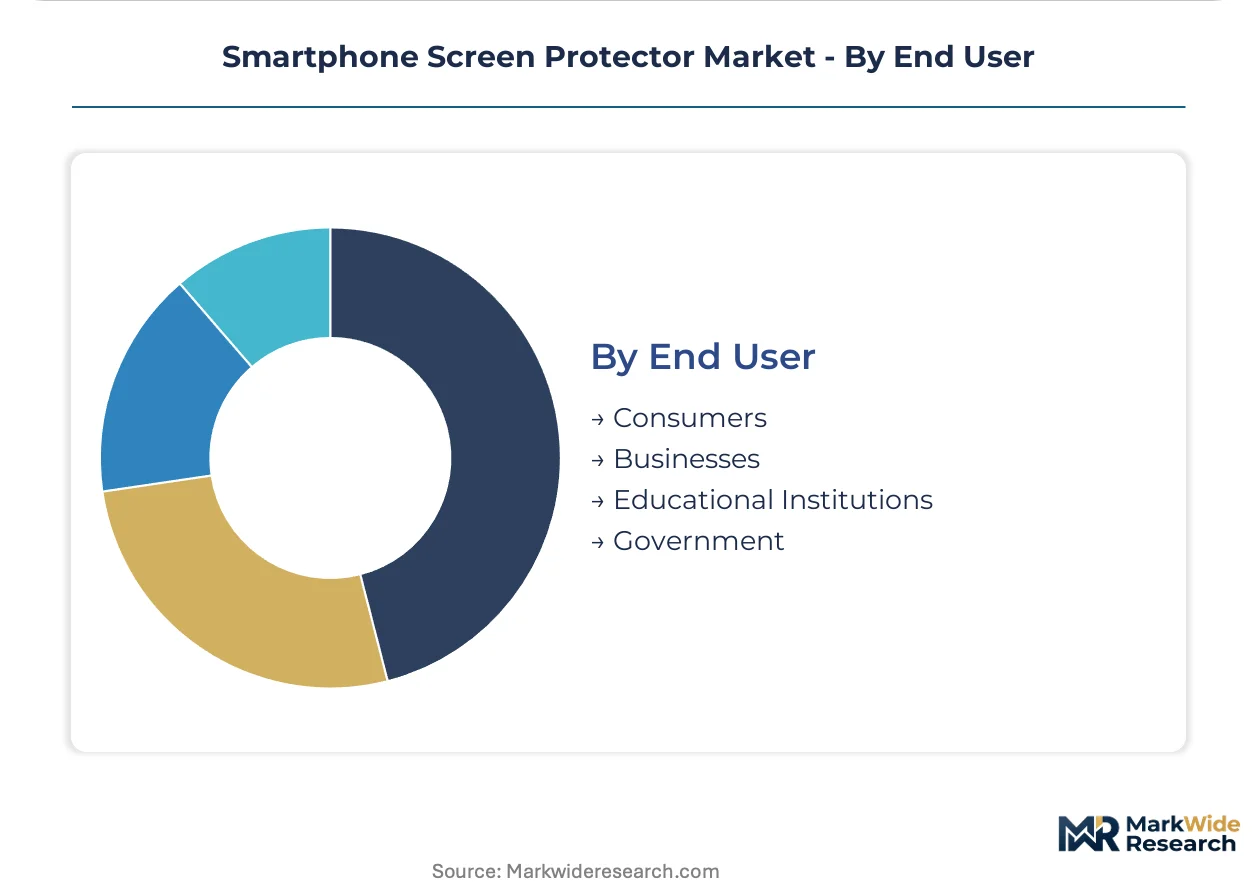
- Consumers:Individual purchasers of smartphones, tablets, and smartwatches represent the largest segment, prioritizing personal device protection, resale value, and aesthetic integrity. This segment is particularly large in emerging economies such as Brazil and Mexico, where device investment is significant for individuals.
- Businesses:Enterprises procure screen protectors for company-issued devices, focusing on durability, bulk purchasing discounts, and asset longevity for their mobile workforce. Corporate clients in Canada and Australia frequently invest in robust protection solutions to minimize repair costs and downtime.
- Educational Institutions:Schools and universities purchase screen protectors for student and faculty devices, emphasizing scratch resistance and ease of application for high-usage environments.
- Government:Public sector entities require screen protectors for official devices, often with specific security features or compliance with procurement standards for sensitive data handling.
Strategic differentiation within end user segments increasingly focuses on Businesses to capture recurring revenue streams and larger volume contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU's REACH and RoHS directives, alongside China's GB standards, increasingly shape material compositions and market access for screen protectors. These regulatory frameworks necessitate specific investments in compliance, particularly for mass-market producers, while also driving demand for higher-quality, safer products in developed regions. The market’s geographic concentration reflects both high smartphone penetration and consumer willingness to protect devices.
United States
Consumers in the United States prioritize screen protectors for their premium feel and superior impact absorption, particularly for high-value smartphones. The Federal Trade Commission (FTC) oversees general consumer product safety, influencing material transparency and marketing claims. Major e-commerce distribution centers, such as those in Kentucky and Tennessee, facilitate the rapid delivery of screen protectors to a wide online consumer base.
China
China's vast smartphone market drives significant demand for screen protectors, with a strong emphasis on material quality and durability. Adherence to GB standards is crucial for manufacturers seeking market access and consumer trust within the country. Shenzhen, a global manufacturing and technology hub, remains central to the production and innovation of screen protector materials and designs.
Germany
Developed markets like Germany show strong demand for screen protectors, valuing both aesthetic appeal and robust device protection. The EU's REACH regulation directly impacts the chemical composition of adhesives and coatings used in products sold here. Munich, a prominent tech and industrial center, represents a key consumer base for high-quality protective accessories for expensive devices.
India
High smartphone penetration and new device sales cycles fuel substantial demand for screen protectors across India's burgeoning consumer segment. The Bureau of Indian Standards (BIS) establishes quality and safety benchmarks for consumer electronics accessories. Bengaluru, a major technology hub, sees significant e-commerce growth for protective accessories, reflecting strong local smartphone adoption.
Vietnam
New smartphone owners in Vietnam highly prioritize device longevity and resale value, creating a significant demand-side pull for protective accessories. Local consumer protection agencies influence product quality and labeling requirements for imported and domestically produced goods. Ho Chi Minh City, a rapidly expanding urban center, serves as a key market for consumer electronics and related protective gear.
Smartphone Screen Protector Market Key Industry Players
Channel-controlling players compete with product-specialist players across the smartphone screen protector market, creating a bifurcated competitive structure. Material science innovators differentiate through advanced technologies, while asset-light e-commerce brands focus on rapid product iteration and marketing. Strategic partnerships with device manufacturers and continuous R&D in next-generation materials represent dominant competitive moves.
Corning Incorporated exemplifies a material science innovator, leveraging deep expertise in specialty glass to maintain a strong market position. Spigen Inc. sits within the archetype of asset-light e-commerce brands, competing effectively through agile marketing and quick adaptation to new phone models. ZAGG Inc. represents a broad portfolio player, utilizing its extensive product range and established retail channel presence to serve diverse consumer segments.
| Leading Market Players |
|---|
| OtterBox |
| Nippon Electric Glass Co. Ltd |
| ZAGG Inc. |
| AGC Inc. |
| Spigen Inc. |
| Belkin International Inc. |
| BodyGuardz |
| Xtreme Guard |
| Corning Incorporated |
| Others |
Cost & Logistics Intelligence
Underutilized manufacturing capacity in China for film and tempered glass screen protectors drives both supplier behavior and pricing posture across the mass market. This overcapacity creates intense competition among manufacturers, directly influencing the cost structure for online retailers and global brands.
Pricing Analysis
Performance tier creates the primary spread in smartphone screen protector pricing, differentiating basic film from advanced hybrid glass solutions. The dominant pricing structure remains per-unit transactional, with significant price differentiation stemming from material composition and brand premium. Pricing pressure stems from the proliferation of low-cost online sellers, particularly impacting the basic film segment. Consumers in emerging economies like India exhibit the highest price sensitivity, while businesses procuring for corporate devices prioritize durability over cost.
Supply Chain Analysis
Upstream feedstock for screen protectors, including specialized glass and thermoplastic polymers, primarily originates from East Asian countries such as Japan, South Korea, and China. Geographic supply concentration for finished goods largely centers in China and Vietnam, leveraging established electronics manufacturing ecosystems. Raw material dependencies on specialty chemical suppliers and glass manufacturers present a single-source vulnerability for advanced materials. Distribution runs through a dual model, with online retail dominating direct-to-consumer sales and traditional electronics shops serving as key physical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartphone screen protector market is experiencing a buyer-power shift, driven by the fragmentation of online distribution channels and the proliferation of direct-to-consumer brands. This dynamic empowers consumers with broader choices and more competitive pricing, challenging traditional retail models.
For Market Incumbents: Build material science expertise as a competitive moat against commoditization from asset-light brands. Focus R&D on hybrid glass and self-healing films to justify premium price points. Invest in robust supply chain agility to rapidly align with new smartphone model releases, mitigating the threat from quick-to-market online competitors. Deepen partnerships with device manufacturers for early access to design specifications and integrated product development.
For New Entrants and Emerging Players: Build out niche market penetration by targeting specific application segments like smartwatches or foldable devices, where traditional tempered glass solutions are incompatible. The online direct-to-consumer channel offers the most penetrable segment, allowing for rapid brand establishment without significant physical retail investment. Focus on a value-driven go-to-market angle, emphasizing specific functional benefits like privacy filters or anti-blue light properties to differentiate from basic offerings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across the online retail segment, favoring asset-light e-commerce models over traditional manufacturing. Identify acquisition targets that possess strong brand recognition within specific material niches or demonstrate advanced R&D capabilities in hybrid glass technologies. A key signal to watch is the market's response to advancements in native screen durability, which could redefine the necessity of third-party protectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Hybrid Material R&D | This initiative allows for differentiation in a commoditizing market and addresses foldable device compatibility gaps. |
| Strengthen E-commerce Logistics | Optimized logistics enable rapid product delivery and competitive pricing, crucial for online sales growth. |
| Expand into Adjacent Device Categories | Diversifying into smartwatches and tablets opens new revenue streams beyond traditional smartphones. |
| Target Emerging African Markets | Early market entry in Nigeria and Kenya captures a new wave of first-time smartphone users. |
| Develop Integrated Functional Protectors | Adding features like privacy filters or anti-blue light layers enhances product value and justifies premium pricing. |
Research Approach
A standing panel of product development leads, e-commerce executives, material scientists, and retail buyers provided ongoing calibration for market insights. This qualitative primary research was rigorously combined with quantitative secondary validation from sources including regulatory filings like REACH and RoHS, trade association reports, and company financial statements. The methodology employed both bottom-up and top-down triangulation to ensure comprehensive data accuracy.
The forecast framework utilizes a scenario-bracketing approach, modeling market evolution across the analysis window under various economic and technological assumptions. Segmentation dimensions modeled include product type, application, distribution channel, end-user, and material composition. Compound annual growth rates (CAGRs) were derived through a proprietary statistical model, integrating key industry-specific inputs such as smartphone sales projections and material innovation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new material science innovators or dominant e-commerce platforms would shift outcomes. These forecasts reflect assumptions regarding sustained consumer demand for device protection and continued innovation in material science. Material shifts in display technology or significant regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Baby Monitor Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Notebook Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Wrist Dive Computer Market